
 Advanced Ceramic Additives Market | 2026-2036
Advanced Ceramic Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Ceramic Additives Market Intelligence
Demand from specialized R&D institutions is unwinding the historical dominance of large-scale automotive suppliers in the procurement of high-purity additives. BASF SE leverages its extensive research and development infrastructure to develop custom formulations for niche electronics applications. Evonik Industries AG specializes in silica-based additives that enhance flowability and dispersion for complex ceramic shapes. Dow Inc. competes on its global manufacturing scale and supply chain efficiency, particularly for foundational alumina additives.
Advanced ceramic additives are specialized materials introduced into ceramic powders to modify processing behavior and final properties. These materials, often in powdered or granulated form, improve sinterability, reduce defects, and enhance mechanical strength or thermal conductivity. Zirconia-based additives are gaining traction over traditional alumina for high-stress medical and aerospace applications. While the electronics sector drives volume for applications like multilayer ceramic capacitors, the aerospace segment commands higher margins for specialized components.
Regulatory frameworks such as the EU's REACH and the US EPA's Toxic Substances Control Act (TSCA) govern chemical safety and market access for new additive chemistries. These regulations compel manufacturers to invest in comprehensive toxicity and environmental impact testing. Future success depends on aligning additive development with the specific performance targets of next-generation semiconductors and medical implants.
Market Dynamics
The market's central dynamic is the divergence between high-volume, cost-sensitive demand from the electronics sector and the low-volume, high-margin requirements of aerospace and medical applications. This split dictates R&D investment, supply chain structure, and competitive specialization among suppliers.
Growth Catalysts
- Zirconia-Based Formulations:The adoption of zirconia additives over traditional alumina is accelerating in high-stress medical implants and aerospace components due to superior fracture toughness and biocompatibility.
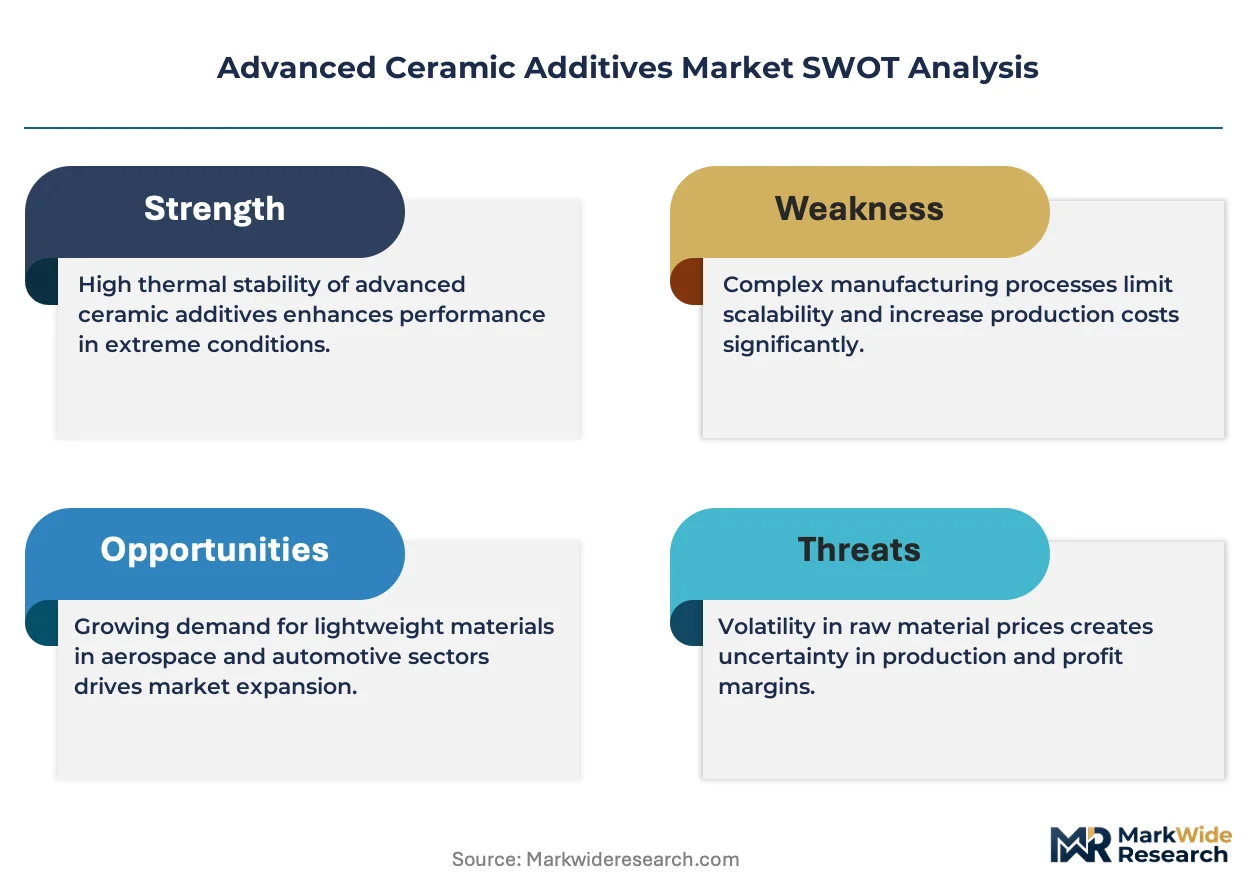
- Electronics Manufacturing in China:Demand for binders, plasticizers, and dispersants is concentrated in China, driven by its vast production of multilayer ceramic capacitors (MLCCs) and other electronic components.
- Aerospace Performance Mandates:Stringent requirements for thermal resistance and lightweighting in next-generation aircraft engines and airframes necessitate the use of advanced additives to enhance ceramic matrix composites.
Market Restraints
- Regulatory Compliance Costs:Frameworks like the EU's REACH and the US EPA's TSCA impose significant testing and documentation burdens, increasing the cost and time-to-market for new additive chemistries.
- Raw Material Price Volatility:The cost of high-purity rare earth oxides, essential for producing certain zirconia and yttria-based additives, is subject to supply chain disruptions and geopolitical factors.
- Technical Processing Complexity:The effective use of advanced additives requires precise control over mixing, dispersion, and sintering processes, posing a barrier for manufacturers without specialized equipment and expertise.
Strategic Opportunities
- Additives for Additive Manufacturing:Developing specialized binder and flowability agent formulations optimized for ceramic 3D printing processes opens a new market for creating complex, customized components.
- Solid-State Battery Electrolytes:The push for next-generation energy storage creates an opportunity for additives that improve the ionic conductivity and stability of solid ceramic electrolytes.
- Medical Device Sector in India:Targeting India's expanding medical device industry, supported by government initiatives like the PLI scheme, offers a new growth vector for biocompatible ceramic additives.
Industry Challenges
- Formulation Standardization:A lack of globally recognized standards for additive purity, particle size, and performance metrics creates integration challenges and quality inconsistencies for end-users.
- Specialized Talent Scarcity:The industry faces a shortage of materials scientists and ceramic engineers with the dual expertise in additive chemistry and advanced ceramic processing.
- Intellectual Property Protection:Securing proprietary formulations for custom additives is difficult, particularly in collaborative R&D projects with clients in competitive sectors like semiconductors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Ceramic Additives Market |
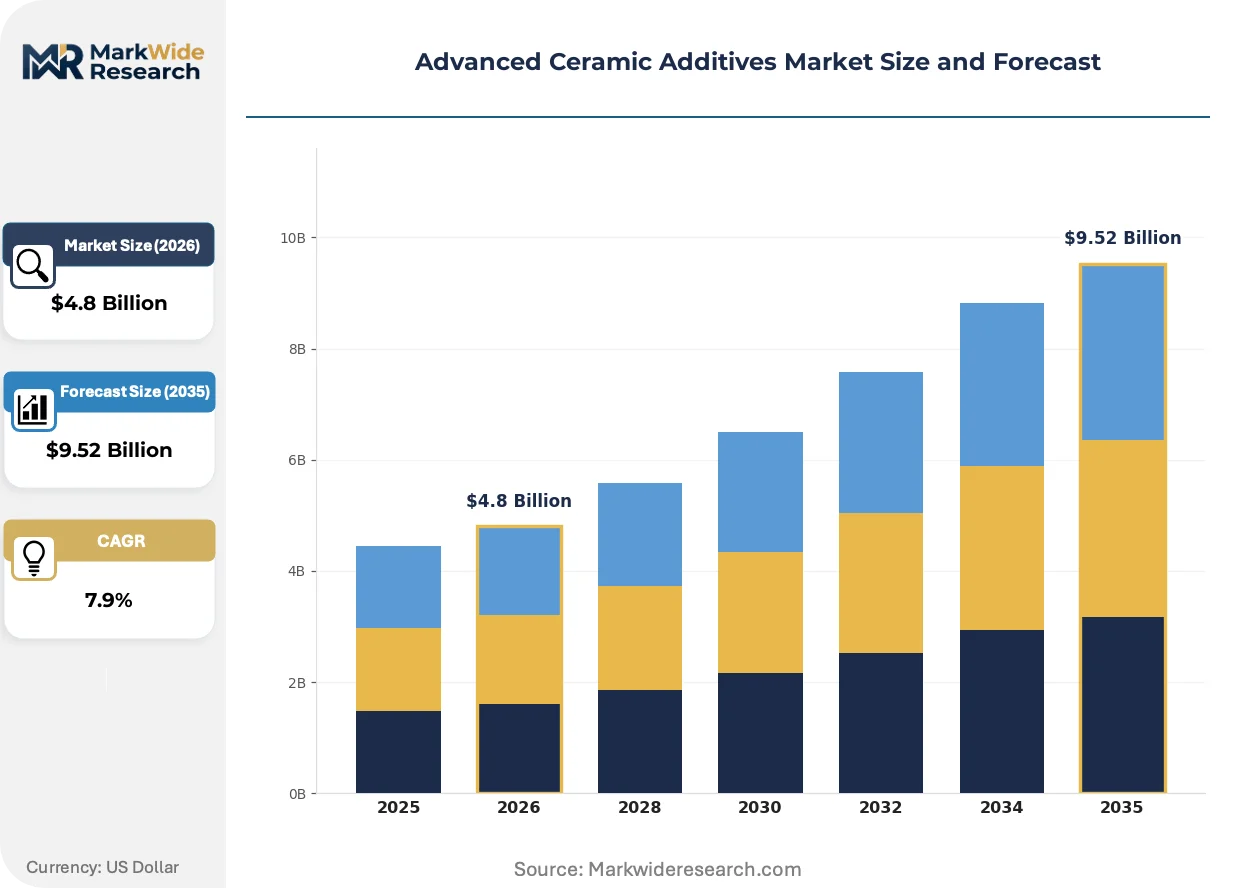
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
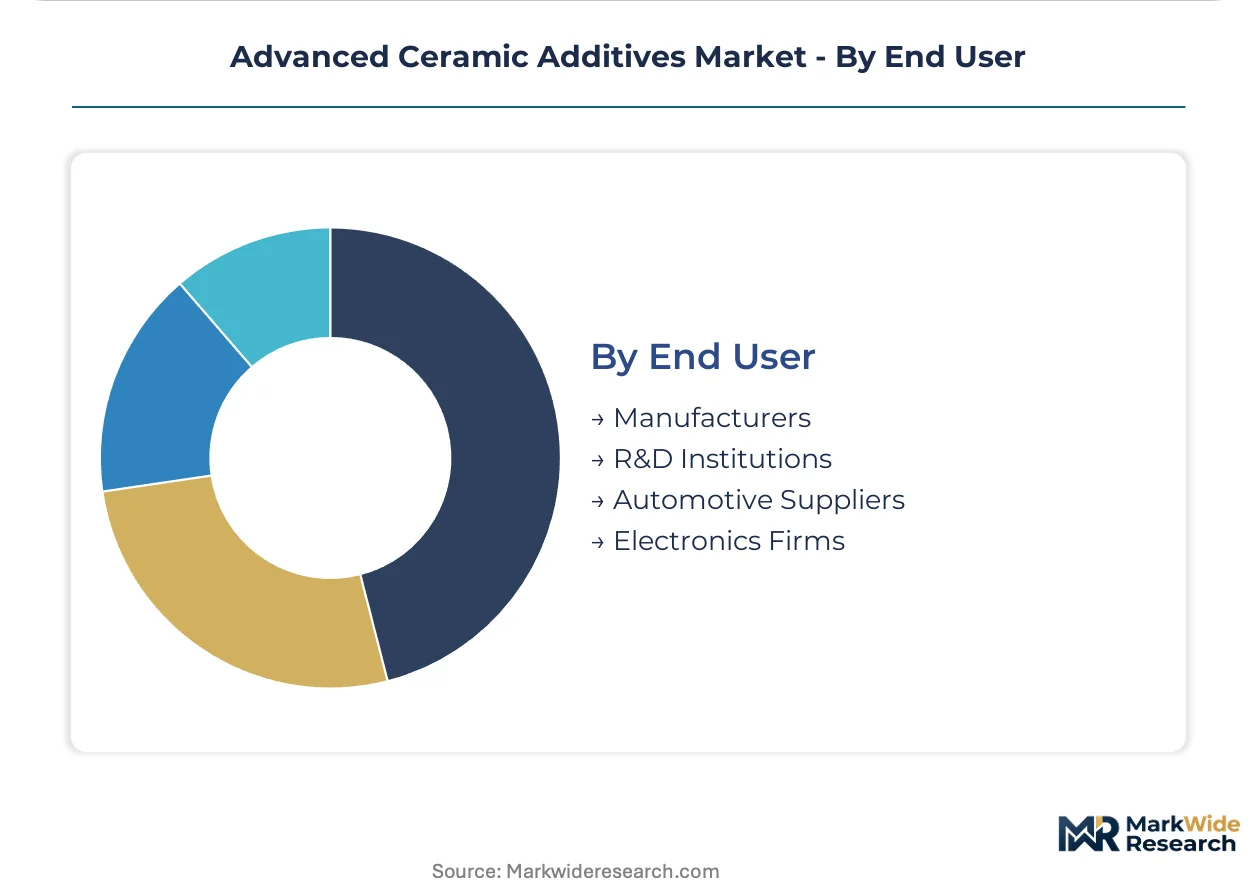
| Segmentation | Type: Alumina, Zirconia, Silicon Carbide, Titania Application: Electronics, Aerospace, Automotive, Medical Form: Powdered, Granulated, Coated, Sintered End User: Manufacturers, R&D Institutions, Automotive Suppliers, Electronics Firms |
| Companies Covered | BASF SE, Evonik Industries AG, Ashland Inc., Dow Inc., Solvay S.A., Wacker Chemie AG, Sanyo Chemical Industries Ltd., Lamberti Group, BOZZETTO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Ceramic Additives Market Strategic Shifts & Innovations
The market is defined by a decisive shift toward application-specific, high-performance formulations. This trend moves the industry away from commoditized, general-purpose additives toward custom solutions engineered for precise end-use performance targets in sectors like aerospace and electronics.
Nanoscale additives, including nano-zirconia and nano-silica, offer superior grain refinement and enhanced sintering activity at lower processing temperatures. Specialized R&D institutions and manufacturers of medical implants are adopting these materials to achieve unprecedented material properties. The functional superiority of nano-additives is displacing conventional micron-sized powders in premium applications where performance cannot be compromised.
The European Union's REACH regulation establishes a comprehensive framework for the registration and evaluation of chemical substances. This forces additive manufacturers to conduct extensive environmental and toxicological assessments before gaining market access. The electronics sector, a heavy user of organic binders and plasticizers, is most affected and is actively reformulating products to ensure compliance.
A transition toward co-development partnerships is changing how additives are specified and sold. This collaborative model is replacing transactional, catalog-based purchasing with integrated design processes where additive specialists work alongside OEM engineers. This trend is most visible within the semiconductor and aerospace industries, where off-the-shelf solutions fail to meet extreme performance criteria.
Advanced Ceramic Additives Market Segmentation
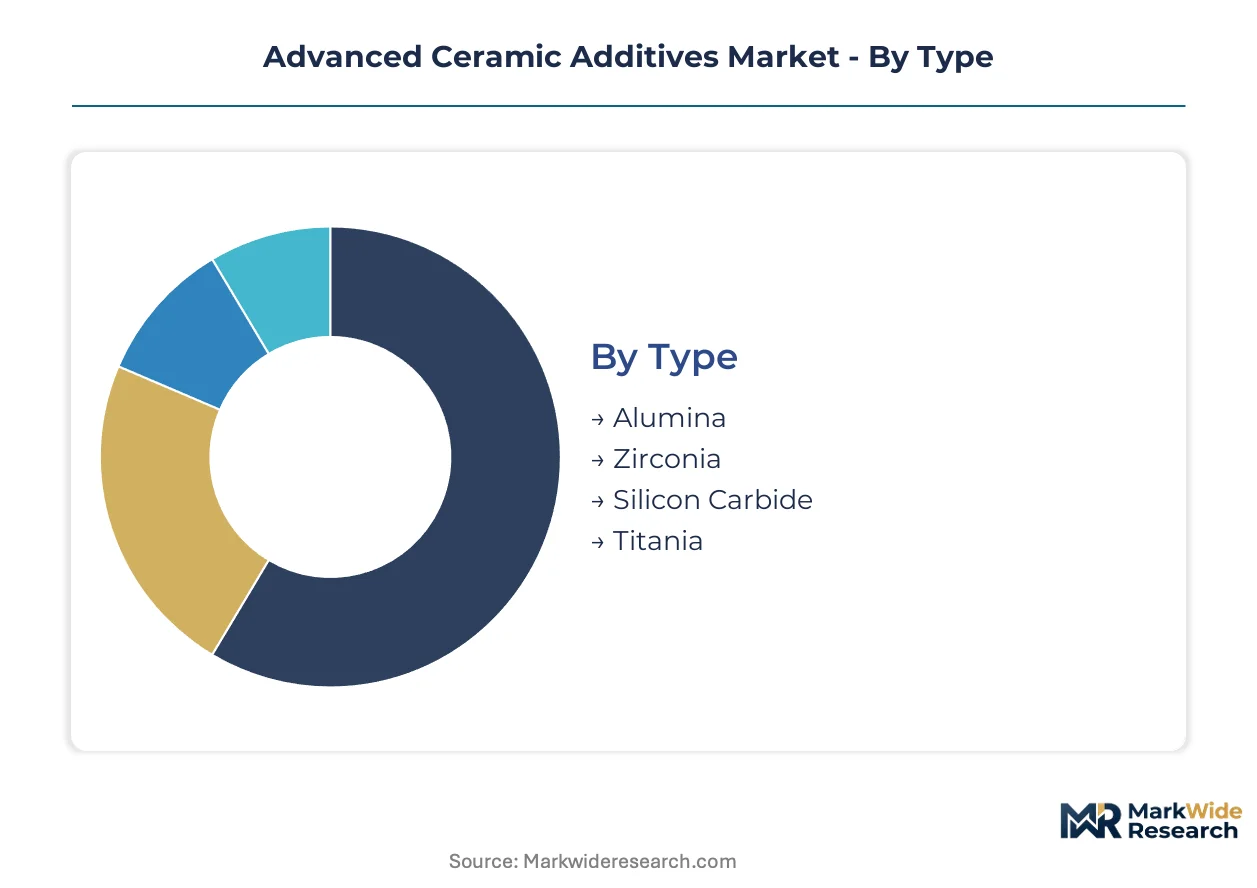
The Advanced Ceramic Additives Market segments across diverse dimensions, reflecting the specialized requirements of various end-use industries. Understanding these distinctions helps stakeholders identify areas of concentrated value creation and niche opportunities for product development. Each segment contributes uniquely to the market's overall structure and growth trajectory.
Type:
Margin pools within the additive market vary significantly by material composition, driven by performance demands and raw material purity. High-performance formulations command premium pricing, reflecting their specialized manufacturing processes.
- Zirconia:These additives offer superior fracture toughness and thermal shock resistance, making them critical for high-stress applications. Demand is accelerating in medical implants and aerospace components, particularly for engine parts requiring extreme durability.
- Alumina:Alumina additives provide excellent hardness and chemical inertness, serving as foundational materials for a broad range of ceramic products. Electronics manufacturing in China drives substantial volume for these cost-effective, high-purity powders.
- Silicon Carbide:Silicon carbide additives enhance wear resistance and high-temperature strength in structural ceramics. Automotive brake systems and industrial furnace components utilize these materials for their robust properties.
- Titania:Titania additives are employed for their dielectric properties and as sintering aids in specialized electronic ceramics. Pigment and coating formulations also incorporate titania for optical characteristics.
Alumina holds installed capacity. Zirconia is rotating up the share rankings.
Application:
Cost-tier differentiation is pronounced across application segments, with some sectors prioritizing volume and others demanding bespoke, high-performance solutions. The technical specifications for each application dictate the required additive properties.
- Electronics:This segment requires high-purity binders, plasticizers, and dispersants for components like multilayer ceramic capacitors (MLCCs). China's expansive electronics production drives immense volume demand for these additives.
- Aerospace:Aerospace applications demand additives that enhance thermal resistance, lightweighting, and mechanical strength in ceramic matrix composites. Specialized components for next-generation aircraft engines command high margins due to stringent performance mandates.
- Medical:Medical applications utilize biocompatible additives for dental prosthetics and surgical implants. Zirconia-based formulations are increasingly specified for their superior fracture toughness and inertness.
- Automotive:Automotive uses include additives for catalytic converters, sensors, and brake systems, focusing on durability and thermal stability. Production volumes in Asia drive a significant portion of this demand.
Electronics drives the majority of volume. Aerospace represents the fastest-growing trajectory.
Form:
Volume concentration varies by the physical form of the additive, reflecting ease of integration into different ceramic processing techniques. Powdered forms remain prevalent due to their versatility and cost-effectiveness.
- Powdered:These additives are the most common form, offering versatility in mixing and dispersion for various ceramic manufacturing processes. Traditional pressing and slip casting methods extensively use powdered additives.
- Coated:Coated additives improve dispersion stability and reduce agglomeration, enhancing homogeneity in complex ceramic formulations. Specialized applications in 3D printing and advanced electronics benefit from these tailored forms.
- Granulated:Granulated additives provide improved flowability and reduced dust generation, optimizing handling and feeding in automated systems. Dry pressing and injection molding processes often prefer granulated materials.
- Sintered:Sintered additives are pre-processed to achieve specific microstructures or properties before integration into final ceramic bodies. High-performance structural components utilize these advanced forms.
Powdered maintains foundational market presence. Coated is expanding its market footprint.
End User:
Customer type influences procurement patterns and technical support requirements, with R&D institutions often seeking custom formulations. Procurement patterns are shifting towards co-development partnerships.
- Manufacturers:This segment includes large-scale producers of ceramic components across various industries, requiring consistent supply and technical support. Electronics firms and automotive suppliers represent significant manufacturing end-users.
- R&D Institutions:Research and development institutions focus on novel additive chemistries and advanced material properties for future applications. Specialized R&D units drive demand for custom, high-purity formulations.
- Automotive Suppliers:These firms integrate ceramic additives into components for engines, brakes, and exhaust systems. Performance and cost-effectiveness are critical considerations for automotive procurement.
- Electronics Firms:Electronics firms utilize additives for their dielectric and mechanical properties in capacitors, substrates, and sensors. Reformulations to comply with EU REACH regulations are a key focus.
Manufacturers command the largest procurement volumes. R&D Institutions are diversifying their supplier base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement patterns are shifting as specialized R&D institutions and high-margin application segments drive demand for custom formulations. This concentration of discerning buyers influences regional growth trajectories and technology adoption. Diverse regulatory environments and manufacturing hubs shape additive market dynamics across key geographies.
China
China's expansive electronics manufacturing base drives immense volume demand for binders, plasticizers, and dispersants, particularly for multilayer ceramic capacitors. The country's GB standards influence chemical formulation and market access for new additive chemistries. Industrial clusters in the Yangtze River Delta and Pearl River Delta lead production, requiring consistent supply of foundational alumina additives.
United States
The United States aerospace and medical sectors demand high-performance additives for extreme durability and biocompatibility. The US EPA's Toxic Substances Control Act (TSCA) mandates rigorous testing for new chemical substances entering the market. Research institutions in California and the Northeast corridor lead innovation in advanced ceramic materials for next-generation applications.
Germany
Germany's advanced automotive and industrial machinery sectors require specialized ceramic additives for wear resistance and high-temperature strength. The EU's REACH regulation significantly impacts additive formulation and substance evaluation for market entry. The chemical industry in regions like North Rhine-Westphalia and Bavaria develops custom solutions for niche applications.
India
India's expanding medical device industry offers a significant growth vector for biocompatible ceramic additives, supported by government initiatives like the PLI scheme. The country's national pharmaceutical regulator influences material selection for implants and prosthetics. Manufacturing hubs in Maharashtra and Gujarat are increasing their capacity for advanced ceramic component production.
Advanced Ceramic Additives Market Key Industry Players
Player mix skews toward large chemical conglomerates with extensive R&D capabilities and specialized materials companies. The market exhibits a tiered structure, with a few global leaders supplying foundational additives and numerous niche players offering highly specialized formulations. Strategic partnerships between additive manufacturers and OEM engineers represent a dominant competitive move, alongside continuous portfolio diversification into high-growth application areas.
Specialists in custom formulations like BASF SE and Evonik Industries AG exemplify the research-intensive approach, leveraging their deep scientific expertise to develop tailored solutions. Dow Inc. occupies a position as a large-scale supplier, anchoring the market with its global manufacturing footprint and efficient supply chains for high-volume materials. These firms represent different facets of the market, from highly customized niche products to broad-based foundational offerings.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Ashland Inc. |
| Dow Inc. |
| Solvay S.A. |
| Wacker Chemie AG |
| Sanyo Chemical Industries Ltd. |
| Lamberti Group |
| BOZZETTO Group |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements lock in both supply access and price visibility for specialized ceramic additives. This contract structure mitigates raw material volatility for manufacturers and ensures consistent input quality for demanding end-use applications like aerospace.
Pricing Analysis
Cost-plus contracts with named indexation for key raw materials dominate pricing for high-purity additives. Price differentiation stems from purity grade and the level of custom formulation required for specific applications. Pricing pressure stems from the high-volume electronics sector, where intense competition drives cost compression. Aerospace and medical sectors exhibit the least price sensitivity, prioritizing performance and regulatory compliance over cost.
Supply Chain Analysis
Geopolitical factors influencing rare earth oxides represent a critical supply chain chokepoint for certain advanced ceramic additives. Supply concentration for foundational alumina additives centers on China, driven by its vast electronics manufacturing. High-purity rare earth oxides and specialized silica powders are key dependencies. Raw material price volatility poses a structural risk. Distribution occurs primarily through direct sales channels to OEM engineers and specialized materials distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at an early-cycle expansion phase, driven by increasing adoption in next-generation semiconductors and medical implants.
For Market Incumbents: Consolidate R&D efforts on application-specific formulations, particularly for aerospace and medical applications. Secure long-term raw material contracts to mitigate the threat of raw material price volatility. Invest in advanced certification processes for biocompatible materials, leveraging this as a key lever against emerging regulatory shifts like REACH.
For New Entrants and Emerging Players: Differentiate on specialized additive manufacturing formulations optimized for ceramic 3D printing processes. Target India's expanding medical device sector, which represents a penetrable segment supported by government initiatives like the PLI scheme. Pursue co-development partnerships with R&D institutions as a primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors niche materials science firms with strong intellectual property. Long-term viability remains strong, driven by demand from high-growth sectors like aerospace and solid-state batteries. Watch for increased M&A activity in specialized additive manufacturing or energy storage as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Zirconia | Ensures supply for high-growth medical and aerospace applications. |
| R&D in Nanoscale Additives | Unlocks superior material properties for premium electronics and implants. |
| Strategic Partnership with OEMs | Integrates additive development directly into advanced product design cycles. |
| Investment in Biocompatibility Testing | Addresses stringent regulatory requirements for medical device market access. |
| Backward Integration into Raw Materials | Secures critical supply chains for high-purity rare earth oxides. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, patent databases, academic journals, and government publications from the EPA and ECHA. Primary interviews involved R&D directors, procurement leads at OEM firms, materials scientists, and regulatory affairs specialists. This approach allowed for robust bottom-up and top-down triangulation of market data.
Segmentation by type, application, form, end user, and regional regulatory frameworks underpinned the analytical framework across the projection horizon. Volume and value outputs were derived from a detailed assessment of end-use sector growth rates and additive consumption patterns. Raw material cost projections and specific performance mandates from aerospace OEMs served as key forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory environments and consistent technological advancement; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as geopolitical disruptions and unexpected regulatory changes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
2N High Purity Alumina Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
China Ceramic Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Lithium Zirconate Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Southeast Asia Melamine Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Ceramic Sanitary Ware Market