
 Brazil Ceramic Tiles Market | 2026-2036
Brazil Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Ceramic Tiles Market Outlook
Skilled kiln-operator shortages across São Paulo's industrial belt is unwinding production capacity expansion plans for several manufacturers. Portobello S.A. leverages proprietary digital printing lines to sustain premium positioning in porcelain segments. Eliane Revestimentos anchors its competitiveness through captive clay reserves and vertical control over glazing chemistry. Ceusa Revestimentos differentiates via specialized large-format slabs targeting commercial facade applications.
Brazil ceramic tiles are flat, fired clay-based surfacing units typically measuring 300x300mm to 1200x2400mm, formed through dry pressing or extrusion and fired at 1000-1250°C for structural densification and decorative surface stability. Floor tiles command the largest product-type position due to replacement cycles in residential stock, yet vitrified tiles represent the fastest-growing material category as builders specify full-body porcelain for high-traffic commercial installations. Porcelain-grade material segments capture disproportionate margin pools because raw-material beneficiation and energy-intensive firing create technical barriers that filter out commodity competitors.
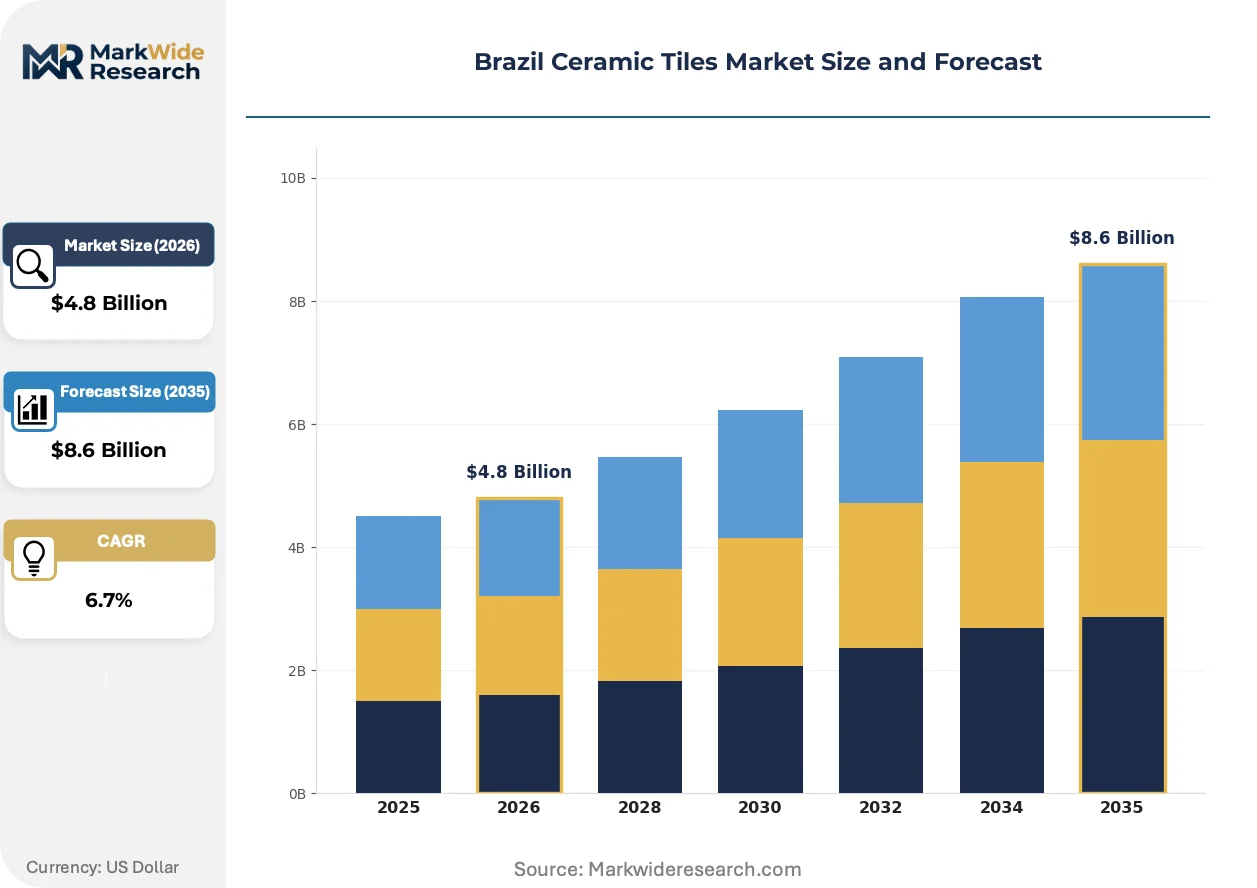
ANVISA governs surface-contact material safety thresholds, while INMETRO certification mandates slip-resistance grading and dimensional tolerance compliance for domestic commercial projects. The country's central bank credit policies for construction financing directly shape residential renovation demand, linking monetary conditions to tile offtake volumes. Stakeholders must monitor how Brazil's PLI-scheme equivalents for building materials reshape local-versus-imported supply equations.
Market Dynamics
ANVISA's tightened surface emission protocols are compressing formulation flexibility across Brazil's southeastern manufacturing belt, forcing producers to requalify glaze chemistries and kiln firing curves ahead of certification deadlines.
Growth Catalysts
- Minas Gerais residential stock replacement:Aging housing inventory in Belo Horizonte's metropolitan ring is accelerating floor tile renovation cycles, pulling porcelain-grade material through distributor networks.
- INMETRO slip-resistance mandates:Commercial project specifications now require certified R9-R11 grading for public spaces, creating specification pull for technically qualified domestic suppliers.
- Digital inkjet decoration:High-resolution surface printing technology is collapsing minimum order quantities for custom pattern runs, enabling architect-specified boutique batches.
Market Restraints
- Natural gas price volatility:Petrobras-linked industrial fuel tariffs are destabilizing firing cost structures across São Paulo state's gas-dependent kiln networks.
- Kiln-operator labor scarcity:Specialized pyrometry and combustion-control expertise is concentrating among retiring cohorts in Santa Gertrudes' tile cluster, constraining output scaling.
- Laminate flooring substitution:Click-lock vinyl and wood-look laminates are capturing price-sensitive residential renovation spending in Rio de Janeiro's apartment sector.
Strategic Opportunities
- Northeast urban corridor penetration:Recife and Salvador's commercial construction pipelines remain undersupplied by large-format porcelain slab capacity relative to southeastern saturation.
- Facade cladding specification:Thin porcelain panels for exterior rainscreen systems are opening specification channels with Brazilian architectural practices designing tropical climate envelopes.
- Central bank construction credit expansion:Brazil's monetary authority housing finance programs are channeling liquidity into Minas Gerais and São Paulo state renovation lending.
Industry Challenges
- ANVISA requalification timelines:Surface emission testing protocols are extending product launch cycles by six to nine months for reformulated glaze systems.
- Continuous kiln thermal uniformity:Maintaining cross-kiln temperature bands within 15°C tolerance for large-format porcelain is demanding advanced burner control retrofits.
- Legacy distributor credit exposure:Extended payment terms to São Paulo's fragmented retail tile networks are compressing manufacturer working capital velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Ceramic Tiles Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Tiles, Wall Tiles, Mosaic Tiles, Vitrified Tiles Application: Residential, Commercial, Industrial, Outdoor Material: Ceramic, Porcelain, Stoneware, Glazed Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cerâmica Villagres, Roca Brasil, Portobello S.A., Carmelo Fior, Lanzi Ceramica, Eliane Revestimentos, Incepa Revestimentos, Lef Ceramica, Ceusa Revestimentos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Ceramic Tiles Market Strategic Shifts
Surface decoration technology and regulatory chemistry standards are bifurcating competitive capability between capital-intensive digital producers and conventional commodity manufacturers across Brazil's ceramic belt.
Single-pass digital inkjet printing with reactive pigment deposition is fragmenting the traditional silk-screen and rotocolor decoration paradigm. São Paulo's premium residential developers are specifying photorealistic stone and wood reproductions in 600x1200mm formats. This capability dispersion is compressing margin pools for undifferentiated commodity tile while expanding architect-specified premium segments.
ANVISA's updated building material safety protocols are mandating formaldehyde and volatile organic compound thresholds for surface-contact applications. Manufacturers must submit third-party emission testing for glaze systems and backing substrates to maintain commercial project eligibility. Vitrified tile categories face the steepest compliance burden due to densified body chemistry and extended firing cycles affecting surface stability.
Builder procurement is consolidating specification authority into São Paulo and Belo Horizonte-based purchasing cooperatives. These centralized buying pools are disintermediating traditional distributor relationships and demanding direct manufacturer pricing with volume-commitment clauses. The concentration is most visible in Minas Gerais state public housing programs where consortium bidding now dominates material sourcing.
Brazil Ceramic Tiles Market Segmentation
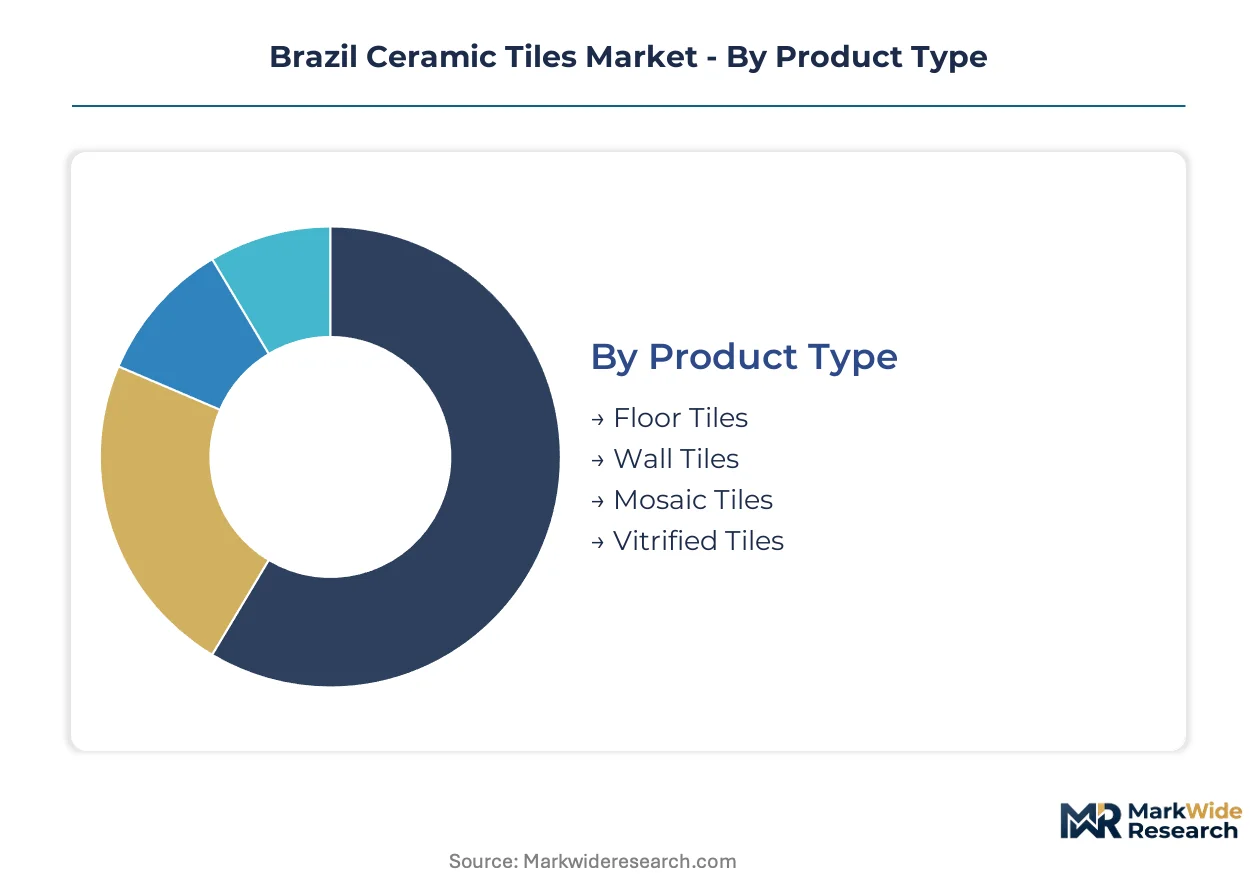
Segmentation in Brazil's ceramic tile market reveals how substitution pressures and specification requirements reshape competitive positioning across product tiers. Understanding these divides exposes where laminate flooring, vinyl plank, and alternative surfacing materials threaten incumbent volume, and where technical barriers protect margin pools.
Product Type:
Floor tiles face the most acute substitution threat from click-lock vinyl and wood-look laminates in Rio de Janeiro's apartment renovation segment, while wall and specialty formats maintain stronger defensive positions.
- Floor Tiles:Dry-pressed clay bodies fired at 1000-1200°C form the structural base for residential and commercial foot traffic applications. São Paulo state's aging housing stock and Minas Gerais replacement cycles sustain volume through distributor networks despite laminate encroachment in price-sensitive segments.
- Vitrified Tiles:Full-body porcelain with water absorption below 0.5% achieves structural densification through extended firing at 1200-1250°C. High-traffic commercial installations in Belo Horizonte's retail and hospitality sectors specify these for durability, with INMETRO slip-resistance mandates reinforcing technical procurement criteria.
- Wall Tiles:Lower-density ceramic bodies with glazed surfaces serve vertical applications where mechanical wear is minimal. São Paulo residential developers specify larger formats with digital inkjet decoration for bathroom and kitchen environments.
- Mosaic Tiles:Small-format units, typically 50x50mm to 100x100mm, compose decorative surfacing for pools, spas, and accent walls. Niche specification channels in coastal hospitality projects sustain demand despite labor-intensive installation.
Floor tiles retain volume leadership; vitrified tiles hold the steepest expansion curve.
Application:
Cost tier differentiation separates specification-grade commercial projects from commodity residential renovations across Brazil's southeastern building corridor.
- Residential:Single-family and multi-family housing dominates unit volume, with renovation cycles in São Paulo and Minas Gerais driving replacement demand. Central bank construction credit policies directly shape affordability tiers and material selection.
- Commercial:Retail, hospitality, and office installations specify technically certified products with INMETRO R9-R11 slip-resistance grading. Public space liability concerns elevate procurement standards above residential baselines.
- Industrial:Heavy-duty flooring for manufacturing and warehousing demands abrasion-resistant vitrified surfaces. Chemical exposure and mechanical load specifications filter out standard ceramic offerings.
- Outdoor:Freeze-thaw resistance and porosity control become critical for Brazilian climate zones with seasonal temperature variation. Pool decking and facade applications require specialized glaze formulations.
Residential absorbs the greatest unit volume; commercial commands the highest value per square meter.
Material:
Margin concentration tracks technical processing intensity, with beneficiated raw materials and energy-intensive firing creating tiered competitive barriers.
- Porcelain:Kaolin-rich formulations with feldspar flux achieve full vitrification and near-zero porosity. Premium positioning in São Paulo's high-end residential developments sustains above-commodity pricing.
- Ceramic:Standard red-body or white-body clay compositions serve mass-market applications with moderate durability requirements. Santa Gertrudes cluster production concentrates in this tier.
- Stoneware:Intermediate density between ceramic and porcelain offers cost-performance balance for specific commercial applications. Limited domestic production scale constrains specification penetration.
- Glazed:Surface glass coatings enable decorative range across all body types, with ANVISA emission protocols now constraining formulation chemistry. Requalification timelines extend product development cycles.
Porcelain captures the widest margin spread; ceramic maintains the deepest volume base.
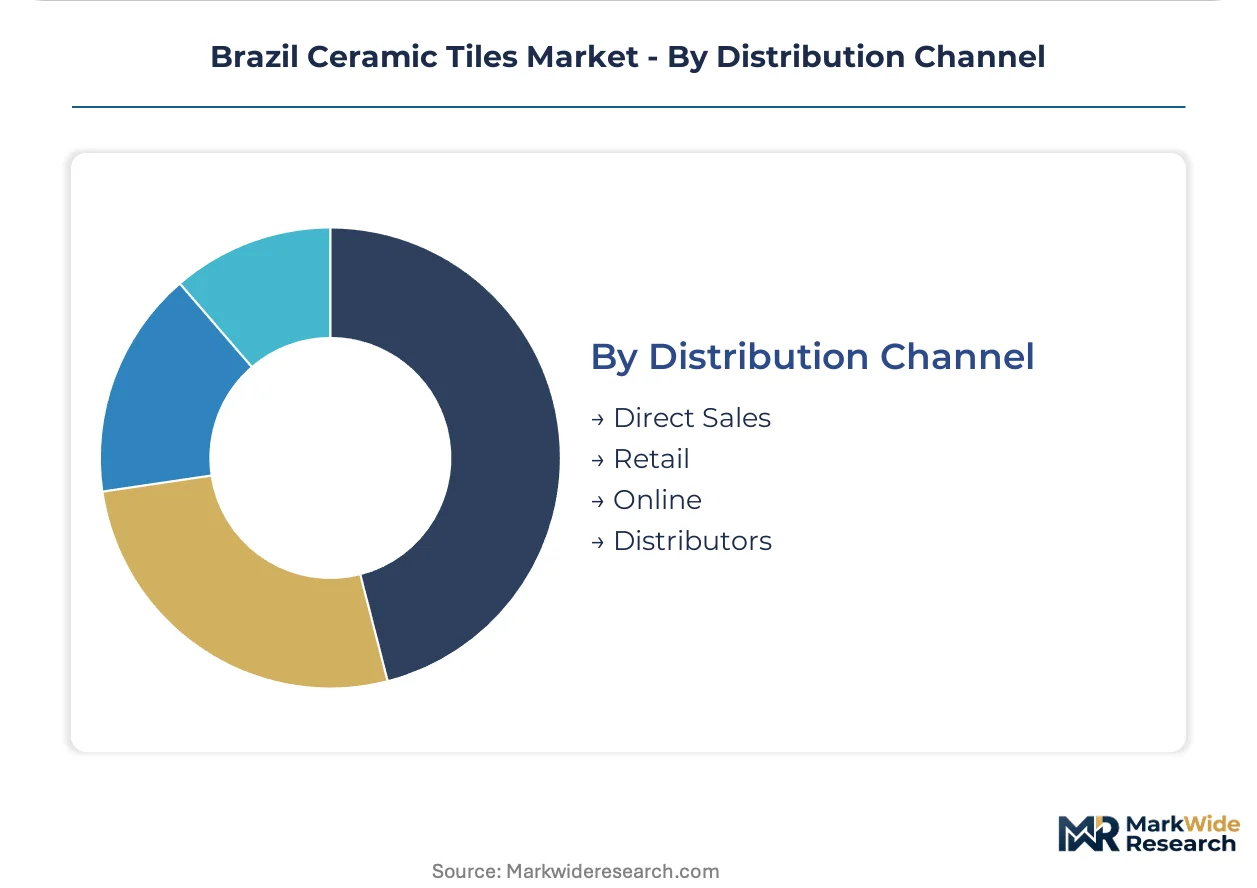
Distribution Channel:
Customer type fragmentation between consolidated purchasing cooperatives and fragmented retail networks reshapes channel economics.
- Distributors:Independent and aligned distribution networks carry inventory risk and extend credit to São Paulo's fragmented retail tile trade. Working capital velocity pressures concentrate in this tier.
- Direct Sales:Manufacturer-to-builder relationships bypass intermediaries for large-scale commercial and public housing projects. Volume-commitment clauses dominate Minas Gerais consortium bidding.
- Retail:Specialty tile showrooms and home improvement centers serve renovation-driven consumers with design consultation and installation referral services. Geographic concentration in southeastern metropolitan areas.
- Online:Digital catalog and logistics platforms capture emerging share in standardized product categories with lower specification complexity. Sample fulfillment and return logistics remain friction points.
Distributors retain the broadest geographic coverage; direct sales channels are climbing fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's building material safety protocols anchor southeastern Brazil's regulatory environment, shaping formulation standards across the country's dominant ceramic tile production belt. State-level construction credit programs and industrial clustering patterns concentrate demand and supply within three key regions.
São Paulo
Metropolitan São Paulo absorbs the largest share of porcelain-grade tile demand through high-rise residential development and commercial renovation cycles. The state's central bank-linked housing finance programs channel liquidity into replacement flooring projects. Santa Gertrudes anchors the country's densest kiln cluster, where specialized pyrometry expertise constrains output scaling.
Minas Gerais
Belo Horizonte's aging housing stock accelerates floor tile renovation cycles across the metropolitan ring. INMETRO slip-resistance mandates for public spaces elevate procurement standards above residential baselines. The state's purchasing cooperatives consolidate specification authority for public housing programs, disintermediating traditional distributor networks.
Rio Grande do Sul
Southern Brazil's industrial base sustains steady demand for abrasion-resistant vitrified surfaces in manufacturing and warehousing applications. State environmental regulations govern kiln emission thresholds for natural gas-fired production. Porto Alegre's commercial construction pipeline specifies certified R9-R11 graded products for liability-sensitive public installations.
Bahia
Northeast urban expansion in Salvador generates undersupplied demand for large-format porcelain slab capacity relative to southeastern saturation. Federal infrastructure programs channel investment into commercial and hospitality development. Local distribution networks remain fragmented, creating working capital velocity pressures for manufacturers extending credit terms.
Paraná
Curitiba's construction sector specifies technically certified products for commercial facade and outdoor applications requiring freeze-thaw resistance. State-level industrial policy supports ceramic cluster development through tax incentives for kiln modernization. The region's logistics connectivity to São Paulo distributors shapes competitive pricing dynamics.
Brazil Ceramic Tiles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's ceramic belt. Premium porcelain producers with digital printing capabilities occupy specification-driven segments, while commodity ceramic manufacturers compete on scale and raw-material proximity. Three archetypes dominate: vertically integrated clay-reserve holders, specialized large-format slab producers, and digital decoration technology adopters. Capacity expansion and glaze chemistry requalification represent the dominant competitive moves as ANVISA deadlines approach.
Among São Paulo-based producers, Portobello S.A. and Ceusa Revestimentos exemplify the technology-specialist archetype, while Eliane Revestimentos represents integrated resource control. These three occupy positions across the premium-to-standard tier spectrum, with each anchoring distinct competitive vectors in porcelain-grade and large-format segments. Their collective presence shapes specification standards and pricing benchmarks for architect-driven commercial projects.
| Leading Market Players |
|---|
| Cerâmica Villagres |
| Roca Brasil |
| Portobello S.A. |
| Carmelo Fior |
| Lanzi Ceramica |
| Eliane Revestimentos |
| Incepa Revestimentos |
| Lef Ceramica |
| Ceusa Revestimentos |
| Others |
Value Chain & Pricing Dynamics
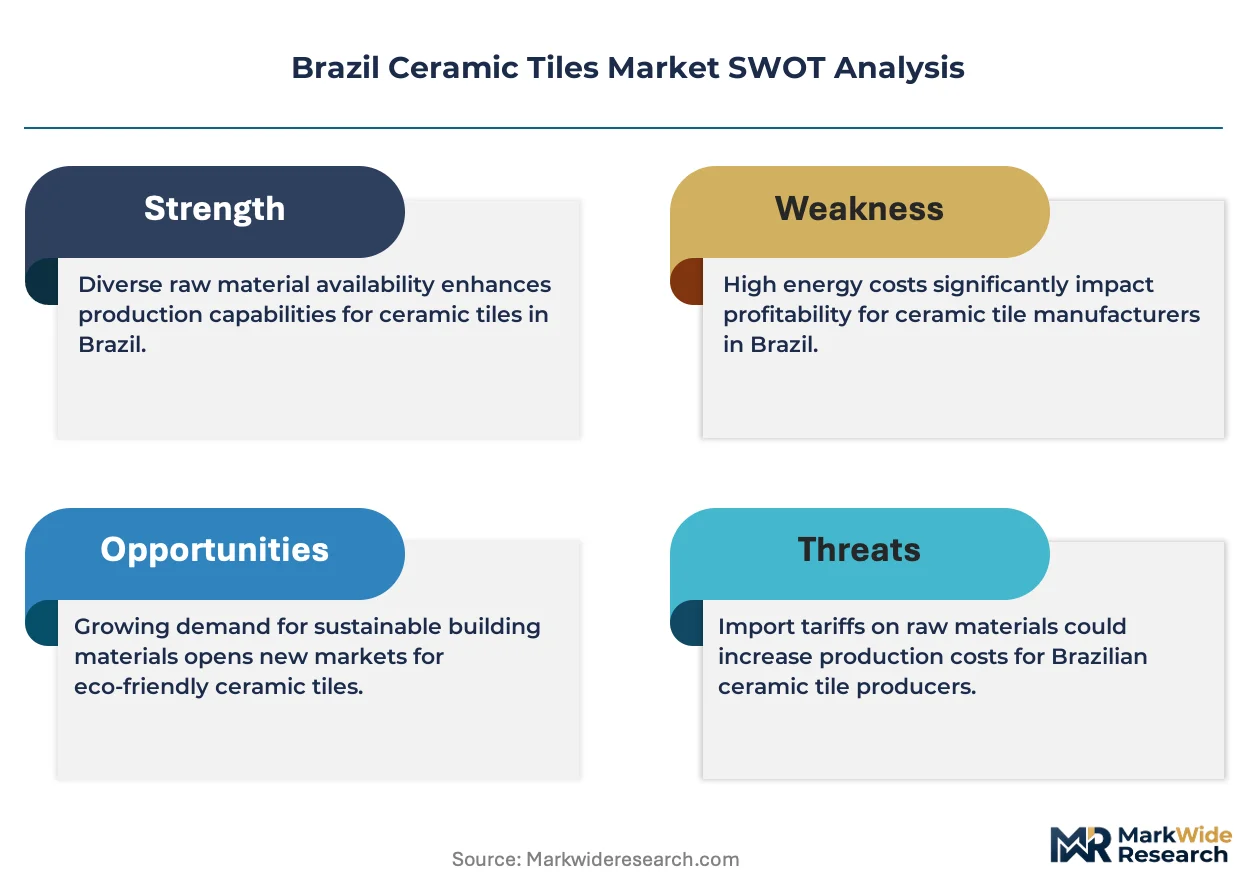
ANVISA's surface emission certification gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb requalification costs that stratify pricing tiers while filtering out non-compliant producers from commercial project eligibility.
Pricing Analysis
São Paulo metropolitan pricing spreads 15-25% above Salvador and Recife for equivalent porcelain grades, reflecting southeastern logistics advantages and distributor density. Three-tier pricing structure across premium, standard, and economy levels tracks INMETRO certification grade and digital decoration capability. Price erosion runs through commodity ceramic tiers as laminate flooring substitutes capture renovation spending in Rio de Janeiro's apartment sector. Small-scale residential renovators exhibit acute price sensitivity; architect-specified commercial projects prioritize technical compliance over unit cost.
Supply Chain Analysis
Port congestion at Santos and Paranaguá container terminals elevates inbound logistics costs for Italian and Spanish glaze additives, compressing margins on specialty formulations. Domestic production draws from captive kaolin reserves in Minas Gerais and imported feldspar flux from Argentina and Portugal. Single-source vulnerability concentrates in natural gas supply through Petrobras-linked distribution networks. Distribution runs through São Paulo-based purchasing cooperatives for large commercial projects and fragmented independent distributors for residential renovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating into São Paulo and Belo Horizonte purchasing cooperatives, disintermediating traditional distributor relationships and demanding direct manufacturer pricing with volume-commitment clauses that compress incumbent margin structures.
For Market Incumbents: Shield premium positioning by accelerating ANVISA-compliant glaze chemistry requalification ahead of certification deadlines, locking in architect-specified commercial channels. Deepen backward integration into captive clay beneficiation to offset natural gas cost volatility through input cost control. Prioritize kiln-operator apprenticeship programs in Santa Gertrudes to alleviate pyrometry expertise scarcity constraining output scaling.
For New Entrants and Emerging Players: Anchor in the undersupplied Northeast corridor, where Recife and Salvador commercial construction pipelines lack large-format porcelain slab capacity relative to southeastern saturation. Target facade cladding specification channels with thin porcelain panels for tropical climate rainscreen systems, leveraging lower incumbent presence in exterior architectural applications. Pursue direct sales relationships with federal infrastructure program contractors bypassing cooperative purchasing consolidation.
For Investors and Strategic Acquirers: ANVISA's emission protocol deadlines reshape the acquisition landscape toward targets with certified glaze systems and completed requalification timelines. Long-term viability hinges on manufacturing assets with digital inkjet printing capabilities and proven commercial specification track records. Monitor central bank construction credit expansion signals as inflection indicators for residential renovation demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Glaze Chemistry Requalification | ANVISA certification maintains commercial project eligibility ahead of regulatory deadlines. |
| Digital Inkjet Capacity Expansion | Photorealistic decoration capability captures architect-specified premium segment pricing. |
| Northeast Distribution Network Buildout | Direct presence in Salvador and Recife reduces southeastern logistics cost disadvantages. |
| Kiln Operator Training Consortium | Santa Gertrudes cluster collaboration alleviates pyrometry expertise scarcity constraining output. |
| Facade Cladding Specification Partnership | Brazilian architectural practice relationships open tropical climate exterior envelope channels. |
Study Parameters
The analysis maps porcelain-grade, ceramic, and vitrified tile sub-sectors, each validated through plant managers, procurement leads at construction firms, distributor channel partners, and technical R&D directors across Brazil's southeastern industrial belt. Primary fieldwork combined with secondary validation from INMETRO certification databases, ANVISA emission protocol filings, central bank construction credit disbursement records, and customs trade data. Bottom-up production capacity modeling and top-down demand segmentation triangulate volume and value estimates.
Consistency checks validated outputs against external benchmarks including industry association production surveys and regional construction permit filings. Segmentation dimensions modeled encompass product type, application, material grade, and distribution channel across the projection horizon. CAGRs derive from installed capacity utilization trends, replacement cycle analysis, and specification-grade penetration curves. Forecast inputs incorporate natural gas tariff trajectories and central bank monetary policy transmission to housing finance.
Decision-makers should treat outputs as directional under assumptions of stable ANVISA regulatory timelines and Petrobras fuel pricing frameworks; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Injection Molding Market
Ceramics
Activated Alumina Market
Ceramics
Global Ceramic Foams Market
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramics Packaging Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
White Fused Alumina Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Glazed Bricks Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Cerium Carbonate Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
China Clay Market
Ceramics
Calcium Silicate Boards Market