
 Ceramic Setter Plate Market | 2026-2036
Ceramic Setter Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Setter Plate Market Insights
ISO 9001 quality management certification is redrawing competitive boundaries in ceramic setter plate supply. CeramTec leverages in-house alumina processing to sustain vertical integration advantages across European kiln furniture networks. CoorsTek anchors North American demand through its dominance in high-purity oxide ceramics for semiconductor firing applications. Morgan Advanced Materials differentiates via specialized silicon carbide-coated setter plates that extend thermal cycle life in aggressive sintering environments.
Ceramic setter plates are refractory support fixtures, typically fabricated from alumina, zirconia, or silica-based compositions, engineered to withstand repeated thermal cycling up to 1,700°C while maintaining dimensional stability for precision-fired components. Their primary function is to bear green ceramic or powder metallurgy parts through binder burnout and densification stages without contamination or distortion. High-temperature plates command premium positioning due to irreplaceable performance in solid oxide fuel cell and advanced ceramic matrix composite processing. Customized plates capture expanding margin pools as dental zirconia sintering and additive manufacturing post-processing drive specification diversity beyond standard catalog offerings.
EMA medical device regulations and REACH chemical safety frameworks in Europe impose stringent migration limits on setter plate surface chemistry, directly filtering supplier eligibility for medical and dental end users. EPA emissions standards in the United States shape kiln atmosphere requirements, indirectly pressuring plate porosity and surface finish specifications to reduce volatile byproducts during firing cycles. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking, as lifecycle documentation becomes a procurement gate for multinational manufacturers sourcing setter plate fleets.
Market Dynamics
ISO 9001 quality management certification is redrawing competitive boundaries in ceramic setter plate supply, filtering supplier eligibility across European kiln furniture networks and medical device manufacturing clusters.
Growth Catalysts
- Sintering intensification in electronics:Solid oxide fuel cell manufacturers require setter plates that withstand thermal cycling above 1,600°C without dimensional drift, pulling specialized alumina and silicon carbide formulations into volume production.
- EMA medical device regulations:Migration limits on surface chemistry in Europe filter supplier pools for dental zirconia sintering applications, creating procurement gates that favor certified manufacturers.
- Germany precision ceramics clustering:The Plochingen and Laufenburg industrial corridors concentrate technical expertise and captive kiln infrastructure, anchoring regional supply security for advanced ceramic matrix composite processing.
Market Restraints
- High-purity alumina feedstock volatility:Refractory-grade alumina supply concentrates among limited mining and processing operations, exposing setter plate fabricators to input cost swings and qualification delays.
- REACH compliance friction:ECHA chemical safety documentation requirements impose multi-year requalification cycles on existing product lines, compressing effective product lifecycles and R&D amortization windows.
- Silicon carbide substitution pressure:Advanced nitride-bonded silicon carbide kiln furniture competes for high-temperature sintering applications above 1,700°C, threatening oxide ceramic plate positioning in aggressive thermal environments.
Strategic Opportunities
- Additive manufacturing post-processing:Metal binder jetting and ceramic stereolithography debinding-sintering workflows create specification diversity beyond standard catalog offerings, opening customized plate margin pools.
- EU Green Deal embodied carbon tracking:Lifecycle documentation requirements for multinational manufacturers sourcing setter plate fleets favor suppliers with verified carbon accounting, creating differentiation for early adopters.
- China dual carbon goals:Domestic kiln operators face pressure to reduce firing cycle energy intensity, creating pull for setter plates with optimized thermal mass and faster heat transfer characteristics.
Industry Challenges
- ISO 9001 certification timeline compression:Medical and dental end users demand current quality management documentation, forcing smaller fabricators through expensive third-party audit cycles to maintain contract eligibility.
- Legacy kiln fleet incompatibility:New silicon carbide-coated plate designs require atmosphere control retrofits incompatible with older pusher and tunnel kiln installations, complicating upgrade decisions for capital-constrained operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Setter Plate Market |
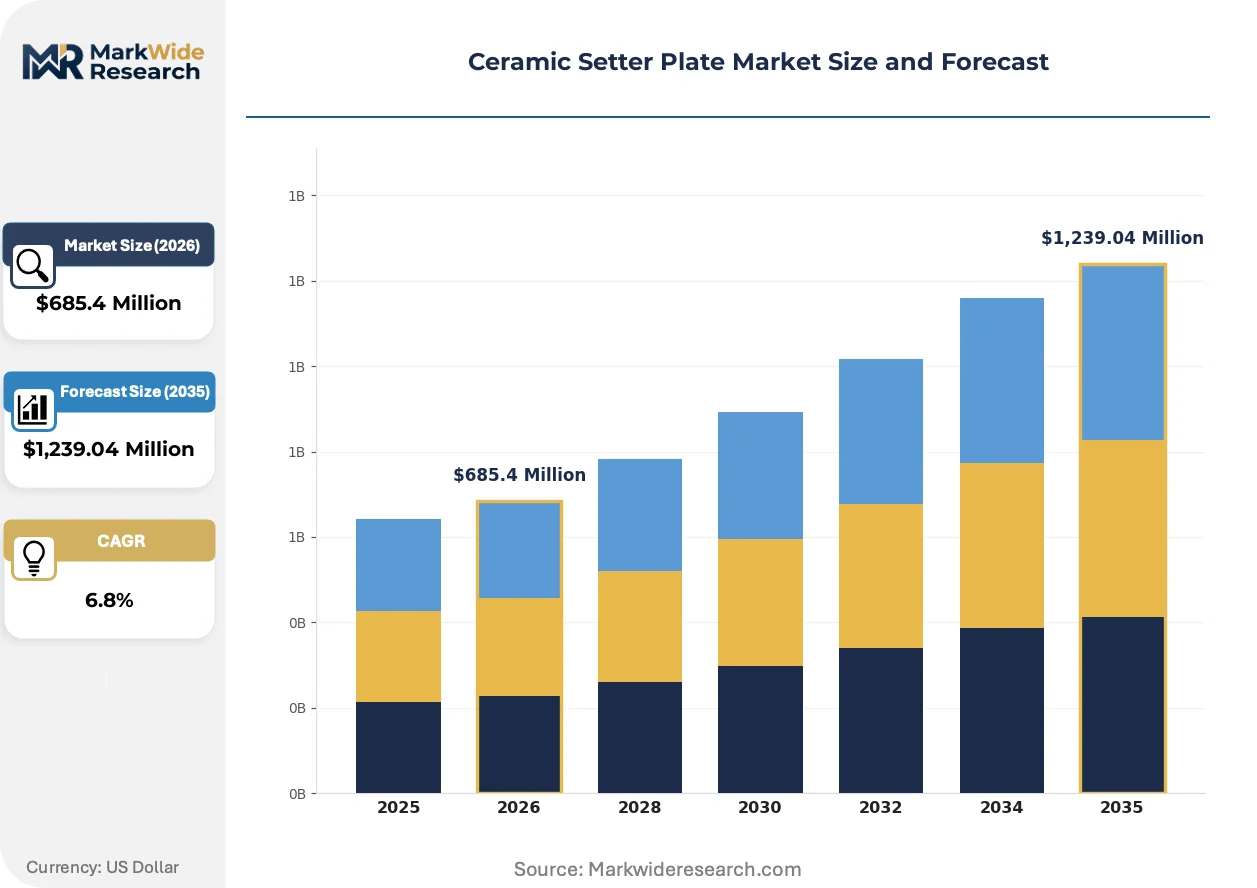
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plates, Customized Plates, High-Temperature Plates, Decorative Plates Application: Industrial, Medical, Dental, Artistic Material: Alumina, Zirconia, Silica, Porcelain End User: Manufacturers, Hospitals, Art Studios, Research Institutions |
| Companies Covered | CeramTec, Kerafol, Applied Ceramics, CoorsTek, Morgan Advanced Materials, Saint-Gobain, IPS Ceramics, Anderman Industrial Ceramics, UNIPRETEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Setter Plate Market Trends and Innovations
Setter plate technology is fragmenting across performance tiers as end-use specifications diverge between commodity ceramic firing and precision medical sintering applications.
Nitride-bonded silicon carbide formulations are fragmenting the high-temperature segment. Solid oxide fuel cell manufacturers adopt these plates for thermal cycling above 1,700°C. This displacement compresses pricing power for traditional oxide ceramic suppliers in aggressive sintering environments.
REACH chemical safety frameworks in Europe tighten migration limits on setter plate surface chemistry. ECHA documentation requirements now filter supplier eligibility for medical and dental end users. German precision ceramics clusters around Plochingen are responding with dedicated clean-room finishing lines to maintain contract access.
Buyer consolidation among dental zirconia manufacturers concentrates procurement leverage. Large dental laboratory networks now specify custom plate dimensions and surface finishes directly, displacing traditional distributor channels. This pattern is most visible in Germany and Switzerland where dental device manufacturing clusters dominate regional demand.
Ceramic Setter Plate Market Segmentation
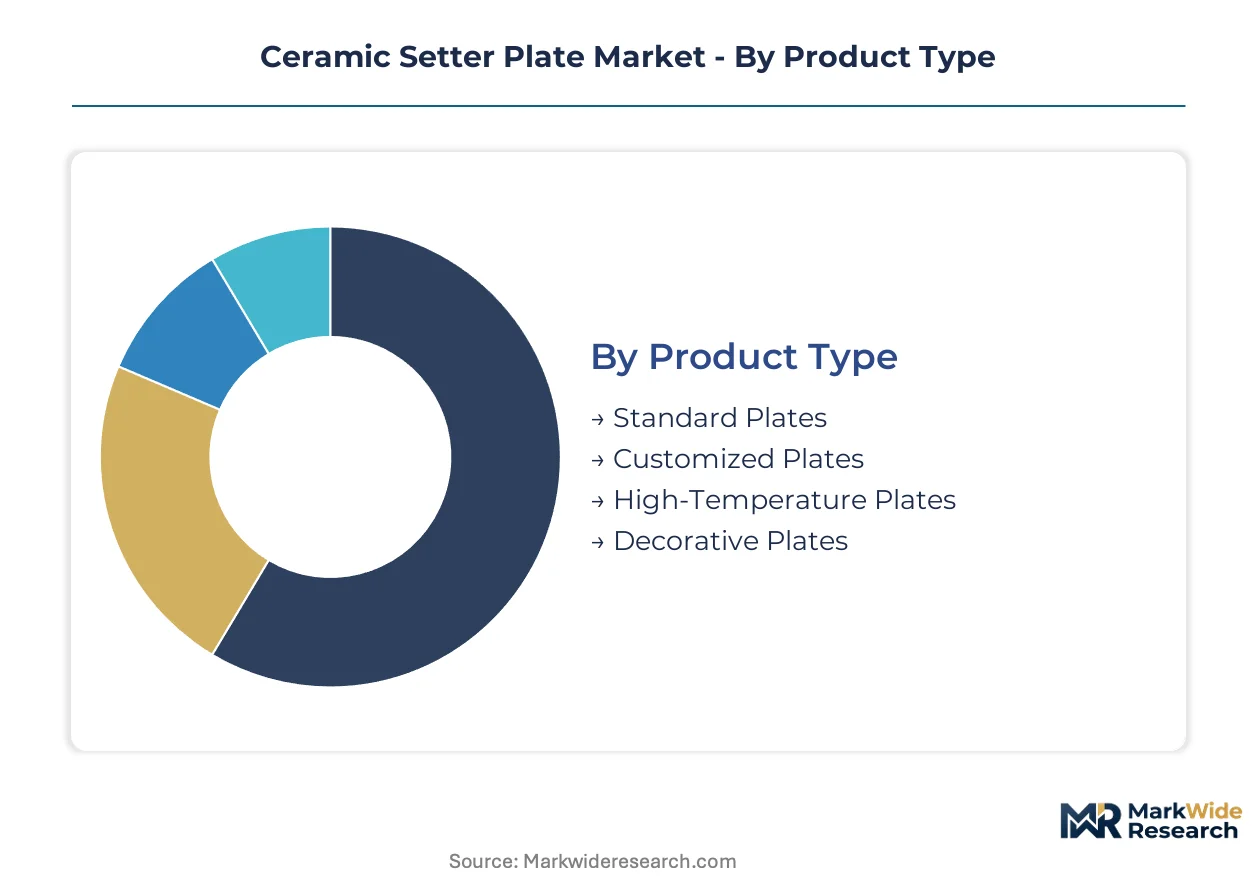
Setter plate specifications diverge sharply between commodity ceramic firing and precision medical sintering, with regulatory thresholds filtering supplier eligibility across each segment tier. Material purity grades and dimensional tolerances now function as procurement gates rather than simple product differentiators.
Product Type:
EMA migration limits and ISO 13485 certification requirements split the product landscape between certified precision plates and general industrial grades.
- Standard Plates:Catalog-dimensioned alumina and silica compositions serve commodity ceramic firing with fixed thermal cycling limits. German dental laboratories in the Plochingen corridor source these for volume zirconia crown production where specification variance stays within 2%. REACH documentation requirements now filter supplier pools for any medical-adjacent use.
- Customized Plates:Tailored dimensions and surface finishes accommodate additive manufacturing post-processing workflows and dental laboratory network consolidation. Swiss and German buyers now specify pore size distributions and flatness tolerances directly, displacing traditional distributor channels.
- High-Temperature Plates:Engineered for thermal cycling above 1,600°C in solid oxide fuel cell manufacturing.
- Decorative Plates:Lower-purity formulations for artistic ceramic firing with minimal certification overhead.
Standard plates handle the majority of throughput; customized plates are expanding most quickly on share.
Application:
End-use thermal profiles and contamination sensitivity determine material selection and surface finish specifications across the four application tiers.
- Industrial:High-volume electronics manufacturing and powder metallurgy sintering dominate consumption. Silicon carbide-coated plates from specialized European fabricators extend thermal cycle life in aggressive kiln atmospheres above 1,500°C.
- Medical:EMA device regulations impose stringent surface chemistry migration limits. German clean-room finishing lines now qualify plates specifically for implantable ceramic processing.
- Dental:Zirconia sintering for crown and bridge fabrication concentrates demand in Switzerland and Germany.
- Artistic:Studio pottery and sculptural ceramic firing with minimal regulatory constraint.
Industrial applications absorb the greatest plate volume; dental sintering is climbing the fastest on specification intensity.
Material:
Feedstock purity grades and thermal expansion coefficients anchor cost structures and performance ceilings across oxide and non-oxide formulations.
- Alumina:Refractory-grade compositions with 99.7% purity and above command premium positioning in semiconductor firing applications. Supply concentrates among limited mining and processing operations, exposing fabricators to input cost volatility.
- Zirconia:Yttria-stabilized tetragonal polycrystal formulations dominate dental sintering fixtures. Transformation toughening mechanisms enable thinner plate designs with equivalent mechanical reliability.
- Silica:Cost-effective option for lower-temperature artistic and some industrial firing cycles.
- Porcelain:Traditional ceramic body compositions for decorative and heritage restoration applications.
Alumina plates carry the highest unit economics; zirconia formulations are gaining share fastest in medical-grade specifications.
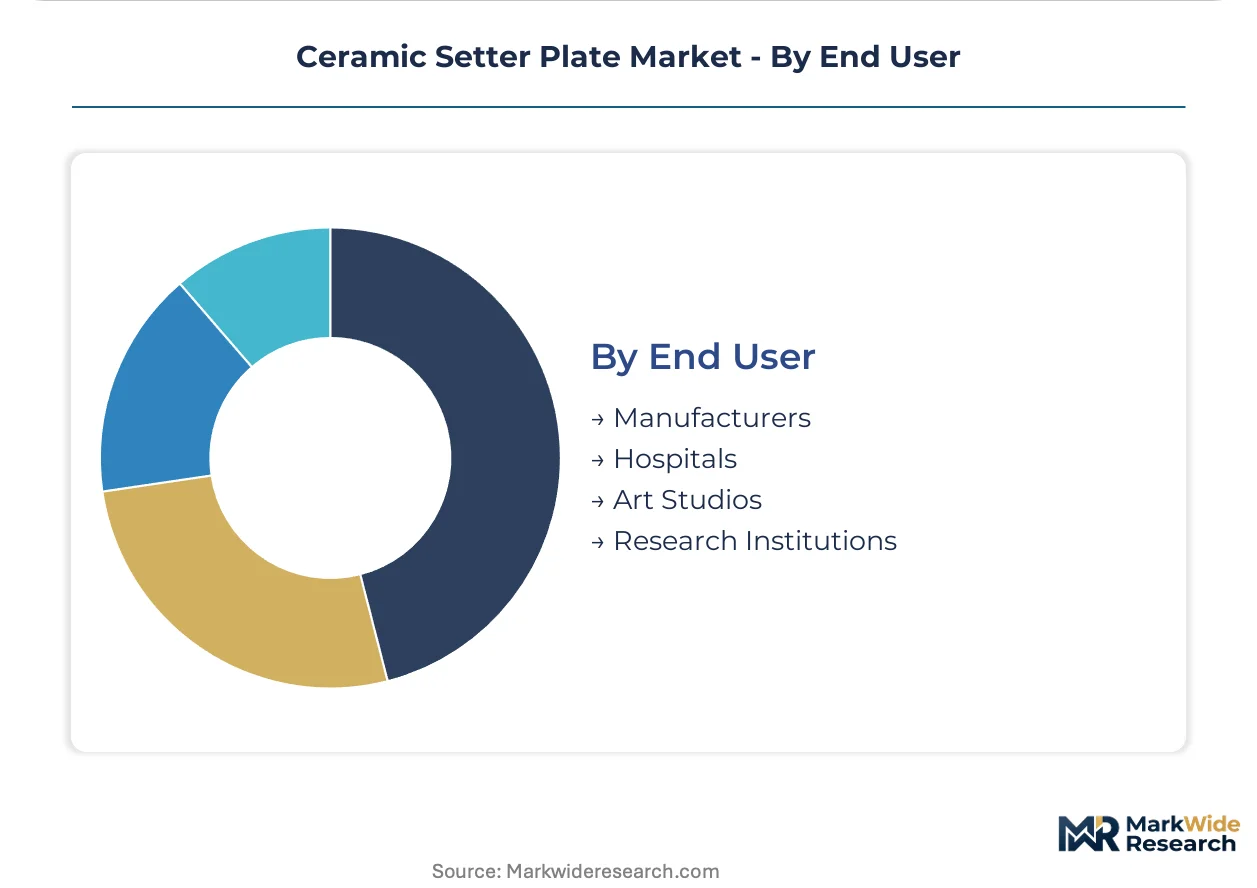
End User:
Procurement sophistication and quality documentation requirements separate institutional buyers from price-sensitive studio operators.
- Manufacturers:Solid oxide fuel cell producers and advanced ceramic matrix composite processors require lot traceability and thermal cycle documentation. Multinational manufacturers now demand embodied carbon accounting under EU Green Deal frameworks.
- Hospitals:In-house dental laboratories and orthopedic ceramic processing units specify ISO 9001-certified plate suppliers exclusively.
- Art Studios:Individual ceramicists and educational institutions with minimal certification requirements.
- Research Institutions:Materials science laboratories requiring small-batch custom specifications.
Manufacturers drive the bulk of specialized plate demand; hospitals are expanding procurement specifications fastest on regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational manufacturers and dental laboratory networks concentrate procurement leverage in Germany, the United States, China, and Japan, with regulatory compliance requirements filtering supplier eligibility unevenly across these buyer clusters.
Germany
Precision ceramics clusters around Plochingen and Laufenburg anchor European demand for high-temperature setter plates in solid oxide fuel cell manufacturing. REACH compliance through ECHA imposes multi-year requalification cycles on existing product lines. Clean-room finishing lines in Baden-Württemberg now qualify plates specifically for EMA-regulated medical device processing.
United States
Semiconductor firing applications and powder metallurgy sintering drive consumption of high-purity alumina formulations. EPA emissions standards shape kiln atmosphere requirements, indirectly pressuring plate porosity specifications to reduce volatile byproducts. CoorsTek anchors North American supply through captive oxide ceramic processing infrastructure.
China
Domestic kiln operators face pressure under dual carbon goals to reduce firing cycle energy intensity, creating demand for plates with optimized thermal mass. MIIT industrial policy supports advanced ceramic matrix composite development. Yangtze River Delta manufacturing corridors concentrate technical ceramic fabrication capacity for electronics supply chains.
Japan
Materials science laboratories and precision electronics manufacturers specify small-batch custom plate dimensions with stringent flatness tolerances. METI industrial standards govern refractory material specifications for high-temperature applications. Nagoya-area ceramic engineering clusters maintain captive kiln infrastructure for automotive sensor component processing.
Switzerland
Dental zirconia sintering for crown and bridge fabrication concentrates demand among specialized laboratory networks. Swissmedic device regulations align with EMA migration limits on surface chemistry, filtering supplier pools to ISO-certified fabricators. Zurich and Basel metropolitan corridors host dental device manufacturing clusters that specify custom plate dimensions directly.
Ceramic Setter Plate Market Competitive Landscape
Player mix skews toward vertically integrated oxide ceramic specialists and silicon carbide-coated plate innovators, with tiered certification requirements fragmenting supplier eligibility across medical and industrial end uses. Consolidation pressures concentrate among European kiln furniture networks where REACH documentation overhead favors scaled manufacturers. Two strategic archetypes dominate: backward-integrated alumina processors controlling feedstock purity, and coating technology specialists extending thermal cycle life. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as fabricators seek to bypass requalification bottlenecks.
Among European-based fabricators, CeramTec GmbH and Morgan Advanced Materials occupy positions reflecting divergent specialization strategies. CeramTec exemplifies the backward-integrated archetype through in-house refractory-grade alumina processing. Morgan Advanced Materials represents the coating-technology vector with silicon carbide surface treatments. CoorsTek anchors North American positioning as a scale-driven oxide ceramic supplier. These three entities collectively illustrate how geographic clustering and vertical control separate premium-tier positioning from commodity fabrication.
| Leading Market Players |
|---|
| CeramTec |
| Kerafol |
| Applied Ceramics |
| CoorsTek |
| Morgan Advanced Materials |
| Saint-Gobain |
| IPS Ceramics |
| Anderman Industrial Ceramics |
| UNIPRETEC |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at refractory-grade alumina smelters in Germany and China anchors cost floors across the ceramic setter plate value chain. Scale concentration among limited mining operations transmits directly to plate fabricators through indexed raw material contracts, compressing margin flexibility for mid-tier producers while rewarding backward-integrated specialists with captive feedstock control.
Pricing Analysis
Long-term offtake agreements with alumina indexation dominate procurement between German precision ceramics clusters and refractory suppliers. Price differentiation rests on ISO 13485 certification tier and thermal cycle performance documentation, with medical-grade plates commanding substantial premiums over industrial catalog offerings. Cost compression in standard alumina formulations is intensifying as Chinese kiln operators consolidate plate purchases under volume frameworks. Dental laboratory networks in Switzerland and Germany exhibit the lowest price sensitivity due to regulatory compliance requirements, while artistic ceramic studios remain highly responsive to unit cost fluctuations.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German solid oxide fuel cell manufacturers with captive kiln infrastructure, whereas Chinese operators maintain strategic alumina stockpiles to buffer feedstock volatility. Supply concentrates in Germany, China, and the United States, with refractory-grade alumina processing anchored in Australian bauxite conversion and Chinese refining capacity. The chain draws from high-purity alumina, yttria-stabilized zirconia, and silicon carbide precursor chemicals. Single-source vulnerability concentrates in Australian bauxite supply routes. Distribution runs through direct technical sales teams for medical and industrial OEMs, with distributor channels serving smaller artistic and research end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitride-bonded silicon carbide kiln furniture substitution threatens oxide ceramic plate incumbents in thermal cycling applications above 1,700°C, forcing defensive repositioning across the value chain.
For Market Incumbents: Shield market position through backward integration into refractory-grade alumina processing and accelerated REACH documentation cycles that filter smaller competitors. Prioritize captive supply of high-purity feedstock to insulate margin structures from raw material volatility. Defend against silicon carbide substitution by extending thermal cycle life through coating technology investments. For New Entrants and Emerging Players: Anchor in additive manufacturing post-processing workflows where specification diversity outpaces incumbent catalog breadth. Target dental zirconia sintering networks in Switzerland and Germany with custom dimension capabilities that bypass traditional distributor channels. Pursue ISO 13485 certification as the primary go-to-market credential for medical device procurement gates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated alumina processors with long-term offtake agreements to semiconductor and solid oxide fuel cell manufacturers. Five-to-ten year viability favors fabricators with verified embodied carbon accounting under EU Green Deal frameworks. Acquisition targets should demonstrate clean-room finishing infrastructure and EMA compliance documentation. Watch for REACH requalification bottlenecks that force distressed divestitures from smaller European players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Processing | Captive feedstock control insulates CeramTec and peers from refractory-grade supply volatility. |
| REACH Documentation Acceleration | ECHA compliance timelines filter competitor pools and extend effective product lifecycles for certified fabricators. |
| Silicon Carbide Coating Technology Investment | Morgan Advanced Materials extends thermal cycle life to defend against nitride-bonded substitution threats. |
| Clean-Room Finishing Line Expansion | Baden-Württemberg facilities qualify plates for EMA-regulated medical device processing contracts. |
| Embodied Carbon Accounting Verification | EU Green Deal documentation becomes procurement gate for multinational manufacturer setter plate fleets. |
Research Methodology
Initial hypotheses were tested against primary input from kiln operations managers, dental laboratory procurement leads, semiconductor firing process engineers, and refractory material R&D directors and refined through secondary validation across customs trade databases, SEC filings from listed ceramics specialists, ECHA REACH registration dossiers, and MIIT industrial policy directives. Bottom-up demand modeling triangulated against top-down value chain analysis.
Variance decomposition across material grade, application thermal profile, end-user certification tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating solid oxide fuel cell manufacturing expansion, dental zirconia sintering intensity, and additive manufacturing post-processing adoption curves.
Material uncertainties — alumina feedstock supply disruptions, REACH requalification timeline extensions, and silicon carbide substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory stability and technology transition rates. Revision becomes warranted when nitride-bonded silicon carbide penetration in high-temperature applications crosses threshold levels that structurally compress oxide ceramic pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramics Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Ceramic Frit Market
Ceramics
Global Alumina Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Ceramic Proppant Market
Ceramics
Zirconium Dioxide Market
Ceramics
China Ceramic Tiles Market
Ceramics
Global Ceramic Coating Market
Ceramics
China Clay Market
Ceramics
Titanium Carbide Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Ceramic Lining Market
Ceramics
Strontium Carbonate Market
Ceramics
Transparent Ceramics Market
Ceramics
West Africa Ceramic Tiles Market