
 Ceramic Additives Market | 2026-2036
Ceramic Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Additives Market Outlook
Specialty chemical distribution through regional formulator networks is reshaping how ceramic additive producers reach tile and sanitary ware manufacturers. BASF SE leverages its global pigment and dispersant portfolio to anchor supply relationships with major ceramic clusters. Evonik Industries AG specializes in high-performance defoamers and rheology modifiers that sustain premium positioning in technical ceramics. Dow Inc. competes through its acrylic polymer expertise, extending binder technology into advanced electrical insulator applications.
Ceramic additives encompass functional chemicals and polymers introduced during clay body preparation, glaze formulation, or firing to modify plasticity, dispersion stability, sintering behavior, or surface properties, typically dosed at 0.1-5.0 wt% depending on the target rheological or mechanical outcome. Their primary purpose is to reduce water demand, enhance green strength, control shrinkage, and enable defect-free surfaces in fired ceramic goods. Dispersants dominate volume consumption in ceramic tile production where water reduction directly cuts drying energy and firing costs. Plasticizers command margin concentration in technical ceramics and electrical insulators where dimensional precision justifies premium formulation spend. Bonding agents represent the fastest-growing category as additive manufacturing of ceramic components expands across aerospace and biomedical prototyping.
EPA oversight of volatile organic compound emissions from ceramic kiln operations shapes additive selection toward low-VOC dispersants and binders in United States manufacturing. REACH registration requirements in Europe restrict certain phthalate-based plasticizers, redirecting formulation development toward bio-derived alternatives. China's GB standards for building materials, enforced by SAMR and MEE, mandate heavy metal limits in ceramic glazes that directly influence additive purity specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain cross-border formulation compliance.
Market Dynamics
Construction sector procurement of dispersants and plasticizers for ceramic tile production is intensifying as builders prioritize material efficiency. REACH compliance in Europe and evolving EPA standards in the United States are tightening chemical disclosure requirements for ceramic additive formulations.
Growth Catalysts
- China's infrastructure programs:Government-backed construction initiatives sustain large-scale sanitary ware and tile manufacturing, concentrating demand for water-reducing dispersants.
- REACH registration requirements:Phthalate restrictions in Europe redirect formulation development toward bio-derived plasticizers, opening premium positioning for compliant suppliers.
- Additive manufacturing expansion:Aerospace and biomedical prototyping of ceramic components is accelerating consumption of specialized bonding agents.
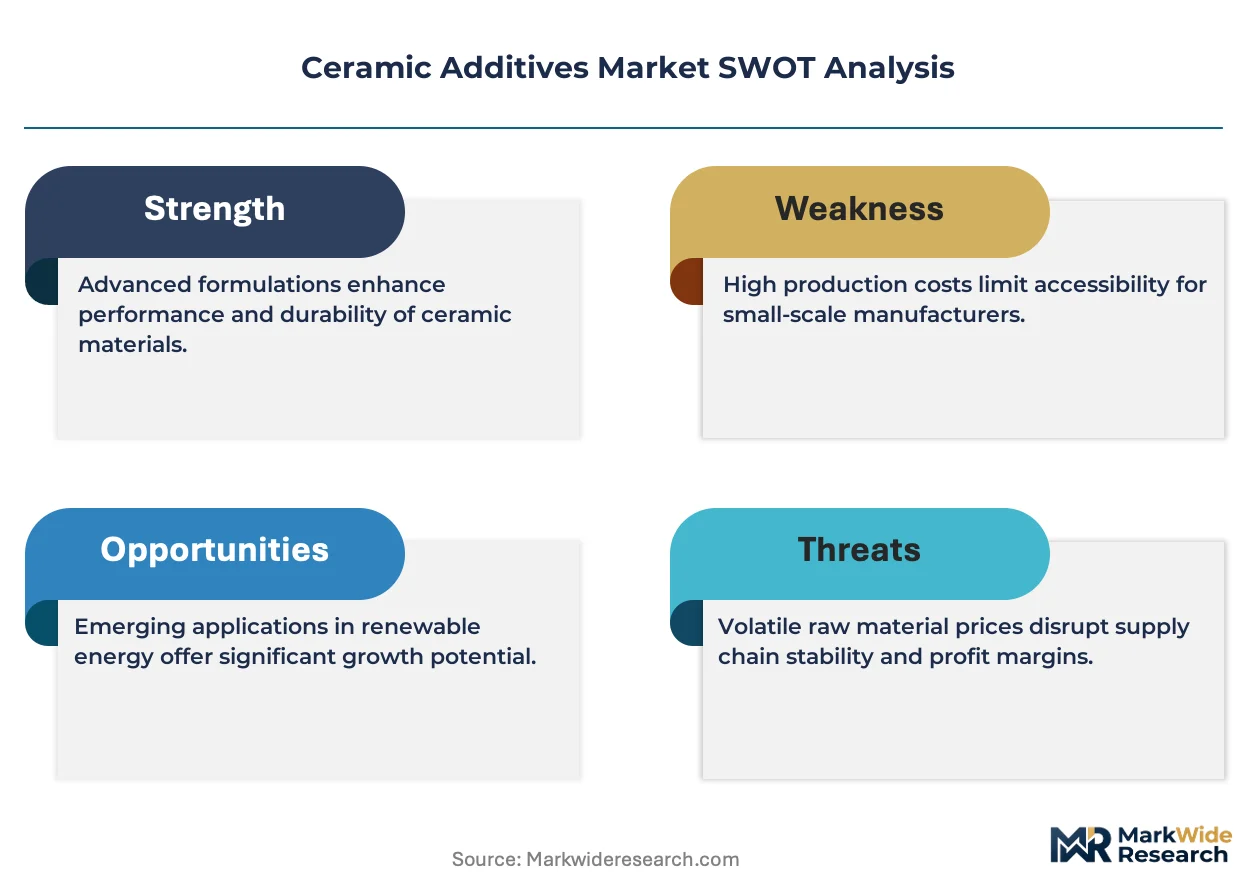
Market Restraints
- Petrochemical feedstock volatility:Acrylic polymer and solvent prices fluctuate with crude oil markets, compressing margins for binder producers.
- Supply concentration in China:Bulk dispersant manufacturing clusters in Shandong and Guangdong provinces create geographic dependency risks for global buyers.
- Technical ceramics precision barriers:Dimensional tolerance requirements below 0.1% limit qualified supplier pools for high-performance rheology modifiers.
Strategic Opportunities
- India's ceramic cluster expansion:Morbi and Thangadh tile manufacturing hubs remain underpenetrated by specialty chemical distributors.
- GB standard heavy metal limits:China's SAMR enforcement of glaze purity specifications creates demand for certified low-impurity additive grades.
- Digital formulation platforms:AI-driven rheology prediction tools are converging with laboratory automation to compress development cycles.
Industry Challenges
- Cross-jurisdictional compliance complexity:Divergent EPA, REACH, and GB standards force manufacturers to maintain parallel inventory lines.
- Specialized formulation talent scarcity:Ceramic chemists with dual expertise in colloid science and kiln firing dynamics command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Additives Market |
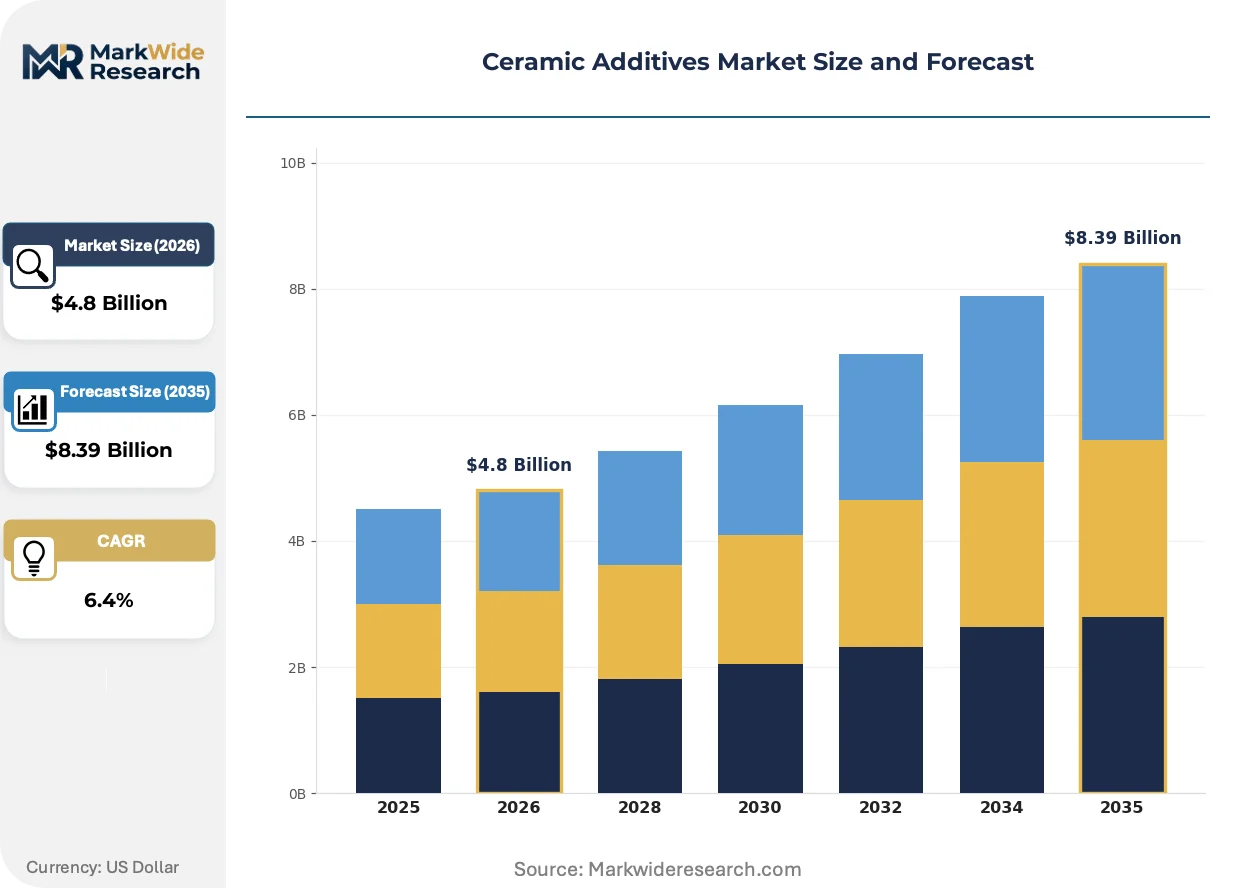
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Dispersants, Starch, Bonding Agents Application: Ceramic Tiles, Sanitary Ware, Tableware, Electrical Insulators End User: Construction, Consumer Goods, Electronics, Healthcare Technology: Drying, Casting, Extrusion, Firing |
| Companies Covered | BASF SE, Evonik Industries AG, Dow Inc., Ashland Inc., Lamberti Group, Sanyo Chemical Industries Ltd., Solvay S.A., Wacker Chemie AG, BOZZETTO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Additives Market Strategic Shifts
Specialty chemical distribution through regional formulator networks is reshaping how ceramic additive producers reach tile and sanitary ware manufacturers. Three developments are compressing traditional supply relationships.
Nano-engineered dispersant architectures with tailored particle size distributions are rendering obsolete conventional polyelectrolyte systems in high-speed tile pressing operations. Italian and Spanish tile manufacturers have adopted these systems at commercial scale since 2023. The shift is compressing supplier margins on legacy product lines while rewarding integrated polymer-pigment portfolios.
REACH authorization procedures for persistent organic pollutants now explicitly scrutinize per- and polyfluoroalkyl substances in ceramic processing aids. The European Chemicals Agency's 2024 restriction proposals force reformulation of defoamers and release agents. Technical ceramics producers in Germany and France are accelerating qualification of silicone-free alternatives.
Direct procurement relationships between additive manufacturers and large tile groups are displacing traditional distributor intermediaries in Southern Europe. Morbi-based manufacturers now negotiate volume contracts with BASF and Dow technical service teams. The pattern is most visible in commodity dispersant categories where specification standardization enables bypass.
Ceramic Additives Market Segmentation
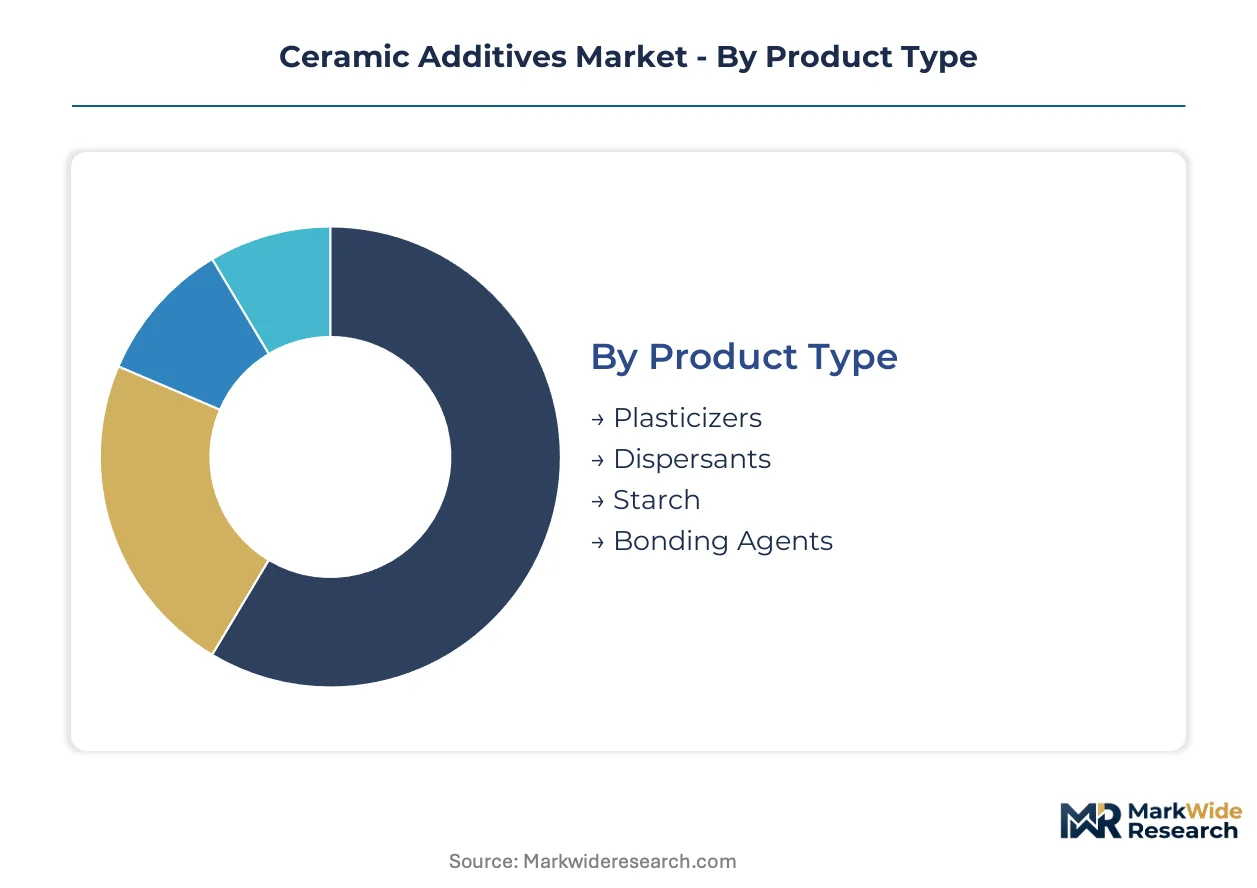
Ceramic additives serve distinct functional roles across manufacturing stages, from clay body preparation through final firing. Segmentation reveals how formulation chemistry aligns with end-product performance requirements and regulatory constraints.
Product Type:
Cost tier differentiation separates commodity bulk chemicals from specialty performance grades.
- Plasticizers:Phthalate and bio-derived alternatives enhance green strength and plasticity in extruded clay bodies. REACH restrictions in Europe redirect procurement toward compliant bio-based grades, compressing margins on legacy formulations.
- Dispersants:Polyelectrolyte and nano-engineered architectures reduce water demand in wet milling operations. Italian and Spanish tile manufacturers have adopted advanced systems at commercial scale, displacing conventional chemistries.
- Starch:Natural binder for temporary green strength in pressed ware before burnout during firing.
- Bonding Agents:Acrylic and PVA-based systems for additive manufacturing of technical ceramics. Aerospace and biomedical prototyping applications are expanding consumption fastest.
Dispersants hold installed capacity. Bonding agents are rotating up the share rankings.
Application:
Volume concentration tracks construction intensity and infrastructure investment cycles.
- Ceramic Tiles:Wall and floor tile production consumes dispersants and plasticizers at highest volume. China's government-backed infrastructure programs sustain large-scale manufacturing clusters in Shandong and Guangdong provinces.
- Sanitary Ware:Toilets, sinks, and bathroom fixtures require controlled shrinkage additives for dimensional stability. Indian manufacturing hubs in Morbi and Thangadh remain underpenetrated by specialty chemical distributors.
- Tableware:Decorative and functional dining ceramics prioritize glaze compatibility and surface finish.
- Electrical Insulators:Technical ceramics for power transmission demand ultra-pure formulations with heavy metal limits enforced by China's SAMR.
Ceramic tiles hold installed capacity. Electrical insulators are rotating up the share rankings.
End User:
Customer type determines specification stringency and procurement relationship structure.
- Construction:Builders prioritize material efficiency and drying energy reduction. Procurement of dispersants and plasticizers intensifies as large tile groups negotiate direct contracts with additive manufacturers.
- Consumer Goods:Tableware and decorative ceramic manufacturers balance cost with aesthetic performance.
- Electronics:Substrate and insulator applications require precision tolerances below 0.1%, limiting qualified supplier pools for high-performance rheology modifiers.
- Healthcare:Biomedical ceramic prototyping for implants and surgical tools drives specialized bonding agent demand.
Construction holds installed capacity. Healthcare is rotating up the share rankings.
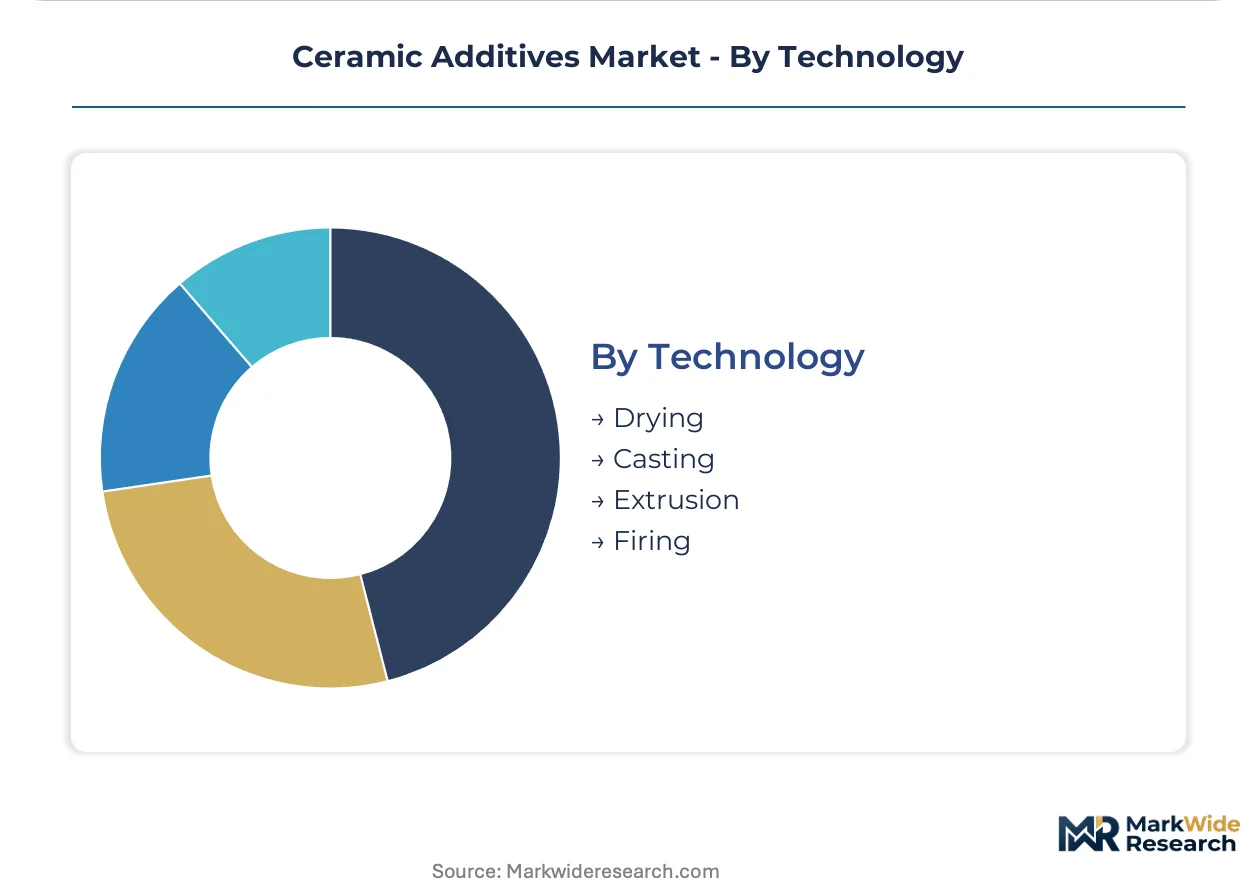
Technology:
Manufacturing process stage dictates additive function and dosing protocol.
- Drying:Moisture control additives prevent crack formation during water removal. Energy costs in this stage drive dispersant adoption for reduced water content.
- Casting:Slip preparation for sanitary ware and technical ceramics requires defoamers and rheology modifiers.
- Extrusion:Plasticizers enable continuous forming of structural clay products and honeycomb substrates.
- Firing:Burnout agents and sintering aids control shrinkage and surface properties in the kiln.
Drying holds installed capacity. Casting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Italian and Spanish ceramic clusters where nano-engineered dispersant adoption commands premium positioning, while Chinese bulk manufacturers compete on volume at compressed margins. This asymmetry shapes procurement patterns across construction and technical ceramics segments.
China
Government-backed infrastructure programs sustain large-scale sanitary ware and tile manufacturing in Shandong and Guangdong provinces. SAMR and MEE enforcement of GB standard heavy metal limits in ceramic glazes mandates certified low-impurity additive grades. Manufacturing clusters in Foshan and Zibo concentrate bulk dispersant consumption for water-reduction efficiency.
Italy
High-speed tile pressing operations in Sassuolo and Modena districts drive adoption of nano-engineered dispersant architectures. REACH compliance requirements redirect formulation sourcing toward bio-derived plasticizer alternatives. Technical ceramics producers in Emilia-Romagna accelerate qualification of silicone-free defoamers under ECHA 2024 restriction proposals.
Spain
Castellón province tile manufacturers negotiate direct procurement contracts with additive technical service teams, displacing traditional distributor intermediaries. ECHA scrutiny of per- and polyfluoroalkyl substances forces reformulation of processing aids. Alcora and Vila-real clusters concentrate demand for advanced rheology modifiers in premium tile production.
United States
EPA oversight of volatile organic compound emissions from ceramic kiln operations shapes additive selection toward low-VOC dispersants and binders. Construction sector procurement intensifies as builders prioritize material efficiency and drying energy reduction. Tennessee and Ohio manufacturing bases serve electrical insulator applications with precision tolerance requirements.
India
Morbi and Thangadh tile manufacturing hubs in Gujarat remain underpenetrated by specialty chemical distributors, creating whitespace for regional formulator networks. BIS standards for building materials influence glaze additive specifications. Sanitary ware production expansion in these clusters drives demand for controlled shrinkage additives.
Ceramic Additives Market Competitive Environment
Integrated chemical conglomerates and specialty additive specialists split the market between scale-driven pigment-dispersant portfolios and precision-formulated rheology modifiers. Three archetypes dominate: multinational polymer-science leaders with construction sector anchoring, European fine-chemical specialists serving technical ceramics, and regional formulator networks penetrating underdeveloped clusters. Capacity expansion in China's Shandong province and strategic partnerships between additive producers and large tile groups represent the dominant competitive vectors.
Among integrated chemical conglomerates, BASF SE and Dow Inc. occupy positions defined by global polymer-science capabilities and construction sector relationships. Evonik Industries AG exemplifies the European fine-chemical specialist archetype, with its AG suffix indicating German corporate structure. These three companies represent distinct strategic postures: scale-anchored supply relationships, acrylic polymer expertise extension, and high-performance modifier specialization respectively. Their positioning reflects how formulation chemistry aligns with end-product performance tiers and regulatory compliance requirements.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Dow Inc. |
| Ashland Inc. |
| Lamberti Group |
| Sanyo Chemical Industries Ltd. |
| Solvay S.A. |
| Wacker Chemie AG |
| BOZZETTO Group |
| Others |
Value Chain & Pricing Dynamics
Shandong and Guangdong province manufacturing clusters concentrate bulk dispersant production, anchoring margin pools with Italian and Spanish tile manufacturers who command premium positioning through nano-engineered formulations. This geographic asymmetry forces global buyers to navigate divergent cost structures across commodity and specialty tiers.
Pricing Analysis
Configured-to-order pricing for nano-engineered dispersants commands spreads of 40-60% above standard polyelectrolyte grades in Sassuolo and Modena districts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from petrochemical feedstock volatility compressing margins on acrylic binder formulations. Large tile groups in Southern Europe exhibit lowest price sensitivity due to direct procurement relationships, while Morbi-based manufacturers remain most cost-conscious.
Supply Chain Analysis
Petrochemical feedstocks from Saudi Arabia, South Korea, and the United States anchor acrylic polymer and solvent supply for binder production. Raw material dependencies center on propylene oxide, ethylene derivatives, and specialty silicone chemistries for defoamer formulations. Single-source vulnerability concentrates in Shandong province bulk dispersant manufacturing. Distribution runs through regional formulator networks in underpenetrated Indian clusters and direct technical service teams in mature European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated tile manufacturing groups in Southern Europe and China, fragmenting traditional distributor intermediaries and compressing supplier negotiation leverage.
For Market Incumbents: Entrench supply relationships through captive technical service teams embedded in Foshan and Zibo manufacturing clusters. Backward integration into acrylic polymer production hedges petrochemical feedstock exposure. Prioritize REACH-compliant bio-derived plasticizer certification to defend positioning against regulatory displacement of phthalate formulations. For New Entrants and Emerging Players: India's Morbi and Thangadh tile hubs offer geographic underpenetration by specialty chemical distributors with limited local formulator presence. Target sanitary ware controlled shrinkage additives where specification standardization remains incomplete. Pursue volume contract anchoring with mid-tier tile groups seeking alternatives to BASF and Dow procurement relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European fine-chemical specialists holding precision rheology modifier portfolios. Five-to-ten year viability hinges on additive manufacturing ceramic bonding agent qualification trajectories. Watch for ECHA restriction finalization on per- and polyfluoroalkyl substances as inflection indicator for silicone-free defoamer replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply of propylene oxide derivatives insulates margin compression from crude-linked petrochemical volatility. |
| REACH-Compliant Bio-Derived Plasticizer Certification | ECHA phthalate restrictions redirect procurement toward compliant suppliers with premium positioning in European technical ceramics. |
| Direct Technical Service Team Deployment | Morbi and Thangadh hub penetration displaces traditional distributor intermediaries in underdeveloped Indian clusters. |
| Nano-Engineered Dispersant Scale-Up | Italian and Spanish tile manufacturer adoption rewards integrated polymer-pigment portfolios with premium pricing power. |
| Additive Manufacturing Bonding Agent Partnership | Aerospace and biomedical prototyping applications accelerate specialized acrylic and PVA-based system consumption. |
Study Parameters
A spread of perspectives from ceramic plant managers, procurement leads at tile manufacturers, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interview insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and SAMR enforcement disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation validated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling product type, application, end user, and technology segmentation dimensions. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements. Forecast inputs incorporated GB standard heavy metal limit enforcement timelines and ECHA restriction proposal progression.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by regional Chinese dispersant manufacturers would shift outcomes. Cross-checking against SAMR and MEE building materials enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Zeolite 4A Market
Ceramics
Industrial Ceramics Market
Ceramics
Graphite Crucibles Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Pottery Ceramics Market
Ceramics
Global Barium Carbonate Market
Ceramics
Lithium Silicate Market
Ceramics
Medical Ceramics Market
Ceramics
Advanced Ceramics Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Porous Ceramic Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Fly Ash and Ceramic Microsphere Market