
 Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market | 2026-2036
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market Foresight
Swiss contract manufacturers is decoupling from traditional small-batch constraints by building dedicated high-containment suites for cytotoxic compounds. Lonza leverages its Visp campus to anchor European supply of oncology HPAPIs. CordenPharma specializes in peptide-drug conjugate manufacturing at its Colorado and Switzerland sites. Dr. Reddy's Laboratories Ltd. competes on cost-engineered synthetic routes for generic oncology APIs.
High Potency Active Pharmaceutical Ingredients are pharmacologically active compounds with occupational exposure limits at or below ten micrograms per cubic meter, requiring isolated containment systems and dedicated air-handling infrastructure during synthesis and handling. These substances serve as the cytotoxic payloads in antibody-drug conjugates, hormone therapies, and targeted oncology treatments where minute doses deliver therapeutic effect. Small molecule HPAPIs dominate current revenue pools due to established synthetic routes and broader generic availability, while synthetic peptides represent the fastest-expanding category driven by conjugate therapy pipelines. Parenteral delivery technology commands premium positioning because sterile fill-finish requirements for oncology biologics add complexity and regulatory scrutiny that oral solid platforms avoid.
FDA, EMA, and ISPE collectively govern HPAPI facility design through containment performance target bands and occupational exposure band classification systems that dictate capital investment thresholds for new entrants. REACH and OSHA standards further constrain raw material sourcing and worker protection protocols, raising compliance costs for manufacturers without established containment infrastructure. Stakeholders must monitor evolving conjugate therapy pipeline failures, as these directly alter forecast HPAPI demand for specific payload classes and containment tiers.
Market Dynamics
Antibody-drug conjugate pipelines are concentrating demand for cytotoxic payloads among a handful of specialized contract manufacturers, tightening containment capacity and reshaping competitive positioning.
Growth Catalysts
- ISPE containment guidelines:FDA-ISPE guidance on potent compound handling has standardized occupational exposure band classifications, enabling cross-border facility qualification and accelerating sponsor outsourcing decisions.
- Peptide-drug conjugate manufacturing:Synthetic peptide HPAPIs are displacing traditional small-molecule payloads in oncology pipelines, expanding addressable chemistry for specialized manufacturers.
- India contract manufacturing clusters:Cost-engineered synthetic routes from Indian facilities are capturing generic oncology API volume, redirecting small-molecule production from Western sites.
Market Restraints
- Containment infrastructure costs:Dedicated high-containment suites require isolated air-handling systems and single-pass HVAC, raising capital thresholds beyond mid-scale entrants.
- Swiss supply concentration:European HPAPI capacity clusters disproportionately around Visp and Basel corridors, creating geographic vulnerability for continental sponsors.
- Containment performance validation:Occupational exposure limit testing at or below ten micrograms per cubic meter demands specialized analytical capabilities that limit batch release velocity.
Strategic Opportunities
- Colorado biotech corridor:Underdeveloped North American containment infrastructure outside Switzerland presents first-mover potential for dedicated cytotoxic suites serving US-based sponsors.
- Dual-use peptide synthesis:Convergence of solid-phase peptide synthesis with small-molecule conjugation chemistry opens hybrid manufacturing architectures.
- EMA accelerated assessment:Regulatory tailwinds for oncology biologics are compressing development timelines, pulling forward HPAPI demand from later-stage pipelines.
Industry Challenges
- Containment engineering talent:Cross-functional expertise spanning synthetic chemistry and industrial hygiene remains scarce, constraining facility expansion timelines.
- Legacy equipment retrofit:Isolator integration with existing reactor trains demands extensive validation, complicating brownfield containment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market |
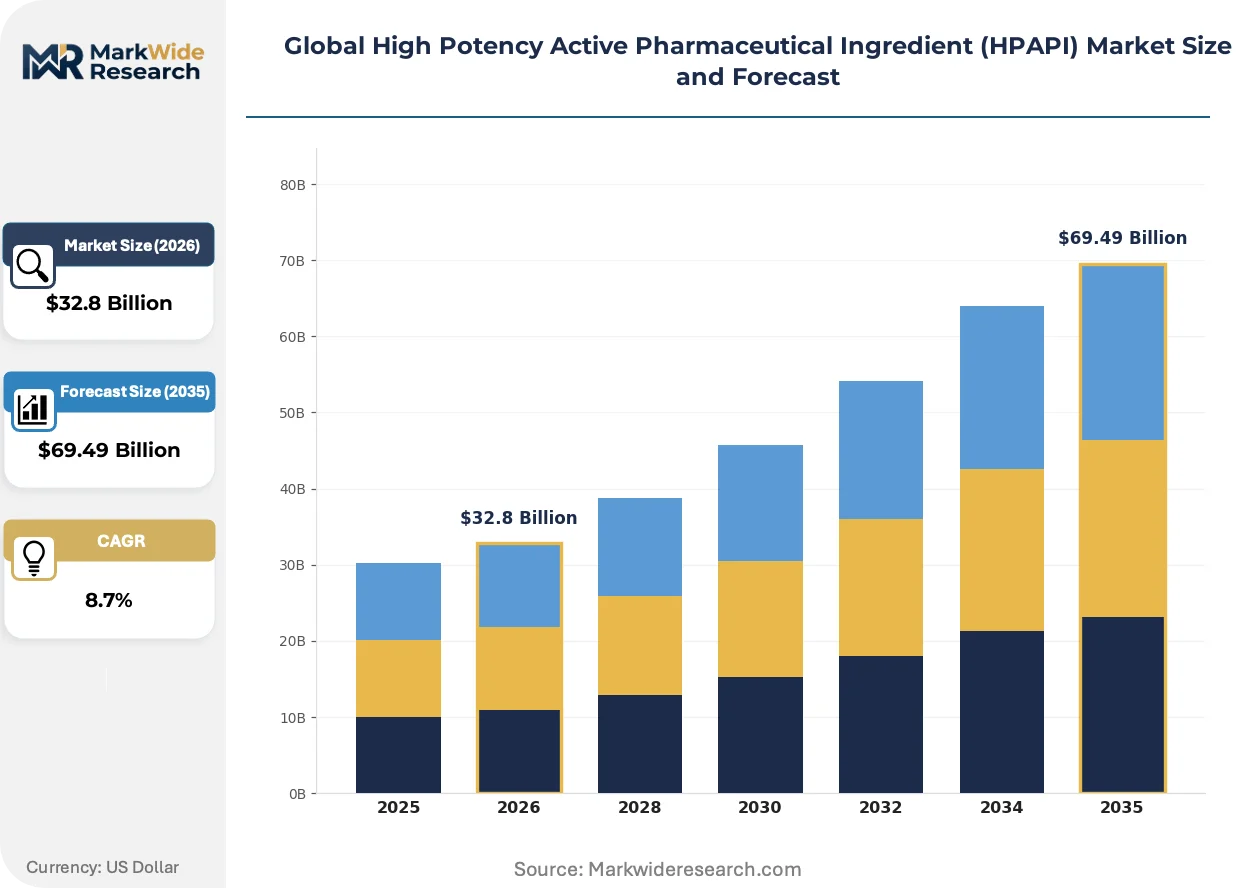
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $69.49 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule, Biologics, Synthetic Peptides, Radiopharmaceuticals, Oligonucleotides Therapy Area: Oncology, Immunology, Neurology, Cardiovascular, Endocrinology, Infectious Diseases End User: Pharmaceutical Manufacturers, Contract Development, Research Organizations, Biopharmaceutical Companies, Clinical Research Laboratories Delivery Technology: Oral Solid, Parenteral, Inhalation, Transdermal, Topical, Implantable |
| Companies Covered | Pfizer Inc., BASF SE, Lonza, CordenPharma, Teva Pharmaceutical Industries Ltd., Boehringer Ingelheim International GmbH, CARBOGEN AMCIS, Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market Shifts & Advancements
Process intensification and closed-system handling are compressing batch sizes while raising potency thresholds, forcing equipment vendors and manufacturers to co-develop next-generation containment architectures.
Continuous flow chemistry is automating hazardous reaction steps that previously required manual intervention in glove-box isolators. Contract manufacturers in Switzerland and the United States are retrofitting multi-purpose suites with skid-mounted flow reactors. This automation is compressing campaign changeover times and reducing operator exposure hours during cytotoxic intermediate synthesis.
REACH authorization requirements for hazardous intermediates are tightening raw material sourcing constraints for European HPAPI manufacturers. ECHA's candidate list expansion is forcing reformulation of synthetic routes and accelerating supplier qualification burdens. Synthetic peptide manufacturers are responding by backward integration into amino acid derivative production to secure supply chain continuity.
Oncology drug developers are unbundling API manufacturing from fill-finish services, creating discrete procurement categories for payload production versus conjugation chemistry. This disintermediation is fragmenting vendor relationships and compressing contract durations as sponsors seek specialized partners for each manufacturing step. The United States exhibits the most pronounced unbundling, with Boston and San Francisco biotech clusters driving demand for standalone HPAPI supply agreements.
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market Segmentation
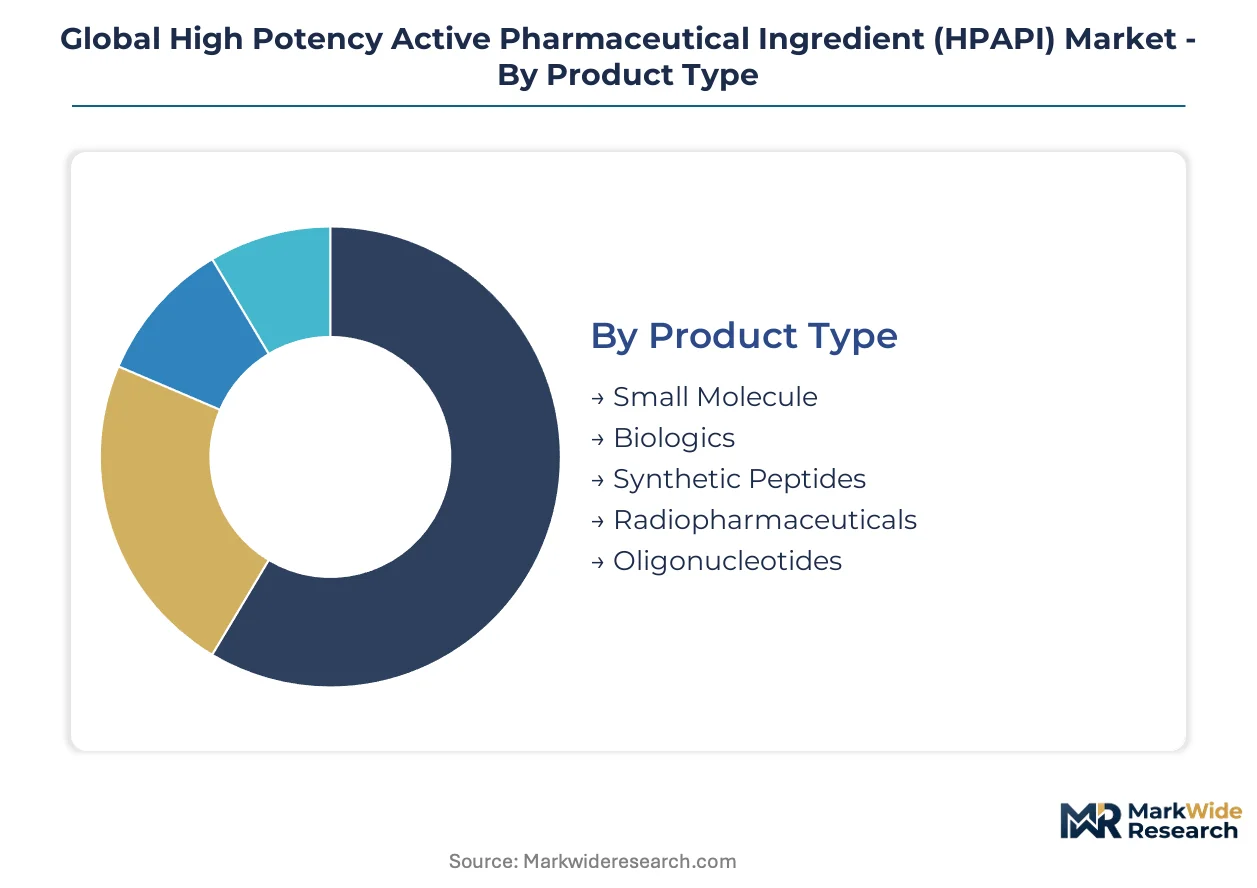
HPAPI segmentation reveals divergent capital requirements across chemistry platforms and delivery modalities. Containment infrastructure investments vary by an order of magnitude between synthetic routes, reshaping manufacturer specialization patterns.
Product Type:
Capital intensity peaks with radiopharmaceuticals and biologics, where shielded facilities and cold-chain infrastructure multiply upfront costs versus small-molecule suites.
- Small Molecule:Established synthetic routes for cytotoxic payloads dominate current manufacturing volumes. Demand concentrates in Indian contract manufacturing clusters serving generic oncology programs, constrained by REACH authorization requirements for hazardous intermediates.
- Biologics:Recombinant protein HPAPIs require single-use bioreactor trains and segregated viral clearance suites. United States biotech corridors in Boston and San Francisco anchor demand for these high-containment biologics.
- Synthetic Peptides:Solid-phase synthesis equipment and protected amino acid derivatives drive moderate capital thresholds.
- Radiopharmaceuticals:Cyclotron or reactor proximity and lead-shielded hot cells impose the steepest facility costs.
- Oligonucleotides:Phosphoramidite chemistry and automated synthesizers occupy a mid-range capital tier.
Most installed capacity flows through Small Molecule. Expansion is steepest in Synthetic Peptides.
Therapy Area:
Oncology commands premium pricing tiers, while immunology and neurology applications are diversifying payload demand across therapeutic modalities.
- Oncology:Cytotoxic payloads for antibody-drug conjugates represent the core revenue pool. FDA-ISPE containment guidelines standardize occupational exposure band classifications, accelerating sponsor outsourcing to qualified facilities in Switzerland and the United States.
- Immunology:Immunosuppressive HPAPIs for autoimmune indications require lower containment tiers but face tightening EMA accelerated assessment timelines.
- Neurology:Blood-brain barrier penetrating compounds command specialized formulation expertise.
- Cardiovascular:Hormone-derived anticoagulants occupy mature manufacturing segments.
- Endocrinology:Potent hormone therapies drive demand for dedicated suite isolation.
- Infectious Diseases:Antiviral HPAPIs are gaining pipeline visibility post-pandemic.
Oncology absorbs the majority of containment capital. Immunology is gaining share fastest among non-oncology categories.
End User:
Contract development organizations command the most sophisticated containment infrastructure, while pharmaceutical manufacturers balance captive capacity against outsourcing economics.
- Pharmaceutical Manufacturers:Large sponsors maintain hybrid models, retaining early-phase synthesis while outsourcing commercial-scale containment.
- Contract Development:CDMOs at Lonza's Visp campus and CordenPharma's Colorado site anchor specialized cytotoxic capacity. Swiss and United States corridors concentrate the most advanced high-containment suites.
- Research Organizations:Academic and government labs require lower-throughput isolator systems.
- Biopharmaceutical Companies:Venture-backed biotechs drive spot demand for clinical-scale HPAPI batches.
- Clinical Research Laboratories:Phase I facilities need rapid-turnaround analytical release capabilities.
Contract Development captures the highest containment investment per square meter. Biopharmaceutical Companies are expanding procurement most quickly.
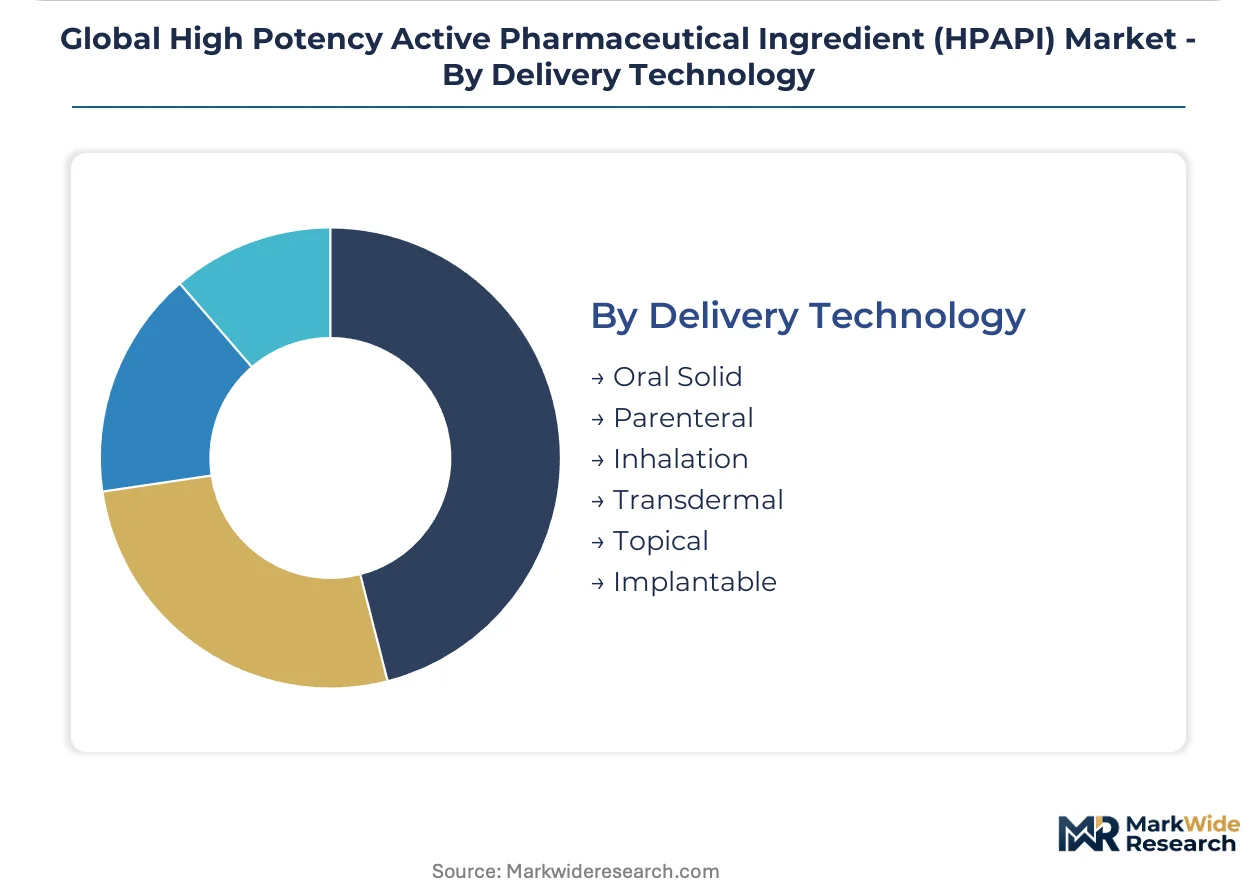
Delivery Technology:
Parenteral platforms impose sterile fill-finish requirements that oral solid dosage forms avoid, fragmenting vendor relationships between API synthesis and final drug product.
- Oral Solid:Tablet and capsule formulations for hormone therapies utilize standard containment without sterile barriers. Indian manufacturers compete aggressively on cost-engineered synthetic routes for these dosage forms.
- Parenteral:Injectable oncology biologics require isolator-integrated filling lines and terminal sterilization validation. United States unbundling trends separate payload manufacturing from conjugation chemistry, creating discrete procurement categories.
- Inhalation:Dry powder and nebulized HPAPIs demand specialized particle engineering.
- Transdermal:Patch-based delivery limits payload potency thresholds.
- Topical:Cream and ointment formulations occupy lower-containment tiers.
- Implantable:Long-acting depot formulations require exotic polymer conjugation expertise.
Parenteral infrastructure commands the steepest capital per dose capacity. Inhalation is climbing the fastest among emerging delivery platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland commands higher containment capital per square meter than India, yet both anchor distinct supply tiers for oncology HPAPIs. Facility investments in Visp and Basel corridors outpace construction timelines in Hyderabad and Ahmedabad clusters.
United States
FDA-ISPE containment guidelines drive sponsor outsourcing to qualified CDMOs in the Boston and San Francisco biotech corridors. The Inflation Reduction Act's oncology provisions accelerate clinical pipeline investments, pulling forward HPAPI demand. Colorado's emerging high-containment infrastructure serves antibody-drug conjugate developers seeking domestic cytotoxic payload supply.
Switzerland
Swissmedic oversight and REACH authorization requirements position the Visp and Basel regions as Europe's premier high-containment manufacturing zone. Lonza's campus anchors continental supply of oncology HPAPIs for conjugate therapies. Specialized suites for peptide-drug conjugate manufacturing concentrate investment around Lake Geneva.
India
CDSCO regulations and PLI scheme incentives for active pharmaceutical ingredients attract cost-engineered synthetic route development to Hyderabad and Ahmedabad clusters. Dr. Reddy's Laboratories Ltd. and Sun Pharmaceutical Industries Ltd. compete on generic oncology API volume. Containment infrastructure investments lag Western standards but capture small-molecule HPAPI share.
Germany
EMA accelerated assessment pathways for oncology biologics compress development timelines for sponsors in the Rhine-Main and Munich biotech zones. ECHA candidate list expansions force reformulation of synthetic routes using hazardous intermediates. Boehringer Ingelheim International GmbH maintains captive high-containment capacity for hormone-derived therapies.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined qualification of high-containment facilities serving London and Cambridge oncology clusters. CARBOGEN AMCIS operates specialized manufacturing infrastructure for cytotoxic payloads. Sterling weakness against the euro and dollar attracts contract manufacturing investment from US sponsors seeking European supply diversification.
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market Competitive Landscape
Swiss producers anchor the premium-containment tier; Indian specialists hold cost-engineered synthetic routes for generic volume. The market structures around three player categories: integrated pharmaceutical manufacturers with hybrid captive-outsourcing models, dedicated CDMOs with purpose-built high-containment suites, and emerging regional contractors competing on capital efficiency. Consolidation pressures concentrate among mid-scale Western facilities unable to fund isolator-integrated reactor upgrades. Dominant competitive moves include geographic expansion into underdeveloped North American containment corridors and portfolio diversification from small-molecule cytotoxics into synthetic peptide payloads.
Within the integrated pharmaceutical tier, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. exemplify hybrid manufacturing strategies balancing internal synthesis with selective outsourcing. Among pure-play contract manufacturers, Lonza and CordenPharma occupy positions defined by geographic clustering around Swiss and US biotech corridors. BAS SE anchors chemical supply relationships upstream of containment manufacturing. These archetypes reflect divergent capital deployment: pharmaceutical incumbents leverage existing infrastructure while CDMOs build dedicated suites for cytotoxic and peptide-drug conjugate production.
| Leading Market Players |
|---|
| Pfizer Inc. |
| BASF SE |
| Lonza |
| CordenPharma |
| Teva Pharmaceutical Industries Ltd. |
| Boehringer Ingelheim International GmbH |
| CARBOGEN AMCIS |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Continuous flow chemistry automation is compressing batch economics while concentrating supply among Swiss and United States facilities that can fund isolator-integrated reactor upgrades. This production-method transition simultaneously raises capital barriers for new entrants and tightens price competition among established contract manufacturers serving antibody-drug conjugate developers.
Pricing Analysis
Capacity additions in India are reshaping price floors for small-molecule cytotoxic payloads, forcing Western contract manufacturers toward premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects containment certification grade and volume scale. Pricing pressure stems from REACH authorization requirements for hazardous intermediates, which elevate compliance costs. Generic oncology API buyers exhibit highest price sensitivity; peptide-drug conjugate sponsors prioritize containment performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Swiss high-containment capacity clustered around Visp and Basel corridors. Geographic supply concentration spans Switzerland, India, and the United States, with each anchoring distinct tiers. Raw material dependencies draw from protected amino acid derivatives, phosphoramidite reagents, and cytotoxic intermediate precursors. Tariff exposure on Chinese-sourced starting materials presents structural risk. Distribution runs through qualified CDMO networks with isolator-validated facilities rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with sponsor procurement shifting toward facilities holding FDA-ISPE occupational exposure band certifications above cost-engineered alternatives.
For Market Incumbents: Anchor containment capacity in the Colorado biotech corridor to capture unbundled demand from Boston and San Francisco antibody-drug conjugate developers. Defend against Indian cost competition by investing in peptide-drug conjugate manufacturing capabilities that command premium positioning. Certification in EMA accelerated assessment pathways protects pricing power.
For New Entrants and Emerging Players: Begin with clinical-scale synthetic peptide production serving venture-backed biotechs in the United States, where containment talent scarcity limits incumbent expansion velocity. Target the inhalation delivery platform segment, which climbs fastest among emerging modalities and lacks established specialists. Go-to-market through standalone HPAPI supply agreements rather than bundled conjugation services.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Western facilities with legacy equipment requiring isolator retrofit. Long-term viability over the analysis window favors CDMOs with purpose-built high-containment suites in underdeveloped North American corridors. Watch conjugate therapy pipeline failures as the signal indicating demand shifts for specific payload classes.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Containment Suite Expansion | Isolator-integrated facilities in Colorado capture unbundled antibody-drug conjugate demand from US sponsors. |
| Peptide Payload Manufacturing Scale-Up | Solid-phase synthesis capacity addresses synthetic peptide displacement of traditional small-molecule cytotoxics. |
| EMA Accelerated Assessment Pathway | Regulatory qualification compresses development timelines and pulls forward HPAPI procurement decisions. |
| Backward Integration into Amino Acids | In-house production of protected derivatives secures supply chain continuity against ECHA candidate list expansions. |
| Continuous Flow Chemistry Retrofit | Skid-mounted reactor automation reduces operator exposure hours and accelerates campaign changeover. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at CDMOs, containment engineering specialists, and formulary directors informed primary intelligence. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and ISPE containment guideline documentation. Bottom-up facility capacity assessments and top-down pipeline molecule counts were triangulated against sponsor outsourcing survey data.
Projected market values and CAGRs emerged from segmented modeling across product type, therapy area, end user, and delivery technology dimensions, with additional stratification by regional regulatory cluster. The analytical framework incorporated antibody-drug conjugate pipeline progression rates and containment infrastructure investment cycles throughout the projection horizon. Cross-sectional analysis of contract manufacturer pricing and sponsor procurement patterns anchored volume-to-value conversions.
Several conditions sit outside the modeled scope, including unforeseen conjugate therapy clinical trial failures, abrupt REACH authorization withdrawals, and geopolitical disruptions to Swiss-Indian supply corridors. Forecasts reflect documented assumptions about pipeline progression and regulatory timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market