
 Automotive Additives Market | 2026-2036
Automotive Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Additives Market Analysis
Modular additive bundling is restructuring how OEMs and Tier-1 suppliers contract for fuel, oil, and polymer additive systems. BASF SE leverages its integrated formulation technology portfolio to anchor long-term supply relationships with major vehicle assemblers. Evonik Industries AG specializes in high-performance polymer additives that sustain margin pools in engine-compartment applications. The Dow Chemical Company competes through manufacturing scale in coating additives for surface protection programs.
Automotive additives comprise chemical compounds blended into fuels, lubricants, coatings, and polymers to enhance performance, durability, or regulatory compliance, typically formulated at concentrations between 50 ppm and 5% by weight depending on the base matrix and target function. These substances serve primarily to reduce friction, inhibit oxidation, disperse contaminants, or modify material properties under thermal and mechanical stress. Fuel additives and oil additives retain the largest volume positions, though polymer additives for lightweighting applications are expanding fastest as OEMs substitute metal components. Coating additives command premium positioning in corrosion resistance segments where formulation complexity and certification requirements protect margin structures.
EPA emission standards and the EU Green Deal's chemical sustainability frameworks are tightening allowable additive chemistries, particularly for sulfur, phosphorus, and heavy-metal content in lubricant and fuel applications. REACH registration requirements and California Air Resources Board protocols are forcing reformulation cycles that favor suppliers with advanced chemical synthesis and biodegradable technology capabilities. Stakeholders must monitor regulatory divergence between jurisdictions and align R&D pipelines with emerging substance restriction lists before compliance deadlines compress sourcing options.
Market Dynamics
Modular additive bundling contracts are restructuring how OEMs and Tier-1 suppliers source fuel, lubricant, and polymer additive systems, compressing traditional multi-vendor procurement into integrated formulation partnerships anchored by technical specification guarantees.
Growth Catalysts
- EU Green Deal chemical sustainability frameworks:REACH registration requirements and substance restriction timelines are accelerating reformulation investments across European manufacturing corridors.
- Lightweight polymer substitution:Metal-to-plastic conversion in engine compartments and structural components is expanding demand for heat-stabilized and reinforced polymer additive packages.
- Germany's automotive manufacturing corridor:Concentrated OEM and Tier-1 production in Baden-Württemberg and Bavaria sustains high-volume additive procurement with stringent technical specifications.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas derivative costs directly compress additive blending margins, particularly for complex ester and polyalphaolefin base stocks.
- Specialty chemical supply concentration:Advanced polymer additive intermediates concentrate among a limited supplier base in the Rhine-Ruhr chemical cluster, creating single-source exposure.
- Heavy-metal substitution limits:REACH Annex XVII restrictions on lead, cadmium, and chromium compounds in corrosion inhibitors force performance trade-offs in high-temperature coating applications.
Strategic Opportunities
- Eastern European manufacturing expansion:Czech Republic and Poland automotive assembly growth outpaces local additive formulation capacity, creating import substitution openings.
- Bio-based additive certification:EU Taxonomy alignment and OEM Scope 3 reduction targets favor biodegradable dispersant and antioxidant technologies with verified carbon intensity credentials.
- Digital formulation platforms:AI-driven additive package optimization is compressing development cycles from 18 months to 6 months for custom lubricant specifications.
Industry Challenges
- Cross-functional formulation expertise scarcity:Chemists with simultaneous competence in polymer science, tribology, and regulatory compliance command premium compensation and extended search timelines.
- REACH authorization timeline compression:Sunset date clustering for critical substances is forcing simultaneous reformulation of multiple additive lines without degradation of OEM-approved performance benchmarks.
- Legacy testing protocol obsolescence:Established ASTM and CEC engine test standards fail to predict additive performance in hybrid-electric powertrains with intermittent combustion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Additives Market |
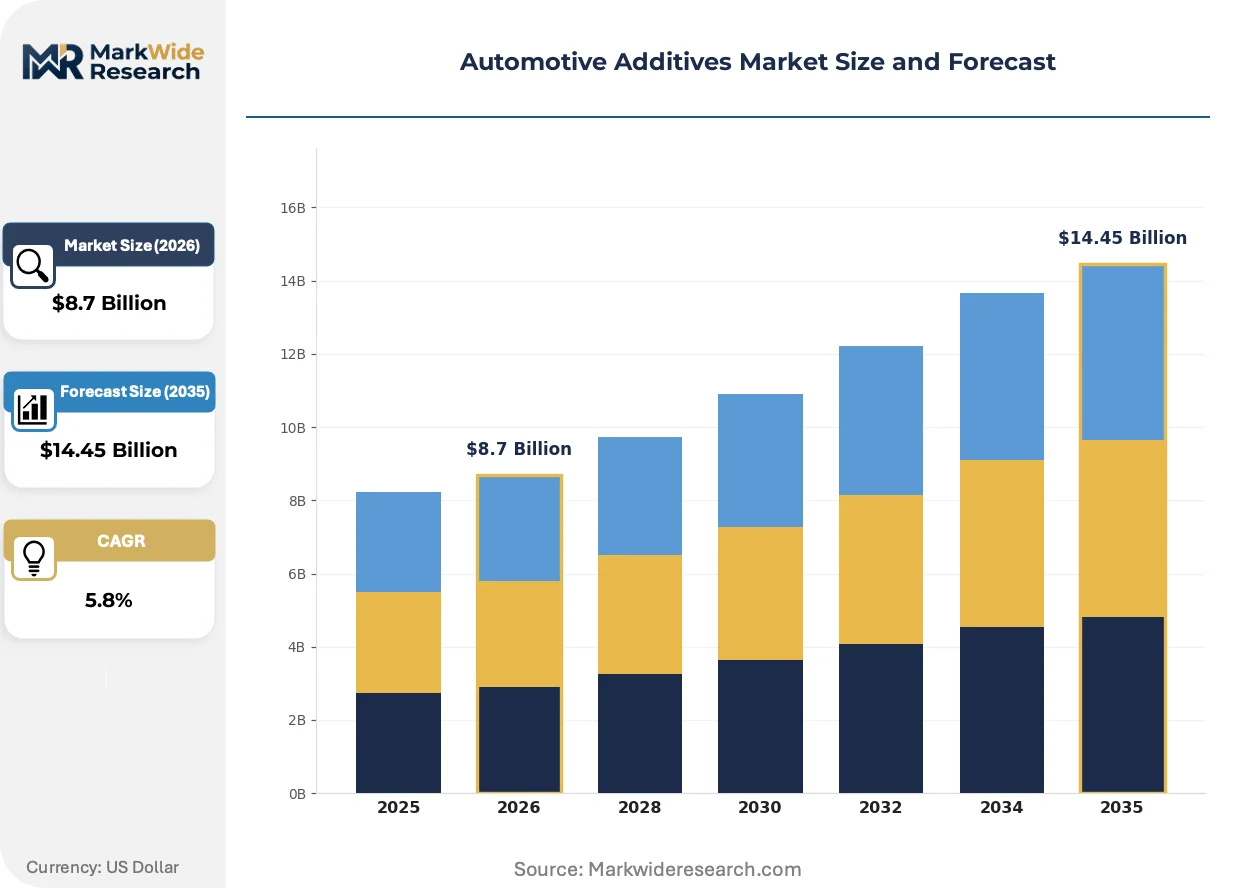
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Additives, Oil Additives, Coating Additives, Polymer Additives Application: Engine Performance, Emission Control, Surface Protection, Corrosion Resistance End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Formulation Technology, Nanotechnology, Biodegradable Technology, Chemical Synthesis |
| Companies Covered | BASF SE, Evonik Industries AG, The Dow Chemical Company, Clariant AG, Lanxess AG, Chevron Oronite, Afton Chemical, Lubrizol Corporation, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Additives Market Emerging Trajectories
Additive chemistry is converging with digital specification platforms and circular material mandates, compressing traditional development timelines while expanding the functional boundaries of fuel, lubricant, and polymer systems.
Nano-dispersed ceramic friction modifiers are integrating into high-performance engine oils to reduce boundary friction in start-stop hybrid powertrains. BMW and Mercedes-Benz powertrain divisions specify these packages for their PHEV lineups. The technology is integrating additive suppliers directly into vehicle-level fuel economy certification processes, bypassing traditional tiered component qualification.
REACH Annex XIV authorization deadlines are forcing systematic substitution of zinc dialkyldithiophosphate antiwear chemistry in passenger car motor oils. ECHA's 2025-2027 sunset date clustering affects an estimated 60% of current lubricant formulations. German additive houses are accelerating ashless phosphorus and ionic liquid alternatives through OEM validation protocols ahead of compliance deadlines.
Specification-led procurement is consolidating additive vendor relationships around integrated formulation technology portfolios rather than discrete product categories. Tier-1 suppliers now contract single-source additive system partners for fuel, oil, and polymer applications spanning a vehicle platform. This concentration is most visible in Stuttgart and Munich engineering centers where procurement teams eliminate redundant technical qualification costs.
Automotive Additives Market Segmentation
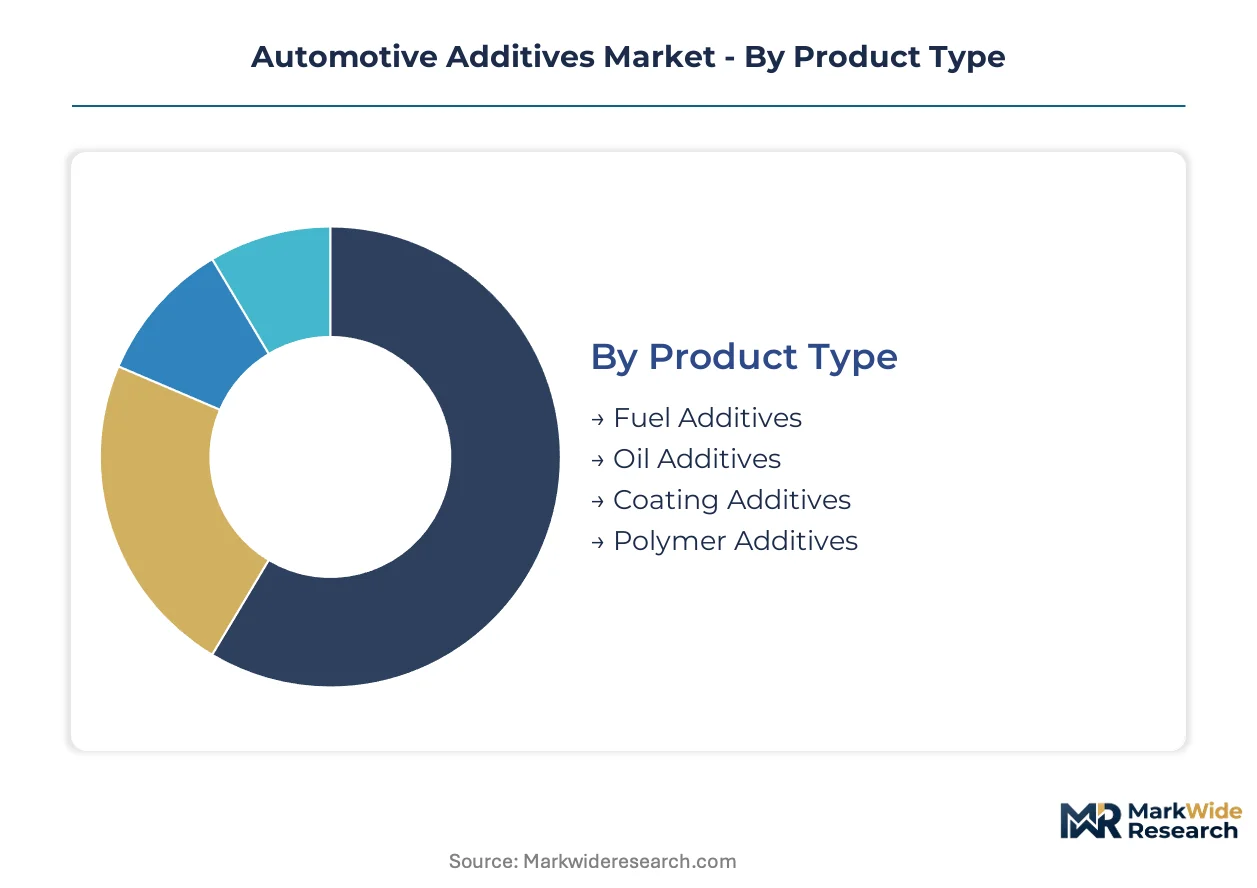
Automotive additive procurement splits sharply between standardized commodity formulations and custom-engineered packages tied to platform-specific performance guarantees. Segmentation clarity determines supplier positioning, R&D allocation, and contract negotiation leverage across fuel, lubricant, and polymer systems.
Product Type:
Standardization dominates high-volume fuel and oil additives, while polymer additives demand bespoke formulation partnerships with Tier-1 component manufacturers.
- Fuel Additives:Oxygenates, detergents, and cetane improvers blended at 50-5000 ppm to meet octane specifications and injector cleanliness standards. Demand clusters in Germany's refining corridor around Bayern Oil and Shell Rheinland, driven by EN 228 gasoline quality mandates and fleet-average CO2 regulations.
- Oil Additives:Viscosity modifiers, dispersants, and antiwear chemistries constitute the largest volume category, with zinc dialkyldithiophosphate (ZDDP) and polymeric pour point depressants forming core specifications. Stuttgart-based powertrain engineering centers specify these packages for 10,000-30,000 km drain intervals in downsized turbocharged engines.
- Coating Additives:Rheology modifiers and UV stabilizers for automotive OEM paint lines.
- Polymer Additives:Heat stabilizers, impact modifiers, and glass fiber sizings for metal-to-plastic substitution in under-hood components.
Most installed capacity flows through Oil Additives. Expansion is steepest in Polymer Additives.
Application:
Performance requirements diverge between combustion-cycle optimization and long-term material integrity under thermal and mechanical stress.
- Engine Performance:Friction reduction and deposit control additives that directly influence fuel economy certification values. BMW and Mercedes-Benz powertrain divisions in Munich and Stuttgart specify nano-dispersed ceramic friction modifiers for PHEV start-stop cycles, with additive suppliers integrated into vehicle-level homologation processes.
- Emission Control:Aftertreatment-compatible low-SAPS (sulfated ash, phosphorus, sulfur) lubricant additives that protect gasoline particulate filters and selective catalytic reduction systems. EU Stage 5 emission standards and EPA Tier 3 protocols are accelerating reformulation investments across European and North American manufacturing corridors.
- Surface Protection:Scratch-resistant and self-healing coating additives for exterior automotive finishes.
- Corrosion Resistance:Inhibitor packages for underbody coatings and cooling system protection.
Engine Performance commands the highest formulation complexity premiums. Emission Control is climbing the fastest as aftertreatment systems proliferate across powertrain architectures.
End User:
Contract structures range from multi-year platform agreements with vehicle assemblers to spot procurement by independent aftermarket distributors.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz negotiate integrated additive system contracts spanning fuel, lubricant, and polymer specifications for entire vehicle platforms. These relationships anchor volume commitments and co-development programs for next-generation powertrains.
- Tier-1 Suppliers:Bosch, Continental, and ZF Friedrichshafen procure custom polymer additive packages for lightweight structural components and thermal management modules. Procurement teams in Baden-Württemberg and Bavaria are consolidating vendor relationships to eliminate redundant technical qualification costs.
- Aftermarket Providers:Independent lubricant blenders and fuel retailers purchasing standardized additive packages.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations with limited in-house formulation capability.
OEMs concentrate the highest-value formulation partnerships. Tier-1 Suppliers are gaining share fastest as modular component sourcing expands.
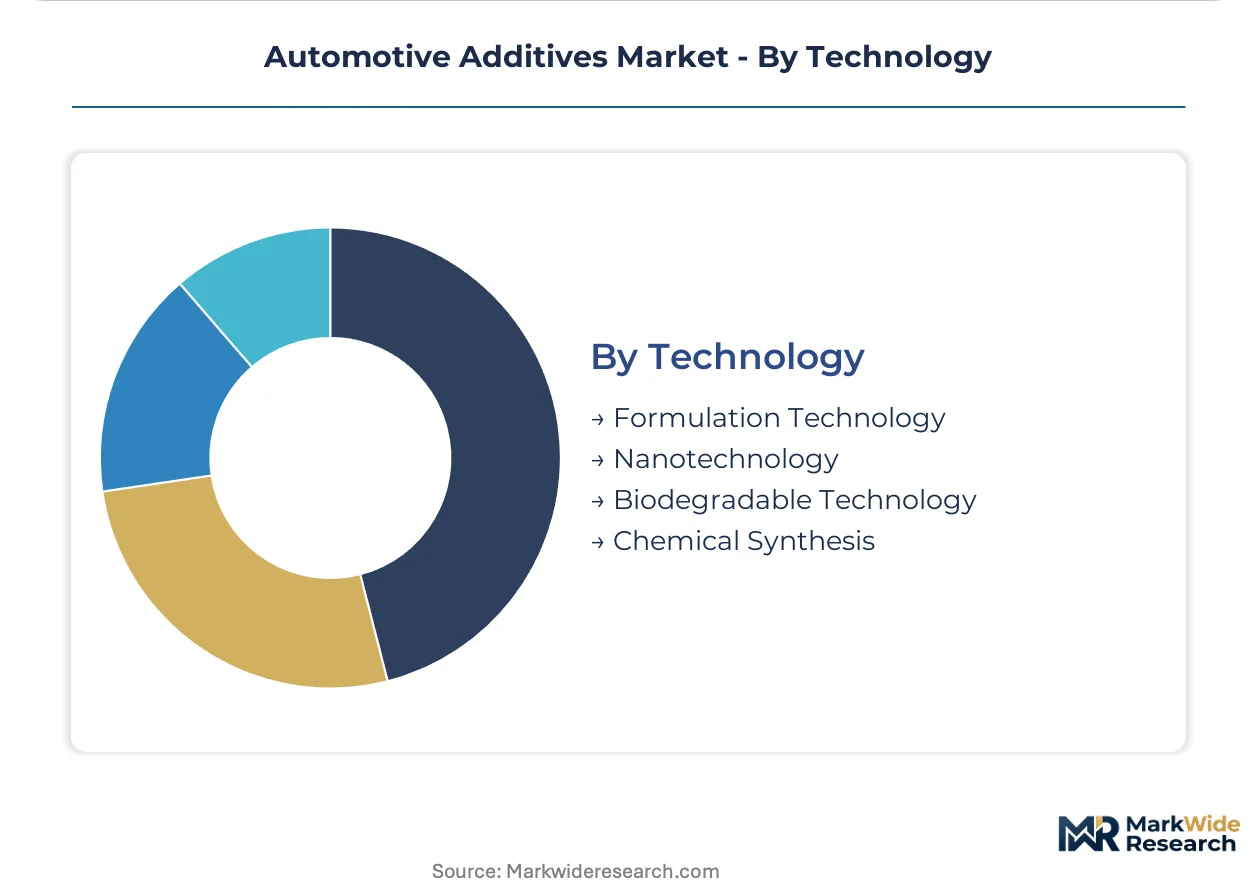
Technology:
Development timelines compress from traditional 18-month cycles to 6-month sprints as digital platforms and bio-based chemistries reshape competitive capability requirements.
- Formulation Technology:Integrated additive package design combining multiple functional chemistries into single-tank blending systems. BASF SE and Evonik Industries AG leverage proprietary formulation databases to anchor long-term supply relationships with specifications guaranteed across temperature and shear regimes.
- Nanotechnology:Nano-dispersed ceramics, graphene derivatives, and sub-100nm particle systems for boundary lubrication and thermal conductivity enhancement. BMW and Mercedes-Benz PHEV lineups specify these technologies for fuel economy certification, bypassing traditional tiered component qualification.
- Biodegradable Technology:Plant-derived dispersants and ester base stocks aligned with EU Taxonomy criteria and OEM Scope 3 reduction targets.
- Chemical Synthesis:Conventional petrochemical routes for high-volume antioxidant and detergent production.
Chemical Synthesis retains the largest installed production base. Nanotechnology is expanding most quickly as hybrid-electric powertrains demand precision friction management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr chemical corridor birthed modern automotive additive formulation in the early twentieth century, establishing the technical standards and supply chain architecture that now structure procurement across major vehicle manufacturing zones worldwide.
Germany
Stuttgart and Munich engineering centers specify integrated additive packages for entire vehicle platforms, compressing multi-vendor procurement into single-source relationships. REACH Annex XVII substance restrictions and the EU Green Deal's chemical sustainability mandates accelerate reformulation investments across Baden-Württemberg and Bavaria. The Rhine-Ruhr cluster concentrates advanced polymer additive intermediates, though this concentration creates single-source exposure for Tier-1 suppliers.
United States
EPA Tier 3 emission standards and California Air Resources Board protocols drive demand for low-SAPS lubricant additives protecting gasoline particulate filters. The Gulf Coast petrochemical corridor supplies base stock derivatives, though feedstock volatility compresses blending margins. Detroit-area powertrain engineering centers integrate additive suppliers directly into fuel economy certification processes for hybrid-electric architectures.
China
MIIT fuel consumption regulations and dual carbon goals reshape additive specifications for the world's largest vehicle production base. Yangtze River Delta manufacturing clusters absorb growing volumes of polymer additives for lightweight structural substitution. Domestic additive formulation capacity expands fastest in Shandong Peninsula chemical zones, though import dependency persists for high-performance friction modifier technologies.
Japan
METI energy efficiency standards and JIS lubricant specifications anchor technical requirements for precision-engineered additive packages. Kansai and Chubu industrial corridors concentrate OEM co-development programs for next-generation powertrain chemistries. Japanese additive houses accelerate ashless antiwear alternatives through validation protocols ahead of regulatory sunset deadlines affecting zinc-based chemistry.
South Korea
Seoul Capital Area vehicle assemblers negotiate platform-spanning additive system contracts mirroring German procurement consolidation patterns. MFDS chemical registration requirements and OEM Scope 3 reduction targets favor bio-based dispersant technologies with verified carbon intensity credentials. Busan-Ulsan chemical complexes expand ester base stock production for high-performance lubricant applications.
Automotive Additives Market Vendor Landscape
The competitive structure tilts toward integrated formulation technology providers capable of anchoring multi-year platform agreements. Three archetypes dominate: diversified chemical conglomerates with cross-portfolio bundling capability, specialty additive houses with deep tribology expertise, and regional blenders competing on spot procurement flexibility. Consolidation pressures intensify as OEMs eliminate redundant technical qualification costs, while backward integration into petrochemical feedstocks separates margin leaders from price-takers.
Among German-based diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated formulation archetype, anchoring long-term supply relationships through proprietary specification databases. The Dow Chemical Company represents scale-driven manufacturing capability in coating additives. Specialty lubricant additive developers including Lubrizol Corporation and Afton Chemical occupy positions defined by tribology expertise and OEM validation depth rather than feedstock integration.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| The Dow Chemical Company |
| Clariant AG |
| Lanxess AG |
| Chevron Oronite |
| Afton Chemical |
| Lubrizol Corporation |
| TotalEnergies |
| Others |
Supply Flow & Price Mechanics
Nano-dispersed ceramic friction modifier integration into PHEV specifications simultaneously compresses additive development economics and concentrates procurement leverage among integrated formulation technology providers. REACH Annex XIV sunset date clustering for zinc dialkyldithiophosphate chemistry forces simultaneous multi-line reformulation, amplifying cost pass-through negotiations between Tier-1 suppliers and additive houses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated custom packages from Tier-1 specification blends and aftermarket commodity formulations. Price differentiation hinges on REACH registration depth and platform-specific homologation status. Cost compression in standard lubricant tiers is intensifying because petrochemical feedstock volatility erodes blending margins. Aftermarket distributors exhibit highest price sensitivity, while OEM powertrain engineering centers accept premium positioning for integrated system guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through platform-spanning additive system contracts, while independent blenders source through chemical distributor networks. Germany, China, and the United States concentrate advanced polymer additive intermediates and friction modifier synthesis capacity. Supply chains draw from crude oil derivatives, natural gas-based olefins, and specialty ester base stocks. Single-source vulnerability persists in Rhine-Ruhr chemical cluster concentration for heat-stabilized polymer packages. Distribution runs through integrated formulation partners for OEMs and regional chemical distributors for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
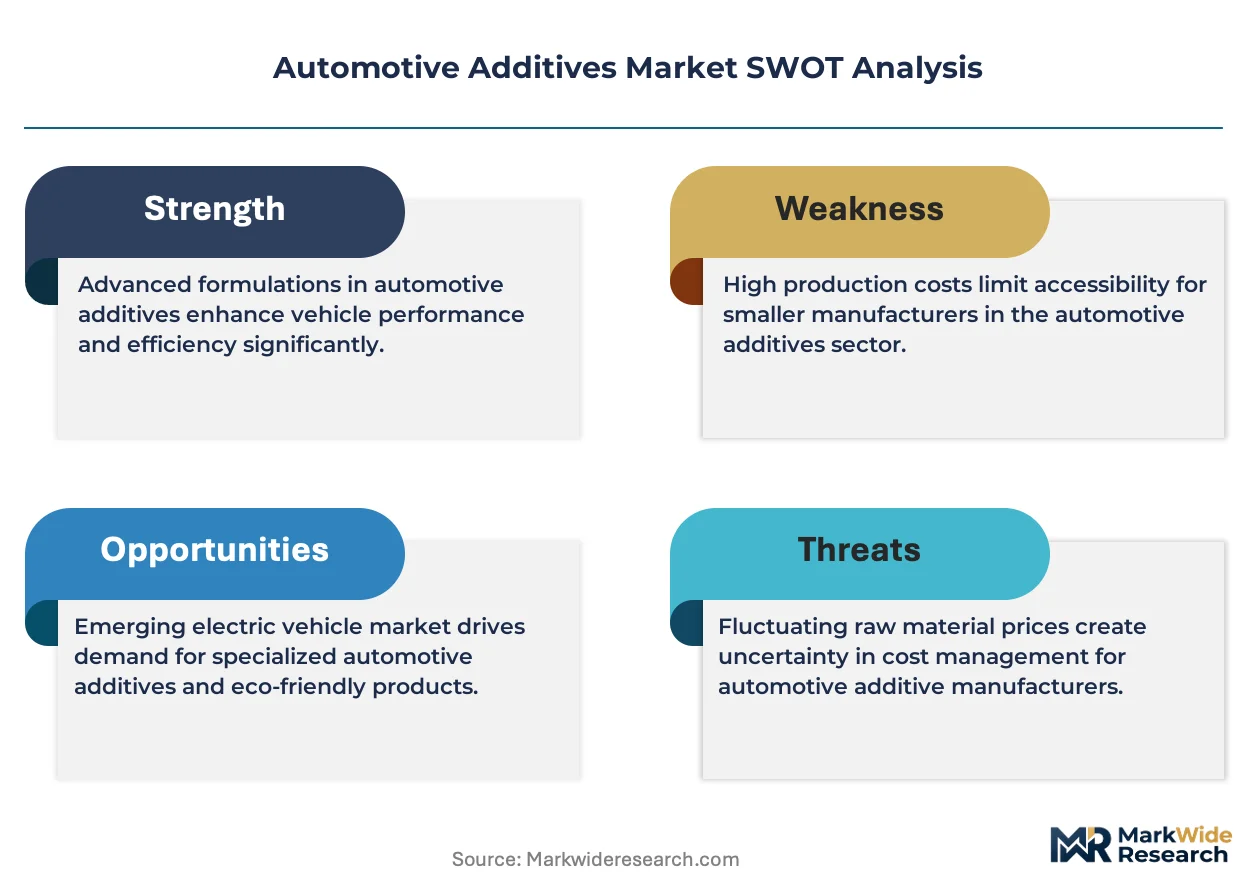
Margin expansion trajectories favor suppliers with backward integration into petrochemical feedstocks and bio-based additive certification capabilities. Reformulation cycle compression under REACH timelines rewards R&D scale and regulatory affairs depth.
For Market Incumbents: Extend formulation technology platform coverage into biodegradable dispersant categories before EU Taxonomy alignment becomes mandatory for OEM Scope 3 compliance. Deepen captive supply of polyalphaolefin base stocks to defend against Gulf Coast feedstock volatility. Anchor long-term platform agreements with Stuttgart and Munich engineering centers through integrated fuel-oil-polymer system guarantees. For New Entrants and Emerging Players: Digital formulation platforms offering AI-driven additive package optimization present the most penetrable entry vector, compressing 18-month development cycles to 6-month sprints for custom lubricant specifications. Target Czech Republic and Poland automotive assembly corridors where local additive formulation capacity lags vehicle production growth. Pursue import substitution positioning through bio-based certification partnerships with Eastern European OEM assembly operations. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders lacking REACH registration depth but holding established aftermarket distribution relationships. Five-to-ten year viability depends on successful navigation of zinc dialkyldithiophosphate substitution timelines and nanotechnology validation depth. Watch for inflection signals in ashless phosphorus antiwear chemistry adoption rates across German OEM validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Base Stocks | Captive supply of polyalphaolefin derivatives insulates blending margins from Gulf Coast petrochemical volatility. |
| REACH Annex XIV Pre-Registration Investment | Early authorization pathways for ashless antiwear alternatives secure OEM validation timelines ahead of sunset deadlines. |
| Bio-Based Additive Certification Program | EU Taxonomy alignment opens platform-spanning contracts with OEMs targeting Scope 3 reduction commitments. |
| Digital Formulation Platform Deployment | AI-driven package optimization compresses development cycles for custom PHEV friction modifier specifications. |
| Eastern European Distribution Expansion | Czech and Poland automotive assembly growth outpaces local formulation capacity, creating import substitution openings. |
Methodological Framework
Multiple input streams — primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distribution heads; secondary validation through SEC filings, customs trade data, and vehicle production databases; and patent landscape analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification evolution, contract structuring, and reformulation timeline pressures across Baden-Württemberg, Bavaria, and Yangtze River Delta manufacturing clusters.
Historical volume trajectories were cross-referenced against panel input from additive house technical directors and regulatory affairs specialists. Segmentation dimensions modeled include product type, application function, end-user contract structure, and technology platform across the analysis window. CAGRs were derived from production volume build-ups by vehicle platform and content-per-vehicle assumptions for polymer lightweighting penetration. Forecast inputs incorporated REACH authorization timeline clustering and MIIT fuel consumption regulation stringency.
Feedstock price volatility, regulatory sunset date delays, and hybrid-electric powertrain adoption speed are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding metal-to-plastic substitution rates and OEM co-development program participation. Periodic stress-testing of base assumptions against ECHA substance restriction announcements and OEM platform engineering priorities is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Anti-Fog Additives Market
Additives
Global Asphalt Additives Market
Additives
Tragacanth Market
Additives
Ascorbyl Stearate Market
Additives
Octane Improver Fuel Additives Market
Additives
Europe UV Stabilizers Market
Additives
Caprylyl Glycol Market
Additives
Green Polymer Additive Market
Additives
Cetane Improver Additives Market
Additives
Alginic Acid Market
Additives
Caustic Sulphite Caramel Market
Additives
Global Synthetic Tackifier Market
Additives
Europe Choline Chloride Market
Additives
Inorganic Rheology Modifiers Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Feed Additive Nosiheptide Premix Market