
 Advanced Structural Ceramics Market | 2026-2036
Advanced Structural Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Structural Ceramics Market Analysis
Silicon carbide is hardening its position as the preferred replacement for nickel superalloys in gas turbine hot-section components, cutting component weight while extending thermal tolerance. KYOCERA Corporation leverages decades of fine-ceramic expertise to anchor its position in semiconductor processing equipment. CoorsTek, Inc. sustains manufacturing scale across North American and Asian facilities, competing on volume for industrial wear parts. CeramTec GmbH specializes in medical and automotive-grade alumina, differentiating through ISO 13485 certification and tight dimensional tolerances.
Advanced structural ceramics are inorganic, non-metallic materials engineered for exceptional hardness, thermal stability, and corrosion resistance, typically formed through sintering of oxide or non-oxide powders at temperatures exceeding 1600°C to produce components that maintain structural integrity under mechanical stress and extreme heat. Alumina dominates current volume owing to its cost-performance balance in wear parts and electrical insulators, while silicon carbide captures the fastest growth trajectory as aerospace and power electronics buyers prioritize thermal conductivity and low density. Titanium diboride occupies a narrower but high-margin niche in armor and cutting tool applications where extreme hardness justifies premium positioning.
The EPA enforces emissions thresholds that push automotive and aerospace OEMs toward lighter, hotter-running ceramic components, while REACH and the EU Green Deal restrict hazardous substances in ceramic precursor supply chains, compelling reformulation of binders and sintering aids. Japan's METI promotes domestic ceramic matrix composite development through industrial technology grants, reinforcing national supply security for defense and space applications. Stakeholders must monitor evolving F-Gas Regulation classifications in Europe, as fluorinated processing agents face phase-down schedules that could disrupt chemical vapor infiltration supply chains.
Market Dynamics
Ceramic matrix composites are overtaking nickel superalloys in aerospace turbine hot-sections, compressing component weight while extending thermal tolerance beyond 1200°C. This material substitution is restructuring supply relationships between engine OEMs and precision ceramics suppliers.
Growth Catalysts
- EPA emissions thresholds:Automotive and aerospace OEMs in the United States face tightening NOx and CO2 limits that mandate lighter, hotter-running engine architectures. Ceramic components enable these thermal and efficiency gains.
- Silicon carbide infiltration:Chemical vapor infiltration processes refined for semiconductor processing equipment now transfer to turbine blade production, cutting manufacturing cycle times for ceramic matrix composites.
- Germany precision clusters:Stuttgart and Dresden ceramics corridors concentrate specialized alumina and silicon carbide capacity within two-hour logistics radius of BMW, Siemens, and Bosch procurement centers.
Market Restraints
- Energy cost volatility:Sintering furnaces operating above 1600°C consume substantial natural gas and electricity; European manufacturers face input cost swings tied to TTF natural gas benchmarks.
- Fluorinated precursor concentration:Chemical vapor infiltration relies on specialty fluorinated processing agents subject to EU F-Gas Regulation phase-down schedules, concentrating supply risk with limited qualified chemical suppliers.
- Silicon carbide brittleness:Fracture toughness limitations below 10 MPa·m½ restrict silicon carbide to non-rotating static components in turbine architectures, capping addressable component value per engine.
Strategic Opportunities
- India industrialization:BIS standards adoption for advanced ceramics in power generation and steel processing creates certified demand channels for ISO-qualified foreign suppliers establishing local technical service presence.
- Electric vehicle thermal management:Silicon carbide power module substrates in 800V architectures require matched ceramic heat spreaders, opening parallel demand streams beyond traditional aerospace and industrial markets.
- METI composite grants:Japan's Ministry of Economy, Trade and Industry funds domestic ceramic matrix composite development for defense and space applications, incentivizing technology transfer partnerships with established European and North American producers.
Industry Challenges
- High-temperature process engineering talent:Sintering furnace operation and atmosphere control require specialized metallurgical and ceramics engineering expertise that universities in Germany and Japan produce at insufficient rates for expanding capacity.
- ISO 13485 certification timelines:Medical-grade alumina for implantable devices requires 18-24 month quality system validation cycles that delay revenue recognition for new product qualifications with orthopedic OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Structural Ceramics Market |
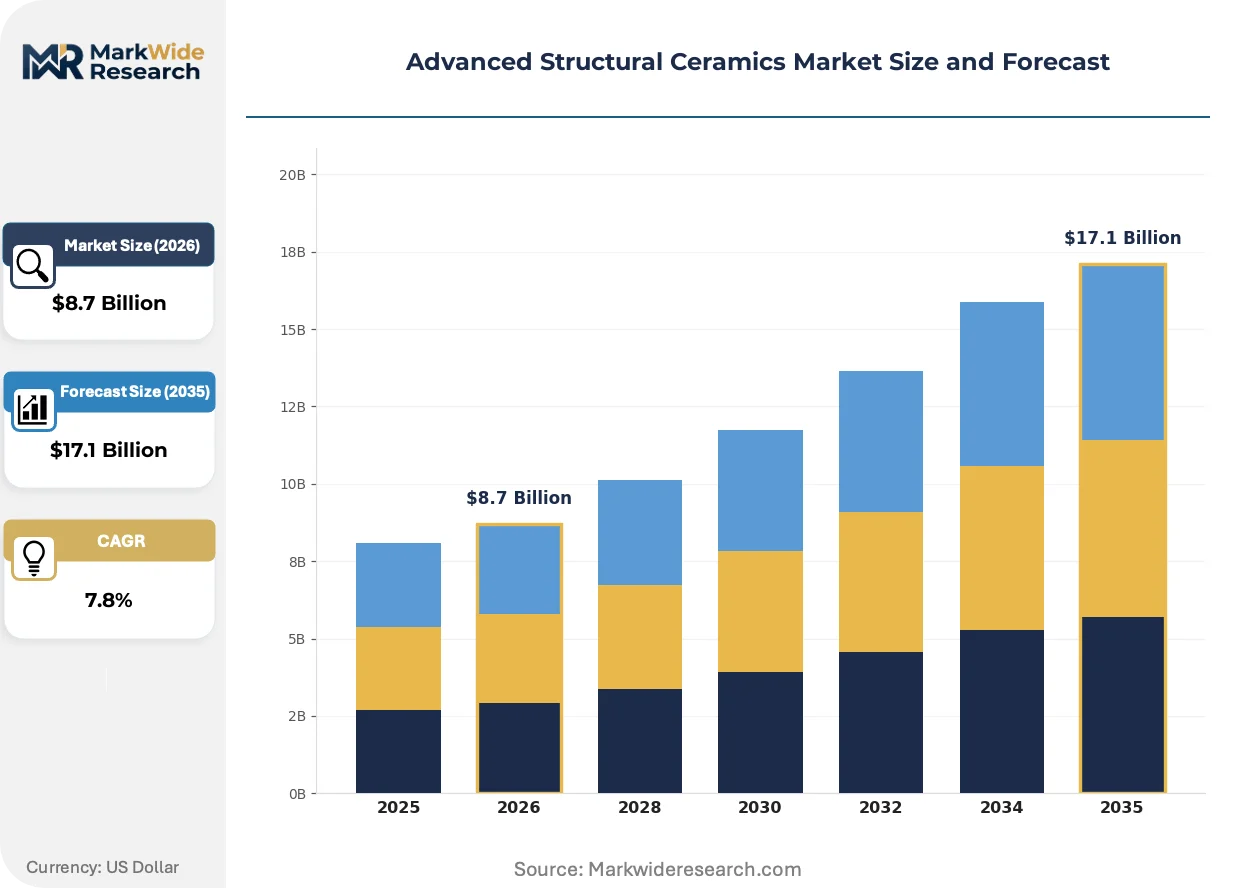
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Alumina, Zirconia, Titanium Diboride End User: Aerospace, Defense, Electronics, Automotive Form: Pipes, Plates, Rods, Components Application: Cutting Tools, Wear Parts, Insulators, Structural Components |
| Companies Covered | Saint-Gobain, 3M, KYOCERA Corporation, NGK Insulators, Murata Manufacturing Co., Ltd., CeramTec GmbH, Morgan Advanced Materials, AGC Ceramics Co., Ltd., CoorsTek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Structural Ceramics Market Emerging Trajectories
Process automation and digital twin modeling are compressing development cycles for ceramic matrix composite components. These innovations reduce empirical trial batches and accelerate qualification with aerospace primes.
Silicon carbide fiber-reinforced ceramic matrix composites are overtaking oxide-oxide systems in turbine hot-section applications. GE Aviation and Rolls-Royce procurement specifications now prioritize silicon carbide-silicon carbide architectures for combustor liners and turbine shrouds. This specification shift is compressing the addressable market for alumina-based alternatives in aerospace.
REACH authorization requirements for boron compounds and certain sintering aids are forcing reformulation of ceramic precursor chemistries. ECHA's 2023-2025 substance evaluation roadmap targets boric acid derivatives used in oxide ceramic densification. German suppliers in the Stuttgart cluster are responding fastest, securing early authorization dossiers to maintain medical and automotive supply continuity.
Buyer consolidation among tier-one aerospace contractors is concentrating procurement leverage with Safran, MTU Aero Engines, and GE Aviation. These primes now mandate long-term supply agreements with technical service commitments, displacing spot-market transactions. France and Germany host the most visible contract restructuring, with 7-10 year ceramic matrix composite supply agreements replacing annual volume commitments.
Advanced Structural Ceramics Market Segmentation
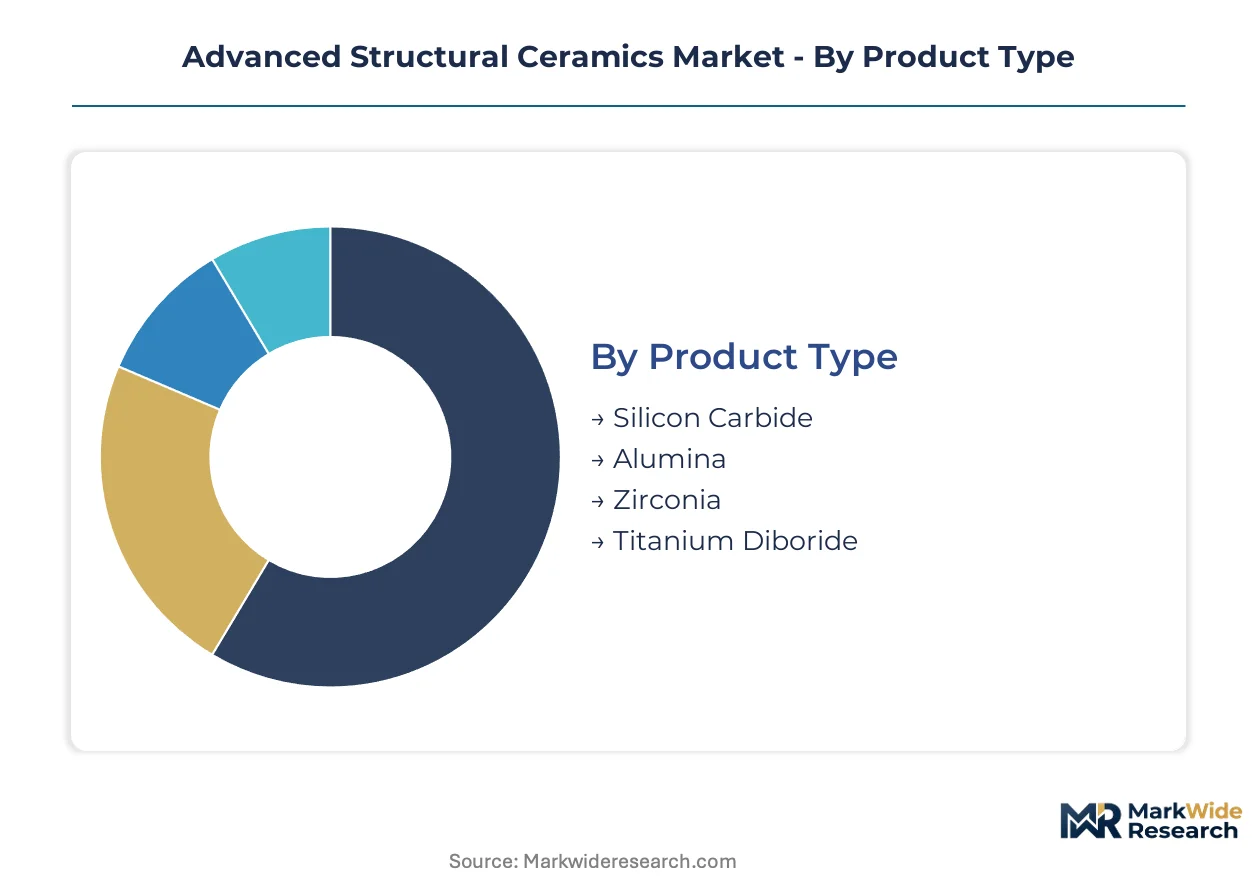
Segmentation in advanced structural ceramics separates volume-driven commodity grades from specification-critical aerospace and medical tiers. Buyers in each category face distinct qualification timelines, thermal performance thresholds, and supply chain concentration risks that reshape procurement strategies.
Product Type:
Cost-performance positioning separates buyers selecting between established oxide ceramics and emerging non-oxide alternatives for extreme thermal environments.
- Silicon Carbide:Non-oxide ceramic formed through carbothermal reduction and sintering, delivering thermal conductivity above 120 W/m·K and service temperatures exceeding 1600°C. Demand concentrates in aerospace turbine shrouds and 800V electric vehicle power modules, where GE Aviation and semiconductor equipment OEMs prioritize low-density thermal management. Sintering furnace energy intensity and fluorinated precursor supply constraints limit European capacity expansion.
- Alumina:Alpha-phase aluminum oxide processed from bauxite-derived feedstock, offering dielectric strength above 15 kV/mm and mature ISO 13485 certification pathways for implantable devices. Stuttgart and Dresden precision clusters supply BMW, Siemens, and Bosch with medical-grade and automotive sensor housings. REACH authorization timelines for boron-based sintering aids compress formulation flexibility for German suppliers.
- Zirconia:Yttria-stabilized tetragonal polycrystals deliver fracture toughness above 10 MPa·m½ for dental implants and industrial cutting inserts.
- Titanium Diboride:Ultra-hard boride ceramic exceeding 25 GPa hardness serves armor plate and premium cutting tool niches where extreme wear resistance justifies premium pricing.
Volume sits with alumina; growth tilts toward silicon carbide.
End User:
Application maturity and qualification stringency divide buyers between long-cycle aerospace primes and fast-qualification industrial OEMs.
- Aerospace:Turbine hot-section components demand ceramic matrix composites with thermal tolerance beyond 1200°C and FAA-certified flame resistance. Rolls-Royce and Safran procurement specifications now mandate silicon carbide-silicon carbide architectures, restructuring supply relationships toward 7-10 year technical service agreements. METI grants in Japan and EPA emissions thresholds in the United States accelerate material substitution away from nickel superalloys.
- Electronics:Semiconductor processing equipment and power module substrates require matched thermal expansion coefficients and plasma resistance. KYOCERA Corporation anchors this segment through decades of fine-ceramic expertise in etch chamber components and wafer handling systems.
- Defense:Armor and hypersonic leading edge applications prioritize titanium diboride and boron carbide for ballistic performance.
- Automotive:Sensor housings, spark plug insulators, and catalytic converter substrates drive high-volume alumina consumption with tight cost tolerances.
Aerospace commands qualification premiums; electronics scales manufacturing transfer.
Form:
Processing complexity and near-net-shape capability differentiate buyers seeking finished components versus semi-finished feedstock for in-house machining.
- Components:Net-shape or near-net-shape parts produced through injection molding, isostatic pressing, and precision grinding eliminate secondary machining for turbine blades, seals, and medical implants. CoorsTek sustains manufacturing scale across North American and Asian facilities for industrial wear parts requiring tight dimensional tolerances.
- Plates:Flat stock for armor systems, heat spreaders, and substrate applications permits buyer-side waterjet or diamond grinding customization.
- Rods:Extruded and sintered cylindrical stock serves cutting tool blanks and high-temperature thermocouple protection tubes.
- Pipes:Isostatically pressed and sintered tubular forms handle molten metal transfer and chemical processing environments.
Components capture value-added margins; plates dominate armor procurement.
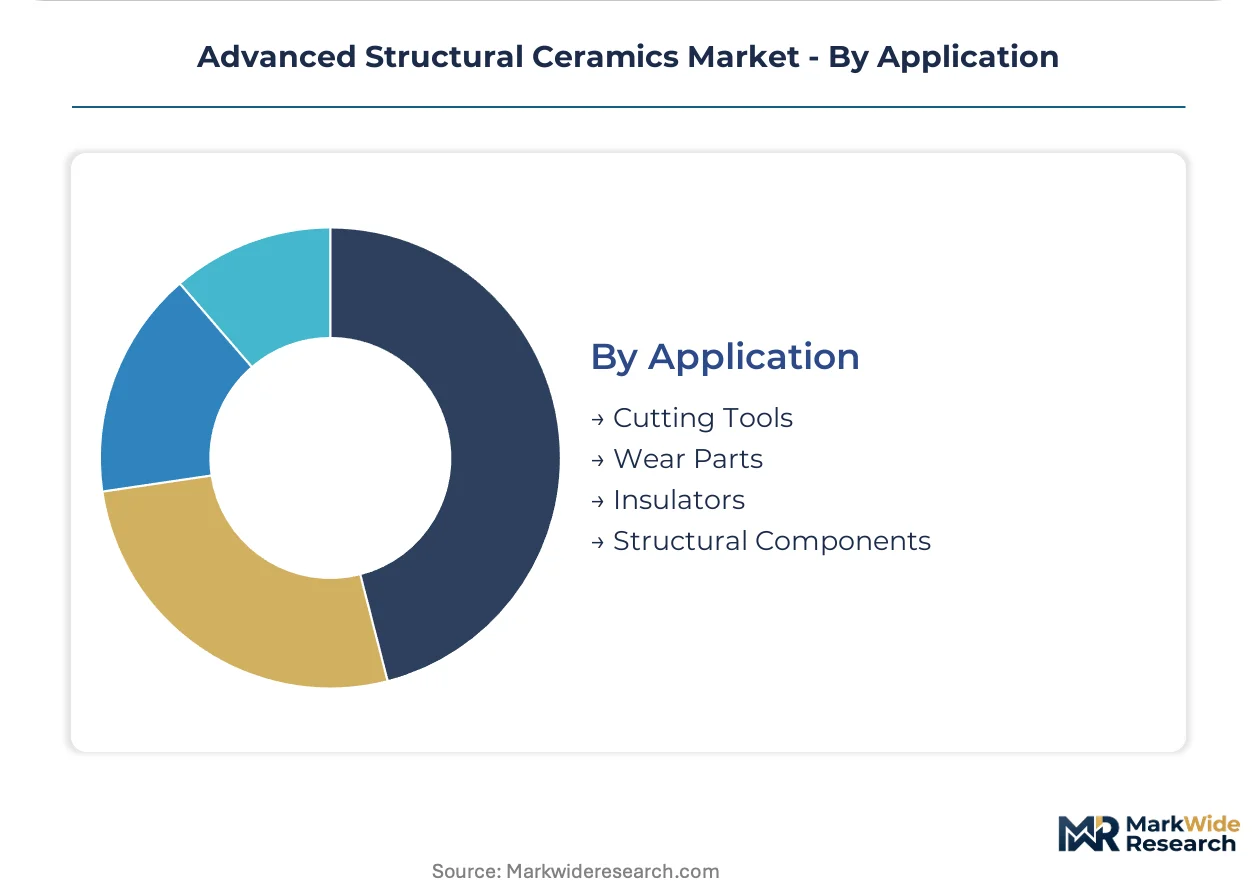
Application:
Functional performance requirements separate buyers optimizing for mechanical wear, electrical isolation, or structural load-bearing under thermal stress.
- Structural Components:Load-bearing parts for aerospace engines, industrial furnaces, and chemical processing equipment combine high-temperature strength with corrosion resistance. Silicon carbide fiber-reinforced ceramic matrix composites displace oxide-oxide systems in GE Aviation and Rolls-Royce combustor specifications.
- Wear Parts:Bearings, seals, and pump components exploit alumina and zirconia hardness for abrasive slurry handling and precision motion systems.
- Cutting Tools:Indexable inserts and round tools from titanium diboride and silicon nitride serve hardened steel and superalloy machining.
- Insulators:High-voltage bushings, spark plug bodies, and substrate cores leverage alumina dielectric properties in power distribution and ignition systems.
Structural components lead technology investment; wear parts sustain volume foundations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced structural ceramics concentrates in manufacturing corridors with established precision ceramics ecosystems and proximity to aerospace, automotive, and electronics OEMs. Germany, the United States, Japan, China, and India host the dominant clusters, each shaped by distinct regulatory frameworks and end-use specializations.
Germany
Stuttgart and Dresden precision ceramics corridors supply BMW, Siemens, and Bosch with medical-grade alumina and silicon carbide components. REACH authorization requirements for boron-based sintering aids are compressing formulation flexibility for local suppliers. The Stuttgart cluster responds fastest to ECHA substance evaluations, securing early authorization dossiers to maintain automotive and medical supply continuity.
United States
EPA emissions thresholds for NOx and CO2 are mandating lighter, hotter-running engine architectures across aerospace and automotive sectors. FAA-certified flame resistance requirements shape ceramic matrix composite specifications for turbine hot-section components. Manufacturing scale concentrates in industrial corridors serving GE Aviation and defense primes with long-term technical service agreements.
Japan
METI industrial technology grants promote domestic ceramic matrix composite development for defense and space applications. KYOCERA Corporation anchors semiconductor processing equipment supply through decades of fine-ceramic expertise. National supply security priorities reinforce technology transfer partnerships with established European and North American producers.
China
Dual carbon goals and MIIT industrial policy accelerate silicon carbide adoption in power electronics and electric vehicle thermal management. Yangtze River Delta manufacturing bases scale chemical vapor infiltration capacity for 800V power module substrates. GB standards adoption creates certified demand channels for automotive-grade ceramic components.
India
BIS standards adoption for advanced ceramics in power generation and steel processing creates certified demand channels for ISO-qualified suppliers. Industrialization in western and southern states drives wear parts and insulator consumption. Foreign suppliers establishing local technical service presence capture early-mover advantage in specification-critical segments.
Advanced Structural Ceramics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace and medical tiers favoring long-term technical partnerships while industrial wear parts trade on volume and logistics proximity. The vendor base organizes around three archetypes: diversified materials conglomerates with ceramics divisions, pure-play precision ceramics specialists, and captive in-house production units at aerospace primes. Competitive moves concentrate on strategic partnerships for technology transfer and geographic expansion through technical service localization.
Within the precision ceramics specialist tier, KYOCERA Corporation and CeramTec GmbH exemplify divergent specialization strategies, with the former representing Japanese fine-ceramic expertise in semiconductor processing and the latter occupying German medical-grade alumina positioning. CoorsTek, Inc. anchors North American manufacturing scale across multiple facilities, representing the volume-driven industrial archetype. Saint-Gobain and 3M exemplify diversified materials conglomerates leveraging cross-divisional technology transfer, while Morgan Advanced Materials and NGK Insulators represent regional specialists with deep heritage in electrical and thermal ceramics applications.
| Leading Market Players |
|---|
| Saint-Gobain |
| 3M |
| KYOCERA Corporation |
| NGK Insulators |
| Murata Manufacturing Co., Ltd. |
| CeramTec GmbH |
| Morgan Advanced Materials |
| AGC Ceramics Co., Ltd. |
| CoorsTek, Inc. |
| Others |
Supply Flow & Price Mechanics
High-temperature ceramics engineering talent concentrated in Stuttgart and Dresden widens pricing-tier spreads between specification-critical aerospace grades and commodity industrial alumina, as labor-cost differentials compound energy intensity gaps across European and Asian manufacturing bases.
Pricing Analysis
Volume-driven industrial wear parts trade on thin margins against specification-critical aerospace and medical grades commanding substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified implantable alumina from automotive sensor housings and bulk industrial insulators. Cost compression in standard grades intensifies because energy price volatility squeezes European sintering operations. Automotive OEMs exhibit highest price sensitivity, while aerospace primes prioritize technical service commitments over unit cost.
Supply Chain Analysis
Workforce availability constraints in high-temperature process engineering concentrate supply chain control within Germany, Japan, and the United States, where university pipelines produce insufficient metallurgical specialists for expanding capacity. Raw material flows draw from Chinese rare earth processing for yttria-stabilized zirconia, Ukrainian titanium feedstock for diboride ceramics, and Qatari natural gas for European sintering energy. Single-source vulnerability concentrates with limited qualified suppliers of fluorinated chemical vapor infiltration precursors subject to EU F-Gas Regulation phase-downs. Distribution runs through long-term technical service agreements with aerospace primes, displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced structural ceramics is consolidating toward specialists with captive certification assets and geographic proximity to aerospace procurement centers, as REACH authorization timelines and ISO 13485 validation cycles force weaker players without regulatory dossier depth toward exit.
For Market Incumbents: Lock in aerospace prime relationships through 7-10 year technical service agreements with embedded R&D collaboration, while securing early REACH authorization dossiers for boron-based sintering aids to defend medical-grade alumina positioning against formulation-locked competitors. Backward integration into fluorinated precursor supply hedges EU F-Gas Regulation disruption.
For New Entrants and Emerging Players: Capture certified demand channels in Indian power generation and steel processing by establishing local technical service presence ahead of BIS standards maturation, while targeting silicon carbide power module substrates for 800V electric vehicle architectures as the most penetrable growth vector outside aerospace qualification barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with precision ceramics specialists possessing ISO 13485 certification and established aerospace technical service contracts given EPA emissions threshold acceleration and METI grant-driven Japanese demand. Watch chemical vapor infiltration capacity expansion announcements as the inflection signal for supply-constrained silicon carbide matrix composite availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Precursors | Secures supply continuity against EU F-Gas Regulation phase-down schedules affecting chemical vapor infiltration. |
| ISO 13485 Certification Investment | Unlocks orthopedic OEM procurement channels with 18-24 month validation timelines blocking unqualified competitors. |
| Long-term Supply Agreement with Aerospace Primes | Restructures procurement toward 7-10 year technical service commitments with Safran, GE Aviation, and Rolls-Royce. |
| Local Technical Service Presence in India | Captures BIS-certified demand in power generation and steel processing ahead of foreign supplier qualification requirements. |
| Silicon Carbide Capacity Expansion | Addresses supply constraints for 800V electric vehicle power modules and aerospace turbine hot-section components. |
Methodological Framework
Multi-period observation of EPA emissions threshold evolution, REACH authorization timelines, and METI grant disbursements anchored the trend analysis, supplemented by interviews with ceramic matrix composite procurement leads at aerospace OEMs, sintering furnace operations managers in Stuttgart and Dresden precision clusters, semiconductor processing equipment engineers, and orthopedic implant quality directors. Secondary validation drew from ECHA substance evaluation roadmaps, FAA certification databases, SEC 10-K filings of listed ceramics producers, and BIS standards development notices. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
The input-output matrix framed demand modeling across product type, end-use industry, form factor, and application functional requirements, with value trajectories derived from price-tier spreads between specification-critical and commodity grades. Segment-level CAGRs were computed from installed base expansion, content-per-unit trends in aerospace engines and electric vehicles, and substitution elasticity estimates for nickel superalloy displacement. Forecast inputs included chemical vapor infiltration capacity buildout schedules, fluorinated precursor supply contract durations, and university ceramics engineering graduation rates in Germany and Japan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation reclassification, natural gas price volatility at TTF benchmarks, and aerospace prime consolidation into long-term sole-source agreements. Forecasts reflect documented assumptions regarding REACH authorization grant rates and METI grant continuation. Material deviation in EU fluorinated gas policy, sintering energy cost trajectories, or aerospace engine platform standardization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Calcite Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Dielectric Ceramics Market
Ceramics
Europe Activated Alumina Market
Ceramics
Calcium Oxide Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Global Functional Ceramics Market
Ceramics
Glass Ceramics Market
Ceramics
Titanates Market
Ceramics
Engineering Ceramics Market
Ceramics
Thermal Spray Powder Market
Ceramics
Alumina Slurry Market
Ceramics
Transparent Ceramics Market