
 West Africa Ceramic Tiles Market | 2026-2036
West Africa Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Ceramic Tiles Market Intelligence
After-sales maintenance contracts and installation support services is realigning how ceramic tiles are monetized in West Africa, shifting value capture beyond the initial product sale. Nile Ceramics leverages its Lagos manufacturing base to control distribution costs across Nigeria's southwestern corridor. Equatorial Ceramics Group anchors its competitive position through specialized vitrified tile production for commercial projects. West African Ceramics Ltd dominates the wholesale channel network serving Ghana and Côte d'Ivoire.
West Africa ceramic tiles are fired clay or silica-based surfacing materials, typically measuring 300x300mm to 600x600mm, produced through roller-kiln processes at temperatures exceeding 1,200°C for residential flooring, wall cladding, and commercial interior finishes. Porcelain tiles command premium positioning due to lower water absorption rates below 0.5%, making them preferred for high-humidity coastal installations. The residential end-user segment sustains volume leadership across Lagos, Accra, and Abidjan metropolitan construction. Flooring installations occupy the largest share of contractor procurement budgets, while outdoor applications represent the fastest-expanding installation category for pool decks and commercial terraces.
Nigeria's Standards Organisation (SON) mandates compliance with NIS building material codes, while Ghana's Ghana Standards Authority enforces GS tile specifications for imported and domestically manufactured products. Côte d'Ivoire's national quality regulator applies CODINORM standards that restrict heavy-metal content in ceramic glazes, shaping supplier certification requirements. The Economic Community of West African States (ECOWAS) common external tariff structure influences cross-border tile pricing and origin labeling rules. Stakeholders must monitor harmonization gaps between national standards and emerging ECOWAS regional conformity protocols to anticipate market access shifts.
Market Dynamics
The West Africa ceramic tiles market is being restructured by tightening national quality standards that are forcing supplier consolidation and raising compliance barriers for imported products. Nigeria's SON certification mandates and Ghana's GS specifications are creating a two-tier market where certified domestic producers capture premium channels while uncertified imports face port delays and rejection risks.
Growth Catalysts
- Lagos-Abidjan residential corridor:Metropolitan housing developments across Nigeria and Côte d'Ivoire are accelerating tile consumption for flooring and wall cladding in multi-unit residential towers.
- ECOWAS common external tariff harmonization:The regional trade framework is reducing cross-border duty friction, enabling Nigerian manufacturers to serve Ghanaian distributors without prohibitive origin penalties.
- Vitrified tile technology adoption:Lower water absorption specifications below 0.5% are displacing traditional ceramic in coastal commercial installations from Accra to Port Harcourt.
Market Restraints
- Natural gas supply volatility:Roller-kiln operations exceeding 1,200°C depend on Nigerian gas infrastructure subject to pipeline disruptions and pricing spikes.
- Chinese import concentration:Wholesale channels in Benin and Togo remain saturated with lower-cost Asian tiles that compress margin structures for regional manufacturers.
- CODINORM heavy-metal restrictions:Côte d'Ivoire's glaze content regulations are forcing reformulation investments that extend product development cycles by 4-6 months.
Strategic Opportunities
- Senegalese coastal commercial expansion:Dakar's hospitality and retail construction pipeline remains underpenetrated by certified regional suppliers.
- Installation service bundling:Contractor procurement is shifting toward turnkey flooring packages that combine material supply with skilled labor deployment.
- ECOWAS regional conformity protocols:Emerging harmonized standards will enable single-certification market access across five member states.
Industry Challenges
- Skilled installer scarcity:Large-format 600x600mm porcelain placement demands specialized tiling crews that are concentrated in Lagos and Accra metropolitan zones.
- SON certification timeline compression:Nigerian import pre-shipment verification requirements are creating inventory gaps for distributors unable to secure timely laboratory testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Ceramic Tiles Market |
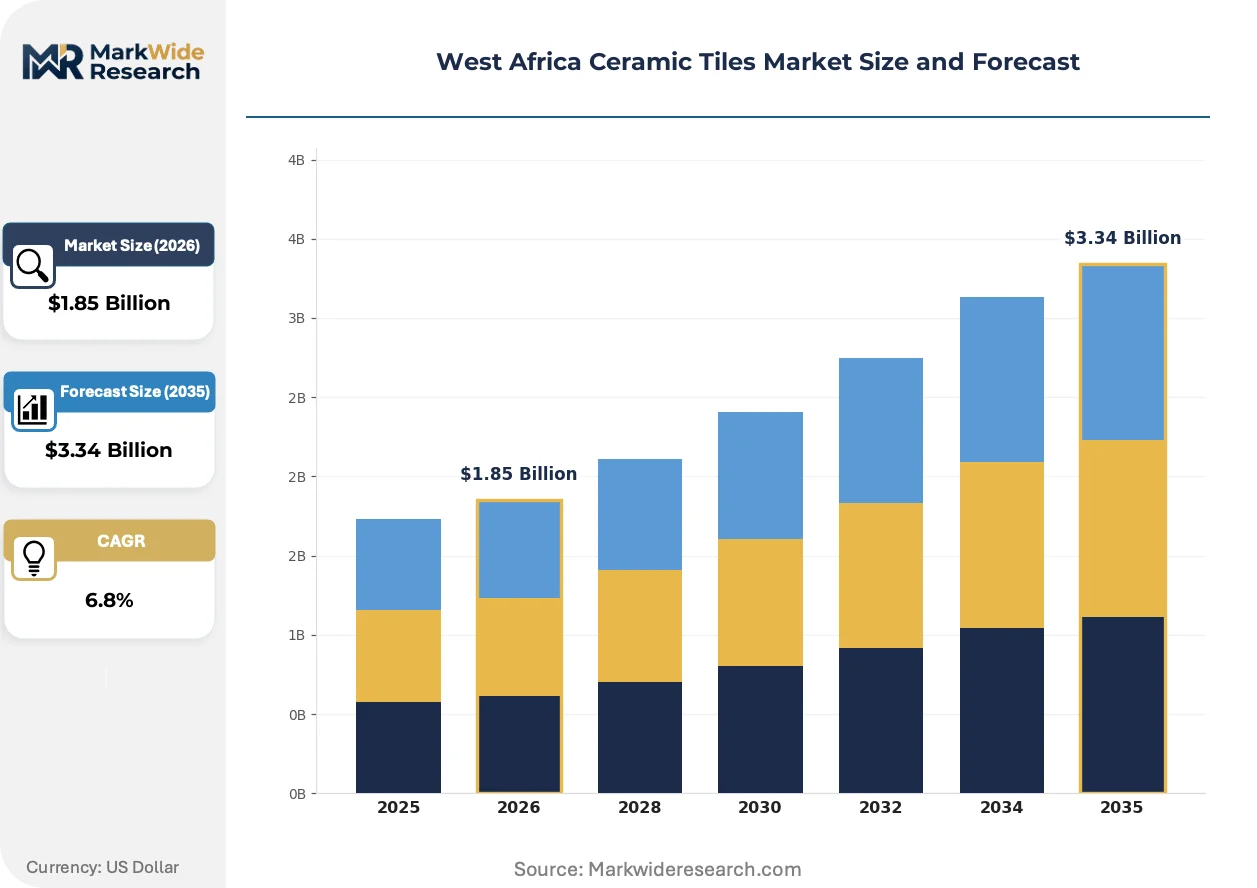
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitrified Tiles, Porcelain Tiles, Glazed Tiles, Rustic Tiles End User: Residential, Commercial, Industrial, Hospitality Installation Type: Flooring, Wall Cladding, Countertops, Outdoor Applications Distribution Channel: Retail Stores, Online Platforms, Wholesale, Direct Sales |
| Companies Covered | Nile Ceramics, Equatorial Ceramics Group, West African Ceramics Ltd, Innovative Ceramics Co. Ltd, Maghreb Ceramics SA, CeramicMasters Limited, African Ceramic Holdings, EcoCeramics Africa, Royal Ceramics, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Ceramic Tiles Market Strategic Shifts & Innovations
Digital printing technology and kiln efficiency upgrades are transforming product differentiation and energy economics across West African manufacturing facilities. These shifts are compressing traditional supply advantages while enabling new competitive entry points.
Digital inkjet decoration systems are expanding into West African production lines, enabling granite and wood-grain surface replication without glaze-layer thickness penalties. Lagos-based manufacturers are adopting these systems to serve premium residential developers seeking differentiated aesthetics. The technology is expanding into mid-market price tiers as equipment financing structures mature.
Nigeria's SON has tightened NIS building material enforcement, mandating third-party laboratory verification for all imported tile batches. Industrial consequence includes extended customs clearance periods and elevated compliance costs for distributors. Commercial project contractors are responding by shifting procurement toward domestically certified manufacturers with established SON relationships.
After-sales maintenance contracts are displacing traditional product-only transactions in commercial channel relationships. Facility management firms serving Accra and Abidjan office complexes are bundling multi-year surface care agreements with initial tile procurement. This pattern is most visible in Nigerian hospitality developments where operator brands demand guaranteed appearance retention across five-year operational cycles.
West Africa Ceramic Tiles Market Segmentation
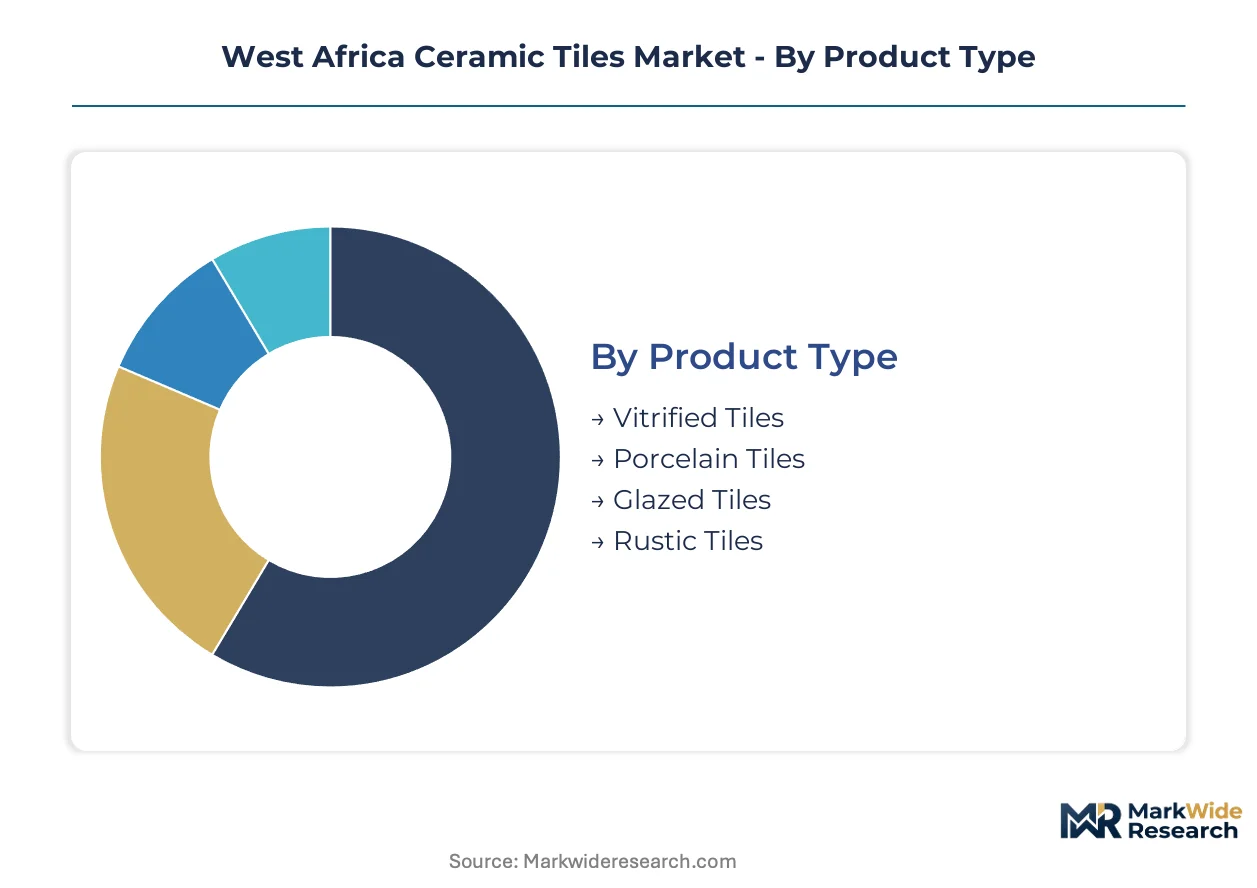
West Africa's ceramic tile segmentation reflects divergent buyer priorities across construction verticals. Material specifications, installation complexity, and channel access costs each reshape procurement patterns from Lagos residential towers to Abidjan hospitality developments.
Product Type:
Buyer decisions here pivot on water absorption thresholds and surface durability requirements for coastal humidity exposure.
- Vitrified Tiles:Manufactured through vitrification at temperatures exceeding 1,200°C with near-zero porosity below 0.5% water absorption. Demand concentrates in Port Harcourt and Accra commercial developments where salt-laden air accelerates surface degradation on standard ceramics. SON certification requirements favor domestic vitrified producers with established laboratory relationships.
- Porcelain Tiles:Dense, fine-grained ceramic body fired at extreme temperatures yielding superior mechanical strength and stain resistance. Lagos metropolitan residential towers specify porcelain for high-traffic lobby and corridor installations; specification engineers prioritize batch consistency over unit cost in these procurement decisions.
- Glazed Tiles:Surface-coated ceramics offering aesthetic variety at moderate price points; Côte d'Ivoire's CODINORM heavy-metal restrictions are forcing glaze reformulation investments.
- Rustic Tiles:Textured, matte-finish products mimicking natural stone; niche positioning in boutique hospitality projects across Dakar and Abidjan.
Volume sits with vitrified tiles; growth tilts toward porcelain as coastal commercial specifications tighten.
End User:
Application scale and specification authority determine channel access and margin capture across construction verticals.
- Residential:Multi-unit housing developments across Lagos, Accra, and Abidjan metropolitan zones drive bulk procurement through contractor networks. Family-owned distributors maintain relationships with mid-scale developers seeking standardized 400x400mm and 600x600mm formats for apartment flooring.
- Commercial:Office complexes and retail centers demand certified products with documented durability testing; facility management firms bundle multi-year maintenance contracts with initial tile supply.
- Industrial:Manufacturing facilities and logistics warehouses prioritize chemical resistance and load-bearing capacity over aesthetic considerations.
- Hospitality:Hotel operators require guaranteed appearance retention across operational cycles; procurement emphasizes after-sales surface care agreements.
Residential commands absolute volume; hospitality offers the steepest expansion trajectory as Dakar and Abidjan tourism infrastructure accelerates.
Installation Type:
Labor skill requirements and substrate preparation costs segment demand across construction trades.
- Flooring:Largest procurement category by square meterage; contractor budgets prioritize material-labor bundling for large-format porcelain placement requiring specialized crews.
- Wall Cladding:Vertical installation demands lighter tile bodies and enhanced adhesive specifications; bathroom and kitchen applications in residential towers concentrate demand.
- Countertops:Thickness and edge-finishing requirements favor premium porcelain slabs; limited local fabrication capacity constrains supply.
- Outdoor Applications:Pool decks, terraces, and commercial plazas require frost-resistant, anti-slip surfaces; fastest-climbing category as coastal hospitality construction expands.
Flooring absorbs the majority of contractor expenditure; outdoor applications are gaining share fastest on hospitality and retail construction pipelines.
Distribution Channel:
Inventory carrying costs and credit terms structure access to different buyer segments across the region.
- Retail Stores:Showroom-based selection for individual homeowners and small-scale renovators; Lagos and Accra metropolitan concentrations support format diversification.
- Online Platforms:Emerging channel for standardized product comparison; limited traction for large-format tiles requiring physical inspection.
- Wholesale:Bulk supply to contractor networks and regional distributors; West African Ceramics Ltd anchors this channel across Ghana and Côte d'Ivoire.
- Direct Sales:Manufacturer relationships with major developers and hospitality operators; bypasses distributor margins for volume commitments.
Wholesale moves the highest tile volumes; direct sales channels are expanding most quickly as certified manufacturers cultivate developer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors West African tile demand through its sprawling metropolitan construction corridor, where residential towers and commercial developments concentrate procurement volumes across Nigeria's southwestern industrial belt.
Nigeria
Multi-unit residential towers across Lagos and Port Harcourt drive bulk vitrified tile procurement for flooring and wall cladding applications. The Standards Organisation of Nigeria enforces NIS building material codes with mandatory third-party laboratory verification for imported batches. Manufacturing clusters in Ogun State's industrial corridor supply certified products to southwestern distributor networks.
Ghana
Accra's hospitality and retail construction pipeline accelerates porcelain tile specifications for high-traffic commercial installations. The Ghana Standards Authority applies GS specifications that restrict port entry for uncertified imports. Tema's port infrastructure and warehousing zones concentrate wholesale distribution serving Greater Accra's contractor networks.
Côte d'Ivoire
Abidjan's metropolitan housing developments sustain demand for mid-market glazed tiles in multi-unit residential formats. CODINORM standards restrict heavy-metal content in ceramic glazes, forcing reformulation investments from suppliers. The Plateau district's commercial renovation cycle favors certified vitrified products for office complex flooring.
Senegal
Dakar's hospitality construction pipeline remains underpenetrated by certified regional suppliers despite accelerating tourism infrastructure investment. The country's national quality regulator applies building material conformity assessments that favor ECOWAS-origin products. Almadies and Mermoz coastal zones concentrate boutique hotel developments specifying premium porcelain terraces.
Benin and Togo
Cotonou and Lomé function as transit hubs for lower-cost Asian tile imports saturating wholesale channels across the sub-region. Port authorities apply origin labeling rules under ECOWAS common external tariff structures. Distributor networks in these corridor economies supply informal retail channels compressing margin structures for certified manufacturers.
West Africa Ceramic Tiles Market Key Industry Players
Capital-heavy producers with captive kiln operations compete with asset-light distributors sourcing through Asian manufacturing partnerships. Market structure tilts toward consolidation as Nigerian SON certification requirements raise compliance barriers and extend customs clearance timelines for import-dependent players. Three archetypes dominate: integrated domestic manufacturers with laboratory relationships, regional distributors controlling wholesale channel access, and specialized hospitality-sector suppliers bundling after-sales maintenance. Competitive moves concentrate on backward integration into raw material sourcing and direct developer relationship cultivation bypassing distributor margins.
Among Nigerian-based integrated manufacturers, Nile Ceramics occupies a position exemplifying domestic production scale advantages, while Equatorial Ceramics Group represents specialization in vitrified formats for commercial project specifications. West African Ceramics Ltd anchors the wholesale distributor archetype across Ghana and Côte d'Ivoire channel networks.
| Leading Market Players |
|---|
| Nile Ceramics |
| Equatorial Ceramics Group |
| West African Ceramics Ltd |
| Innovative Ceramics Co. Ltd |
| Maghreb Ceramics SA |
| CeramicMasters Limited |
| African Ceramic Holdings |
| EcoCeramics Africa |
| Royal Ceramics |
| Others |
Cost & Logistics Intelligence
Natural gas feedstock costs cascade through Nigerian manufacturing economics, driving three-tier pricing stratification across vitrified, porcelain, and glazed ceramic segments. Lagos-based integrated producers capture margin premiums through captive kiln operations, while import-dependent distributors absorb SON certification laboratory fees and extended customs clearance timelines.
Pricing Analysis
Outcome-based pricing anchors commercial procurement through multi-year surface appearance guarantees bundled with initial tile supply. SON certification grade and after-sales service bundling differentiate price tiers, with certified domestic producers commanding premiums over uncertified imports. Cost compression in wholesale channels intensifies as Chinese import saturation through Benin and Togo compresses margin structures. Residential contractors exhibit highest price sensitivity; hospitality operators prioritize guaranteed performance retention over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Nigerian natural gas infrastructure feeding roller-kiln operations exceeding 1,200°C. Manufacturing concentration clusters in Nigeria, Ghana, and Côte d'Ivoire, with raw material dependencies spanning imported feldspar, kaolin clay deposits, and specialized glaze formulations. Tariff exposure through ECOWAS common external tariff harmonization gaps creates cross-border friction. Distribution runs through wholesale channel networks anchored by Tema and Lagos port warehousing zones serving contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas-fired kiln capacity constraints across Nigeria's Ogun State industrial corridor prop pricing power for certified domestic producers. Supply scarcity in large-format porcelain fabrication supports margin defense.
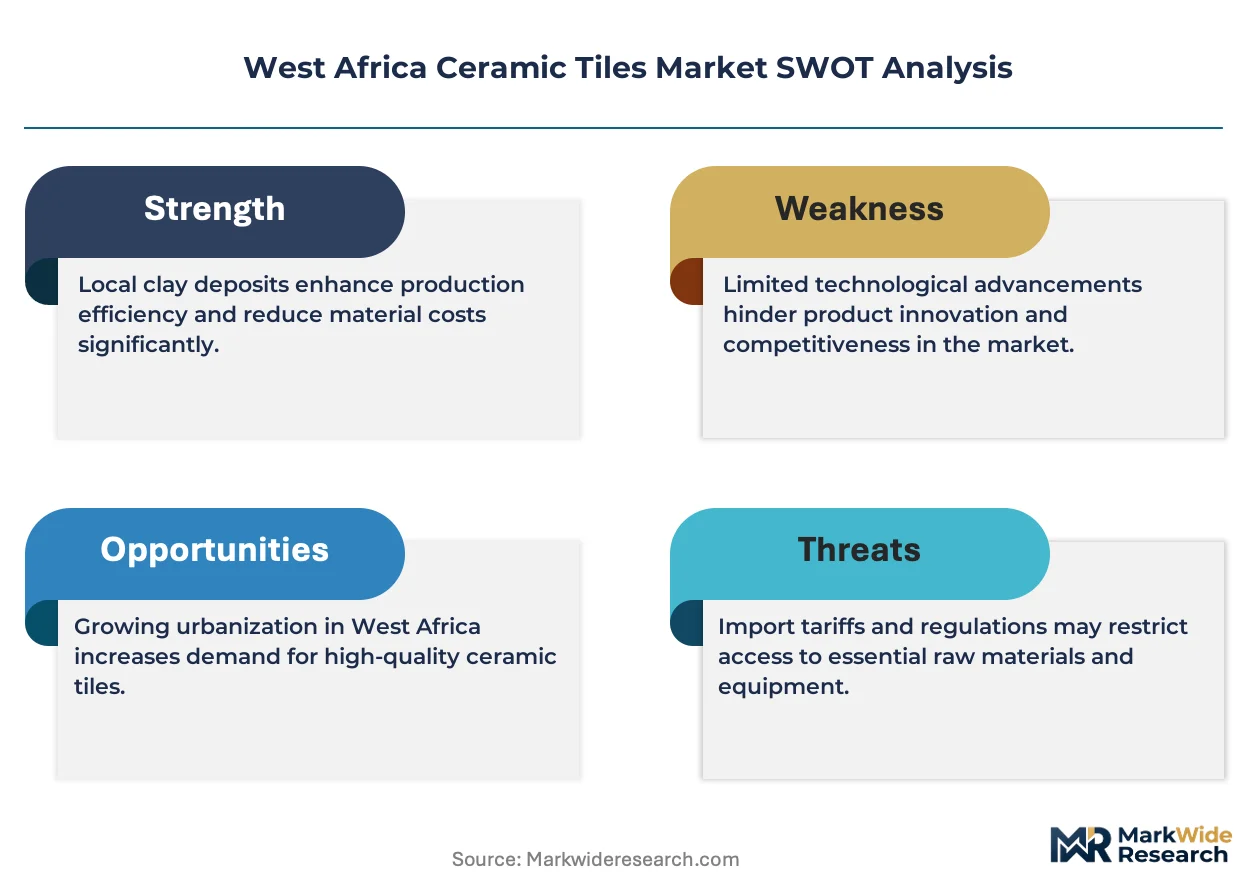
For Market Incumbents: Anchor defensive positioning through backward integration into kaolin clay deposits and feldspar sourcing partnerships. SON certification timeline compression threatens import-dependent distributors; prioritize laboratory relationship investments and direct developer procurement contracts bypassing wholesale margins. Capacity addition in Ghana's Tema corridor secures ECOWAS market access. For New Entrants and Emerging Players: Begin with Dakar's underpenetrated hospitality construction pipeline, where certified regional supplier scarcity creates white-space opportunity. Target boutique hotel terrace specifications demanding premium porcelain anti-slip surfaces. Go-to-market leverage rests on installation service bundling with skilled crew deployment. For Investors and Strategic Acquirers: ECOWAS regional conformity protocol harmonization announcement is the leading indicator that single-certification market access across five member states will consolidate procurement toward certified producers. Long-term viability favors integrated manufacturers with captive kiln operations and established regulatory relationships. Acquisition target archetype: mid-scale vitrified specialists with SON laboratory partnerships and Ogun State production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive kaolin and feldspar supply secures margin protection against import price volatility. |
| SON Certification Investment | Third-party laboratory relationships accelerate customs clearance and unlock premium channel access. |
| Installation Service Bundling | Turnkey flooring packages capture contractor procurement shifting toward material-labor combinations. |
| Digital Inkjet Technology Adoption | Granite and wood-grain surface replication enables premium residential developer differentiation. |
| ECOWAS Regional Conformity Alignment | Harmonized standards enable single-certification market access across Nigeria, Ghana, and Côte d'Ivoire. |
Research Approach
Document review covered customs trade databases, SON certification records, and ECOWAS tariff harmonization frameworks, complemented by interviews with plant operations managers, ceramic distributor procurement leads, commercial project contractors, and facility management firms serving hospitality developments. Secondary validation drew from Ghana Standards Authority publications, CODINORM regulatory filings, and industry production capacity disclosures. Bottom-up tile volume estimates triangulated against top-down construction spending projections across Lagos, Accra, and Abidjan metropolitan zones.
Segment-level value outputs trace product type, end-user vertical, installation category, and distribution channel dimensions across the projection horizon. CAGRs derive from regression analysis against urbanization rates, residential tower completion pipelines, and commercial floor space expansion. Forecast inputs incorporate natural gas pricing trajectories, SON enforcement intensity indices, and vitrified technology adoption curves.
Underlying measurement precision varies by segment; vitrified and porcelain categories carry tighter precision than emerging outdoor application estimates. Forecasts reflect assumptions around ECOWAS tariff harmonization implementation and SON laboratory capacity expansion. Deviation in Nigerian gas infrastructure reliability or CODINORM heavy-metal restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Alumina Trihydrate Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Strontium Carbonate Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
ME K-Feldspar Market
Ceramics
Calcium Oxide Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Kaolin Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Europe Activated Alumina Market
Ceramics
Asia-Pacific Activated Alumina Market