
 Southeast Asia Melamine Market | 2026-2036
Southeast Asia Melamine Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Melamine Market Analytics
Buyer concentration among Southeast Asia's integrated furniture exporters is rebalancing as Vietnamese and Indonesian millwork producers expand captive laminate production. Mitsui Chemicals Asia-Pacific Ltd leverages its regional urea-melamine integration to secure feedstock cost advantages across ASEAN manufacturing zones. PTT Global Chemical anchors Thai domestic supply through its petrochemical corridor linkages. Petronas Chemicals Group Berhad competes via Malaysian port logistics and duty-efficient access to Commonwealth markets.
Melamine is a nitrogen-rich heterocyclic organic compound (C3H6N6) manufactured through urea thermal decomposition at elevated pressure, yielding a crystalline powder that crosslinks with formaldehyde to produce thermoset resins with exceptional hardness and heat resistance. Its primary industrial purpose centers on decorative laminates, molded dinnerware, and flame-retardant foams where surface durability and thermal stability are critical. Melamine Formaldehyde dominates current formulation volumes due to established supply chains and proven performance in high-wear furniture applications. Melamine Foam represents the fastest-expanding category, driven by acoustic and thermal insulation demand from ASEAN automotive assembly plants and commercial construction. Melamine Resin maintains mature, margin-compressed positioning in commodity-grade particleboard binders where price competition from alternative amino resins intensifies.
Thailand's Department of Industrial Works enforces effluent and air emission standards that elevate compliance costs for melamine-formaldehyde resin producers operating near Bangkok industrial zones. Indonesia's Ministry of Environment and Forestry implements hazardous substance controls affecting imported melamine raw materials and finished compound classifications. Malaysia's Department of Standards Malaysia (DSM) administers product certification protocols for formaldehyde release in wood-based panels, directly shaping resin specification requirements for laminate suppliers serving the Klang Valley furniture cluster. Stakeholders must monitor evolving national chemical inventories across ASEAN member states, as regulatory harmonization delays could fragment product approval timelines and complicate cross-border formulation standardization.
Market Dynamics
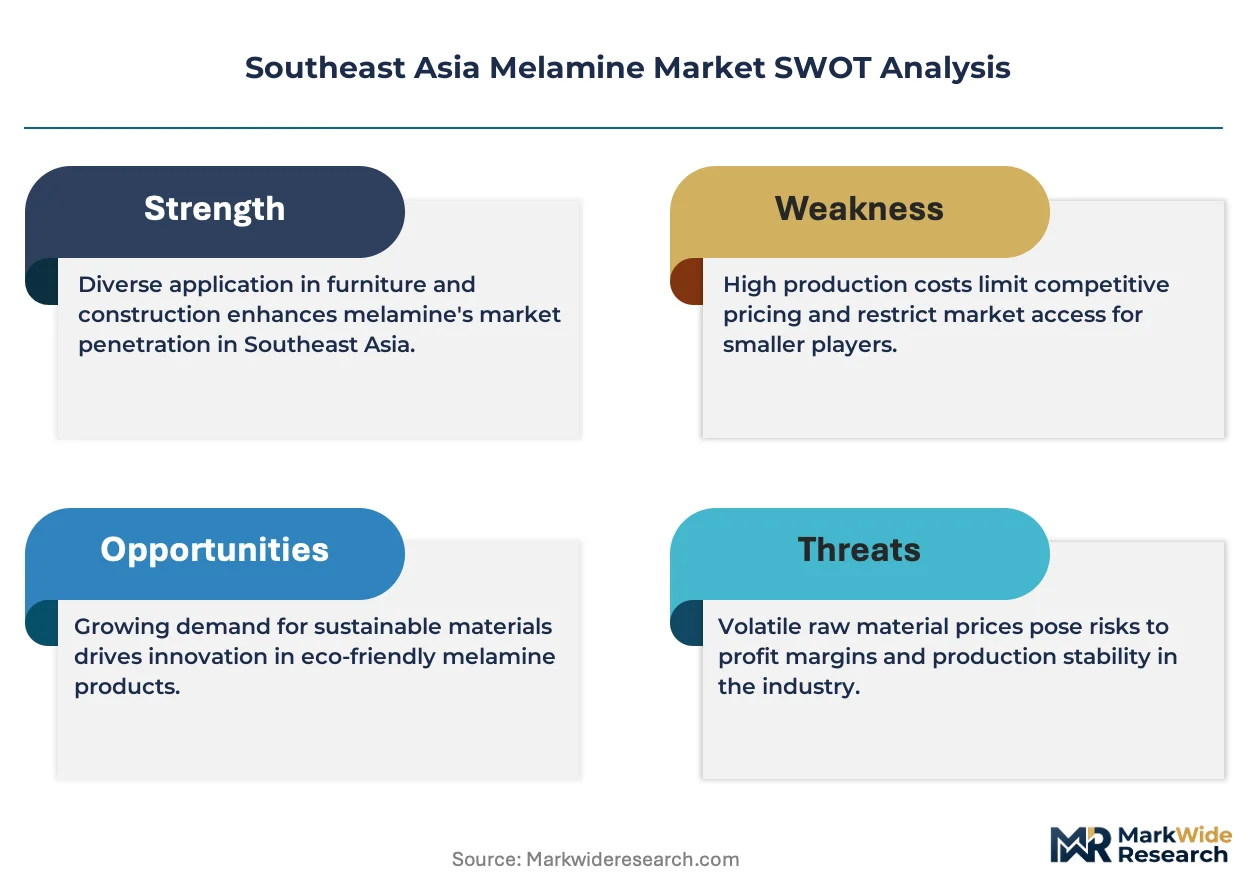
Malaysia's stricter formaldehyde emission standards under DSM certification are forcing laminate converters to reformulate resin systems, compressing margins for commodity-grade suppliers while rewarding low-emission specialists across the Thai-Vietnamese furniture corridor.
Growth Catalysts
- DSM Certification Mandate:Malaysia's national standards body enforces formaldehyde release limits that accelerate specification upgrades across Klang Valley panel manufacturers.
- Automotive Acoustic Insulation:Melamine foam demand from ASEAN vehicle assembly plants in Thailand and Indonesia expands application scope beyond traditional decorative laminates.
- Surabaya-Jepara Woodworking Cluster:Indonesia's concentrated furniture production hub drives localized resin consumption and captive laminate integration.
Market Restraints
- Urea Feedstock Volatility:Natural gas price swings in Thai petrochemical corridors directly compress melamine resin margins for non-integrated converters.
- Regional Supply Concentration:Mitsui Chemicals Asia-Pacific and PTT Global Chemical control upstream urea-melamine integration, limiting feedstock access for independent formulators.
- Amino Resin Substitution:Urea-formaldehyde binders in commodity particleboard applications displace melamine resins where heat resistance requirements permit.
Strategic Opportunities
- Vietnamese Millwork Expansion:Furniture exporters in Binh Duong and Dong Nai provinces are building captive laminate capacity, creating localized chemical formulation partnerships.
- Low-Emission Resin Formulations:DSM-compliant binders command specification premiums in Malaysian export furniture serving Commonwealth markets.
- Cross-Border Formulation Harmonization:Divergent ASEAN national chemical inventories create first-mover advantage for suppliers achieving multi-jurisdictional product approvals.
Industry Challenges
- Multi-Jurisdictional Compliance Timelines:Indonesia's Ministry of Environment and Forestry maintains separate hazardous substance classifications from Thai and Malaysian regulators, fragmenting product registration cycles.
- Legacy Resin System Retrofit Costs:Bangkok industrial zone manufacturers face capital-intensive effluent and air emission upgrades under Department of Industrial Works enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Melamine Market |
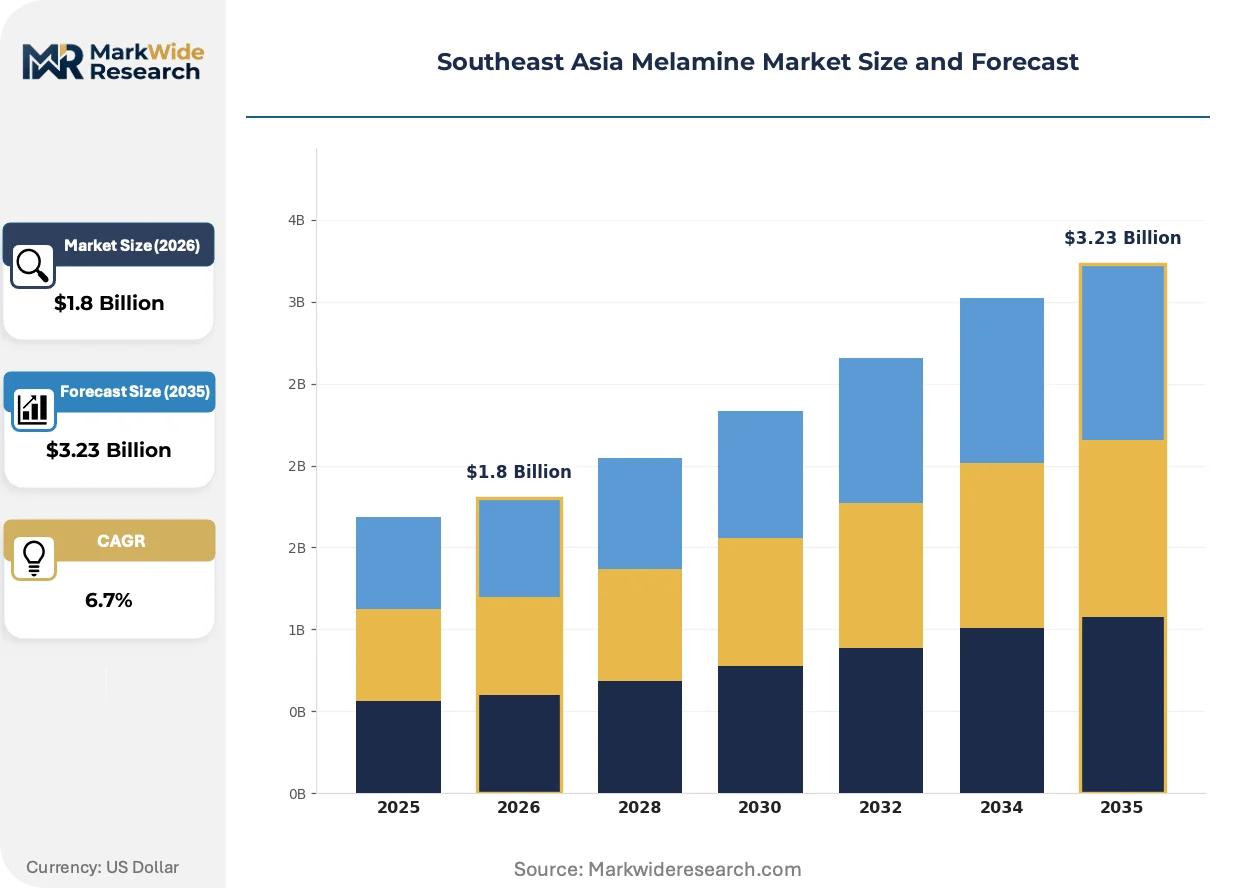
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melamine Resin, Melamine Formaldehyde, Melamine Moulding Compounds, Melamine Foam End User: Furniture, Building Materials, Automotive, Consumer Goods Application: Coatings, Adhesives, Laminates, Surface Treatment Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Mitsui Chemicals Asia-Pacific Ltd, PTT Global Chemical, Petronas Chemicals Group Berhad (PCG), PT Chandra Asri Petrochemical, Formosa Chemicals & Fibre Corporation, Nissan Chemical Corporation, Wakomas Chemical Sdn. Bhd., AICA Hatyai Co Ltd, Borealis Agrolinz Melamine GmbH, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Melamine Market Evolving Landscape
Formulation chemistry and regulatory compliance are converging to reshape competitive positioning across Southeast Asian melamine value chains, with sustainability specifications and captive production models driving divergence between premium and commodity supply tiers.
Low-emission melamine-formaldehyde resin systems are electrifying specification standards across Malaysian and Thai furniture manufacturing. DSM-certified panel producers in the Klang Valley are mandating reduced formaldehyde release binders for export shipments. This electrifying shift compresses demand for legacy high-emission formulations while expanding specification premiums for compliant suppliers.
Indonesia's Ministry of Environment and Forestry is tightening hazardous substance controls on imported melamine raw materials and finished compound classifications. Industrial consequence includes extended product registration timelines and reformulation requirements for suppliers serving Surabaya-Jepara woodworking clusters. Vietnamese and Thai exporters are responding by accelerating in-house resin production to circumvent import classification friction.
Captive laminate integration is reshaping procurement patterns among Southeast Asia's integrated furniture exporters. Vietnamese millwork producers in Binh Duong and Dong Nai are displacing third-party laminate suppliers with in-house panel production. This behavioral shift is most visible in Thailand's automotive component supply chain, where acoustic foam buyers now specify direct resin relationships over distributor-mediated procurement.
Southeast Asia Melamine Market Segmentation
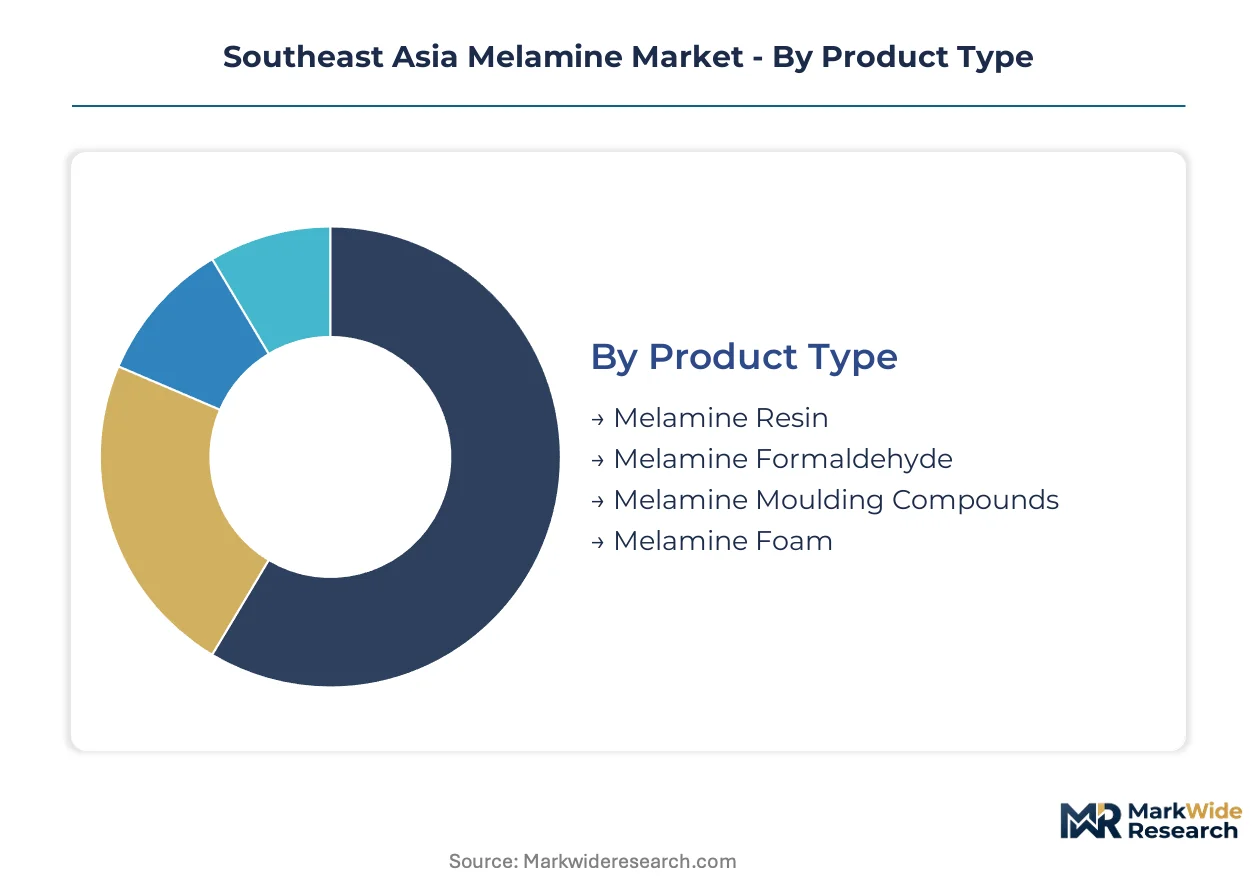
Melamine value chains in Southeast Asia fragment across technical specifications, regulatory compliance tiers, and captive integration models. Understanding these divisions reveals where margin concentrates and which conversion technologies command specification premiums.
Product Type:
Cost tier separates commodity thermoset binders from specialty formulations serving emission-certified export markets.
- Melamine Formaldehyde:This thermoset resin crosslinks melamine with formaldehyde under heat and pressure to produce surface coatings with exceptional hardness and thermal stability. Furniture manufacturers across Thailand's Eastern Economic Corridor and Vietnam's Binh Duong province consume the bulk of volumes for decorative laminate production. DSM certification requirements in Malaysia are accelerating specification upgrades toward low-emission grades.
- Melamine Foam:A lightweight, open-cell thermoset polymer manufactured through controlled foaming of melamine-formaldehyde resin precursors. ASEAN automotive assembly plants in Thailand's Rayong province and Indonesia's Bekasi district specify this material for engine bay acoustic insulation and thermal management. The segment expands most quickly as vehicle production localizes.
- Melamine Resin:Unmodified amino resin serving commodity particleboard binders where urea-formaldehyde substitution pressure intensifies.
- Melamine Moulding Compounds:Compression-grade thermoset powders for dinnerware and electrical component housings.
Melamine Formaldehyde leads volumes today; Melamine Foam is gaining share fastest.
End User:
Application maturity and emission compliance intensity divide buyers into specification-sensitive exporters versus price-driven domestic suppliers.
- Furniture:Integrated millwork producers in Vietnam's Dong Nai province and Indonesia's Jepara cluster drive laminate consumption for export shipments. Malaysian DSM certification mandates are forcing reformulation toward low-emission binders for Commonwealth market access.
- Automotive:Thailand's vehicle assembly corridor from Bangkok to Rayong sources melamine foam for NVH reduction and under-hood thermal barriers. Indonesian plants in Bekasi are following similar specification patterns.
- Building Materials:Construction-grade laminates and surface coatings for commercial interiors.
- Consumer Goods:Moulded dinnerware and household items where food-contact regulations shape resin selection.
Furniture commands the largest share; Automotive climbs the fastest.
Application:
Volume scale and margin structure diverge between commodity binders and certified surface treatments.
- Laminates:Decorative high-pressure laminates for furniture and interior surfaces dominate value extraction. Thai and Vietnamese captive production is displacing third-party procurement.
- Adhesives:Wood panel binders face amino resin substitution pressure in commodity particleboard.
- Coatings:Industrial finishes requiring heat resistance and surface hardness.
- Surface Treatment:Specialty treatments for wear-resistant applications.
Laminates anchor current volumes; Coatings show steepest expansion trajectory.
Distribution Channel:
Supply chain configuration separates integrated direct procurement from distributor-mediated spot buying.
- Direct Sales:Mitsui Chemicals Asia-Pacific and PTT Global Chemical supply captive laminate operations through long-term offtake agreements. Vietnamese furniture exporters in Binh Duong are consolidating procurement through direct resin relationships.
- Distributors:Independent formulators and small-scale converters rely on regional chemical distributors for feedstock access.
- Retail:Small-volume sales for specialty applications and maintenance supplies.
- Online:Emerging channel for technical documentation and sample procurement.
Direct Sales dominates transaction value; Distributors retain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam diverge in melamine consumption patterns despite sharing the same furniture export boom. Thai producers leverage integrated petrochemical corridors while Vietnamese manufacturers accelerate captive laminate production. Indonesia's woodworking clusters and Malaysia's emission standards enforcement add regulatory complexity across the region.
Thailand
Furniture exporters along the Eastern Economic Corridor and automotive acoustic foam buyers in Rayong province drive resin consumption. The Department of Industrial Works enforces effluent and air emission standards that elevate compliance costs for Bangkok industrial zone manufacturers. PTT Global Chemical anchors domestic supply through petrochemical corridor linkages serving captive laminate operations.
Vietnam
Millwork producers in Binh Duong and Dong Nai provinces expand decorative laminate consumption for export shipments. The country's Ministry of Industry and Trade monitors chemical imports affecting raw material access for independent formulators. Vietnamese furniture exporters are consolidating procurement through direct resin relationships rather than distributor channels.
Indonesia
Woodworking clusters around Surabaya and Jepara concentrate demand for particleboard binders and decorative laminates. The Ministry of Environment and Forestry implements hazardous substance controls that extend product registration timelines for imported melamine compounds. Local furniture manufacturers are responding by accelerating in-house resin production to circumvent import friction.
Malaysia
DSM-certified panel producers in the Klang Valley mandate reduced formaldehyde release binders for Commonwealth market access. The Department of Standards Malaysia administers product certification protocols that directly shape resin specifications for laminate suppliers. Stricter emission standards compress margins for commodity-grade suppliers while rewarding low-emission specialists.
Philippines
Construction-grade laminate demand from commercial interior projects in Metro Manila supplements regional consumption patterns. The country's national chemical regulator maintains separate hazardous substance classifications from neighboring ASEAN states. Emerging woodworking clusters in Cebu and Davao are developing localized procurement relationships with Thai and Vietnamese resin suppliers.
Southeast Asia Melamine Market Competitive Landscape
Thai producers anchor one tier through integrated petrochemical infrastructure; Malaysian and Japanese specialists hold specification-sensitive positions in low-emission formulations. The market structure concentrates upstream around urea-melamine integration while fragmenting downstream among laminate converters and automotive foam fabricators. Three archetypes dominate: integrated petrochemical conglomerates, regional chemical specialists with standards certification, and captive resin producers serving furniture exporters. Capacity expansion and backward integration into urea supply represent the dominant competitive moves.
Among Thai-based integrated producers, PTT Global Chemical exemplifies the petrochemical conglomerate archetype through corridor-linked supply security. Mitsui Chemicals Asia-Pacific Ltd represents Japanese regional specialists leveraging feedstock integration across ASEAN manufacturing zones. Petronas Chemicals Group Berhad occupies a position bridging Malaysian port logistics with Commonwealth market access. These three companies sit within distinct competitive tiers yet collectively shape upstream supply concentration.
| Leading Market Players |
|---|
| Mitsui Chemicals Asia-Pacific Ltd |
| PTT Global Chemical |
| Petronas Chemicals Group Berhad (PCG) |
| PT Chandra Asri Petrochemical |
| Formosa Chemicals & Fibre Corporation |
| Nissan Chemical Corporation |
| Wakomas Chemical Sdn. Bhd. |
| AICA Hatyai Co Ltd |
| Borealis Agrolinz Melamine GmbH |
| Others |
Value Network & Pricing Analysis
Malaysia's DSM certification mandate gates qualified supply and premium-tier pricing access, compressing margins for commodity-grade resin suppliers while rewarding low-emission specialists serving Commonwealth-bound furniture exports. This environmental standard reshapes procurement economics across the Thai-Vietnamese furniture corridor.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for standard-grade melamine-formaldehyde resins. Three-tier pricing structure across low-emission certified, industrial-grade, and commodity-economy levels dominates transaction structures. Price differentiation rests on DSM compliance status and captive integration depth. Cost compression in commodity binders is intensifying because urea-formaldehyde substitution pressure intensifies in particleboard applications. Domestic Vietnamese millwork producers show lowest price sensitivity due to backward integration; independent Indonesian formulators face acute margin pressure.
Supply Chain Analysis
DSM certification and Indonesian hazardous substance controls gate qualified supplier status across ASEAN manufacturing zones. Geographic supply concentration centers on Thailand, Vietnam, and Malaysia, with Thai petrochemical corridors anchoring upstream urea-melamine integration. Raw material dependencies draw from natural gas feedstocks, formaldehyde precursors, and specialized foaming agents for acoustic grades. Single-source vulnerability runs through Mitsui Chemicals Asia-Pacific and PTT Global Chemical's corridor-linked supply control. Distribution runs through direct long-term offtake agreements for captive laminate operations, with regional distributors serving fragmented independent converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's melamine market functions as a stable compounder, with furniture export growth and automotive localization providing steady demand expansion across the analysis window.
For Market Incumbents: Deploy backward integration into urea supply to defend feedstock cost positions against natural gas volatility in Thai petrochemical corridors. Incumbents should lock DSM-compliant formulation capacity ahead of Malaysian standards propagation, while consolidating distributor relationships in Indonesia's Surabaya-Jepara cluster before captive resin production displaces third-party procurement. For New Entrants and Emerging Players: DSM certification requirements in Malaysia open a window for low-emission resin specialists to capture specification premiums in Klang Valley panel production. Entrants should target Vietnamese automotive acoustic foam supply chains in Binh Duong and Dong Nai provinces, where direct resin relationships are displacing distributor channels. A technical partnership route with Indonesian woodworking clusters bypasses extended import registration timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional low-emission formulation specialists because certification fragmentation creates local moats against integrated petrochemical giants. Platform consolidation across DSM-compliant Malaysian suppliers and Vietnamese captive laminate operations offers long-term viability through standards-driven margin expansion. Watch for Indonesian Ministry of Environment and Forestry hazardous substance reclassification as inflection signal for import-dependent formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Urea Supply | PTT Global Chemical's corridor linkages demonstrate feedstock security against natural gas volatility. |
| DSM Certification Investment | Low-emission resin capacity captures specification premiums in Malaysian Commonwealth-bound furniture exports. |
| Captive Laminate Integration | Vietnamese millwork producers in Binh Duong displace third-party suppliers with in-house panel production. |
| Cross-Border Formulation Harmonization | Multi-jurisdictional product approvals create first-mover advantage amid divergent ASEAN chemical inventories. |
| Automotive Acoustic Foam Partnership | Thailand's Rayong vehicle assembly corridor sources melamine foam for NVH reduction specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with resin plant managers, furniture procurement leads at Vietnamese exporters, DSM certification officers, and automotive component buyers with secondary validation. Trade data from ASEAN customs databases, Department of Standards Malaysia certification records, petrochemical corridor output disclosures, and SEC filings from listed chemical conglomerates anchored volume estimates. Bottom-up resin consumption modeling triangulated against top-down furniture export value projections.
Historical reference periods spanning pre-pandemic baseline through recent supply chain normalization anchored the forecast window. Segmentation modeling addressed product type tiers, end-use industry concentration, captive versus merchant supply configurations, and regional regulatory cluster variations. CAGRs were derived through regression analysis of correlated industrial output indicators including furniture export volumes, vehicle assembly rates, and construction activity indices. Urea feedstock cost trajectories and formaldehyde emission standards evolution served as primary forecast sensitivity inputs.
Revisions become necessary when DSM certification scope expands beyond Malaysia, Indonesian hazardous substance reclassification accelerates, or Thai petrochemical corridor natural gas pricing experiences structural regime change. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and captive integration penetration rates. A model refresh is warranted upon material change in ASEAN furniture export demand or automotive acoustic foam specification adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Glass Ceramics Market
Ceramics
Earthenware Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Wollastonite Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Industrial Ceramics Market
Ceramics
Colloidal Alumina Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Cerium Carbonate Market
Ceramics
Titanium Carbide Market
Ceramics
China Ceramic Tiles Market
Ceramics
Calcium Oxide Market
Ceramics
Nanoceramic Powder Market