
 Japan Ceramic Tiles Market | 2026-2036
Japan Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Ceramic Tiles Market Foresight
Asset-light leasing arrangements for production kilns is tilting competitive dynamics toward mid-tier manufacturers with limited capital reserves. INAX Corporation leverages its vertical integration from clay sourcing through retail distribution to sustain margin control across the value chain. TOTO Ltd. anchors premium positioning through advanced glazing R&D, while Danto Tile Co. Ltd. specializes in region-specific textures that dominate rural prefectural markets.
Japan ceramic tiles are fired clay or porcelain slabs, typically measuring 300x300mm to 600x600mm, formed through pressing or extrusion and finished with glazes that achieve water absorption below 0.5% for exterior-grade products. These surfaces provide structural protection, thermal insulation, and aesthetic finishing for built environments across residential and commercial settings. Glazed tiles lead volume due to their stain resistance and design versatility in interior applications, while digital printing technology captures expanding share as architects demand custom surface replication of natural stone and wood grain. Floor applications generate the deepest margin pools, particularly in commercial specifications where slip-resistance ratings under JIS standards command premium positioning.
METI enforces building material energy standards that shape product development cycles, while JIS certification requirements govern dimensional tolerances and frost resistance for market access. The country's national construction regulator mandates seismic-safety compliance for heavy cladding systems, directly influencing thin-format tile innovation. Stakeholders must monitor evolving amendments to the Building Standards Act, as these will determine whether lightweight ceramic alternatives displace traditional stone in high-rise facades.
Market Dynamics
Residential renovation cycles in earthquake-prone prefectures are compressing replacement timelines for moisture-resistant surfacing, while METI energy-efficiency mandates force manufacturers to reformulate toward thinner, lighter clay bodies that reduce structural load.
Growth Catalysts
- Seismic retrofit mandates:Tokyo's Building Standards Act amendments accelerate cladding replacement in high-rise residential stock, pulling forward specification volumes for lightweight ceramic alternatives.
- Digital printing adoption:Architects specify custom surface replication of natural stone and wood grain, expanding addressable share against traditional materials in premium residential segments.
- Kanto urban densification:Tokyo's sustained redevelopment pipeline maintains consistent floor-area demand for commercial and institutional flooring specifications.
Market Restraints
- Energy cost volatility:Natural gas prices for tunnel kiln firing compress margin stability for producers without captive energy hedging arrangements.
- Clay deposit concentration:Domestic kaolin sourcing concentrates in specific prefectural basins, exposing supply continuity to localized geological or regulatory disruption.
- Thin-format technical limits:Sub-6mm tile bodies face frost-resistance certification gaps under JIS standards, restricting exterior vertical applications in northern prefectures.
Strategic Opportunities
- Rural prefectural penetration:Region-specific texture formulations for Hokkaido and Tohoku residential markets remain underdeveloped relative to Kanto saturation.
- Leasing-based kiln access:Asset-light production arrangements enable mid-tier manufacturers to scale capacity without fixed capital deployment.
- Building Standards Act tailwind:Pending amendments to seismic cladding rules may formally qualify lightweight ceramics for high-rise facade substitution against stone.
Industry Challenges
- Glaze formulation expertise scarcity:Specialized technicians for advanced digital inkjet glazing command premium compensation, constraining R&D throughput at smaller producers.
- JIS certification timeline compression:Frost-resistance and dimensional tolerance testing cycles extend product launch windows, delaying revenue recognition for new formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Ceramic Tiles Market |
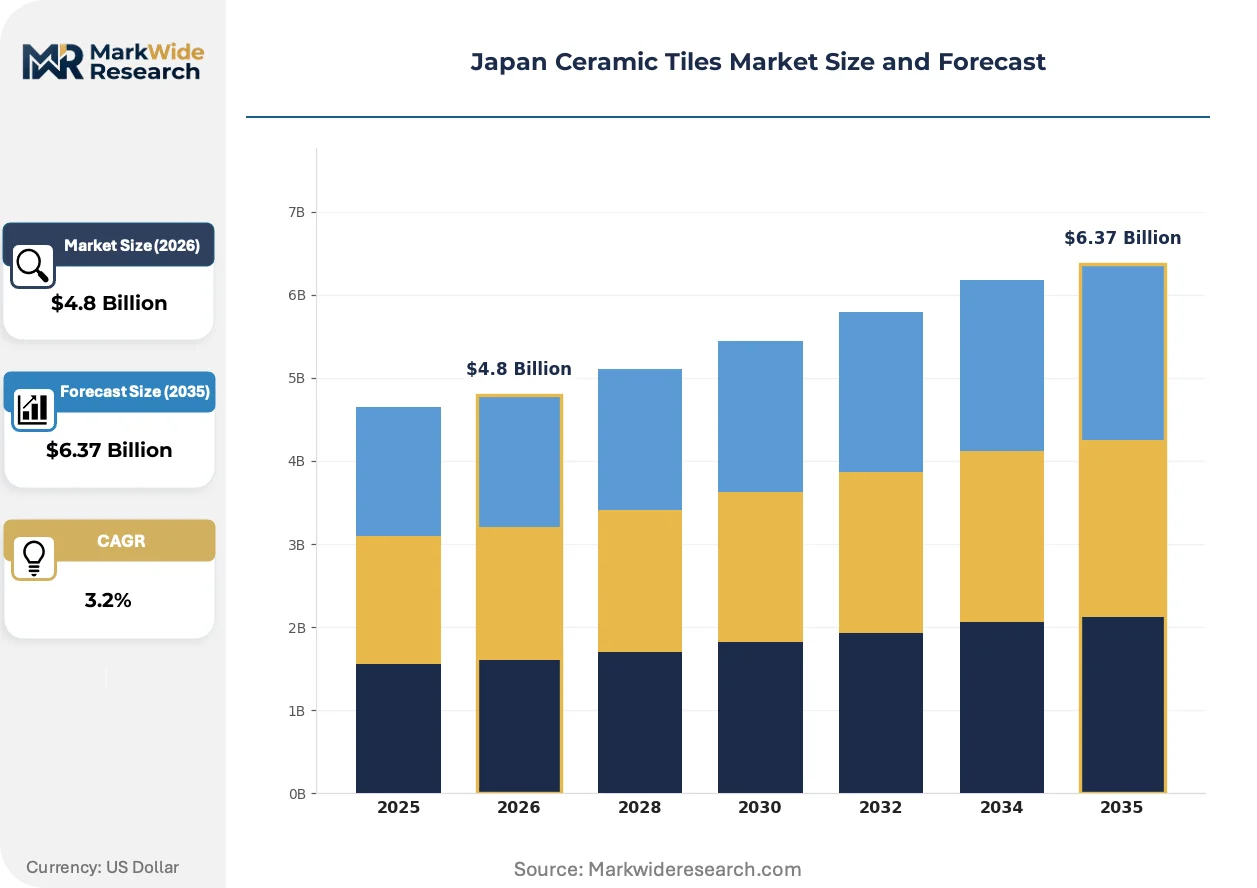
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Polished Tiles, Textured Tiles Application: Wall Applications, Floor Applications, Countertop Applications, Outdoor Applications End User: Residential, Commercial, Industrial, Institutional Technology: Digital Printing, Extrusion, Pressing, Slip Casting |
| Companies Covered | Danto Tile Co. Ltd., Nittai-Kogyo Co., Ltd., INAX Corporation, Yamase Co., Ltd., Nagoya Mosaic Industry, TOTO Ltd., ICOT RYOWA Co., Ltd., Asahi Glass Co., Ltd., Nitto Ceramics Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Ceramic Tiles Market Shifts & Advancements
Surface replication technology and regulatory pressure on building energy performance are converging to reshape specification behavior across Japan's architectural community.
Digital inkjet printing systems are digitizing the decorative layer application process, replacing traditional screen-printing methods with pixel-precise glaze deposition. Architectural firms in Tokyo and Osaka specify these surfaces for luxury residential lobbies and hospitality interiors, compressing the traditional 8-12 week custom order cycle to under 4 weeks. This capability is digitizing the competitive boundary between ceramic and natural stone, enabling tile producers to capture specification share previously reserved for quarried materials.
METI's energy-efficiency guidelines for building materials now explicitly reference embodied carbon in cladding selection criteria. Manufacturers reformulate body compositions toward recycled content and reduced firing temperatures to maintain specification eligibility for public sector projects. Prefectural governments in Kanto and Kansai regions have begun incorporating these standards into municipal tender requirements, accelerating adoption of thin-format, low-mass tile systems.
Consolidated purchasing by large-scale condominium developers is compressing supplier negotiation cycles and unbundling after-sales service from material supply contracts. Major Tokyo-based developers now contract directly with tile producers for bulk volume, displacing traditional distributor intermediaries in high-rise residential specifications. This pattern concentrates most visibly in the Kanto region, where single developers control multiple concurrent tower projects.
Japan Ceramic Tiles Market Segmentation
Tile specification in Japan diverges sharply across building typologies and regulatory exposure zones. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
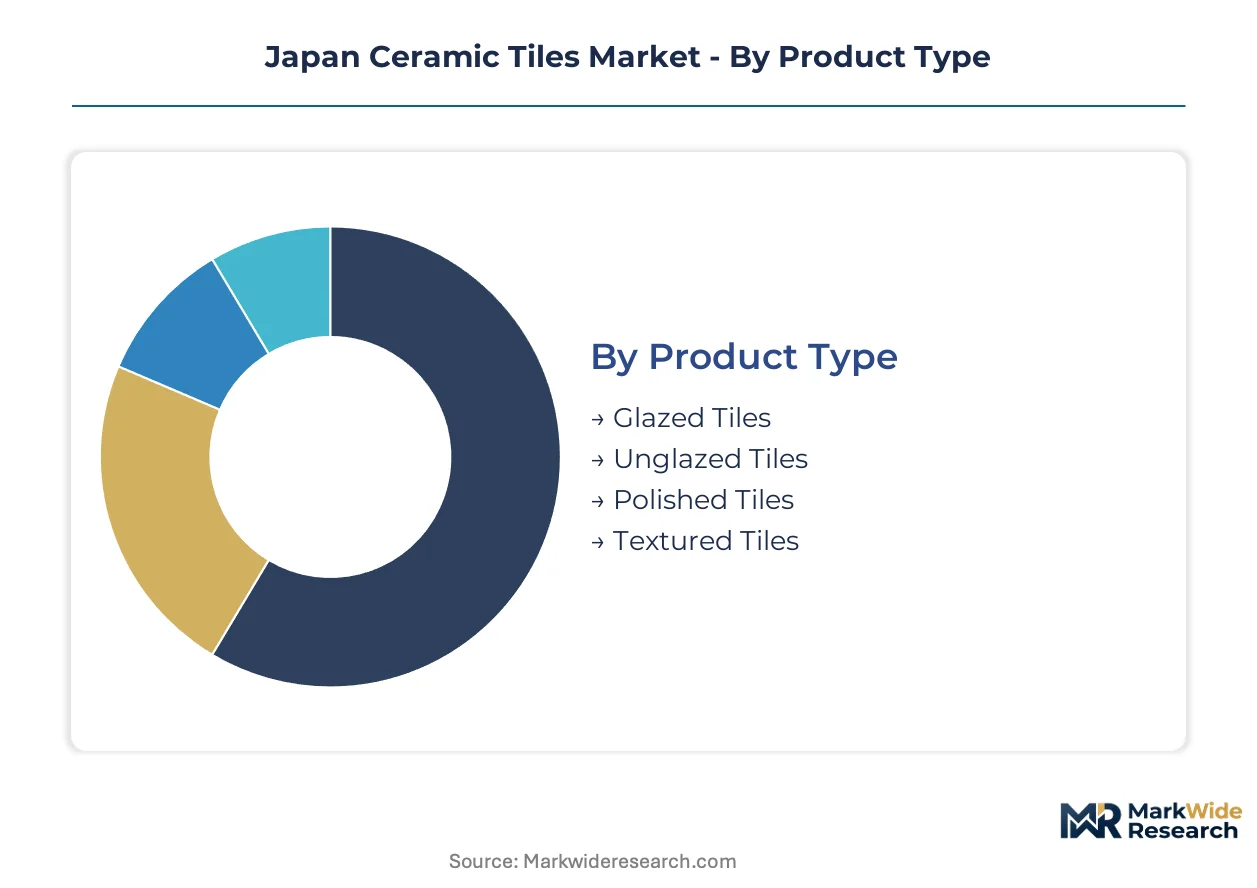
Product Type:
Cost tier differentiation separates premium-specified surfaces from commodity replacement cycles in Japan's renovation-driven market.
- Glazed Tiles:Vitreous surface coatings fired at high temperature create impermeable barriers against moisture intrusion. Residential bathrooms and kitchens in Tokyo's high-rise stock specify these surfaces for stain resistance and simplified maintenance protocols.
- Unglazed Tiles:Raw clay bodies retain natural porosity and slip-resistant texture without surface coating. Commercial flooring in Kansai logistics facilities and factory settings favors this format for abrasion tolerance under heavy mechanical load.
- Polished Tiles:Post-firing mechanical grinding achieves mirror-flat reflectivity suitable for premium interior specifications. Luxury hospitality lobbies in Osaka and luxury residential towers specify this finish.
- Textured Tiles:Surface relief patterns provide tactile variation and enhanced traction coefficients. Rural prefectural markets in Hokkaido favor these for residential entryways and exterior walkways.
Glazed tiles command the established base. The steepest expansion runs through polished tiles as premium residential specifications multiply.
Application:
Functional load requirements and JIS certification exposure create divergent margin profiles across installation surfaces.
- Floor Applications:Structural bearing surfaces require slip-resistance certification under JIS standards and compressive strength ratings for commercial load. Tokyo commercial specifications generate the deepest margin pools where anti-slip ratings command premium positioning.
- Wall Applications:Vertical cladding emphasizes lightweight attachment systems and seismic-safety compliance under Building Standards Act amendments. High-rise residential retrofit projects in Kanto drive specification volume for thin-format alternatives.
- Countertop Applications:Work surfaces demand chemical resistance and thermal shock tolerance for kitchen environments. Residential renovation segments in urban prefectures specify these for moisture protection.
- Outdoor Applications:Exterior exposure requires frost-resistance certification and UV-stable glazes under JIS protocols. Northern prefectures face technical gaps for sub-6mm formats in this category.
Floor applications anchor revenue concentration. Wall applications are climbing the fastest as seismic retrofit mandates accelerate.
End User:
Customer type determines procurement channel structure and after-sales service bundling in Japan's consolidated developer market.
- Residential:Single-family renovation and condominium replacement cycles dominate volume, with moisture-resistant specifications prioritized in earthquake-prone structures. Tokyo's dense urban redevelopment sustains consistent demand through large-scale developer purchasing.
- Commercial:Office, retail, and hospitality specifications emphasize design differentiation and durability under public traffic. Digital printing adoption concentrates in this segment for custom surface replication.
- Industrial:Manufacturing facilities and warehouses require chemical resistance and mechanical load tolerance. Unglazed formats capture share here for abrasion performance.
- Institutional:Schools, hospitals, and government buildings face METI energy-efficiency guidelines in material selection. Public sector tenders increasingly reference embodied carbon criteria.
Residential end users command the established base. Commercial specifications are gaining share fastest as digital printing capabilities expand.
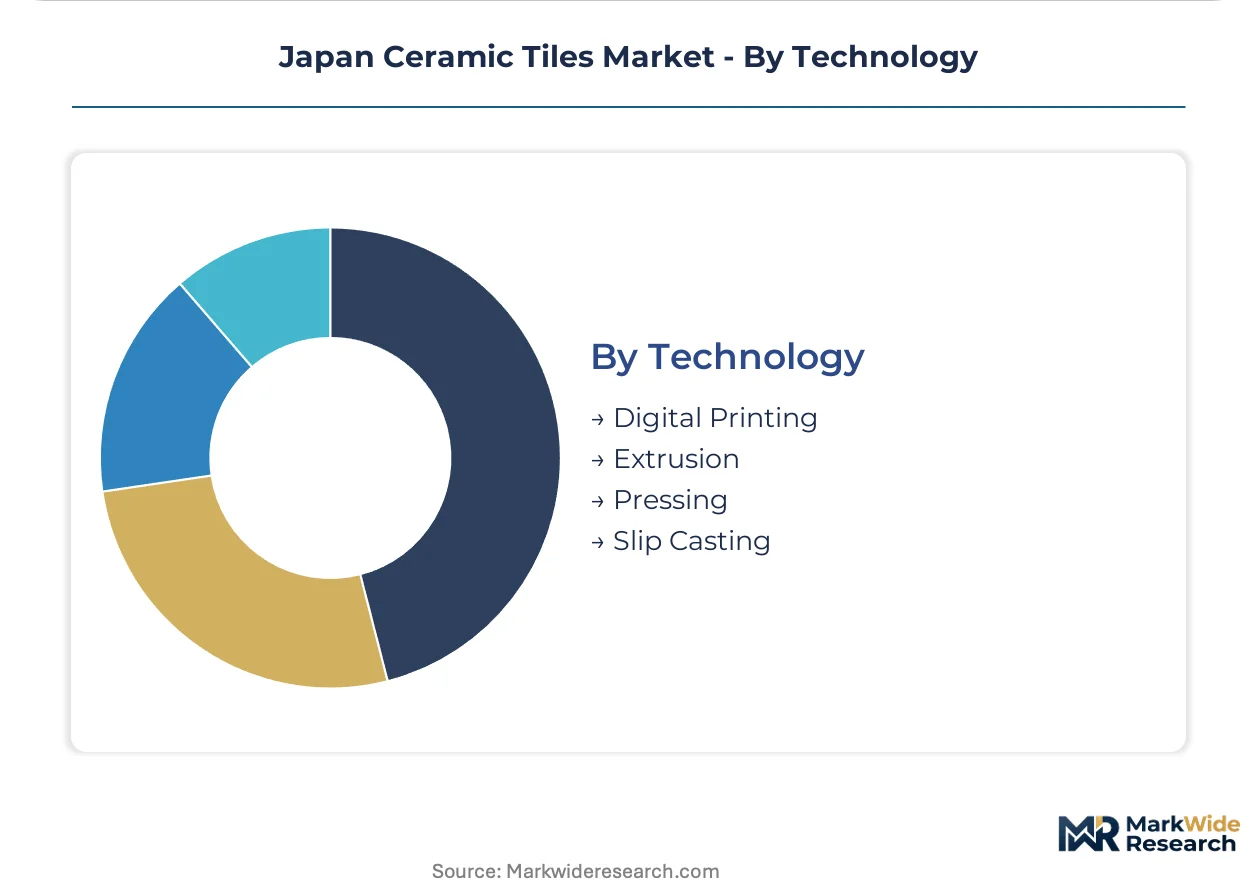
Technology:
Production method determines capital intensity, design flexibility, and regulatory compliance pathways for Japanese manufacturers.
- Digital Printing:Inkjet glaze deposition enables pixel-precise surface replication of natural materials with compressed order cycles. Architectural firms in Tokyo and Osaka specify this technology for luxury interiors and custom hospitality finishes.
- Pressing:Powder compaction in hydraulic presses produces uniform body density for standard-format tiles. High-volume residential applications rely on this established method for cost-efficient output.
- Extrusion:Continuous clay forming creates hollow profiles and specialized shapes for structural applications. Limited penetration in decorative surfacing.
- Slip Casting:Liquid clay pouring into plaster molds enables complex three-dimensional forms. Artisanal and specialized architectural elements utilize this labor-intensive approach.
Pressing technology commands the established base. Digital printing represents the steepest expansion trajectory as specification behavior shifts toward customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI energy-efficiency guidelines for building materials now explicitly reference embodied carbon in cladding selection criteria, accelerating specification shifts toward thin-format tile systems across Japan's prefectural construction markets.
Kanto/Tokyo
Tokyo's dense urban redevelopment sustains consistent floor-area demand for commercial and institutional flooring specifications. The Building Standards Act amendments accelerate cladding replacement in high-rise residential stock, pulling forward specification volumes for lightweight ceramic alternatives. Major developers in the Tokyo metropolitan area now contract directly with tile producers for bulk volume, displacing traditional distributor intermediaries.
Kansai/Osaka
Osaka's luxury hospitality sector specifies polished tiles and digitally printed surfaces for premium interior finishes. Commercial flooring in Kansai logistics facilities favors unglazed formats for abrasion tolerance under heavy mechanical load. The region's architectural firms specify custom surface replication of natural stone and wood grain, compressing traditional order cycles through digital printing adoption.
Chubu/Nagoya
Nagoya's manufacturing base generates industrial flooring demand for chemical-resistant and mechanically tolerant tile systems. Prefectural tender requirements increasingly incorporate METI energy-efficiency standards into municipal procurement. The region's tile producers supply standard-format pressed tiles for high-volume residential applications across central Japan.
Hokkaido
Rural prefectural markets in Hokkaido favor textured tiles for residential entryways and exterior walkways. Sub-6mm tile bodies face frost-resistance certification gaps under JIS standards, restricting exterior vertical applications in northern prefectures. Region-specific texture formulations for Hokkaido residential markets remain underdeveloped relative to Kanto saturation.
Tohoku
Earthquake-prone structures in Tohoku prefectures compress replacement timelines for moisture-resistant surfacing. Residential renovation cycles prioritize seismic-safety compliance and structural load reduction through lighter clay bodies. Local distributors maintain stronger channel presence here than in consolidated Kanto markets.
Japan Ceramic Tiles Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive clay sourcing and direct developer relationships, while mid-tier producers exploit asset-light kiln leasing to scale without fixed capital deployment. Three archetypes dominate: premium-positioned R&D specialists, region-focused texture formulators, and scale-driven standard-format suppliers. Competitive moves concentrate on backward integration into raw material basins and direct contracting with large-scale condominium developers.
Within the premium-tier vector, TOTO Ltd. and INAX Corporation exemplify integrated manufacturers controlling value chain stages from clay extraction through retail distribution. Danto Tile Co. Ltd. occupies a position among region-focused specialists tailoring surface formulations to prefectural aesthetic preferences. These three anchors illustrate how competitive positioning separates R&D-driven premium capture from scale efficiency and regional customization.
| Leading Market Players |
|---|
| Danto Tile Co. Ltd. |
| Nittai-Kogyo Co., Ltd. |
| INAX Corporation |
| Yamase Co., Ltd. |
| Nagoya Mosaic Industry |
| TOTO Ltd. |
| ICOT RYOWA Co., Ltd. |
| Asahi Glass Co., Ltd. |
| Nitto Ceramics Co. Ltd. |
| Others |
Supply & Pricing Matrix
The Seto Inland Sea freight corridor carries kaolin shipments from domestic clay basins to Kanto manufacturing clusters, and its volatile bunker fuel costs compress margin stability for producers without captive sourcing arrangements while amplifying price spreads between JIS-certified premium grades and standard-format commodity tiles.
Pricing Analysis
Certification level under JIS A 5209 creates the primary spread between premium frost-resistant exterior grades and interior commodity specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by glaze complexity and slip-resistance ratings, with Tokyo commercial flooring commanding the widest premiums. Cost compression in standard pressed tiles is intensifying because consolidated developer purchasing unbundles after-sales service from material contracts. Small-scale renovation contractors in rural prefectures exhibit the highest price sensitivity, while major condominium developers in Kanto prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control regimes on digital inkjet printing heads limit technology flows to Japanese manufacturers, constraining decorative layer capabilities for mid-tier producers without licensed equipment partnerships. Clay sourcing concentrates in domestic Shigaraki and Seto basins, with supplementary feldspar draws from India and Thailand. Natural gas dependency for tunnel kiln firing creates single-source vulnerability to commodity price spikes. Distribution runs through manufacturer-direct contracting with large-scale developers in urban corridors, displacing traditional wholesaler networks in consolidated Kanto markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic retrofit mandates and digital printing adoption are reshaping specification behavior, creating a high-growth disruption window as architects abandon natural stone for lightweight ceramic alternatives with compressed order cycles.
For Market Incumbents: Build captive clay sourcing moats through basin acquisition or long-term offtake agreements with Shigaraki deposit operators. Deepen backward integration into glaze formulation R&D to defend against digital printing specialists capturing premium hospitality specifications. METI energy-efficiency amendments threaten to disqualify traditional heavy-body formats from public sector tenders, making thin-format certification investment the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Hokkaido and Tohoku textured tile segments where region-specific surface formulations remain underdeveloped relative to Kanto saturation. Target rural prefectural renovation contractors through distributor partnerships that bundle technical support with material supply, exploiting the service gap left by consolidated urban direct contracting. Leasing-based kiln access enables asset-light capacity scaling without fixed capital deployment against entrenched integrated manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital printing equipment specialists and thin-format body innovators over legacy pressed-tile scale operators. Long-term viability hinges on specification share in seismic retrofit-driven high-rise residential cladding, where JIS certification timelines create barriers to rapid competitive entry. Watch for Building Standards Act amendment finalization as the signal for accelerated lightweight ceramic substitution against stone facades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Basins | Captive Shigaraki kaolin supply secures margin control against deposit concentration risk. |
| Digital Printing Technology Licensing | Inkjet glaze deposition capabilities capture architect-specified custom surface replication orders. |
| Thin-Format JIS Certification Investment | Sub-6mm frost-resistance approval unlocks exterior vertical applications in northern prefectures. |
| Direct Developer Contracting Expansion | Bypassing distributor intermediaries concentrates volume with Tokyo metropolitan area condominium builders. |
| Region-Specific Texture Formulation R&D | Hokkaido and Tohoku residential preferences create differentiation against Kanto-standardized competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including ceramic plant managers, architectural specification consultants at Tokyo and Osaka firms, prefectural government procurement officers, and distributor channel partners in rural Tohoku markets. Secondary validation drew from METI building materials statistics, JIS certification registry databases, customs trade records for feldspar imports, and municipal tender documentation from Kanto and Kansai regional governments. Bottom-up volume modeling triangulated against top-down construction floor-area forecasts.
Calibration anchored segment-level projections to historical replacement cycle patterns and regulatory amendment timelines without specifying discrete years. The analytical framework modeled product type, application surface, end-user category, and production technology dimensions across the analysis window. CAGRs derived from regression of renovation expenditure trends against seismic retrofit policy implementation phases, with digital printing adoption curves and METI embodied carbon guideline compliance serving as industry-specific demand shapers.
Sensitivities concentrate around Building Standards Act amendment finalization timing, natural gas price volatility for kiln operations, and JIS certification timeline compression for novel thin formats. Forecasts reflect documented assumptions regarding urban densification continuity and developer consolidation patterns. Material shifts in seismic cladding regulatory qualification or breakthroughs in sub-6mm frost-resistance formulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Pigments Market
Ceramics
Earthenware Market
Ceramics
Fire Clay Market
Ceramics
Glass Ceramics Market
Ceramics
Ceramic Frit Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Refractories Market
Ceramics
Global Alumina Market
Ceramics
Calcined Alumina Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Ceramic Kilns Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Advanced Ceramic Additives Market