
 Polymer-Derived Ceramics Market | 2026-2036
Polymer-Derived Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer-Derived Ceramics Market Outlook
Ultra-high-temperature specification grades above 1,600°C is unwinding competitive dynamics across the value chain. COI Ceramics leverages proprietary polymer infiltration and pyrolysis cycles to dominate defense-aerospace qualification pipelines. Ultramet sustains captive precursor synthesis capabilities that anchor its position in satellite propulsion thrusters. Kyocera competes through integrated silicon carbide powder-to-part manufacturing scale that extends across Japanese and North American supply nodes.
Polymer-derived ceramics are advanced ceramic materials synthesized through the controlled pyrolysis of preceramic polymers, typically yielding near-stoichiometric silicon carbide or silicon nitride with residual carbon contents below 2 wt% and porosity levels tunable between 5% and 40% depending on precursor architecture and processing atmosphere. These materials serve primarily as lightweight, oxidation-resistant structural components in environments where metallic alloys experience creep or accelerated corrosion. Silicon carbide product grades occupy the largest volume position due to established supply chains and broad aerospace applicability, while silicon nitride segments attract premium positioning for biomedical implant applications where fracture toughness exceeds 7 MPa·m½. Additive manufacturing technology channels are expanding fastest as direct ink writing and vat photopolymerization of preceramic resins enable geometrically complex cooling architectures previously inaccessible through conventional sintering or machining routes.
FAA airworthiness certification requirements for ceramic matrix composites in commercial propulsion systems shape qualification timelines and testing expenditure burdens for new entrants. EPA emissions standards and REACH precursor chemical registrations in Europe constrain precursor formulation choices and cross-border material shipments. The EU Green Deal industrial decarbonization framework creates additional compliance layers for energy-intensive pyrolysis operations. Stakeholders must monitor evolving FAA-EASA harmonization on ceramic damage tolerance protocols and decide whether to absorb qualification costs in-house or partner with established Tier-1 aerostructures suppliers holding existing design authority.
Market Dynamics
Ultra-high-temperature specification grades above 1,600°C are concentrating procurement authority among defense primes and NASA centers, compressing qualification timelines and reshaping supplier-tier relationships across the value chain.
Growth Catalysts
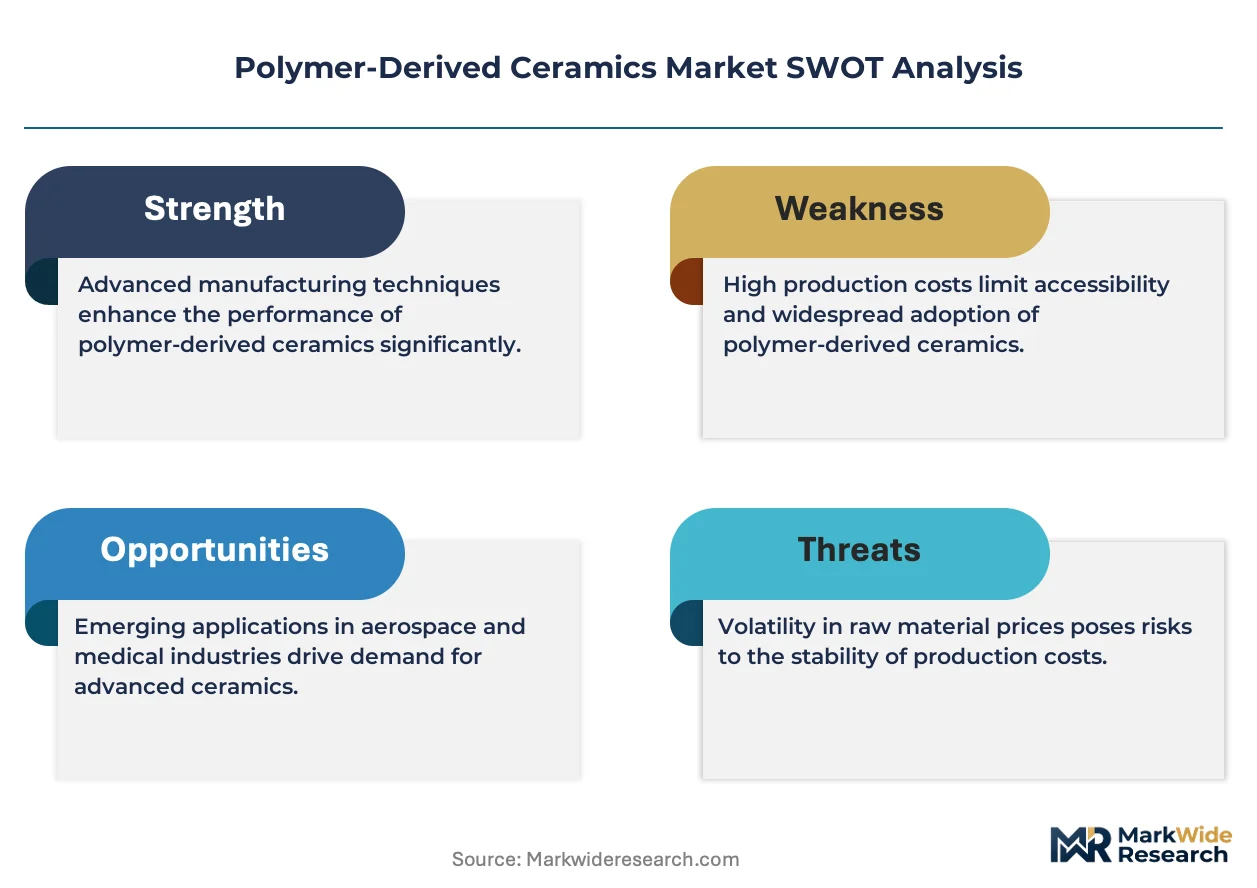
- EPA emissions standards:Aircraft propulsion regulations are accelerating ceramic matrix composite adoption over metallic alloys in hot-section components.
- Satellite propulsion thrusters:Miniaturized spacecraft architectures are driving demand for lightweight silicon carbide structural elements.
- Biomedical implant applications:Fracture toughness specifications exceeding 7 MPa·m½ are pulling silicon nitride grades into orthopedic device supply chains.
Market Restraints
- Precursor chemical volatility:Organosilicon monomer supply concentrates among specialty chemical producers in Germany and Japan, exposing formulators to input cost swings.
- REACH registration burdens:European precursor shipments face extended compliance timelines and toxicity documentation requirements that constrain cross-border material flows.
- Metallic alloy substitution:Nickel-based superalloys retain cost advantages in sub-1,200°C applications, limiting ceramic penetration in commercial aviation mid-temperature zones.
Strategic Opportunities
- India defense modernization:Indigenous hypersonic vehicle programs are creating qualification pathways for domestic polymer-derived ceramic suppliers.
- Additive manufacturing convergence:Direct ink writing of preceramic resins is unlocking geometrically complex cooling architectures previously inaccessible through conventional routes.
- EU Green Deal industrial decarbonization:Pyrolysis energy intensity is attracting green hydrogen substitution incentives that could reshape process economics for European producers.
Industry Challenges
- FAA-EASA harmonization gaps:Divergent damage tolerance protocols for ceramic matrix composites are forcing redundant testing expenditure on dual-certification programs.
- Precursor synthesis skill scarcity:Organometallic chemistry expertise concentrates among aging specialist workforces in Japan and the United States, constraining talent pipeline expansion.
- Pyrolysis furnace capacity bottlenecks:Inert atmosphere processing equipment requires seven-figure capital commitments with 24-month lead times, compressing new entrant scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer-Derived Ceramics Market |
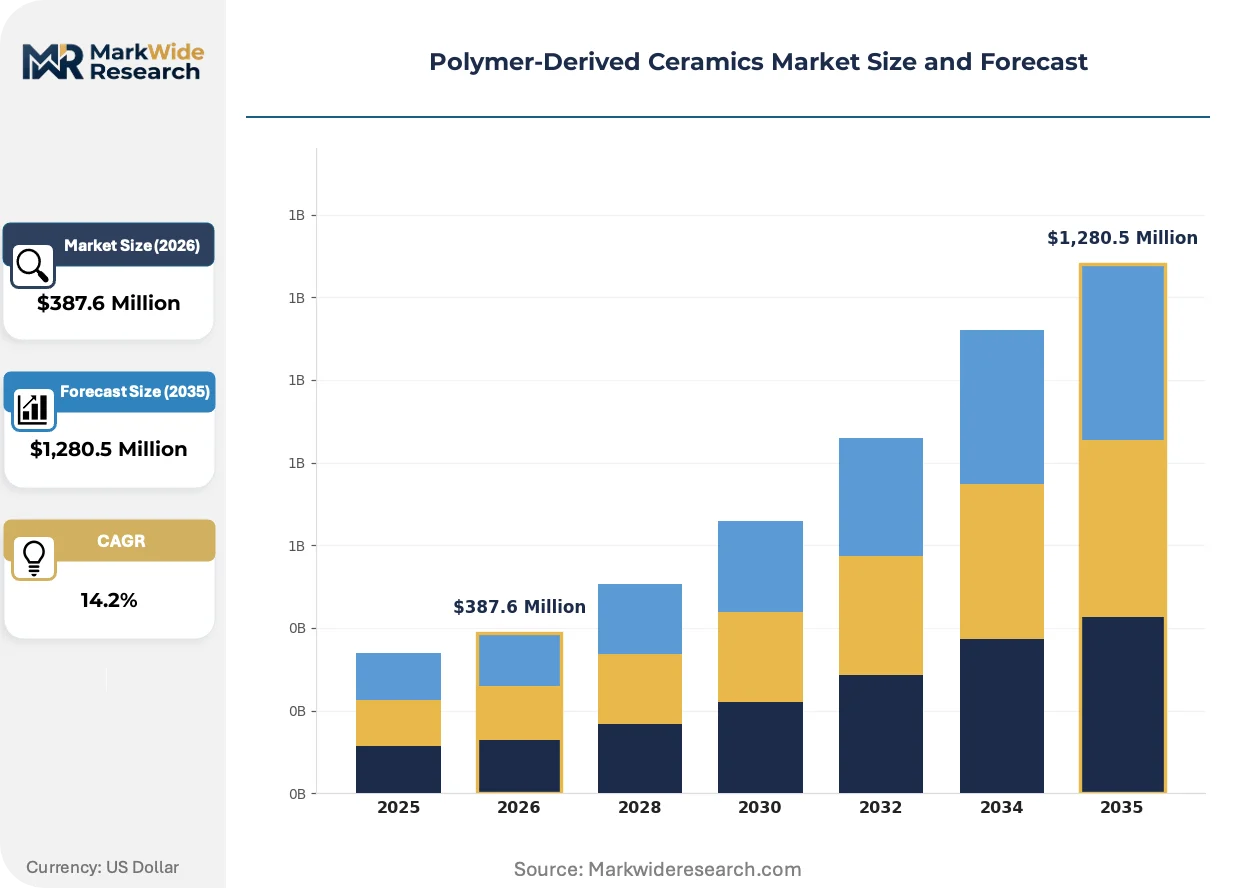
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Silicon Nitride, Zirconia, Alumina Application: Aerospace, Electronics, Biomedical, Defense End User: Manufacturers, Research Institutions, Aerospace Companies, Medical Device Producers Technology: Additive Manufacturing, Sintering, Casting, Machining |
| Companies Covered | COI Ceramics, Ultramet, CeramTec, 3M, Pyromeral Systems, Ube Industries, Hitachi Chemical, CoorsTek, KYOCERA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer-Derived Ceramics Market Strategic Shifts
Process innovation and regulatory harmonization pressures are actively restructuring how polymer-derived ceramics move from precursor formulation to qualified aerospace components.
Additive manufacturing of preceramic resins is fragmenting traditional supply chain hierarchies. Direct ink writing and vat photopolymerization enable geometrically complex cooling architectures without conventional machining constraints. Satellite propulsion thruster manufacturers are adopting these channels fastest, compressing supplier tiers by bringing shape-forming in-house.
REACH precursor chemical registrations in Europe are constraining formulation choices and cross-border material shipments. The EU Green Deal industrial decarbonization framework adds compliance layers for energy-intensive pyrolysis operations. Formulators serving dual US-European supply chains are consolidating precursor portfolios to minimize registration duplication costs.
Defense prime procurement patterns are compressing supplier qualification cycles. Tier-1 aerostructures suppliers with existing FAA design authority are absorbing testing burdens from smaller ceramic specialists. This consolidation is most visible in United States aerospace clusters, where NASA thermal protection system programs anchor multi-year offtake commitments.
Polymer-Derived Ceramics Market Segmentation
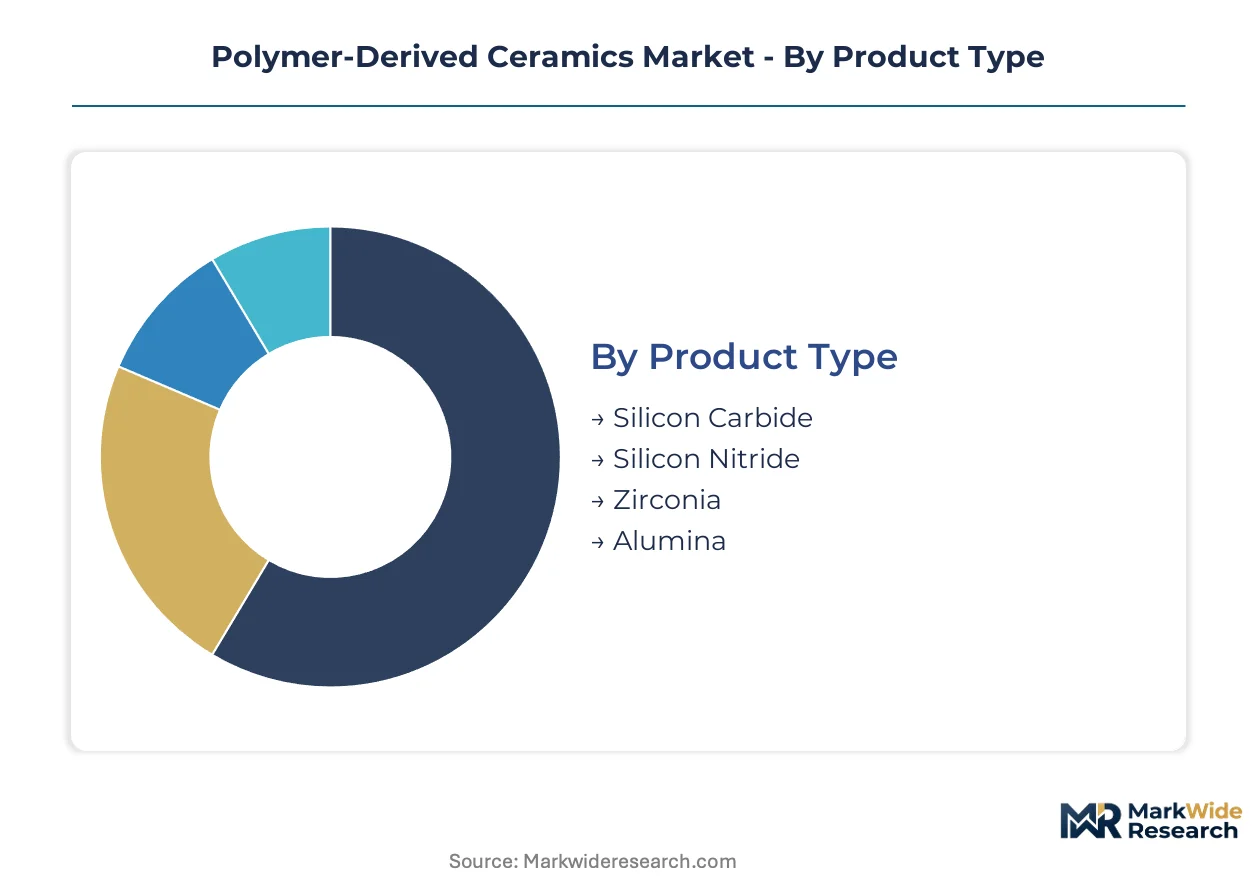
Polymer-derived ceramics exhibit divergent value capture patterns across product chemistry, processing route, and end-use qualification burden. Segment boundaries reflect where technical specifications, regulatory thresholds, and capital intensity concentrate margin pools.
Product Type:
Margin pools concentrate in near-stoichiometric compositions where residual carbon control below 2 wt% commands aerospace qualification premiums.
- Silicon Carbide:Near-stoichiometric SiC dominates volume through established polymer infiltration and pyrolysis supply chains. Aerospace engine manufacturers in the United States anchor procurement for hot-section components exceeding 1,600°C service temperatures, with EPA emissions standards accelerating displacement of nickel-based superalloys.
- Silicon Nitride:Fracture toughness exceeding 7 MPa·m½ positions this grade in biomedical implants where orthopedic device producers specify oxidation resistance and biocompatibility. Japanese and German precursor suppliers capture value through proprietary organosilicon monomer formulations.
- Zirconia:Transformation-toughened variants serve dental and structural electronics applications where thermal shock resistance matters.
- Alumina:Cost-competitive oxide ceramics penetrate industrial wear components and electrical insulators with less stringent purity requirements.
The dominant share belongs to Silicon Carbide, while Silicon Nitride is closing the gap fastest.
Application:
Application segmentation tracks where qualification timelines and testing expenditure burdens create defensible supplier positions.
- Aerospace:FAA airworthiness certification for ceramic matrix composites in commercial propulsion systems imposes multi-year qualification cycles. NASA thermal protection system programs in the United States anchor multi-year offtake commitments that compress supplier-tier relationships.
- Defense:Hypersonic vehicle programs in India and the United States concentrate procurement authority among primes demanding ultra-high-temperature grades above 1,600°C.
- Electronics:Semiconductor processing equipment and substrate applications drive demand for high-purity silicon carbide with tunable porosity between 5% and 40%.
- Biomedical:Orthopedic implant specifications pull silicon nitride into spinal fusion and joint replacement devices where metallic ion release concerns favor ceramic alternatives.
Aerospace commands the largest revenue pool, though Defense applications are expanding most quickly through hypersonic procurement acceleration.
End User:
End user segmentation reveals where design authority and captive processing capabilities reshape procurement patterns.
- Aerospace Companies:Tier-1 aerostructures suppliers with existing FAA design authority absorb testing burdens from smaller ceramic specialists, consolidating supplier relationships in United States clusters.
- Medical Device Producers:Orthopedic OEMs specify fracture toughness and biocompatibility thresholds that favor silicon nitride grades, with REACH registration burdens in Europe constraining precursor sourcing flexibility.
- Manufacturers:Industrial component fabricators prioritize cost-competitive alumina and zirconia grades for wear and thermal management applications.
- Research Institutions:NASA centers and defense laboratories anchor qualification programs for next-generation thermal protection systems, creating technology pull-through for commercial adoption.
Aerospace Companies retain the dominant procurement volume, while Medical Device Producers are gaining share fastest through orthopedic ceramic adoption.
Technology:
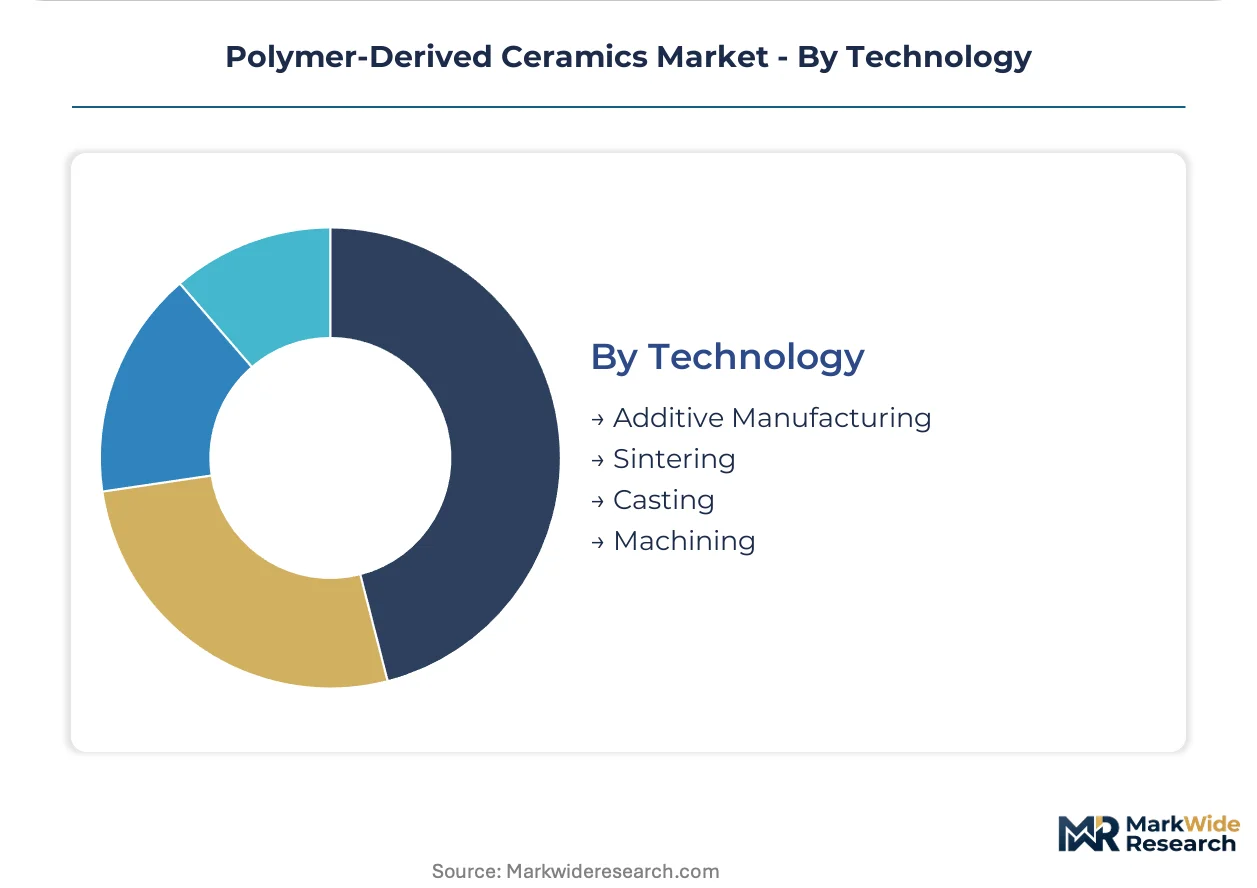
Technology segmentation tracks where geometric complexity and energy intensity alter competitive economics.
- Additive Manufacturing:Direct ink writing and vat photopolymerization of preceramic resins enable cooling architectures previously inaccessible through conventional routes. Satellite propulsion thruster manufacturers in the United States adopt these channels fastest, compressing supplier tiers by bringing shape-forming in-house.
- Sintering:Conventional pressureless and hot isostatic pressing routes retain cost advantages in high-volume silicon carbide production for established aerospace programs.
- Machining:Diamond grinding and ultrasonic machining of pyrolyzed ceramics persists where tight dimensional tolerances exceed as-formed capabilities.
- Casting:Preceramic polymer infiltration into fiber preforms remains foundational for ceramic matrix composite fabrication in defense applications.
Sintering retains the dominant installed base, while Additive Manufacturing is climbing the fastest as satellite and hypersonic programs demand geometric complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of organosilicon precursors concentrate in Germany and Japan, while import dependence shapes qualification strategies in defense-aerospace clusters across the United States, India, and Western Europe.
United States
NASA thermal protection system programs and hypersonic vehicle procurement anchor demand for ultra-high-temperature grades above 1,600°C. FAA airworthiness certification requirements impose multi-year qualification timelines for ceramic matrix composites in commercial propulsion. Huntsville, Alabama and the broader Ohio aerospace corridor concentrate defense prime procurement authority.
Germany
Specialty chemical producers in the Rhine-Ruhr region dominate organosilicon monomer supply for preceramic polymer formulation. REACH registration burdens constrain cross-border precursor shipments and extend compliance timelines for toxicity documentation. Bavaria's industrial ceramics cluster integrates polymer infiltration capabilities with automotive and aerospace supply chains.
Japan
Organometallic chemistry expertise concentrates among aging specialist workforces in Osaka and Nagoya, constraining talent pipeline expansion for precursor synthesis. METI industrial policy supports silicon carbide powder-to-part manufacturing scale across Kyocera's integrated supply nodes. Yokohama-based research institutions anchor qualification programs for next-generation thermal protection materials.
India
Indigenous hypersonic vehicle programs under the DRDO create qualification pathways for domestic polymer-derived ceramic suppliers. BIS standards development for advanced ceramics lags defense procurement timelines, forcing reliance on imported qualification data. Bengaluru and Hyderabad defense laboratories concentrate materials characterization infrastructure.
France
Safran and ArianeGroup procurement patterns compress supplier qualification cycles for satellite propulsion thruster components. ANSM chemical safety evaluations add compliance layers for preceramic resin formulations used in biomedical applications. The Toulouse aerospace cluster absorbs testing burdens from smaller ceramic specialists through Tier-1 aerostructures partnerships.
Polymer-Derived Ceramics Market Competitive Environment
Listed leaders compete with private specialists across defense-aerospace qualification pipelines, creating a tiered structure where public companies leverage capital access for furnace capacity expansion while private firms retain agility in precursor formulation. The vendor base separates into three strategic archetypes: integrated powder-to-part manufacturers, captive precursor synthesizers, and additive manufacturing technology developers. Consolidation pressure operates through defense prime procurement concentration and Tier-1 aerostructures partnerships that absorb testing burdens from smaller specialists.
Within the integrated manufacturing tier, KYOCERA exemplifies scale-driven positioning through silicon carbide operations spanning Japanese and North American supply nodes. COI Ceramics and Ultramet occupy specialist positions in defense-aerospace qualification pipelines, with the former representing proprietary polymer infiltration capabilities and the latter anchoring captive precursor synthesis for satellite propulsion applications. CeramTec and CoorsTek sit within the technical ceramics fabricator archetype, leveraging existing customer relationships in industrial and biomedical segments.
| Leading Market Players |
|---|
| COI Ceramics |
| Ultramet |
| CeramTec |
| 3M |
| Pyromeral Systems |
| Ube Industries |
| Hitachi Chemical |
| CoorsTek |
| KYOCERA |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between defense primes and polymer-derived ceramic suppliers lock in pyrolysis furnace capacity and freeze input cost visibility for multi-year NASA thermal protection system programs. These arrangements concentrate pricing power among established Tier-1 aerostructures partners while exposing smaller formulators to organosilicon monomer volatility from German and Japanese specialty chemical producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across aerospace qualification grade, volume commitment tier, and REACH registration status. Price differentiation separates FAA-certified ceramic matrix composites from industrial-grade silicon carbide, with cost compression in the latter tier intensifying due to nickel-based superalloy substitution pressure. Medical device producers exhibit lowest price sensitivity, prioritizing fracture toughness specifications above 7 MPa·m½ for silicon nitride implants.
Supply Chain Analysis
Germany and Japan anchor organosilicon monomer production for preceramic polymer formulation, with the Rhine-Ruhr region and Osaka-Nagoya corridor feeding global defense-aerospace supply chains. Raw material dependencies center on chlorosilane precursors, high-purity silicon metal, and specialty polymerization catalysts. Single-source vulnerability concentrates in pyrolysis furnace fabrication, where seven-figure capital equipment draws from limited inert atmosphere processing specialists. Distribution runs through defense prime procurement offices and Tier-1 aerostructures partnerships that absorb qualification testing burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-derived ceramics constitute a high-growth materials disruption propelled by EPA emissions standards accelerating ceramic matrix composite displacement of metallic alloys in aircraft propulsion. The convergence of additive manufacturing with preceramic resin formulation is fragmenting traditional supply hierarchies and opening new qualification pathways.
For Market Incumbents: Compound captive precursor synthesis capabilities to defend against organosilicon monomer supply volatility from German and Japanese specialty chemical producers. Expand pyrolysis furnace capacity in United States defense-aerospace clusters to capture NASA thermal protection system procurement concentration. Lock in long-term offtake structures with Tier-1 aerostructures suppliers holding existing FAA design authority. For New Entrants and Emerging Players: FAA certification fast-tracks through partnerships with established aerostructures suppliers offer the most penetrable entry vector for commercial propulsion applications. Target biomedical implant segments where silicon nitride fracture toughness specifications exceed 7 MPa·m½ and orthopedic OEMs seek ceramic alternatives to metallic ion release concerns. Pursue additive manufacturing technology licensing as a go-to-market angle for satellite propulsion thruster manufacturers demanding geometrically complex cooling architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive precursor synthesizers with integrated pyrolysis capabilities and multi-year defense prime contracts. Across a five-to-ten year viability window, acquisition targets should demonstrate established polymer infiltration and pyrolysis cycles with active qualification pipelines. The signal to watch is FAA-EASA harmonization progress on ceramic damage tolerance protocols, which would compress redundant testing expenditure and accelerate commercial adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive organosilicon monomer production insulates against REACH registration burdens and German-Japanese supply concentration. |
| Additive Manufacturing Technology Licensing | Direct ink writing of preceramic resins unlocks geometrically complex cooling architectures for satellite propulsion thrusters. |
| Long-term Supply Agreement with Defense Primes | Multi-year NASA thermal protection system commitments anchor furnace capacity utilization and compress supplier-tier relationships. |
| Green Manufacturing Transition | EU Green Deal hydrogen substitution incentives reshape pyrolysis energy economics for European polymer-derived ceramic producers. |
| Joint Venture with Tier-1 Aerostructures Suppliers | Partnerships with FAA design authority holders absorb qualification testing burdens from smaller ceramic specialists. |
Study Parameters
Cross-validation between primary interviews with defense procurement officers, ceramic matrix composite engineers, preceramic polymer formulators, and REACH compliance specialists anchors the qualitative findings. Secondary validation draws from FAA airworthiness certification databases, EPA emissions standard filings, ECHA precursor registration records, and SEC disclosures from listed technical ceramics manufacturers. Bottom-up segment sizing triangulates against top-down aerospace and defense spending projections.
Sensitivity analysis around pyrolysis furnace capacity expansion timelines and organosilicon monomer price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, processing route technology, end-use qualification burden, and regional regulatory cluster. CAGRs derive from installed base growth in aerospace engine hot-section components and satellite propulsion miniaturization trends. Industry-specific forecast inputs incorporate hypersonic vehicle program procurement acceleration and biomedical implant ceramic adoption curves.
Underlying assumptions cover sustained EPA emissions standard enforcement, stable REACH precursor registration pathways, and continued FAA-EASA regulatory divergence, with deviation risk concentrated in pyrolysis energy cost inflation and defense budget reallocation. Recalibration cycles align with material shifts in ceramic matrix composite airworthiness certification timelines and additive manufacturing technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Optical Ceramics Market
Ceramics
Global Industrial Clay Market
Ceramics
Europe Activated Alumina Market
Ceramics
Spain Ceramic Tiles Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
China Clay Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Global Ceramic Foams Market
Ceramics
Calcium Silicate Market
Ceramics
Global Functional Ceramics Market
Ceramics
Advanced Ceramics Market
Ceramics
United States Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Calcined Alumina Market
Ceramics
Ceramic Setter Plate Market