
 Taiwan Ceramic Tiles Market | 2026-2036
Taiwan Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Ceramic Tiles Market Analytics
CNS 11267 ceramic tile quality certification is bifurcating the competitive landscape into qualified suppliers and marginal producers. Champion Building Materials leverages its vertically integrated kiln operations to sustain consistent CNS-grade output across northern Taiwan manufacturing bases. White Horse Ceramic differentiates through specialized glaze R&D, occupying the premium architectural specification channel where designers demand custom color matching. Ho Long Ceramic anchors the mid-market residential segment with standardized floor tile formats distributed through Taichung-area builder networks.
Ceramic tiles are fired clay-based surfacing materials, typically measuring 300x300mm to 600x1200mm, engineered for moisture resistance, abrasion tolerance, and aesthetic finish in built environments. Porcelain segments command the strongest margin pools due to higher density requirements and frost-resistance specifications that filter out lower-tier producers. Residential end users currently lead volume absorption, though commercial contracting channels are expanding fastest as Taipei retail and hospitality developers specify large-format slabs for accelerated installation timelines.
Taiwan's Bureau of Energy green building material standards and CNS 11267 compliance requirements shape product development cycles and procurement eligibility for public infrastructure projects. The Ministry of Economic Affairs enforces industrial emissions protocols that raise capital barriers for kiln modernization, effectively consolidating production capacity among established operators. Stakeholders must monitor evolving carbon-intensity thresholds and their impact on export competitiveness against mainland Chinese and Southeast Asian supply alternatives.
Market Dynamics
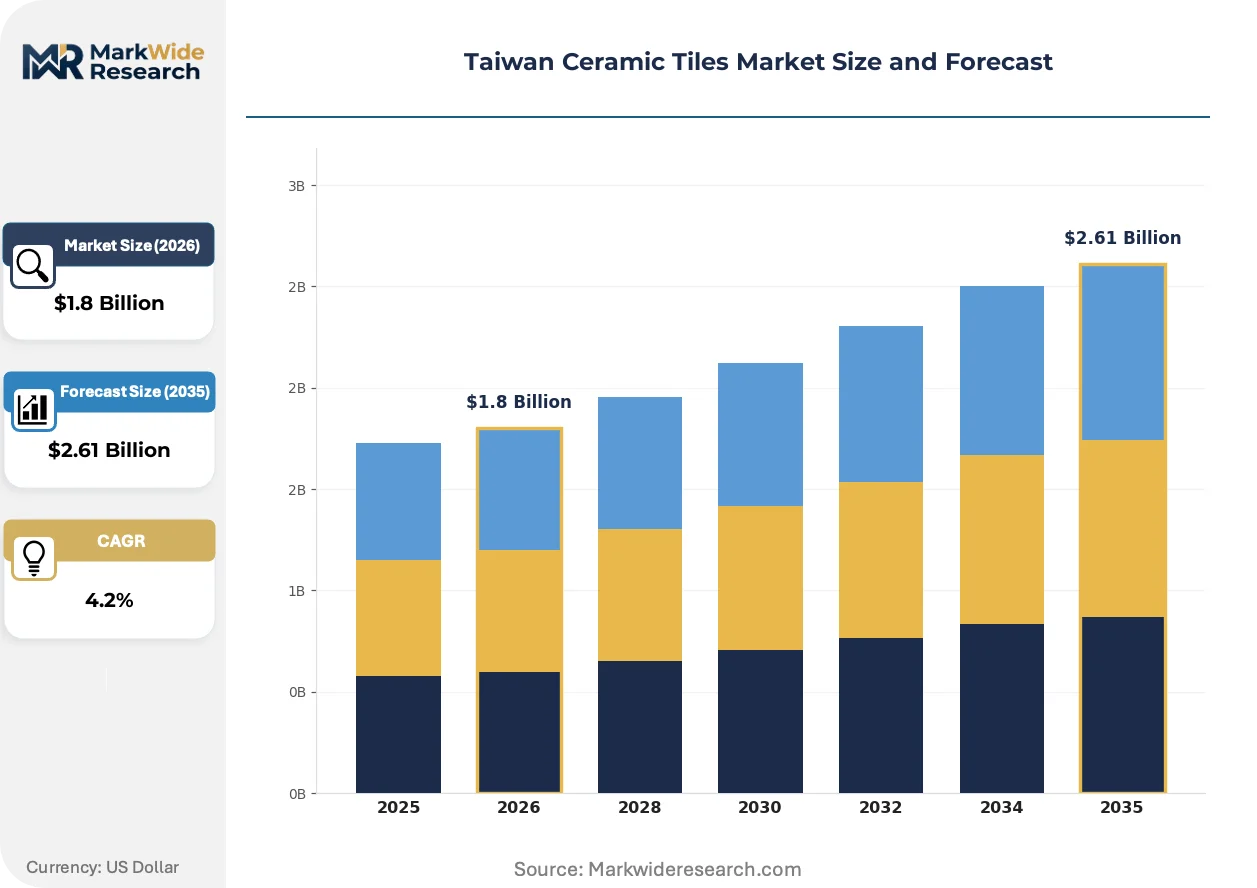
Taiwan's ceramic tile sector is consolidating around CNS 11267 certification compliance, with kiln modernization costs filtering marginal producers from public procurement eligibility. Bureau of Energy green building mandates are compressing margins for non-compliant operators while rewarding low-carbon technology adopters.
Growth Catalysts
- Luxury Residential Tower Development:Northern Taiwan developers specify large-format glazed porcelain for premium positioning, pulling volume through architectural specification channels.
- Bureau of Energy Green Label Mandate:Public procurement rules require certified green building materials, creating guaranteed demand pools for compliant domestic manufacturers.
- Low-Carbon Kiln Technology:Natural gas and electric firing systems reduce carbon intensity scores, unlocking eligibility for government infrastructure contracts.
Market Restraints
- Natural Gas Price Volatility:Kiln operations depend on imported LNG feedstock, exposing margin structures to global energy market swings.
- Mainland Chinese Import Pressure:Cross-strait supply alternatives undercut domestic pricing in standard-grade segments, compressing mid-market producer returns.
- Frost-Resistance Technical Barrier:Porcelain density requirements for outdoor applications exclude ceramic-grade manufacturers from premium exterior specification pools.
Strategic Opportunities
- Taichung Metro Area Expansion:Central Taiwan residential construction growth outpaces northern saturation, creating volume absorption for distributed builder networks.
- Large-Format Slab Specification:Accelerated installation timelines in Taipei retail and hospitality projects favor 1200x2400mm porcelain over traditional formats.
- Circular Material Incentives:Taiwan's Ministry of Economic Affairs waste-reduction credits reward post-industrial recycled content integration in glaze formulations.
Industry Challenges
- CNS 11267 Certification Timeline:Testing and audit cycles extend 8-14 months, delaying new product launches and locking out rapid market entrants.
- Glaze Chemistry Talent Scarcity:Specialized color-matching expertise for architectural specification channels concentrates among retiring technician cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Ceramic Tiles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Tiles, Floor Tiles, Outdoor Tiles, Mosaic Tiles Material: Ceramic, Porcelain, Stoneware, Earthenware End User: Residential, Commercial, Institutional, Industrial Distribution Channel: Online Retail, Showrooms, Distributors, Contracting |
| Companies Covered | Ho Long Ceramic Co., Ltd., White Horse Ceramic Co., Ltd., Jing Kong Ceramic Co., Ltd., Link Kind Trading Co., Ltd., Horng Jou Ceramics Co., Ltd., Sanwon Ceramic, Champion Building Materials Co., Ltd., San Ya Zih Yuan Kai Fa Co., Ltd., King Mint Ceramic Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Ceramic Tiles Market Evolving Landscape
Digital inkjet decoration and low-carbon firing systems are restructuring competitive advantage in Taiwan's ceramic tile production base. These shifts favor capital-rich incumbents while raising barriers for traditional roller-print operators.
Digital inkjet printing is bifurcating the decorative tile segment by enabling unlimited pattern variation without screen-change downtime. Taipei luxury developers and architectural specifiers now demand photorealistic stone and wood replication that roller systems cannot achieve. This capability gap is compressing commodity-grade producers into price-driven builder channels while rewarding inkjet-equipped operators with specification premiums.
Taiwan's Bureau of Energy green building material standards now mandate carbon-intensity disclosure for all public procurement eligibility. Manufacturers must document kiln fuel sources and firing temperatures to qualify for government infrastructure contracts. The policy most affects northern Taiwan producers serving municipal projects, forcing accelerated natural gas conversion or electric kiln investment.
Builder-direct procurement is displacing traditional distributor intermediaries in Taichung-area residential construction. Volume contractors now negotiate directly with manufacturers for standardized floor tile formats, compressing channel margins and demanding just-in-time delivery coordination. This pattern is most visible in central Taiwan's mid-market housing developments where cost engineering dominates specification decisions.
Taiwan Ceramic Tiles Market Segmentation
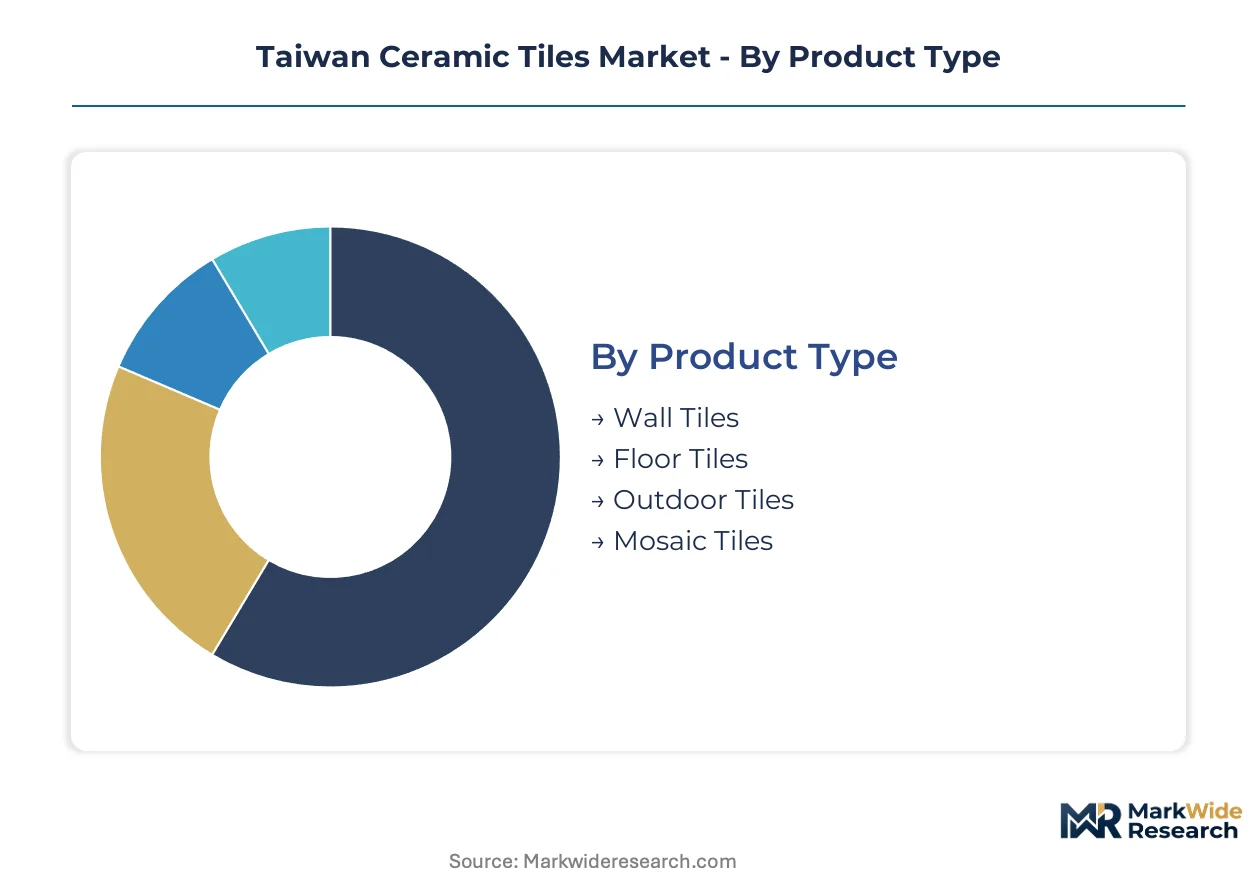
Taiwan's ceramic tile segmentation reflects divergent margin structures across material grades and specification channels. Product type and material composition determine kiln investment requirements, while end-user and distribution dynamics shape pricing power and working capital intensity for domestic manufacturers.
Product Type:
Floor tiles capture the deepest margin pools through large-format porcelain specification in Taipei luxury towers. Wall tiles concentrate volume in mid-market residential renovation, while outdoor and mosaic segments serve niche architectural applications with distinct technical barriers.
- Floor Tiles:Dense porcelain and ceramic formats engineered for abrasion resistance and load-bearing capacity. Northern Taiwan luxury residential towers specify 600x1200mm and 1200x2400mm glazed porcelain, pulled by developer demand for premium positioning and accelerated installation timelines.
- Wall Tiles:Lighter-bodied ceramic products with decorative glaze finishes for vertical surfacing. Taichung-area residential renovation and new construction absorb standardized formats through builder-direct procurement channels displacing traditional distributors.
- Outdoor Tiles:Frost-resistant porcelain with slip-resistant surface treatments for exterior applications. Bureau of Energy green building material standards mandate carbon-intensity disclosure for public infrastructure eligibility.
- Mosaic Tiles:Small-format decorative units for accent walls and wet-area detailing. Custom color-matching requirements concentrate specification among specialized glaze R&D operators.
Floor tiles hold installed capacity. Outdoor tiles are rotating up the share rankings.
Material:
Porcelain commands price premiums through density and frost-resistance specifications that filter out lower-tier producers. Ceramic anchors volume in cost-sensitive residential segments, while stoneware and earthenware occupy specialized niches with limited domestic production scale.
- Porcelain:Fired above 1200°C to achieve vitrified, low-porosity body structure meeting CNS 11267 density requirements. Northern Taiwan architectural specification channels demand photorealistic stone and wood replication enabled by digital inkjet decoration systems.
- Ceramic:Standard-grade fired clay products for interior wall and light-traffic floor applications. Cross-strait import pressure from mainland Chinese supply undercuts domestic pricing in this segment.
- Stoneware:Intermediate density material for heavy-duty commercial flooring. Limited domestic kiln capacity restricts production scale.
- Earthenware:Low-fire porous body for decorative and artisanal applications. Marginal commercial significance in Taiwan's industrialized production base.
Porcelain dominates value capture. Ceramic maintains volume leadership.
End User:
Residential channels absorb the highest tile volumes through renovation and new construction cycles. Commercial contracting is expanding most quickly as Taipei retail and hospitality developers specify large-format slabs, while institutional demand ties to Bureau of Energy green procurement mandates.
- Residential:Single-family renovation and multi-family new construction across Taipei, Taichung, and Kaohsiung metropolitan areas. Northern Taiwan luxury tower developers specify imported-look glazed porcelain for premium positioning.
- Commercial:Retail, hospitality, and office fit-out projects with accelerated installation timelines. Large-format 1200x2400mm porcelain slabs reduce labor hours versus traditional formats.
- Institutional:Government infrastructure and public building projects requiring Bureau of Energy green building material certification. Natural gas and electric firing systems unlock eligibility through reduced carbon intensity scores.
- Industrial:Manufacturing facility flooring with chemical resistance and heavy-load specifications. Specialized technical requirements limit qualified supplier pools.
Residential channels hold installed capacity. Commercial contracting is climbing the fastest.
Distribution Channel:
Contracting and builder-direct procurement are displacing traditional intermediaries, compressing channel margins and demanding just-in-time delivery coordination. Showrooms retain influence in architectural specification, while online retail remains nascent for tile categories requiring physical inspection.
- Contracting:Direct manufacturer relationships with volume residential and commercial builders. Taichung-area mid-market housing developments drive this channel's expansion through cost-engineering priorities.
- Distributors:Traditional wholesale networks for standardized product formats. Margin compression from builder-direct procurement limits growth in this channel.
- Showrooms:Specification-focused display centers serving architects and interior designers. Custom color-matching and large-format slab presentation sustain relevance in premium segments.
- Online Retail:Digital catalog and logistics platforms for standardized tile formats. Limited penetration due to tactile purchase requirements and freight handling complexity.
Contracting holds installed capacity. Showrooms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Bureau of Energy green building material standards and CNS 11267 certification requirements are steering procurement patterns and manufacturing investment across the island's regional production clusters.
Northern Taiwan
Taipei and New Taipei City luxury residential towers specify large-format glazed porcelain for premium developer positioning. Bureau of Energy mandates require carbon-intensity disclosure for all public infrastructure eligibility. Manufacturing concentrates in Taoyuan and Yilan counties where natural gas kiln conversion unlocks government contract access.
Central Taiwan
Taichung Metro Area residential construction outpaces northern saturation with volume absorption through builder-direct procurement channels. Taichung City construction codes align with national green building standards. Manufacturing bases in Changhua and Nantou counties serve distributed housing developments with standardized floor tile formats.
Southern Taiwan
Kaohsiung industrial flooring and institutional projects drive frost-resistant porcelain specification for chemical resistance requirements. Ministry of Economic Affairs emissions protocols raise capital barriers for kiln modernization. Production clusters in Tainan and Kaohsiung municipalities consolidate among established operators with compliant firing systems.
Eastern Taiwan
Hualien and Taitung counties absorb limited volume through tourism hospitality renovation and indigenous community housing programs. Local procurement preferences under Taiwan's regional development framework support small-scale distributors. Yilan County's northern corridor maintains satellite production for niche architectural specification.
Taiwan Ceramic Tiles Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and kiln technology investment tiers. Champion Building Materials exemplifies the vertically integrated archetype with captive kiln operations sustaining consistent CNS-grade output. White Horse Ceramic occupies the specialized glaze R&D position where custom color-matching commands architectural specification premiums. Ho Long Ceramic anchors the mid-market residential segment through standardized format distribution. Capacity consolidation and natural gas conversion represent the dominant competitive moves filtering marginal producers from public procurement eligibility.
Within the vertically integrated tier, Champion Building Materials represents capital-rich incumbents leveraging in-house kiln control for certification consistency. White Horse Ceramic exemplifies the R&D-specialist archetype where glaze chemistry expertise concentrates specification power. Ho Long Ceramic sits within the volume-distributed segment, occupying a position in Taichung-area builder networks where cost-engineering priorities dominate procurement decisions. These three company structures illustrate how Taiwan's ceramic tile sector stratifies across technology investment, certification compliance, and channel access dimensions.
| Leading Market Players |
|---|
| Ho Long Ceramic Co., Ltd. |
| White Horse Ceramic Co., Ltd. |
| Jing Kong Ceramic Co., Ltd. |
| Link Kind Trading Co., Ltd. |
| Horng Jou Ceramics Co., Ltd. |
| Sanwon Ceramic |
| Champion Building Materials Co., Ltd. |
| San Ya Zih Yuan Kai Fa Co., Ltd. |
| King Mint Ceramic Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Kiln capacity utilization above 85% at Champion Building Materials and White Horse Ceramic anchors Taiwan's supply concentration, compressing price floors for mid-market operators while CNS 11267 compliance premiums protect qualified incumbents from cross-strait import erosion.
Pricing Analysis
Certification level creates the primary spread across Taiwan's ceramic tile tiers, with CNS 11267-qualified porcelain commanding 35-50% premiums over non-certified ceramic imports from mainland China. Three-tier pricing structure across premium architectural specification, standard residential renovation, and economy-grade builder channels reflects glaze R&D investment and kiln technology differentiation. Cost compression in the economy tier intensifies because Taichung-area builder-direct procurement eliminates distributor margins. Volume contractors exhibit highest price sensitivity, while Taipei luxury developers prioritize photorealistic digital inkjet finishes over unit cost.
Supply Chain Analysis
Strategic stockpiling of imported LNG feedstock dominates inventory strategy among northern Taiwan kiln operators buffering against global energy price volatility. Raw material sourcing draws from China for clay bodies, Italy for digital inkjet printers, and Australia for alumina additives. Single-source vulnerability concentrates in natural gas supply through Taiwan's limited LNG terminal infrastructure. Distribution runs through contracting channels displacing traditional wholesalers, with just-in-time delivery coordination now mandatory for Taichung-area residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's ceramic tile sector approaches a platform-economics inflection as Bureau of Energy green building standards and CNS 11267 certification interoperability reshape procurement eligibility into a two-sided marketplace connecting compliant manufacturers with government infrastructure demand pools.
For Market Incumbents: Consolidate kiln capacity around natural gas and electric firing systems to lock in Bureau of Energy green label eligibility for municipal infrastructure contracts. Champion Building Materials demonstrates how backward integration into captive clay processing defends margin position against cross-strait import pressure. Acquire distressed mid-market competitors in Changhua and Nantou counties to absorb their CNS certification queues and distribution relationships.
For New Entrants and Emerging Players: Differentiate on circular material integration by securing Ministry of Economic Affairs waste-reduction credits through post-industrial recycled glaze content. The most penetrable white space sits in Taichung Metro Area mid-market residential contracting, where builder-direct procurement favors new relationships over legacy distributor entrenchment. Pursue specification partnerships with Taipei architectural firms demanding custom color-matching capabilities that retiring technician cohorts can no longer supply.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CNS 11267-certified operators with locked government infrastructure contracts, positioning them as platform-arbitrage targets. Long-term viability hinges on carbon-intensity score advantages against Southeast Asian supply alternatives. The signal to watch is Bureau of Energy threshold tightening that would disqualify additional mainland Chinese imports from public procurement eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Gas Kiln Conversion | Unlocks Bureau of Energy green label eligibility for government infrastructure contracts. |
| Circular Material Integration | Captures Ministry of Economic Affairs waste-reduction credits for recycled glaze formulations. |
| Digital Inkjet Decoration Investment | Enables photorealistic stone replication for Taipei luxury developer specification channels. |
| Builder-Direct Procurement Partnerships | Displaces traditional distributors in Taichung-area cost-engineered residential developments. |
| Glaze Chemistry Talent Acquisition | Secures retiring technician expertise for architectural color-matching service premiums. |
Research Methodology
Desk research of Taiwan Bureau of Energy green building material standards, CNS 11267 certification documentation, and Ministry of Economic Affairs emissions protocols preceded structured interviews with kiln operations managers, architectural specification consultants, Taichung-area builder procurement officers, and glaze R&D directors. Secondary validation drew from customs trade data, industrial energy consumption disclosures, and municipal procurement records. Bottom-up capacity modeling triangulated against top-down construction spending forecasts across northern, central, and southern Taiwan regions.
Variance decomposition across product type, material grade, end-user segment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity utilization trends, green building code adoption curves, and cross-strait import elasticity estimates. Forecast inputs incorporated natural gas price scenarios and Bureau of Energy carbon-intensity threshold evolution.
The analysis sits within stated boundaries; outcomes outside sustained CNS 11267 enforcement or abrupt cross-strait trade policy shifts would require recalibration. Forecasts reflect assumptions regarding kiln modernization completion timelines and green procurement mandate expansion. Revision becomes warranted when mainland Chinese import pricing crosses domestic natural gas-fired production cost thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramics Market
Ceramics
Boiler Refractory Material Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Kaolin Market
Ceramics
Ceramic Pigments Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Ceramic Binders Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Porous Ceramic Market
Ceramics
Stoneware Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Global Barium Carbonate Market
Ceramics
Zirconia Ceramics Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Advanced Ceramics Market