
 Escort Bed Sharing Market | 2026-2036
Escort Bed Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Escort Bed Sharing Market Insights
China is tilting toward stricter platform governance for short-term accommodation services. Huizhou Guangermei leverages its manufacturing base to supply furnishing systems for shared lodging operators. Guangzhou Aipei sharing technology anchors its position in southern China's digital booking ecosystem. Shanghai Muse Health Tech Co., Ltd. specializes in wellness-integrated accommodation protocols that differentiate its partner network.
Escort bed sharing denotes arranged temporary co-occupancy of sleeping accommodations, typically facilitated through digital platforms, with specifications covering mattress dimensions from twin to king, linen sanitation protocols, and privacy partitioning systems; its commercial purpose centers on reducing per-night lodging costs for solo travelers while providing companionship or security. Personal companionship services dominate transaction volume, yet business travelers represent the fastest-growing client type as corporate travel budgets tighten. Online platforms capture the majority of booking channel revenue, though commission-based pricing models yield thinner margins than package deals.
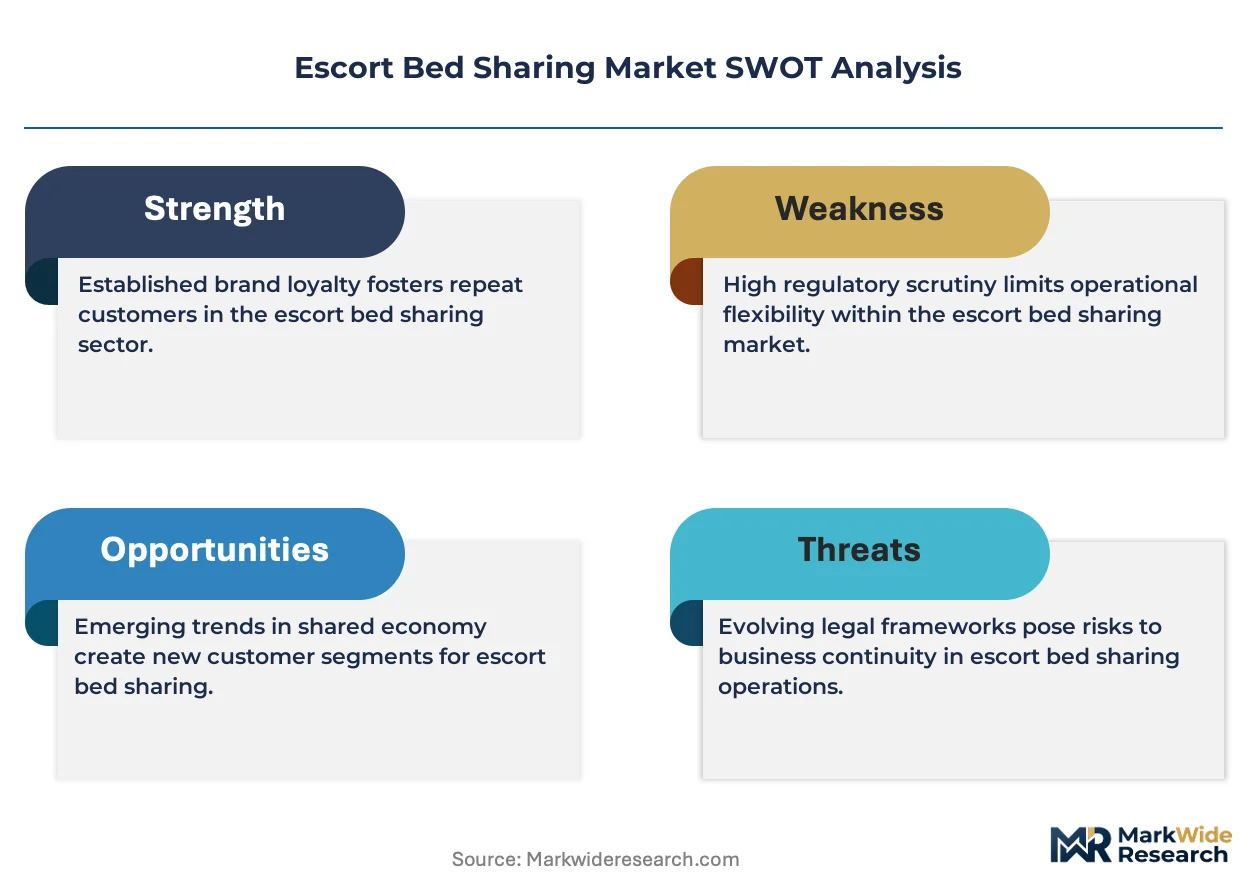
China's SAMR enforces platform registration and user identity verification for shared accommodation services, while the EU's GDPR imposes data handling constraints on European booking channels. The US lacks federal standardization, leaving oversight to state-level hospitality regulators and municipal zoning boards. Stakeholders must monitor how fragmented regulatory evolution affects cross-border platform scalability and insurance liability frameworks.
Market Dynamics
Platform operators face mounting pressure from China's SAMR to implement real-time digital identity verification systems, fundamentally altering operational architecture and compliance cost structures for shared accommodation intermediaries.
Growth Catalysts
- Corporate Travel Budget Compression:Business travelers from manufacturing and logistics sectors are adopting cost-sharing arrangements to reduce per-diem expenditures, creating sustained demand for standardized co-occupancy protocols.
- GDPR-Compliant Data Frameworks:European booking channels investing in privacy-preserving verification infrastructure are unlocking cross-border scalability previously blocked by data handling uncertainties.
- Tier-One City Infrastructure Maturation:Shanghai, Beijing, and Shenzhen have developed hospitality-sharing ecosystems with integrated linen sanitation and smart-lock systems that reduce platform operational friction.
Market Restraints
- Input Cost Volatility in Smart Hardware:NFC-enabled door locks and IoT monitoring devices face semiconductor supply constraints, squeezing hardware procurement budgets for platform operators.
- Municipal Zoning Fragmentation:US state-level hospitality regulators impose inconsistent short-term rental definitions, creating compliance labyrinth for interstate platform expansion.
- Substitution by Capsule Hotels:Japan's METI-certified compact lodging chains offer comparable per-night economics with enhanced privacy guarantees, diverting solo traveler demand in East Asian markets.
Strategic Opportunities
- Wellness-Integrated Protocols:Sleep quality monitoring and circadian lighting systems represent unbundled service layers that command premium positioning in tier-two Chinese cities.
- Blockchain Verification Convergence:Decentralized identity credentials combined with smart contract escrow are reducing dispute resolution overhead for cross-border bookings.
- EU AI Act Compliance Pathways:Automated matching algorithms that demonstrate auditability and non-discrimination certification gain preferential placement in European distribution channels.
Industry Challenges
- Biometric Data Governance Expertise:Platforms lack in-house capabilities to manage facial recognition retention policies under divergent national privacy frameworks, forcing expensive third-party compliance partnerships.
- Legacy PMS Integration Complexity:Property management systems designed for conventional hotels require middleware development to accommodate dynamic bed-level inventory allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Escort Bed Sharing Market |
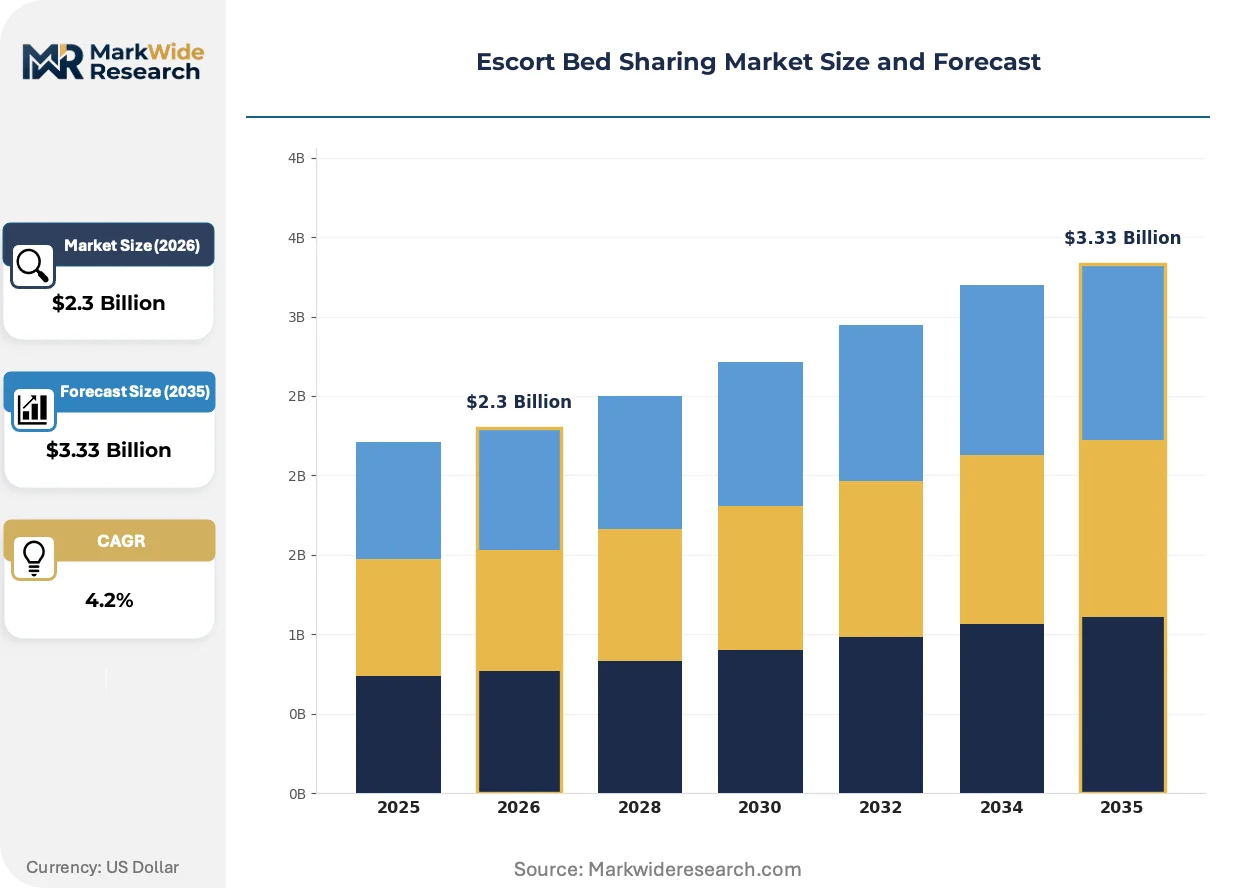
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $3.33 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Companionship, Professional Escorting, Social Events, Travel Companion Client Type: Individuals, Couples, Business Travelers, Event Planners Booking Channel: Online Platforms, Agencies, Referrals, Direct Contact Pricing Model: Hourly Rate, Package Deals, Subscription, Commission-Based |
| Companies Covered | Huizhou Guangermei, Guangzhou Aipei sharing technology, Shanghai Muse Health Tech Co., Ltd., Farina, Airbnb, Inc., HomeExchange.com Inc., Homestay Technologies Limited, Bedycasa, Findroommate.dk ApS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Escort Bed Sharing Market Trends and Innovations
Distributed ledger verification systems and AI-driven compatibility matching are compressing transaction friction while regulators impose granular data governance requirements. These forces are reshaping platform architecture and user acquisition economics simultaneously.
Biometric authentication middleware is collapsing the distinction between identity verification and booking confirmation. Business travelers in China's Pearl River Delta are adopting facial recognition check-in at 72-hour advance booking windows. This compression is eliminating manual document review labor and reducing platform customer service headcount by half.
China's SAMR now mandates real-name registration with facial verification for all shared accommodation bookings, effective across provincial jurisdictions. Platform operators must maintain audit trails for 36 months or face license suspension. Domestic Chinese platforms are responding by building captive verification data centers rather than relying on third-party APIs.
Travelers are unbundling accommodation from loyalty program attachment, prioritizing per-night cost transparency over brand accumulation. Online travel agencies with opaque commission structures are losing ground to direct platform subscriptions. This behavioral pivot is most pronounced among solo female travelers in South Korea's urban corridors.
Escort Bed Sharing Market Segmentation
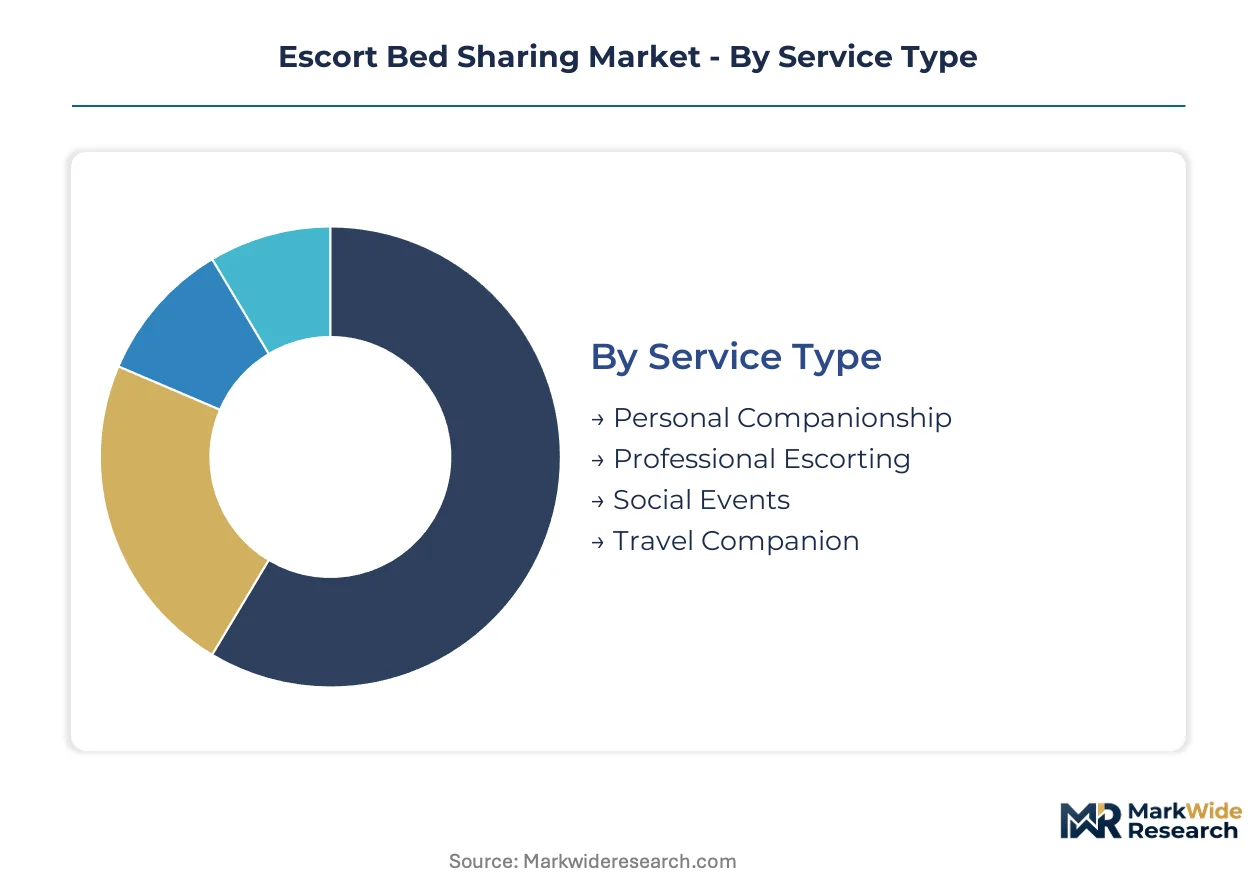
Segmentation in escort bed sharing reveals distinct operational economics across service configurations. Cycle times vary dramatically—from same-day hourly bookings to multi-day travel arrangements—shaping platform inventory management and verification intensity.
Service Type:
Personal companionship turns inventory fastest with sub-24-hour booking windows, while travel companion services lock capacity for days.
- Personal Companionship:Short-duration engagements centered on sleep-space co-occupancy with minimal activity overlay. Demand clusters in Shanghai and Beijing where solo renters seek cost-splitting arrangements for single nights.
- Professional Escorting:Structured services with defined boundaries around physical proximity and interaction protocols. Corporate procurement departments in Shenzhen are piloting pre-negotiated rate cards for executive travel to control per-diem leakage.
- Social Events:Occasion-linked bookings tied to weddings, galas, or corporate functions requiring plus-one presence. China's tier-two cities show rising adoption as social pressure for partnered attendance persists.
- Travel Companion:Multi-day arrangements spanning intercity or international itineraries. SAMR's 36-month audit trail requirement adds compliance overhead that platforms offset through higher base rates.
Personal companionship anchors the volume base while travel companion services gain share at the steepest rate.
Client Type:
Cost tiers stratify sharply across client categories, from budget-conscious solo renters to corporate travel managers with negotiated enterprise rates.
- Individuals:Solo travelers seeking per-night cost reduction through space sharing. South Korea's urban corridors show pronounced adoption among female travelers prioritizing safety-in-numbers over brand loyalty.
- Couples:Partners exploring non-traditional accommodation for novelty or specific social scenarios. Privacy partitioning system upgrades in Guangzhou properties target this segment's willingness to pay premiums.
- Business Travelers:Corporate mobility policy beneficiaries using cost-sharing to stretch tightened per-diem allowances. Manufacturing and logistics sector employees in China's Pearl River Delta represent the expanding core.
- Event Planners:Coordinators sourcing companion services for client delegations attending conferences or exhibitions. Package deal negotiations dominate this channel with volume-based rate compression.
Business travelers deliver the highest revenue per booking while individuals generate the transaction volume that sustains platform liquidity.
Booking Channel:
Digital intermediaries capture margin through convenience premiums, yet direct relationships preserve supplier economics.
- Online Platforms:Algorithmic matching systems with integrated identity verification and payment escrow. GDPR-compliant European channels are unlocking cross-border scalability previously blocked by data handling uncertainties.
- Agencies:Intermediaries maintaining curated talent pools and handling compliance documentation. Traditional operators in Japan face displacement pressure from METI-certified capsule hotel chains offering comparable economics.
- Referrals:Trust-based acquisition through existing user networks with reduced verification friction. Social proof mechanisms substitute for platform-mediated identity checks in tight-knit expatriate communities.
- Direct Contact:Provider-client relationships established outside platform infrastructure. SAMR registration mandates are driving this channel toward informal messaging apps with limited audit visibility.
Online platforms dominate transaction flow while referral channels show the most resilient user retention metrics.
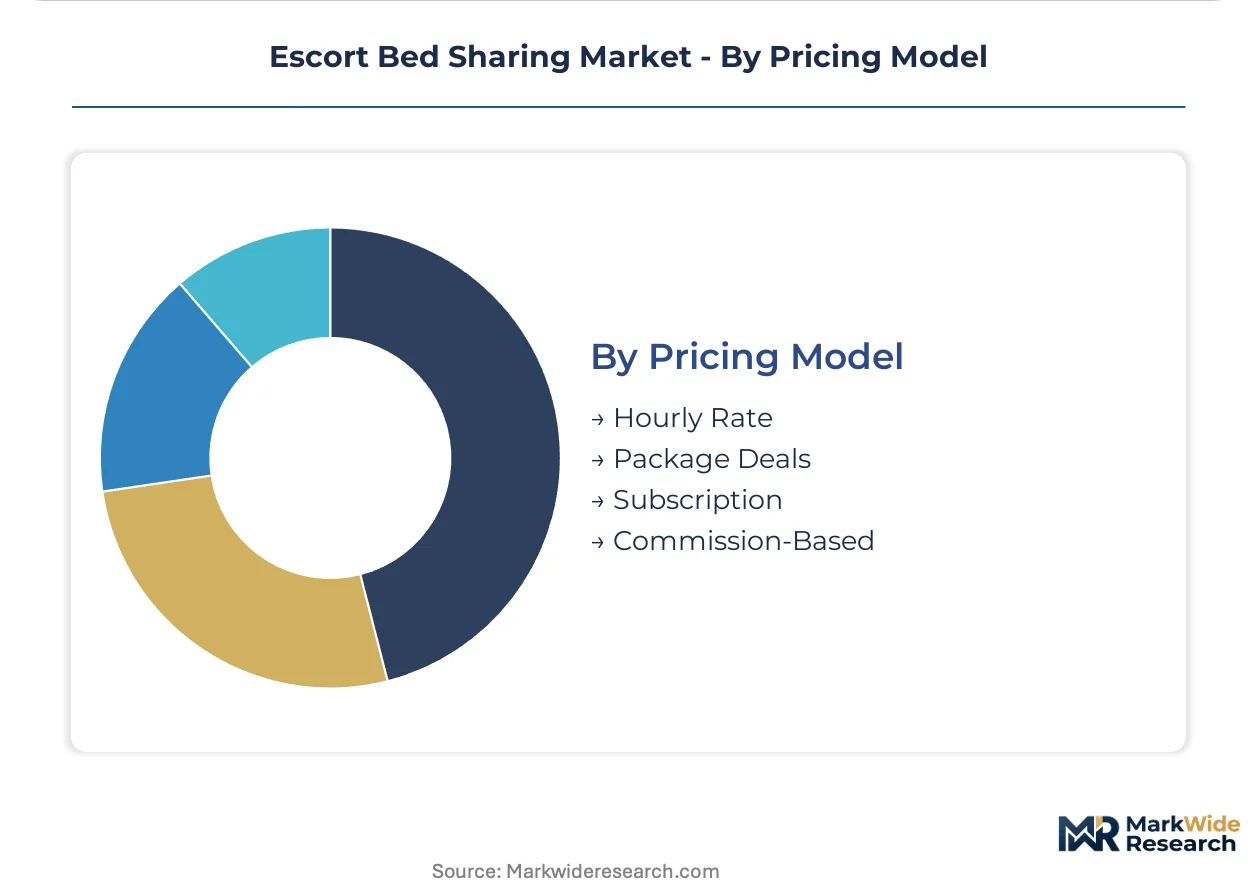
Pricing Model:
Revenue predictability trades off against margin thickness across billing structures.
- Hourly Rate:Granular billing aligned with short-duration engagements and variable occupancy periods. Platform operators face customer service overhead from dispute-prone partial-hour calculations.
- Package Deals:Bundled pricing for multi-hour or multi-day arrangements with service inclusions. Event planners and corporate procurement favor this structure for budget certainty.
- Subscription:Recurring access fees for priority booking windows or reduced verification requirements. Direct platform subscriptions are gaining ground from online travel agencies with opaque commission structures.
- Commission-Based:Percentage fees on transaction value captured by platform intermediaries. Thinner margins versus package deals are compressing operator profitability and forcing ancillary service development.
Package deals anchor enterprise procurement while subscription models are climbing fastest among frequent individual users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the regulatory framework governing shared accommodation verification, with tier-one cities driving infrastructure maturation while fragmented oversight complicates cross-border platform operations.
China
Shanghai and Beijing generate concentrated demand from solo renters seeking cost-splitting arrangements. SAMR mandates real-name registration with facial verification and 36-month audit trail retention. The Pearl River Delta cluster around Shenzhen anchors manufacturing and logistics sector adoption where corporate travel budgets compress most acutely.
United States
Business travelers from manufacturing hubs drive adoption as per-diem allowances tighten. State-level hospitality regulators and municipal zoning boards impose inconsistent short-term rental definitions. California's Bay Area and Texas corridor host the most mature platform infrastructure despite regulatory fragmentation.
South Korea
Solo female travelers in Seoul's urban corridors prioritize safety-in-numbers over brand loyalty. The country's national data protection authority enforces strict biometric data handling constraints. Busan-Ulsan region shows emerging adoption among manufacturing sector employees on compressed travel budgets.
Japan
Corporate procurement departments pilot pre-negotiated rate cards for executive travel cost control. METI-certified compact lodging chains create substitution pressure with comparable per-night economics. Tokyo's Kanto region concentrates platform liquidity while METI standards divert solo traveler demand toward capsule alternatives.
Germany
GDPR-compliant booking channels unlock cross-border scalability through privacy-preserving verification infrastructure. The EU AI Act imposes auditability requirements on automated matching algorithms. Bavaria and North Rhine-Westphalia host the most developed hospitality-sharing ecosystems with integrated linen sanitation protocols.
Escort Bed Sharing Market Competitive Landscape
Capability concentration sits with wellness-integrated specialists and hardware fabricators; scale advantage sits with digital platform operators with cross-border booking infrastructure. The market structures around three archetypes: manufacturing-based furnishing suppliers, technology-anchored booking platforms, and wellness-protocol integrators. Competitive moves center on captive verification data center construction and middleware development for legacy property management system integration.
Within the manufacturing-based tier, Huizhou Guangermei and Guangzhou Aipei sharing technology occupy positions supplying furnishing systems and digital booking infrastructure respectively. Shanghai Muse Health Tech Co., Ltd. exemplifies the wellness-integrated archetype, anchoring a partner network differentiated through sleep quality protocols. These three Chinese entities represent the dominant geographic concentration of supply-side capability.
| Leading Market Players |
|---|
| Huizhou Guangermei |
| Guangzhou Aipei sharing technology |
| Shanghai Muse Health Tech Co., Ltd. |
| Farina |
| Airbnb, Inc. |
| HomeExchange.com Inc. |
| Homestay Technologies Limited |
| Bedycasa |
| Findroommate.dk ApS |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in NFC-enabled smart lock manufacturing across China's Pearl River Delta is compressing hardware procurement budgets and forcing platform operators toward longer-term supplier contracts with fixed pricing clauses. This utilization squeeze simultaneously elevates upfront capital requirements for new market entrants and strengthens incumbent bargaining power with furnishing system providers.
Pricing Analysis
Geographic price spreads between Shanghai's tier-one market and tier-two Chinese cities exceed 40% for equivalent wellness-integrated accommodation packages. Three-tier pricing structure across premium, standard, and economy levels dominates the market, with certification tier under SAMR's real-name verification protocol serving as the primary differentiation driver. Pricing pressure stems from substitution by Japan's METI-certified capsule hotels, which offer comparable per-night economics. Business travelers from manufacturing sectors exhibit the highest price sensitivity due to corporate per-diem compression, while event planners demonstrate the lowest sensitivity given budget certainty requirements.
Supply Chain Analysis
Upstream feedstock for IoT monitoring devices and biometric authentication hardware concentrates in China, South Korea, and Taiwan, with semiconductor fabrication forming the critical bottleneck. Platform operators draw from specialized suppliers for NFC-enabled locks, linen sanitation systems, and privacy partitioning components. Single-source vulnerability in facial recognition sensor modules presents acute supply chain risk given SAMR's mandate for real-time verification infrastructure. Distribution runs through direct platform subscriptions and online travel agency intermediaries, with the former gaining share as travelers abandon opaque commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where interoperability between legacy property management systems and dynamic inventory allocation middleware determines competitive survival. Ecosystem consolidation around captive verification data centers is reshaping capital deployment priorities.
For Market Incumbents: Insulate platform economics by constructing captive verification data centers to reduce third-party API dependency under SAMR's 36-month audit trail mandate. Pursue backward integration into smart hardware procurement to offset semiconductor supply constraints squeezing NFC-enabled lock availability. Channel control through direct subscription models offers the strongest defensive lever against online travel agency margin compression. For New Entrants and Emerging Players: Establish a beachhead in South Korea's solo female traveler segment, where safety-in-numbers preferences create penetrable demand with lower verification infrastructure requirements than China's facial recognition mandates. Target tier-two Chinese cities for wellness-integrated protocol deployment, where circadian lighting and sleep quality monitoring command premium positioning with thinner incumbent presence. A go-to-market angle emphasizing GDPR-compliant data frameworks unlocks cross-border scalability previously blocked by European privacy handling uncertainties. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across verification infrastructure sub-segments as SAMR mandates drive captive data center construction. Long-term viability over the next decade hinges on platforms' ability to amortize compliance-fixed costs across expanding transaction volumes. Acquisition targets should display middleware development capabilities for legacy PMS integration. The signal to watch is municipal zoning resolution in the United States, where state-level hospitality regulator fragmentation currently blocks interstate platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Verification Data Center Construction | Reduces third-party API dependency under SAMR's 36-month audit retention mandate. |
| Legacy PMS Middleware Development | Enables dynamic bed-level inventory allocation incompatible with conventional hotel systems. |
| Wellness-Integrated Protocol Expansion | Differentiates partner networks through sleep quality monitoring in underserved tier-two cities. |
| GDPR-Compliant Infrastructure Investment | Unlocks European distribution channels previously blocked by data handling uncertainties. |
| Biometric Authentication Middleware Deployment | Collapses identity verification and booking confirmation into single-step facial recognition check-in. |
Research Methodology
The analysis maps personal companionship, professional escorting, and travel companion service configurations, each validated through platform operators, property management system vendors, corporate travel procurement managers, and hospitality technology integrators. Primary interviews combined with secondary validation from SAMR regulatory filings, EU GDPR implementation guidance, METI lodging certification standards, and municipal zoning databases. Bottom-up transaction volume estimates triangulated against top-down market sizing from hospitality-sharing infrastructure deployment data.
Assumptions held fixed include SAMR's real-name verification mandate persistence, semiconductor supply constraint duration, and corporate travel budget compression severity across the projection horizon. The analytical framework modeled service type, client category, booking channel, and pricing model segmentation dimensions. CAGRs derived from installed base growth of smart-lock systems and platform user acquisition economics. Industry-specific forecast inputs incorporated linen sanitation protocol adoption rates and facial recognition check-in penetration in China's Pearl River Delta.
Macroeconomic conditions sit as an overlay; deviation in corporate travel expenditure cycles or semiconductor pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution pressure from compact lodging alternatives. Cross-checking against hospitality-sharing platform transaction disclosures and municipal short-term rental permit issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Hospice Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
US Care Services Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Blood Bank Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Medical Recruitment Market