
 Contract Manufacturing Organization (CMO) Market | 2026-2036
Contract Manufacturing Organization (CMO) Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Manufacturing Organization (CMO) Market Intelligence
Capital investment divergence between large-molecule and small-molecule capacity is rotating the competitive landscape. Large-scale players like Lonza Group specialize in high-value biologics and cell and gene therapy production, requiring massive upfront capital expenditure. Catalent leverages its global network for a wide range of formulation and advanced drug delivery technologies. In contrast, Siegfried focuses on API manufacturing for small molecules, a segment with different capital and operational requirements.
A Contract Manufacturing Organization (CMO) provides outsourced pharmaceutical production services, from active pharmaceutical ingredient (API) manufacturing to final dosage formulation and packaging. These organizations operate under strict cGMP (Current Good Manufacturing Practice) standards to ensure product quality and international regulatory compliance. API Manufacturing remains a foundational service type, while advanced formulation development sees significant investment. Within therapy areas, complex oncology programs command premium capacity and specialized handling capabilities due to their high value.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA dictates global operational standards. These agencies enforce cGMP guidelines through rigorous, often unannounced, facility inspections which are critical for market access in their respective jurisdictions. CMOs must continuously decide whether to invest in dedicated, large-scale facilities for blockbuster drugs or maintain flexible, multi-product capacity for a diverse portfolio of smaller-batch therapies.
Market Dynamics
The fundamental dynamic shaping the CMO market is the capital investment divergence between large-molecule biologics and small-molecule APIs. This split dictates facility design, regulatory strategy, and competitive positioning, creating distinct sub-markets with different barriers to entry and operational demands.
Growth Catalysts
- Continuous Bioprocessing:The industry-wide shift from batch to continuous manufacturing for biologics enhances efficiency and product consistency, compelling biopharmaceutical firms to outsource to CMOs with established expertise in these advanced platforms.
- Favorable Regulatory Hubs:Established biopharma clusters in Ireland, Switzerland, and Singapore offer tax incentives, skilled labor pools, and clear regulatory pathways from agencies like Swissmedic, attracting significant foreign direct investment in specialized CMO capacity.
- Complex Disease Pipelines:The growing pipeline of high-value oncology and orphan drugs, which often involve complex biologics or cell therapies, requires specialized handling and manufacturing capabilities that many developers lack in-house.
Market Restraints
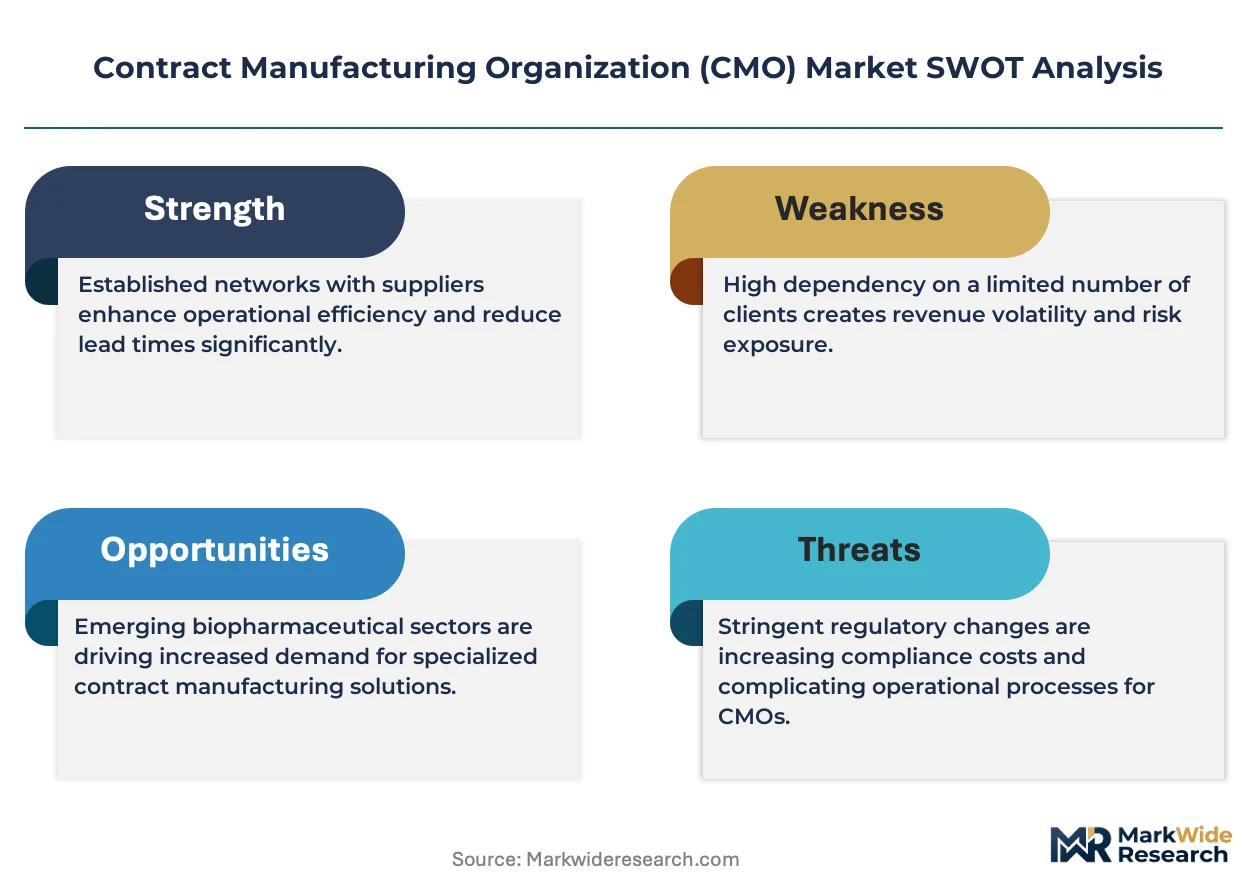
- High Capital Expenditure:The immense upfront investment required to build and validate cGMP-compliant facilities for large-molecule biologics and cell therapies creates a significant barrier to entry and limits capacity expansion.
- Regulatory Scrutiny:Rigorous and often unannounced facility inspections by agencies like the US FDA and EMA create operational risk, where a single compliance failure can halt production and disrupt global supply chains.
- Technical Complexity:Manufacturing advanced therapies, such as cell and gene therapies, faces challenges with process scalability, yield variability, and ensuring consistent quality, which can constrain commercial viability and limit outsourcing options.
Strategic Opportunities
- Advanced Therapy Manufacturing:There is a significant opportunity in building dedicated capacity for advanced therapy medicinal products (ATMPs), including CAR-T and gene therapies, which represent a high-value, capacity-constrained segment.
- Digitalization and AI Integration:The convergence of process analytical technology (PAT) with artificial intelligence offers a path to predictive maintenance, real-time quality control, and optimized production scheduling in multi-product facilities.
- End-to-End Service Integration:CMOs can capture greater value by offering integrated services that span the entire product lifecycle, from cell line development and process optimization through to commercial manufacturing and fill-finish services.
Industry Challenges
- Talent Scarcity:A critical shortage of scientists and technicians with expertise in process development, analytical testing, and operations for complex biologics and cell therapies constrains growth and drives up labor costs.
- Capacity Planning Dilemma:CMOs face a constant strategic challenge in deciding whether to invest in large-scale, dedicated lines for potential blockbuster drugs or maintain flexible, multi-product facilities for a diverse clinical-stage portfolio.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Manufacturing Organization (CMO) Market |
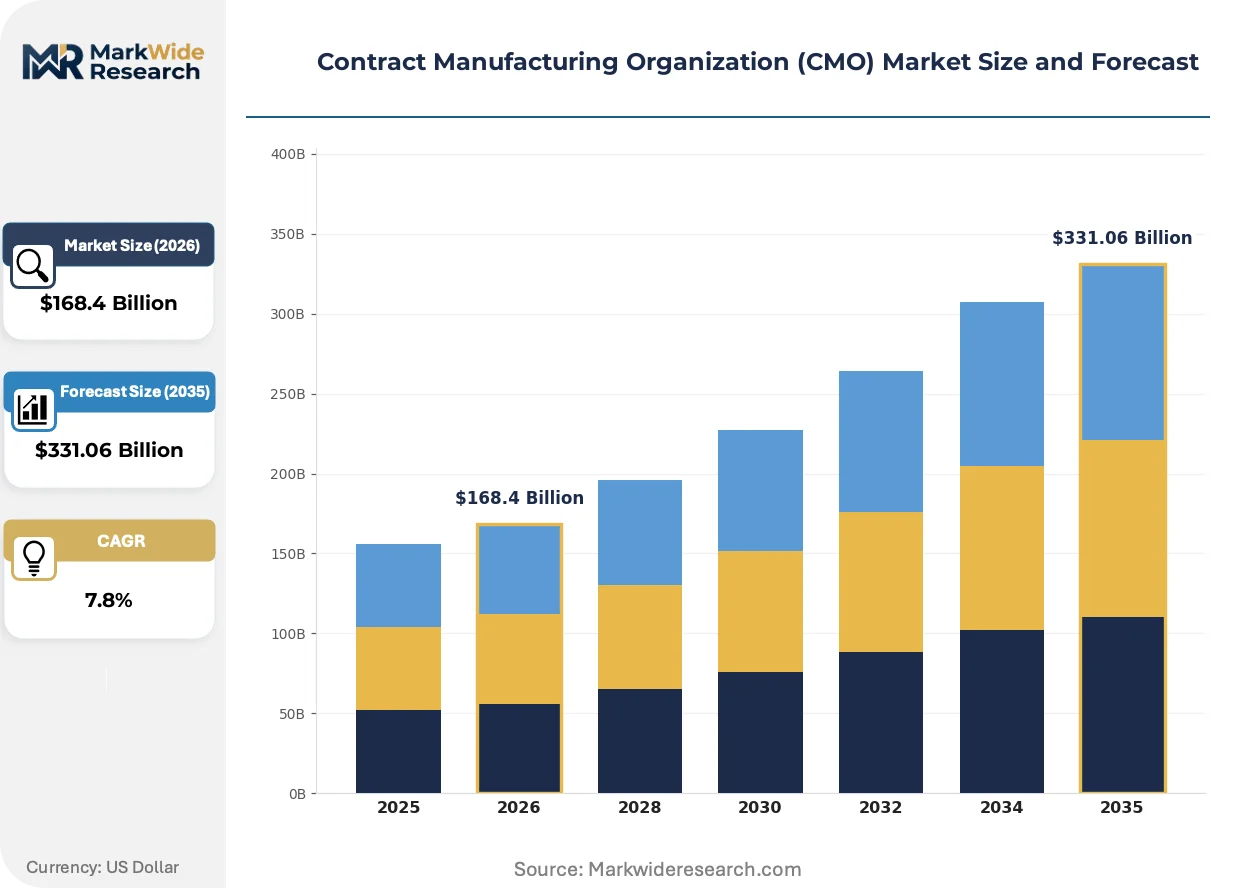
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $331.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Analytical Testing, API Manufacturing, Packaging Services, Stability Testing Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases, Respiratory Client Type: Biopharmaceutical Companies, Generic Drug Manufacturers, Biotechnology Firms, Nutraceutical Producers, Veterinary Product Developers Delivery Model: On-demand, Dedicated Facility, Flexible Capacity, Turnkey Solutions, Risk-sharing Partnerships |
| Companies Covered | Samsung Biologics, Siegfried, Lonza Group, Boehringer Ingelheim, Fujifilm Biotechnologies, Thermo Fisher Scientific, WuXi Biologics, AGC Biologics, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Manufacturing Organization (CMO) Market Strategic Shifts & Innovations
Industrialization of novel modalities and the digitalization of the factory floor are defining the next phase of CMO evolution. These forces are compelling service providers to invest in both new technological platforms and the data infrastructure needed to optimize them for regulatory compliance and efficiency.
Technology and Product Evolution
Single-use bioreactors and modular systems provide flexible and scalable production environments. Emerging biotechs focused on niche patient populations and personalized medicines are the fastest adopters of this technology. This adoption is miniaturizing the physical and capital footprint required for clinical-scale manufacturing, lowering barriers for developers of orphan drugs and advanced therapies to bring products to trial.
Regulatory and Policy Shift
Regulatory encouragement for continuous manufacturing from bodies like the US FDA is changing investment priorities. This official support provides a clearer validation pathway, de-risking capital investment in continuous bioprocessing equipment and facilities. The large-molecule drug substance segment is most affected, with leading CMOs building dedicated continuous processing suites to secure long-term contracts for high-volume biologics.
Demand-Side and Behavioral Shift
Strategic partnership models are displacing transactional, fee-for-service engagements. Biopharma clients increasingly seek integrated relationships where the CMO acts as an extension of their development team, co-managing process optimization and regulatory filings. This evolution is most prominent within the cell and gene therapy sector, where the manufacturing process is inseparable from the final product's clinical efficacy.
Contract Manufacturing Organization (CMO) Market Segmentation
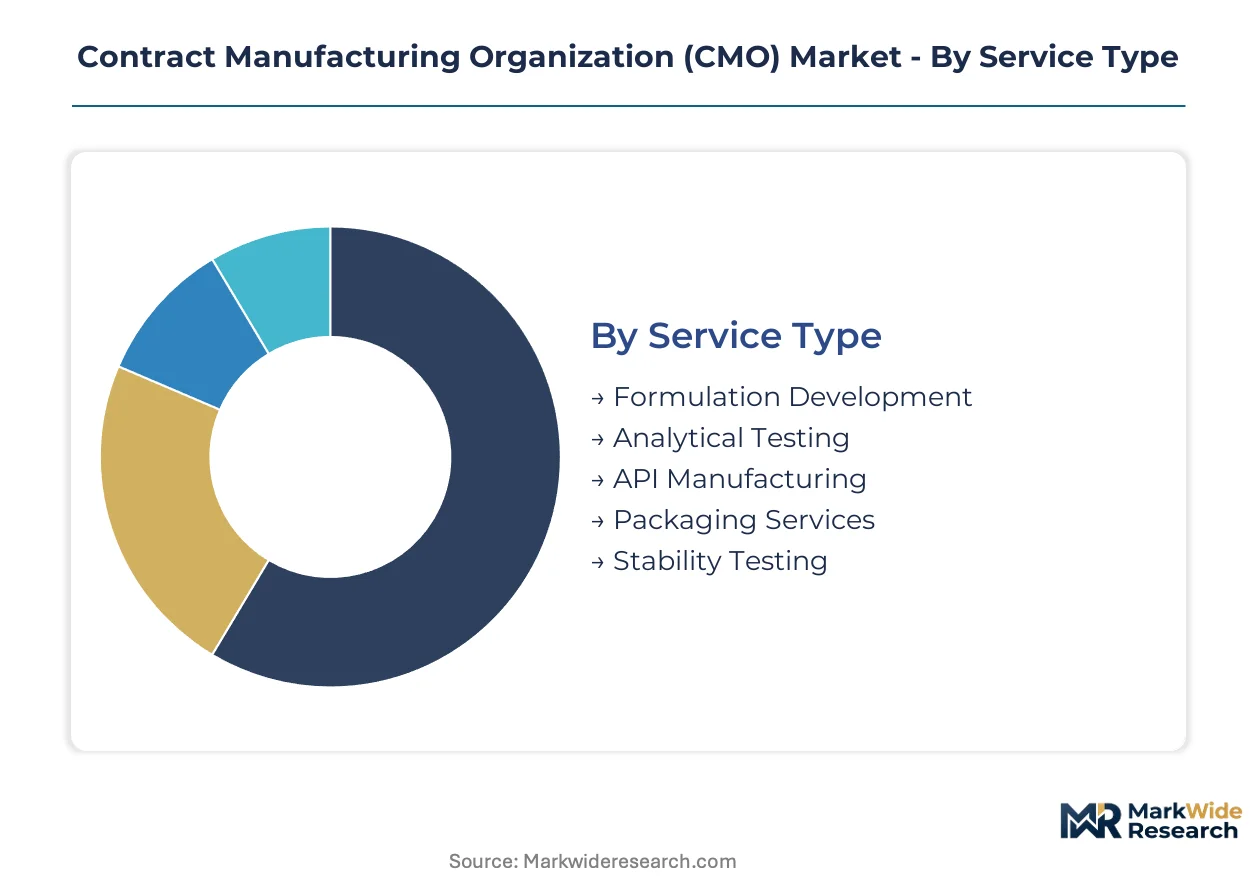
Understanding the Contract Manufacturing Organization (CMO) market through segmentation reveals where specialized capabilities are concentrated and how diverse client needs drive service evolution. This granular view highlights the distinct operational models and technological investments required to serve various therapeutic areas and client types effectively.
Service Type:
Margin pools within the service type category are highest for advanced formulation development and specialized API manufacturing services. These services demand significant intellectual capital and proprietary technology, allowing CMOs to command premium pricing. Analytical testing and stability testing also contribute to profitability by ensuring regulatory compliance and product quality throughout development.
- API Manufacturing:This foundational service involves the production of active pharmaceutical ingredients, the biologically active component of a drug. Demand for complex API manufacturing is rising as biopharmaceutical companies increasingly outsource synthesis of novel small molecules and biologics to specialized facilities.
- Formulation Development:CMOs provide expertise in converting active pharmaceutical ingredients into stable, effective, and patient-friendly dosage forms, including tablets, injectables, and advanced delivery systems. Investment in advanced formulation capabilities is accelerating to meet the needs of complex biologics and personalized medicines.
- Analytical Testing:Services include method development, validation, and routine quality control tests for raw materials, in-process samples, and finished products, ensuring compliance with cGMP standards. Rigorous analytical testing supports regulatory submissions to agencies like the US FDA and European Medicines Agency (EMA).
- Packaging Services:CMOs offer primary and secondary packaging solutions, including blistering, bottling, and sterile filling, often integrated with serialization capabilities for global supply chain security. Efficient packaging operations are critical for market distribution and patient safety.
- Stability Testing:This involves evaluating a drug product's quality over time under various environmental conditions to determine its shelf life and recommended storage conditions. Stability testing is a mandatory component of regulatory filings for new drug applications.
The dominant share belongs to API Manufacturing, while Formulation Development is closing the gap fastest.
Therapy Area:
The therapy area segment is defined by the specific medical conditions CMOs target, influencing facility design and regulatory expertise. Oncology programs command premium capacity due to their high value and complex handling requirements. Cardiovascular and neurology drugs also represent significant market segments, requiring specialized manufacturing processes.
- Oncology:This segment encompasses the manufacturing of drugs for cancer treatment, often involving highly potent compounds, complex biologics, and cell and gene therapies. High-value oncology pipelines drive significant demand for specialized, cGMP-compliant manufacturing capacity.
- Infectious Diseases:CMOs produce vaccines, antivirals, and antibiotics to combat bacterial, viral, and parasitic infections. The global focus on pandemic preparedness and emerging pathogens increases the need for rapid development and scalable production capabilities in this area.
- Cardiovascular:Manufacturing services for drugs treating heart and circulatory system conditions, including hypertension, cholesterol, and arrhythmias, remain a consistent demand driver. These therapies often require large-volume production and robust quality control.
- Neurology:This area involves the production of drugs targeting disorders of the nervous system, such as Alzheimer's, Parkinson's, and epilepsy. Manufacturing neurological products often requires specialized handling of sensitive compounds.
- Respiratory:CMOs provide manufacturing for drugs treating respiratory conditions like asthma, COPD, and cystic fibrosis, often involving specialized inhalation devices and sterile filling processes. This segment benefits from continuous innovation in drug delivery.
Oncology therapies drive the most significant investment, with Infectious Diseases demonstrating the steepest expansion trajectory.
Client Type:
The client type segmentation reflects the diverse needs of pharmaceutical companies, from large biopharmaceutical corporations to smaller biotechnology firms. Biopharmaceutical companies represent the largest outsourcing segment, seeking comprehensive manufacturing solutions. Biotechnology firms prioritize specialized capacity for novel advanced therapies.
- Biopharmaceutical Companies:These large enterprises outsource a significant portion of their drug substance and drug product manufacturing to optimize costs and access specialized technologies. Strategic partnerships with CMOs allow biopharmaceutical companies to manage their extensive pipelines efficiently.
- Biotechnology Firms:Typically smaller, innovation-driven companies focused on developing novel biologics, cell and gene therapies, and orphan drugs. Biotechnology firms rely heavily on CMOs for specialized manufacturing infrastructure and regulatory expertise they lack in-house.
- Generic Drug Manufacturers:These clients require cost-effective, high-volume manufacturing of off-patent drugs, often focusing on API synthesis and final dosage form production. Generic drug manufacturers seek CMOs with efficient processes and competitive pricing structures.
- Nutraceutical Producers:CMOs provide manufacturing services for dietary supplements, functional foods, and other health-promoting products, often requiring specific ingredient sourcing and formulation expertise. This segment emphasizes natural product processing and quality assurance.
- Veterinary Product Developers:This segment includes companies developing pharmaceuticals and biologics for animal health, requiring manufacturing facilities compliant with veterinary specific regulatory standards. CMOs offer specialized services for animal health products.
Biopharmaceutical Companies constitute the largest client base, while Biotechnology Firms are gaining share most quickly.
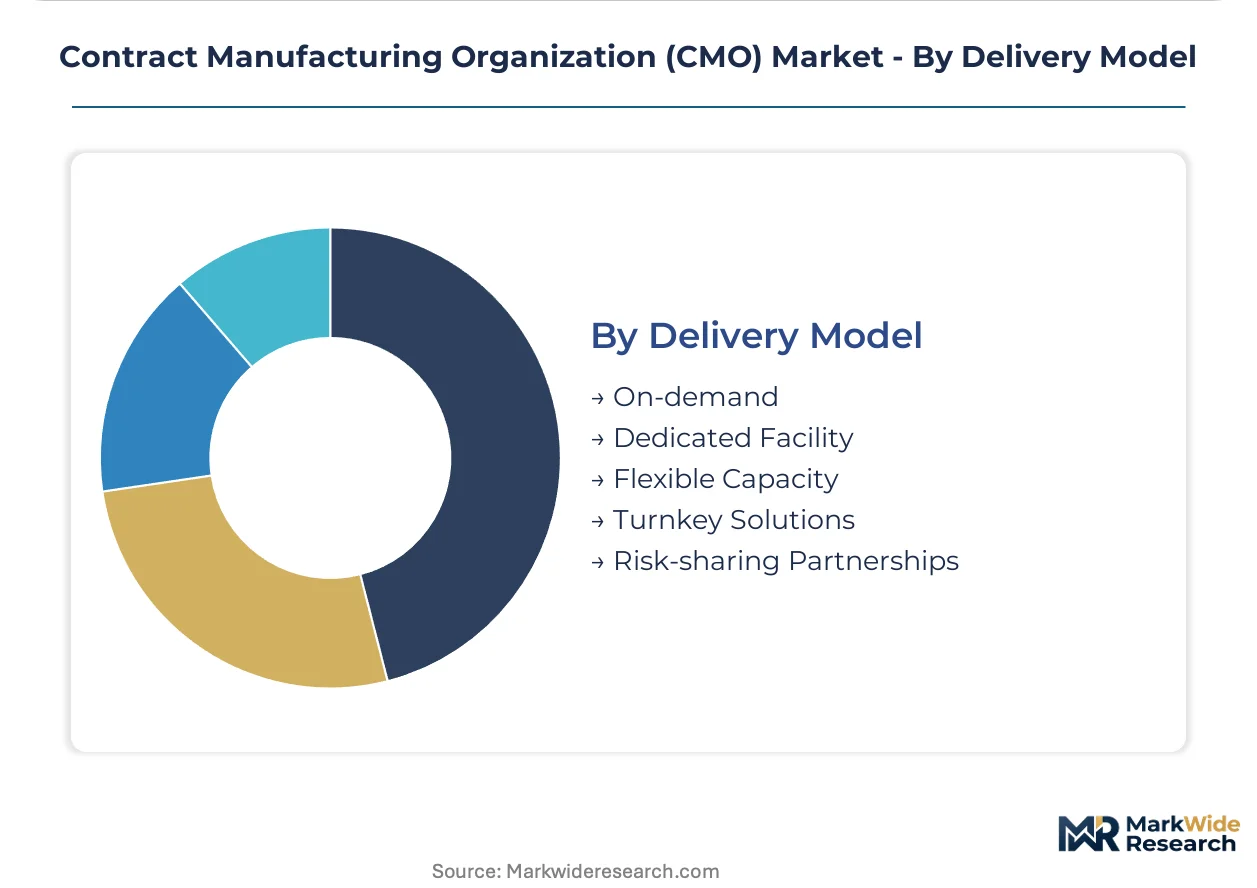
Delivery Model:
The delivery model category describes the operational frameworks CMOs offer to clients, ranging from flexible capacity arrangements to integrated risk-sharing partnerships. Dedicated facilities are preferred for blockbuster drugs requiring consistent, large-scale production. Risk-sharing partnerships align incentives and foster deeper collaboration for complex projects.
- Dedicated Facility:A CMO dedicates an entire manufacturing facility or a specific production line exclusively to one client's product, ensuring supply security and customized operational control. This model is common for high-volume blockbuster drugs or highly sensitive products.
- Risk-sharing Partnerships:These collaborative models involve CMOs sharing development costs, intellectual property, or commercial risks with clients, aligning incentives for successful product launch and market penetration. Such partnerships are increasingly prevalent in advanced therapy manufacturing.
- Flexible Capacity:CMOs offer adaptable manufacturing slots that can be scaled up or down based on client demand, suitable for clinical trial materials or products with fluctuating market needs. This model provides agility for smaller biotechs and clinical-stage programs.
- Turnkey Solutions:CMOs provide comprehensive, end-to-end services, handling all aspects from process development and manufacturing to quality control and regulatory submission. Turnkey solutions simplify the supply chain for clients seeking a single point of contact.
- On-demand:This model allows clients to access manufacturing services as needed, typically for smaller batches, urgent requirements, or specialized analytical services without long-term commitments. On-demand services support rapid prototyping and early-stage development.
Dedicated Facility models secure substantial contracts, with Risk-sharing Partnerships seeing the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the CMO market, with specialized biologics and advanced therapies commanding premium pricing due to high technical complexity. Conversely, generic API manufacturing often faces greater price sensitivity and commoditization. This divergence influences regional investment patterns and the types of manufacturing capacity developed in different geographies.
United States
A robust biopharmaceutical pipeline drives demand for complex biologics and cell and gene therapy manufacturing. The US FDA's accelerated approval pathways encourage rapid development and outsourced production. Boston and San Francisco Bay Area clusters concentrate advanced therapy manufacturing and process development expertise.
Germany
Europe's largest pharmaceutical market generates consistent demand for both small-molecule APIs and biologics. EMA guidelines ensure stringent quality standards, influencing facility investments by CMOs. The Rhine-Main region, particularly around Frankfurt, hosts significant pharmaceutical production and R&D activities.
Switzerland
High-value biologics and precision medicine manufacturing anchor significant CMO investments in this region. Swissmedic provides a favorable regulatory environment for specialized pharmaceutical production. Basel acts as a major biopharmaceutical hub, attracting capital for advanced manufacturing facilities.
Japan
An aging population and strong domestic pharmaceutical industry create sustained demand for innovative drug products. PMDA regulations emphasize quality and safety, requiring advanced manufacturing capabilities. The Kansai region, including Osaka, fosters a strong ecosystem for pharmaceutical research and production.
India
Generic drug manufacturing and vaccine production drive substantial CMO activity, alongside emerging biologics capabilities. The PLI scheme encourages domestic API production and pharmaceutical exports. Hyderabad and Ahmedabad are key pharmaceutical manufacturing centers, supporting diverse production needs.
Contract Manufacturing Organization (CMO) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the CMO market, creating a tiered competitive structure. Large, integrated CMOs offer comprehensive services for complex biologics and advanced therapies, requiring substantial capital investment. Smaller, specialized firms often focus on niche API manufacturing or specific formulation challenges, competing on agility and specialized expertise. Strategic partnerships, capacity expansion, and portfolio diversification represent dominant competitive moves for market participants.
Within the high-value biologics segment, Lonza Group exemplifies a large-scale player specializing in complex drug substance manufacturing, including advanced cell and gene therapies. This Swiss-based entity anchors significant upfront capital expenditure into specialized facilities. Catalent, Inc. occupies a position as a global network provider, leveraging its extensive facilities for a wide range of formulation and advanced drug delivery technologies across multiple geographies. Conversely, Siegfried AG represents a specialized focus on active pharmaceutical ingredient (API) manufacturing for small molecules. This archetype caters to distinct operational demands and capital requirements, often serving a broader client base with different product portfolios.
| Leading Market Players |
|---|
| Samsung Biologics |
| Siegfried |
| Lonza Group |
| Boehringer Ingelheim |
| Fujifilm Biotechnologies |
| Thermo Fisher Scientific |
| WuXi Biologics |
| AGC Biologics |
| Catalent |
| Others |
Cost & Logistics Intelligence
Single-use bioreactors replacing traditional stainless-steel systems are reshaping CMO supply chains, driving investment towards specialized manufacturing hubs and influencing pricing for flexible capacity. This technological shift impacts both material sourcing and the cost structures for biopharmaceutical production.
Pricing Analysis
Long-term process optimization support frequently drives the lifetime value for CMO engagements, extending beyond initial manufacturing contracts. Contract-based long-term offtake agreements dominate pricing models, particularly for high-volume biologics. Price differentiation stems from cGMP compliance levels and the inherent process complexity of advanced therapies. Pricing softness affects generic API manufacturing due to high competition from Asian producers, while biopharmaceutical companies developing novel biologics exhibit lower price sensitivity.
Supply Chain Analysis
Inbound logistics costs for specialized raw materials, particularly for cell culture media and single-use components, influence CMO operational expenditures. Geographic supply concentration for critical APIs primarily resides in India and China, while advanced bioprocessing components often source from European hubs like Switzerland. Single-source vulnerability for specialized cell culture media creates a structural risk. Distribution runs through direct shipments to client-controlled final fill-finish sites or regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CMO market is experiencing a buyer-power shift as biopharmaceutical companies increasingly consolidate their manufacturing needs into strategic, long-term partnerships. This trend favors integrated service providers capable of end-to-end solutions.
For Market Incumbents: Fortify existing market share by aggressively investing in continuous bioprocessing capabilities and expanding dedicated capacity for advanced therapy medicinal products (ATMPs). This defends against emerging specialized entrants and addresses the talent scarcity in complex biologics. Leverage certification investment for US FDA and EMA compliance to secure long-term contracts. Prioritize R&D in process analytical technology to enhance real-time quality control.
For New Entrants and Emerging Players: Anchor in niche API manufacturing segments or specialized flexible capacity for orphan drugs, which represent significant white-space opportunities. The most penetrable segment involves supporting early-stage biotechnology firms with complex formulation development. A compelling go-to-market angle involves offering integrated R&D support, acting as an extension of the client's internal development team. This strategy leverages agility over scale.
For Investors and Strategic Acquirers: The market sits at a high-growth phase that favors specialized, technology-forward CMOs, indicating strong long-term viability over the next 5-10 years. Acquisition targets should focus on mid-sized CMOs with established advanced therapy medicinal product (ATMP) capacity or proprietary advanced formulation expertise. The signal to watch is the increasing number of regulatory approvals for novel biologics and cell and gene therapies, validating investment in these complex areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for ATMPs | Secures future demand from high-value cell and gene therapy developers. |
| Digitalization of Production Floors | Optimizes operational efficiency and quality control across multi-product facilities. |
| End-to-End Service Integration | Captures greater client value across the entire drug development lifecycle. |
| Investment in Continuous Bioprocessing | Attracts large-molecule drug substance contracts requiring enhanced efficiency. |
| Talent Development Programs | Addresses critical scarcity of specialized scientists and technicians in biologics. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, CMO operations managers, and biopharmaceutical procurement leads converged on the working assumptions for this analysis. This involved combining insights from primary interviews with extensive secondary validation. Secondary data sources included US FDA filings, EMA submissions, industry association reports, and financial disclosures. Bottom-up and top-down triangulation ensured robust market sizing and growth projections.
Service Type, Therapy Area, Client Type, Delivery Model, and regional regulatory compliance represented the segmentation dimensions modeled across the analysis window. The analytical framework integrated demand-side and supply-side dynamics. Compound Annual Growth Rates (CAGRs) were derived through a regression analysis of historical trends and projected future demand. Key forecast inputs included pipeline drug approvals and biopharmaceutical R&D spending.
Material uncertainties — unforeseen regulatory changes, rapid technological disruptions, or global health crises — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable geopolitical environments and consistent R&D investment trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Aged Care Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Hospital Workforce Management Market