
 3D Cardiac Mapping Systems Market | 2026-2036
3D Cardiac Mapping Systems Market Size, Share, and Industry Trends Forecast 2026-2036
3D Cardiac Mapping Systems Market Intelligence
Software-defined mapping modules with subscription-based analytics is expanding the recurring revenue base for system vendors. Biosense Webster leverages its integrated catheter-electronics ecosystem to sustain high switching costs among electrophysiologists. Abbott Laboratories anchors its competitive position through proprietary contact force technology that differentiates ablation outcomes. Boston Scientific competes aggressively on hospital capital equipment financing while Philips navigates the convergence of imaging and mapping workflows.
3D cardiac mapping systems create real-time, patient-specific geometric reconstructions of cardiac chambers using electroanatomical or image-based tracking, with spatial resolution typically below one millimeter and frame rates exceeding 100 Hz to guide catheter navigation during arrhythmia procedures. Electrophysiology mapping systems occupy the largest installed base and margin pool, while software solutions represent the fastest-expanding segment as hospitals seek cloud-based case archiving and AI-assisted signal interpretation. Ablation catheters command premium pricing tied to disposable utilization, whereas imaging systems face longer replacement cycles and greater capital scrutiny.
FDA 510(k) and premarket approval pathways govern system commercialization in the United States, while the EU MDR and CE marking requirements impose stricter clinical evidence standards for active implantable accessories. Japan's PMDA maintains distinct quality management system audits that extend timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for complex ablation procedures and anticipate how integrated AI diagnostic modules trigger new regulatory classification thresholds.
Market Dynamics
Software-defined mapping architectures are compressing hardware replacement cycles while subscription analytics recalibrate vendor revenue models toward recurring streams.
Growth Catalysts
- Catheter ablation volume expansion:Tertiary electrophysiology laboratories in the United States, Germany, and Japan are scaling procedure throughput for atrial fibrillation, directly expanding installed base requirements for navigation platforms.
- MDR clinical evidence pathways:The EU Medical Device Regulation mandates enhanced safety documentation for active implantable accessories, accelerating hospital procurement of next-generation systems with pre-validated compliance bundles.
- Cloud-based case archiving:Hospital IT departments are prioritizing interoperable data infrastructure, pulling demand toward mapping vendors offering integrated PACS connectivity and remote proctoring capabilities.
Market Restraints
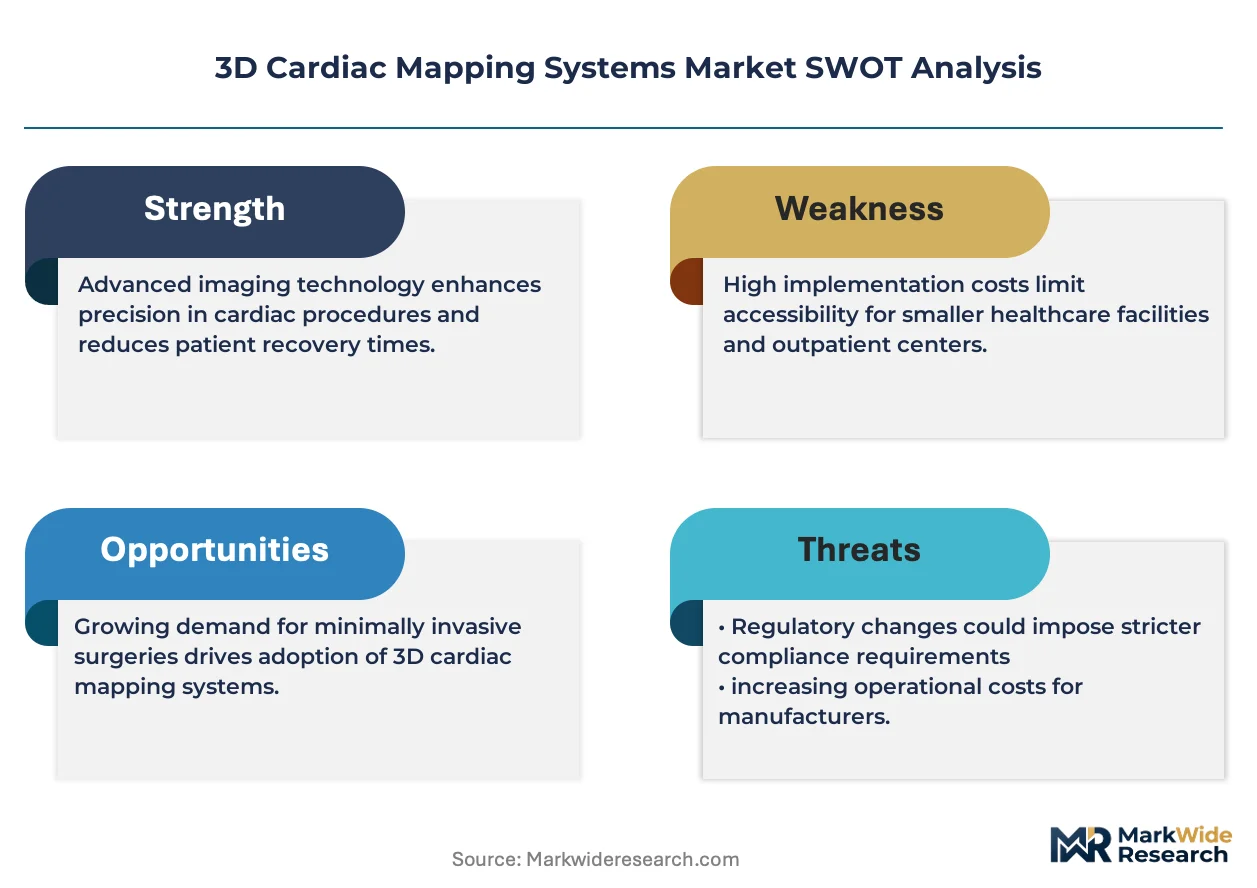
- Capital equipment financing constraints:Elective procedure deferrals during reimbursement uncertainty have tightened hospital capital committees, elongating sales cycles for imaging-integrated mapping suites.
- Disposable catheter supply concentration:Ablation catheter manufacturing clusters in specific European and North American contract manufacturing regions create vulnerability to sterile barrier material shortages.
- Signal processing latency limitations:Current electroanatomical mapping frame rates constrain real-time visualization during high-density mapping of complex atrial substrates.
Strategic Opportunities
- AI-assisted signal interpretation:Machine learning modules for automated arrhythmia mechanism classification are opening differentiation vectors beyond hardware specifications.
- Japan PMDA quality management audits:Foreign manufacturers completing extended certification timelines gain durable competitive insulation against late entrants.
- Hybrid operating room convergence:Integration of fluoroscopy reduction protocols with surgical ablation workflows is creating new specification requirements for multi-modal navigation systems.
Industry Challenges
- Electrophysiologist training pipeline:Fellowship program capacity constraints limit the specialist workforce required to operate advanced mapping platforms at scale.
- FDA 510(k) predicate device navigation:Evolving substantial equivalence standards for software-as-medical-device components complicate clearance strategies for algorithm-enhanced mapping modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Cardiac Mapping Systems Market |
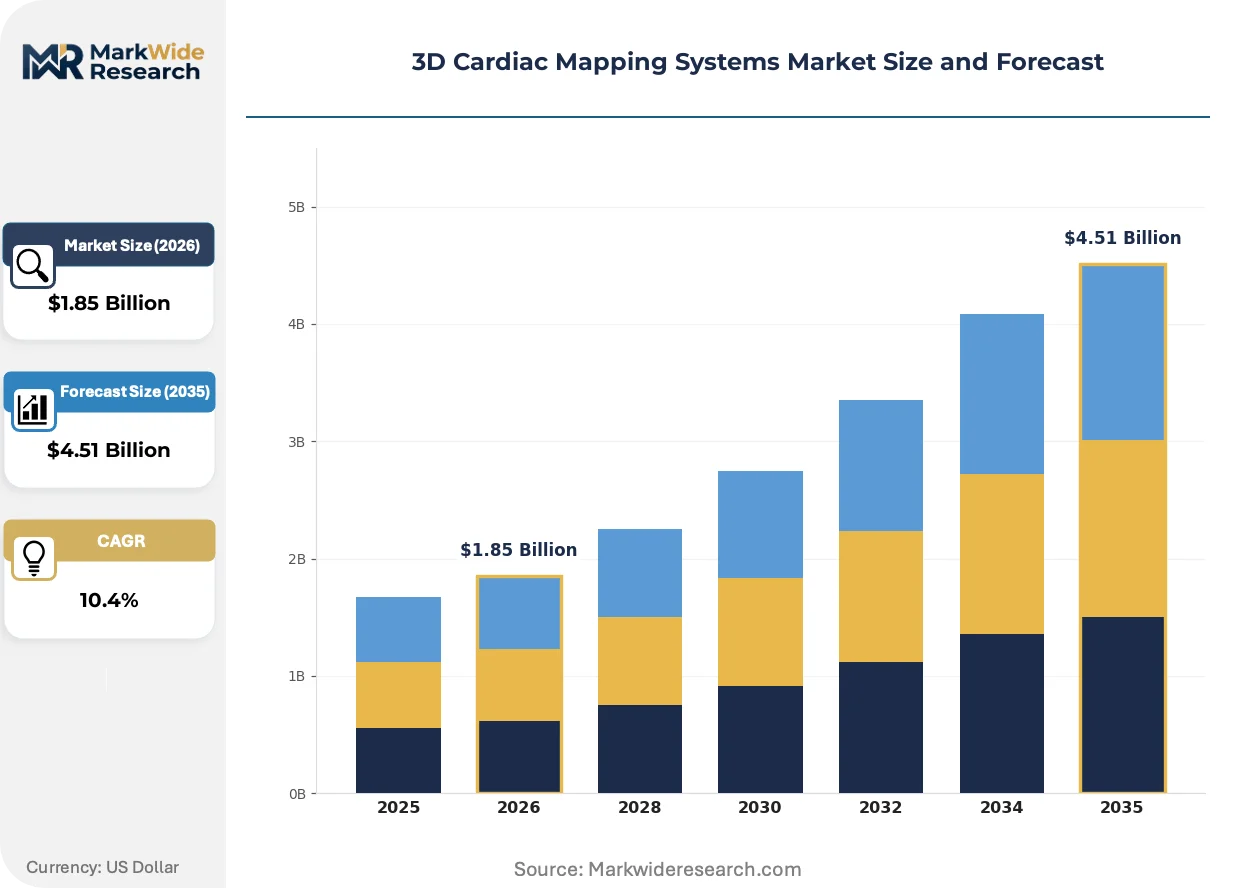
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrophysiology Mapping Systems, Imaging Systems, Software Solutions, Ablation Catheters End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Research Institutions Technology: Electroanatomical Mapping, Magnetic Resonance, Fluoroscopy, Ultrasound Application: Arrhythmia Management, Atrial Fibrillation, Heart Failure, Ventricular Tachycardia |
| Companies Covered | Medtronic plc, Biotronik SE & Co. KG, Biosense Webster Inc., MicroPort Scientific Corporation, Kardium Inc., Abbott Laboratories, Acutus Medical Inc., Koninklijke Philips N.V., Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Cardiac Mapping Systems Market Strategic Shifts & Innovations
Computational methods are displacing manual electrogram annotation while regulatory frameworks recalibrate around software-intensive medical devices.
Artificial intelligence is automating the detection and classification of fractionated electrograms during atrial fibrillation mapping. Academic medical centers in the United States and Western Europe are piloting these modules within existing Biosense Webster and Abbott Laboratories installations. The technology is automating previously labor-intensive signal interpretation, compressing procedure duration and reducing operator-dependent variability in ablation endpoint determination.
The EU Medical Device Regulation imposes stricter clinical evidence requirements for active implantable accessories than its predecessor directive. System vendors must now generate prospective safety data for catheter-electronics combinations, extending development timelines by twelve to eighteen months. Electrophysiology laboratories in Germany and France are prioritizing MDR-certified platforms to preempt procurement compliance risks.
Hospital purchasing committees are consolidating vendor relationships around integrated catheter-system ecosystems rather than best-of-breed component sourcing. Tertiary centers in Japan and the United States are negotiating multi-year disposable supply agreements tied to exclusive mapping platform commitments. This concentration is visible most acutely in high-volume ablation centers where switching costs encompass retraining, protocol revision, and outcomes data continuity.
3D Cardiac Mapping Systems Market Segmentation
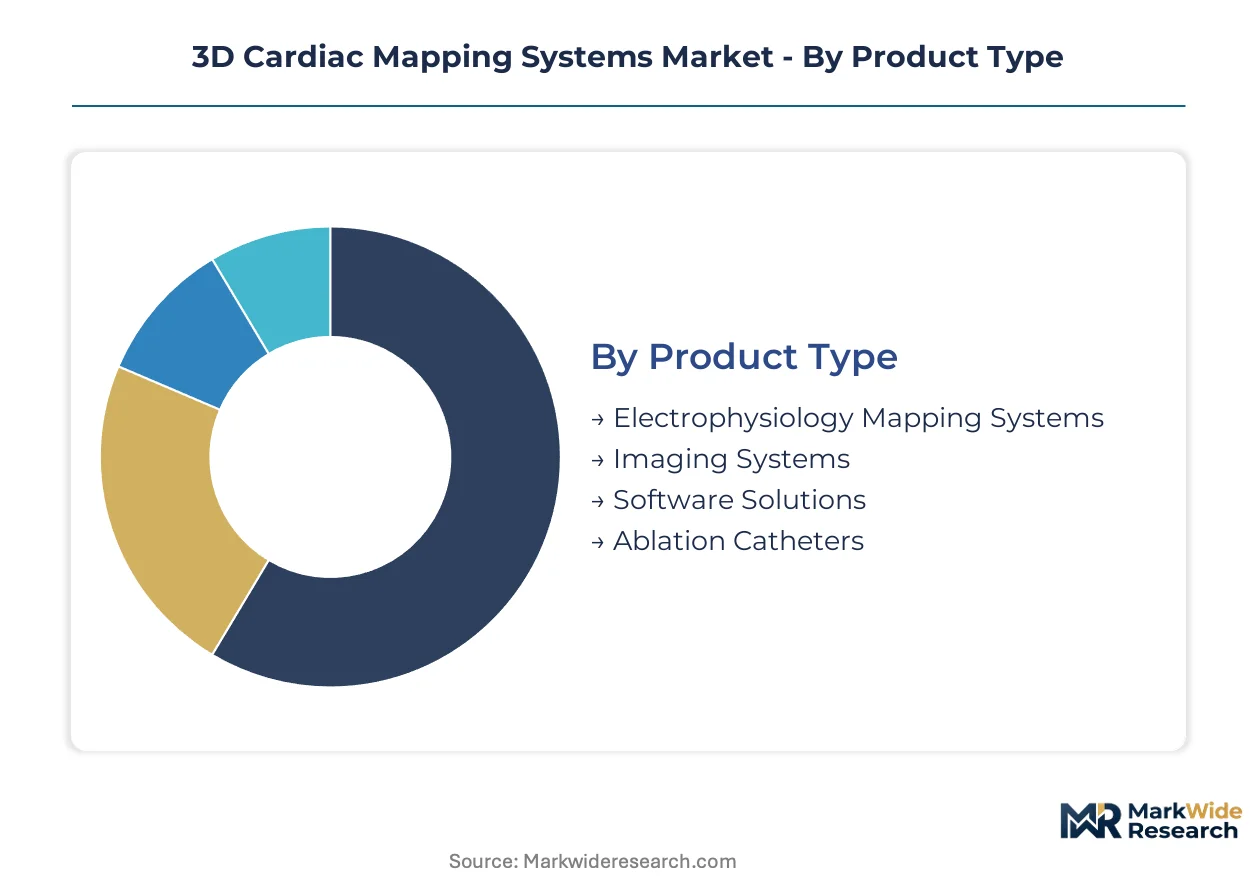
Segmentation in 3D cardiac mapping systems reveals how procurement committees balance capital intensity against clinical workflow integration. Vendor strategies diverge sharply across these dimensions, with hardware platforms demanding long sales cycles while software modules penetrate through subscription models.
Product Type:
The customization-to-standardization spectrum runs from fully configurable electrophysiology platforms to commoditized disposable catheters with fixed specifications.
- Electrophysiology Mapping Systems:These platforms generate real-time electroanatomical reconstructions using catheter-localization algorithms with submillimeter spatial resolution. Tertiary hospitals in the United States and Germany concentrate procurement around integrated systems that bundle navigation with proprietary catheter ecosystems, driven by electrophysiologist training investments and outcomes data continuity requirements.
- Software Solutions:Cloud-native mapping modules with AI-assisted signal interpretation enable remote case archiving and predictive analytics without hardware replacement. Demand is concentrating in hospital systems prioritizing IT interoperability and value-based care reporting, with subscription revenue models displacing perpetual licenses.
- Imaging Systems:Intracardiac echocardiography and rotational angiography platforms provide anatomical visualization complementary to electroanatomical mapping.
- Ablation Catheters:Radiofrequency and cryoablation disposables command premium pricing tied to procedure volume rather than capital budgets.
Leading the category by volume: Ablation Catheters. Expanding most quickly: Software Solutions.
End User:
Facility type determines capital access, procedure complexity, and vendor relationship depth across the installed base.
- Hospitals:Academic medical centers and tertiary community hospitals house the dominant installed base of integrated mapping suites, with electrophysiology laboratories performing high-complexity ablation volumes that justify seven-figure capital investments and multi-year disposable supply agreements.
- Ambulatory Surgical Centers:These facilities concentrate simpler diagnostic electrophysiology studies and straightforward ablation procedures, constrained by reimbursement codes that limit capital equipment depreciation schedules and favor mobile C-arm fluoroscopy over fixed mapping platforms.
- Cardiology Clinics:Outpatient settings focus on diagnostic mapping and patient selection for referral to hospital-based ablation.
- Research Institutions:Academic consortia pilot next-generation mapping algorithms and hybrid ablation techniques prior to commercial translation.
Highest capital deployment per site: Hospitals. Fastest facility-type expansion: Ambulatory Surgical Centers.
Technology:
Tracking modality selection reflects trade-offs between anatomical fidelity, radiation exposure, and real-time latency.
- Electroanatomical Mapping:Contact-based impedance or magnetic field localization reconstructs cardiac geometry from catheter position data, with frame rates exceeding 100 Hz enabling dynamic substrate mapping during arrhythmia. United States and Japanese electrophysiology laboratories dominate adoption, prioritizing fluoroscopy reduction protocols.
- Magnetic Resonance:Pre-procedural MRI integration enables patient-specific anatomical modeling and scar tissue characterization, particularly for ventricular tachycardia substrate mapping in heart failure populations.
- Fluoroscopy:X-ray guidance remains ubiquitous for catheter visualization despite radiation dose concerns, concentrated in cost-constrained settings and emergency procedures.
- Ultrasound:Intracardiac echocardiography provides real-time soft-tissue imaging without ionizing radiation, increasingly bundled with electroanatomical platforms.
Dominant installed base technology: Electroanatomical Mapping. Steepest expansion trajectory: Magnetic Resonance integration.
Application:
Clinical indication drives mapping density requirements, procedure duration, and reimbursement intensity.
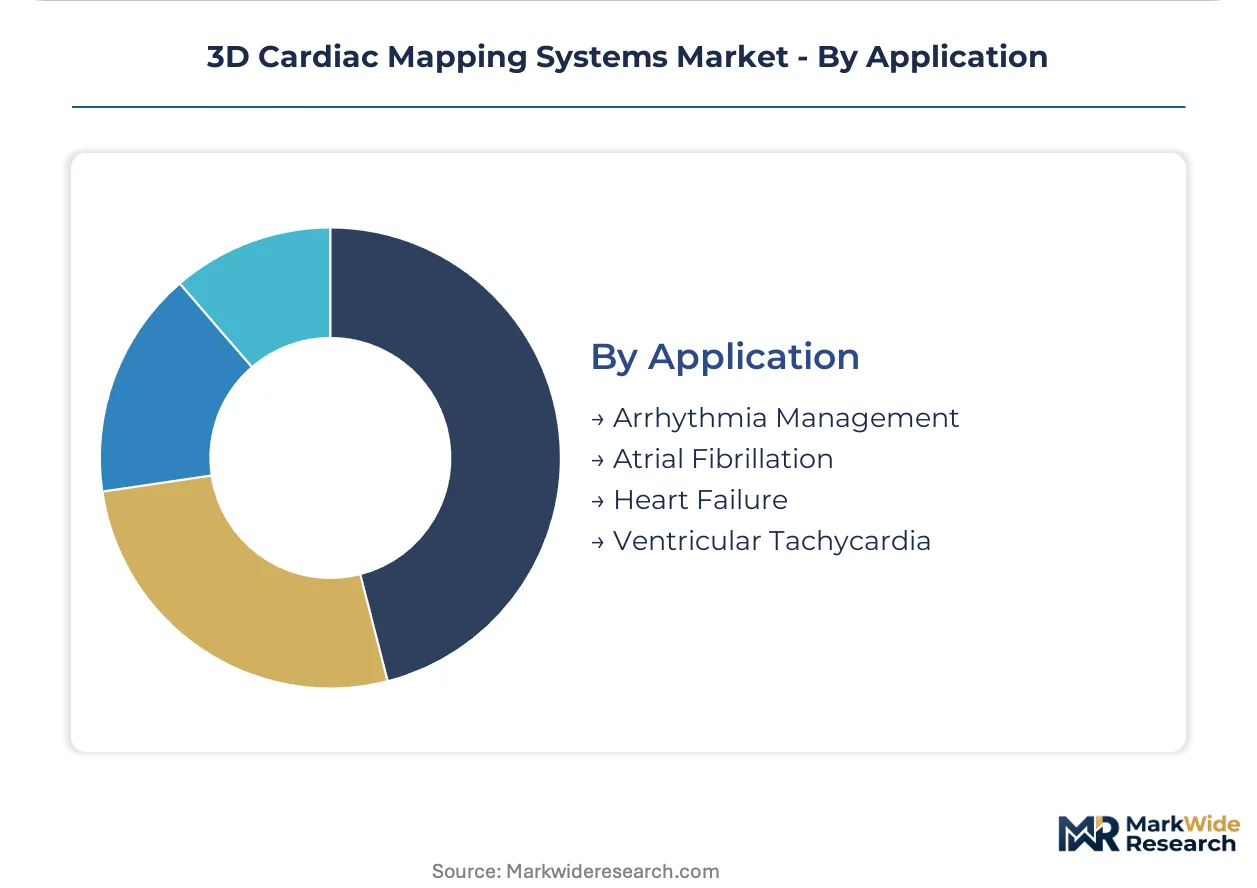
- Atrial Fibrillation:This arrhythmia category generates the largest procedure volume and highest mapping system utilization, with pulmonary vein isolation requiring precise left atrial reconstruction and complex fractionated atrial electrogram analysis. German and Japanese reimbursement frameworks specifically incentivize catheter ablation as first-line rhythm control therapy.
- Ventricular Tachycardia:Scar-related arrhythmias in ischemic cardiomyopathy demand high-density epicardial and endocardial mapping with hemodynamic support, concentrating in specialized centers with hybrid operating room capabilities.
- Arrhythmia Management:Broad diagnostic and therapeutic category encompassing supraventricular tachycardia and accessory pathway ablation.
- Heart Failure:Emerging application for cardiac resynchronization optimization and autonomic modulation mapping.
Largest procedure volume: Atrial Fibrillation. Fastest clinical application growth: Ventricular Tachycardia ablation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleveland Clinic anchors global electrophysiology innovation, with its arrhythmia center driving mapping system validation protocols that diffuse across academic medical centers worldwide.
United States
Catheter ablation volumes for atrial fibrillation at tertiary centers in Cleveland and Boston are expanding installed base requirements for navigation platforms. FDA 510(k) clearance pathways govern commercialization timelines for algorithm-enhanced mapping modules. The Texas Medical Center in Houston concentrates multi-site electrophysiology consortiums piloting AI-assisted signal interpretation prior to national rollout.
Germany
Electrophysiology laboratories in Berlin and Munich are scaling procedure throughput under reimbursement frameworks that incentivize catheter ablation as first-line rhythm control therapy. EU MDR certification requirements impose stricter clinical evidence standards for active implantable accessories than predecessor directives. The Rhine-Ruhr corridor houses concentrated procurement committees prioritizing MDR-certified platforms to preempt compliance risks.
Japan
PMDA quality management system audits extend certification timelines for foreign manufacturers, creating durable competitive insulation for early entrants. METI funding programs support domestic medical device innovation clusters in Tokyo and Osaka. The Kansai region concentrates high-volume ablation centers negotiating multi-year disposable supply agreements tied to exclusive platform commitments.
United Kingdom
NHS England specialized commissioning frameworks are consolidating electrophysiology service provision into designated cardiac centers in London and Manchester. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, requiring parallel conformity assessment strategies. The Oxford-Cambridge arc anchors academic consortia validating next-generation mapping algorithms prior to commercial translation.
France
ANSM oversight of active implantable medical devices mandates enhanced safety documentation for catheter-electronics combinations entering Paris and Lyon electrophysiology laboratories. HAS reimbursement assessments influence hospital capital equipment procurement priorities. The Grenoble-Alps cluster concentrates contract manufacturing for sterile barrier materials serving European ablation catheter supply chains.
3D Cardiac Mapping Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the mapping system value chain. The vendor base concentrates around integrated catheter-platform ecosystems rather than modular component sourcing. Three archetypes dominate: diversified medical technology conglomerates with electrophysiology divisions, specialized electrophysiology pure-plays, and imaging system vendors extending into navigation workflows. Competitive intensity manifests through exclusive supply agreements with high-volume ablation centers and strategic partnerships around AI module development.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify the integrated ecosystem archetype, anchoring competitive positioning through proprietary catheter-electronics combinations. Boston Scientific Corporation occupies a position within the specialized electrophysiology tier, while Koninklijke Philips N.V. represents imaging-to-navigation convergence strategies. These three entities collectively illustrate how vendor strategies diverge between disposable utilization models and capital equipment financing approaches.
| Leading Market Players |
|---|
| Medtronic plc |
| Biotronik SE & Co. KG |
| Biosense Webster Inc. |
| MicroPort Scientific Corporation |
| Kardium Inc. |
| Abbott Laboratories |
| Acutus Medical Inc. |
| Koninklijke Philips N.V. |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between MDR-validated integrated systems and legacy hardware creates tiered procurement economics that concentrate vendor pricing power in compliant European supply corridors while compressing margins for non-validated alternatives. This bifurcation channels hospital purchasing committees toward pre-certified platform ecosystems that bundle disposable catheters with navigation hardware, reshaping both supplier qualification requirements and capital equipment financing structures across German and French electrophysiology laboratories.
Pricing Analysis
Margin tightening in imaging-integrated mapping suites reflects elongated hospital capital committee cycles and elective procedure deferrals during reimbursement uncertainty. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and proprietary catheter-electronics bundling intensity. Cost-down pressure on software modules accelerates as cloud-native subscription models displace perpetual licenses, with ambulatory surgical centers exhibiting highest price sensitivity and academic medical centers least.
Supply Chain Analysis
ISO 13485 and MDR quality management certification gates concentrate sterile barrier material sourcing and catheter electronics assembly in Germany, France, and Switzerland. Manufacturing draws from specialized polymer suppliers for catheter shafts, magnetic sensor arrays for localization, and semiconductor components for signal processing. Single-source vulnerability in European contract manufacturing regions for sterile barrier films creates exposure to material qualification delays. Distribution runs through exclusive supply agreements with high-volume ablation centers and GPO-negotiated hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation imposes twelve-to-eighteen-month development timeline extensions for active implantable accessories, erecting compliance moats that favor incumbents with pre-validated platform ecosystems and capital reserves for prospective clinical evidence generation.
For Market Incumbents: Deepen proprietary catheter-electronics integration to sustain high switching costs among electrophysiologists trained on specific navigation workflows. Fortify MDR certification portfolios ahead of predicate device obsolescence. Expand exclusive disposable supply agreements with German and Japanese high-volume centers to preempt competitive platform displacement.
For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable buyer archetype given constrained capital budgets and preference for mobile C-arm compatibility over fixed mapping suites. Target cloud-native software modules with AI-assisted signal interpretation to bypass hardware replacement cycles. Pursue strategic partnerships with existing imaging system vendors for workflow integration rather than direct platform competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking electrophysiology portfolio expansion. Long-term viability hinges on sustained catheter utilization volumes and software subscription retention. Monitor FDA substantial equivalence determinations for algorithm-enhanced mapping modules as inflection indicator for regulatory classification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Pre-validated compliance bundles accelerate hospital procurement in German electrophysiology laboratories. |
| AI Module Development | Automated arrhythmia classification differentiates beyond hardware specifications at Cleveland Clinic pilots. |
| Hospital System Partnership | Multi-year disposable agreements with Texas Medical Center consortiums lock in platform exclusivity. |
| Software Companion Development | Cloud-based case archiving with PACS connectivity pulls demand from hospital IT prioritization. |
| Reimbursement Strategy | Complex ablation procedure code alignment shapes capital equipment depreciation justification. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and electrophysiology society procedure registries, complemented by interviews with electrophysiologists, biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at system vendors. Secondary validation drew from CMS Medicare reimbursement data, Japanese PMDA quality management audit reports, and catheter ablation volume statistics. Bottom-up installed base modeling and top-down market sizing triangulated revenue estimates.
Historical catheter ablation volume trajectories cross-referenced against panel input from electrophysiology laboratory directors established procedure growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, tracking technology modality, and clinical application intensity. CAGRs derived from logarithmic interpolation of value outputs across the modeling period, with specific inputs for software subscription renewal rates and disposable catheter utilization per procedure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrophysiologist fellowship pipeline constraints, evolving FDA substantial equivalence standards for software-as-medical-device components, and sterile barrier material supply disruptions. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway predictability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Implantable Infusion Pumps Market