
 AI-Enabled Diagnostic Imaging Market | 2026-2036
AI-Enabled Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Enabled Diagnostic Imaging Market Outlook
Class II diagnostic-grade algorithm certification is collapsing the barrier between experimental AI and reimbursable clinical workflow. Siemens Healthineers leverages its installed base of imaging hardware to bundle AI modules directly at the point of image acquisition. GE Healthcare anchors its competitive position through Edison platform integration, which sustains recurring revenue from algorithm deployment across hospital networks.
AI-enabled diagnostic imaging deploys deep learning convolutional neural networks and computer vision pipelines to detect, segment, and classify pathological patterns in DICOM-standard medical images, operating at inference latencies under thirty seconds per study to support real-time radiologist decision-making. CT scanner-integrated AI for lung nodule and stroke detection commands the largest current revenue pool, while neurology applications for MRI-based tumor and neurodegenerative disease classification represent the fastest-expanding segment due to higher reimbursement complexity and unmet diagnostic precision needs. Deep learning architectures dominate technology deployment, though natural language processing for automated radiology report generation is gaining structural importance as health systems prioritize operational efficiency.
FDA Software as a Medical Device frameworks, EU MDR Class IIa/IIb certification requirements, and China's NMPA AI medical device approval pathways collectively determine market access timelines and clinical evidence burdens for algorithm developers. These regulatory regimes enforce algorithmic transparency, prospective validation datasets, and post-market performance monitoring that shape R&D investment priorities across the industry. Stakeholders must monitor evolving reimbursement codes for autonomous AI reads versus physician-augmented interpretations, as payer policy will determine whether algorithm vendors capture value through subscription fees or per-study transactional pricing.
Market Dynamics
FDA 510(k) clearance pathways for Software as a Medical Device are compressing time-to-market for diagnostic algorithms while EU MDR Class IIa/IIb requirements impose parallel clinical evidence burdens that reshape vendor R&D allocation.
Growth Catalysts
- Hospital digitization budgets:Radiology departments in the United States, China, and Germany are accelerating capital deployment for AI-augmented CT and MRI interpretation tools.
- Autonomous reimbursement codes:Emerging payer policies for physician-augmented versus autonomous AI reads are creating transactional revenue streams for algorithm vendors.
- Inference latency thresholds:Sub-thirty-second study processing speeds are enabling real-time radiologist decision support and expanding addressable use cases.
Market Restraints
- Regulatory fragmentation:Divergent FDA, EU MDR, and NMPA approval pathways force redundant clinical validation studies that extend commercialization timelines.
- GPU compute costs:Deep learning training and inference workloads depend on concentrated NVIDIA supply chains subject to export control volatility.
- Algorithmic transparency mandates:Post-market performance monitoring requirements under EU AI Act and FDA guidance increase ongoing compliance overhead.
Strategic Opportunities
- Neurology MRI applications:Tumor and neurodegenerative disease classification segments face unmet diagnostic precision needs and complex reimbursement structures.
- Natural language processing convergence:Automated radiology report generation is gaining structural importance as health systems prioritize operational efficiency metrics.
- India's diagnostic network expansion:Teleradiology platforms and tier-two hospital digitization create deployment channels for cloud-based AI screening tools.
Industry Challenges
- DICOM-HL7 integration complexity:Legacy PACS infrastructure in established health systems requires costly middleware development for seamless AI workflow embedding.
- Radiologist-AI interaction design:User interface standardization for algorithmic confidence scoring and alert prioritization remains immature across vendor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Enabled Diagnostic Imaging Market |
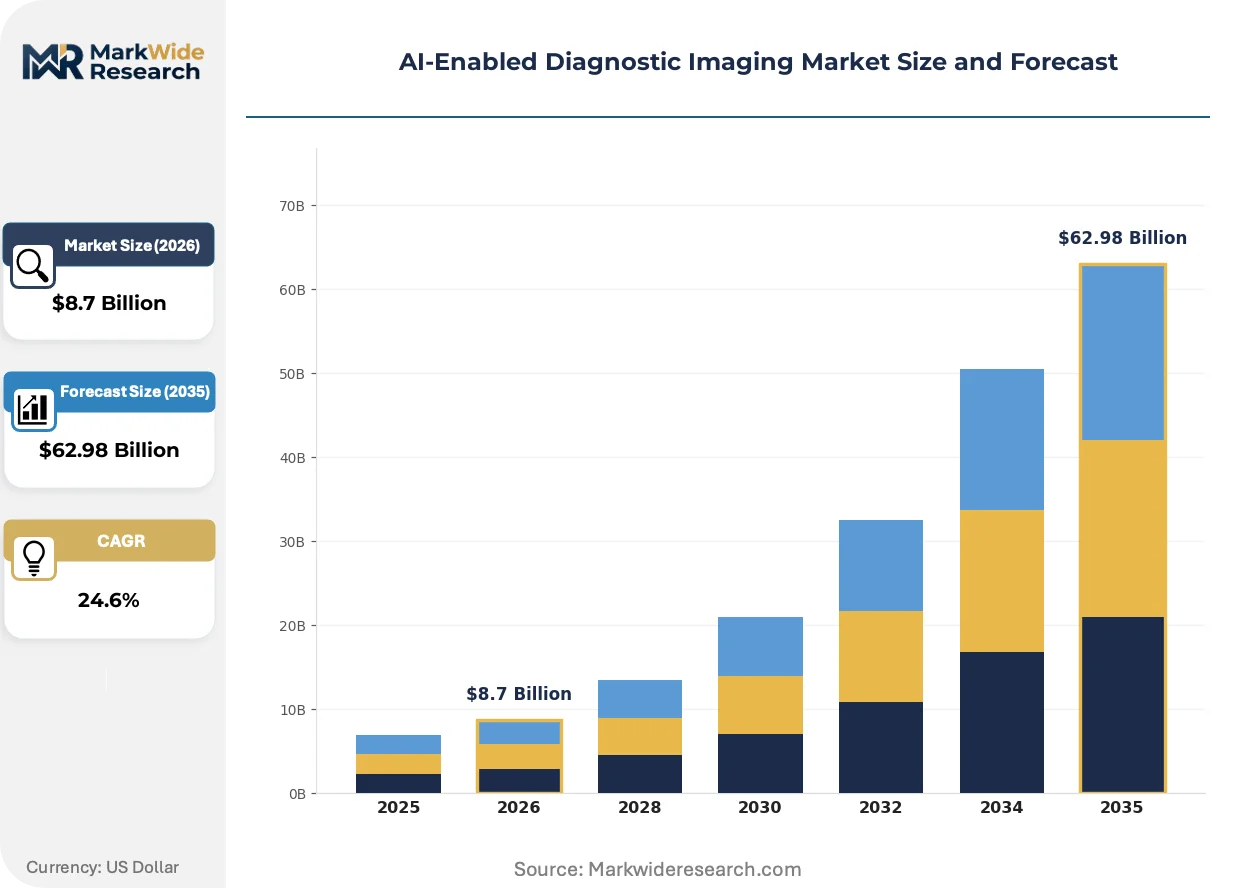
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Machines, Ultrasound Devices, X-Ray Systems Technology: Deep Learning, Computer Vision, Natural Language Processing, Machine Learning Application: Neurology, Oncology, Cardiology, Orthopedics End User: Hospitals, Imaging Centers, Research Laboratories, Outpatient Clinics |
| Companies Covered | Aidoc, United Imaging, Siemens Healthineers, Lunit, HeartFlow, GE Healthcare, Viz.ai, Qure.ai, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Enabled Diagnostic Imaging Market Strategic Shifts
Deep learning architectures are fragmenting into specialized pipelines while regulatory jurisdictions compete to define algorithmic accountability standards. Three developments are restructuring competitive positioning and value capture mechanisms.
Federated learning architectures for multi-site model training without centralizing patient data are bifurcating vendor strategies between cloud-native deployment and on-premise edge computing. Academic medical centers in Germany and the United States are piloting privacy-preserving collaboration frameworks. This technology is compressing the traditional data moat advantage of large integrated delivery networks.
EU AI Act high-risk system classifications are extending CE marking requirements to diagnostic algorithms previously governed by lighter MDR pathways. Algorithm developers must now implement conformity assessment procedures including bias monitoring and human oversight protocols. Radiology AI vendors are responding by establishing dedicated regulatory affairs functions in Brussels and Dublin.
Subscription pricing for algorithm modules is displacing perpetual license models as Siemens Healthineers and GE Healthcare bundle AI capabilities into hardware service agreements. Hospital procurement teams are consolidating vendor relationships around integrated platform contracts rather than point solutions. This shift is most visible in United States IDN central purchasing agreements where total cost of ownership metrics dominate vendor selection.
AI-Enabled Diagnostic Imaging Market Segmentation
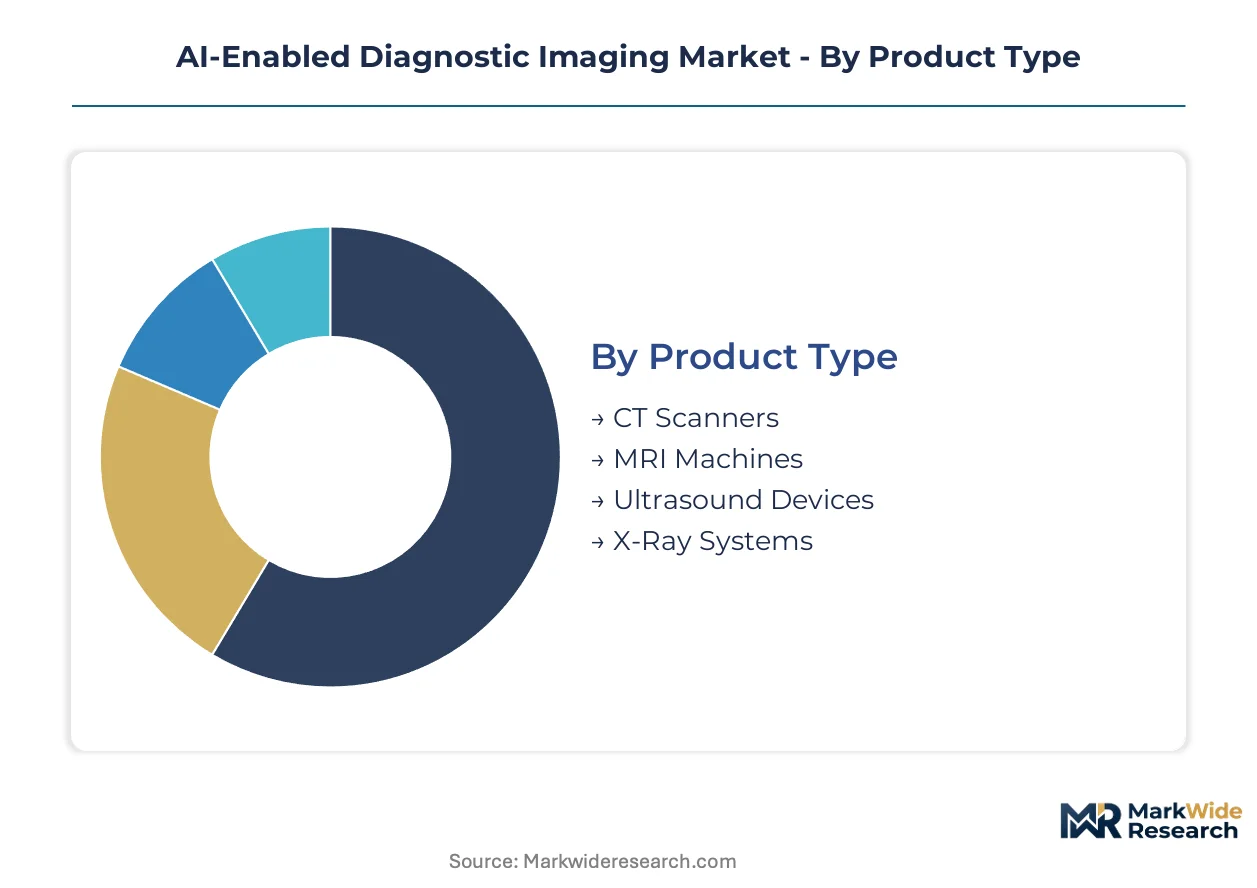
Segmentation in AI-enabled diagnostic imaging determines regulatory pathways, procurement cycles, and integration complexity. Hardware-software bundling strategies differ sharply across imaging modalities, while FDA Software as a Medical Device frameworks create tiered certification burdens by technology type.
Product Type:
FDA 510(k) clearance timelines vary substantially across hardware categories, with CT and MRI platforms commanding stricter clinical evidence requirements than ultrasound and X-ray systems.
- CT Scanners:AI-augmented CT platforms integrate deep learning inference engines directly at the point of image reconstruction. Hospital radiology departments in the United States and Germany concentrate procurement here for stroke and lung nodule detection protocols.
- MRI Machines:Magnetic resonance systems deploy convolutional neural networks for tumor segmentation and neurodegenerative pattern classification. Siemens Healthineers bundles AI modules into hardware service agreements, capturing recurring revenue from academic medical centers.
- Ultrasound Devices:Portable ultrasound AI applications enable point-of-care cardiac and obstetric screening in outpatient settings.
- X-Ray Systems:Chest radiograph AI tools target tuberculosis and pneumonia screening in India's expanding teleradiology networks.
CT scanners handle the majority of throughput; MRI machines are climbing the fastest on share.
Technology:
Cost tiers separate experimental research tools from reimbursable clinical deployments, with deep learning architectures commanding premium pricing against traditional machine learning baselines.
- Deep Learning:Convolutional neural networks and transformer architectures process DICOM images at sub-thirty-second latencies. NVIDIA GPU supply chain volatility constrains training and inference scalability for vendors building on these foundations.
- Computer Vision:Image segmentation and pattern recognition pipelines enable real-time radiologist decision support. GE Healthcare's Edison platform integrates these capabilities across hospital network deployments.
- Natural Language Processing:Automated radiology report generation reduces transcription overhead in high-volume imaging centers.
- Machine Learning:Classical statistical methods persist in resource-constrained settings and legacy PACS integrations.
Deep learning captures the dominant revenue pool; natural language processing is gaining structural importance fastest.
Application:
Reimbursement complexity and unmet diagnostic precision needs concentrate R&D investment in neurology and oncology, with cardiology and orthopedics following distinct clinical validation pathways.
- Neurology:MRI-based tumor and neurodegenerative disease classification addresses precision gaps in Alzheimer's and Parkinson's diagnosis. Academic medical centers in Germany pilot federated learning frameworks for multi-site model training without centralizing patient data.
- Oncology:AI tools for tumor detection, staging, and treatment response monitoring command complex payer negotiations. Hospital procurement teams prioritize these applications for cancer center accreditation requirements.
- Cardiology:Echocardiogram and cardiac CT AI applications target heart failure and coronary artery disease screening.
- Orthopedics:Fracture detection and joint replacement planning algorithms integrate with surgical navigation systems.
Neurology commands the steepest expansion trajectory; oncology maintains the largest installed base.
End User:
Customer type dictates deployment architecture, with hospitals requiring on-premise edge computing while imaging centers and outpatient clinics adopt cloud-native SaaS models.
- Hospitals:Integrated delivery networks centralize procurement of AI-augmented CT and MRI interpretation tools through platform contracts. Legacy PACS infrastructure demands costly middleware development for seamless workflow embedding.
- Imaging Centers:Independent diagnostic facilities prioritize operational efficiency metrics and automated report generation to maximize throughput per scanner hour.
- Research Laboratories:Academic medical centers drive federated learning pilots and algorithmic transparency research under EU AI Act requirements.
- Outpatient Clinics:Tier-two hospital digitization in India creates deployment channels for cloud-based AI screening tools.
Hospitals absorb the dominant procurement volume; outpatient clinics are expanding most quickly as teleradiology platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany and the United States show minimal price elasticity for FDA-cleared diagnostic algorithms, while imaging centers in India and outpatient networks in China prioritize cloud-based deployment economics over premium hardware integration.
United States
Integrated delivery networks in Massachusetts and California centralize purchasing of AI-augmented CT interpretation tools through multi-year platform contracts. FDA 510(k) clearance pathways compress commercialization timelines for Software as a Medical Device developers. The Mayo Clinic and Cleveland Clinic anchor federated learning pilots for multi-site neurology model training without centralizing patient data.
Germany
Academic medical centers in Munich and Heidelberg drive procurement of MRI-integrated tumor segmentation algorithms for cancer center accreditation compliance. EU AI Act high-risk system classifications extend CE marking requirements to diagnostic algorithms previously governed by lighter MDR pathways. The Berlin-Brandenburg metropolitan cluster hosts dedicated regulatory affairs functions established by radiology AI vendors responding to conformity assessment mandates.
China
Tier-two hospital digitization in Sichuan and Shandong provinces creates deployment channels for chest X-ray tuberculosis screening tools. NMPA AI medical device approval pathways enforce algorithmic transparency and prospective validation dataset requirements that reshape R&D investment priorities. The Yangtze River Delta concentration of teleradiology platforms accelerates cloud-native AI screening adoption in Jiangsu and Zhejiang provinces.
India
Imaging centers in Maharashtra and Karnataka prioritize operational efficiency metrics and automated report generation to maximize throughput per scanner hour. The country's national pharmaceutical regulator maintains distinct approval frameworks for imported versus domestically developed diagnostic algorithms. Bangalore and Hyderabad anchor teleradiology network expansion that channels cloud-based AI tools into tier-two and tier-three city hospitals.
AI-Enabled Diagnostic Imaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with imaging hardware manufacturers bundling AI modules into service agreements while standalone algorithm vendors compete on inference speed and subspecialty depth. The market structure concentrates around three tiers: integrated platform providers with captive hardware installed bases, cloud-native specialists with federated learning capabilities, and point-solution developers targeting specific pathologies. Strategic differentiation runs through M&A activity absorbing standalone algorithms into platform ecosystems, and geographic expansion into India's diagnostic network buildout.
Among hardware-integrated platform providers, Siemens Healthineers and GE Healthcare exemplify the bundling archetype that captures recurring revenue through service agreements rather than per-study licensing. Aidoc occupies a position within the standalone specialist tier, representing vendors that compete on subspecialty algorithm depth and radiologist workflow integration speed. These three companies collectively illustrate the competitive tension between hardware-captive distribution and software-native agility that defines vendor positioning across the United States, Germany, and China procurement markets.
| Leading Market Players |
|---|
| Aidoc |
| United Imaging |
| Siemens Healthineers |
| Lunit |
| HeartFlow |
| GE Healthcare |
| Viz.ai |
| Qure.ai |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
NVIDIA GPU supply chain concentration at foundries in Taiwan and South Korea creates scale economies that compress inference cost floors for algorithm vendors while elevating price premiums for FDA-cleared diagnostic modules. Hospital procurement teams in the United States and Germany absorb these premiums through multi-year platform contracts, whereas imaging centers in India and China prioritize cloud-native deployment economics that bypass hardware-integrated pricing structures.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across the AI-enabled diagnostic imaging market, separating reimbursable clinical deployments from experimental research tools. Subscription pricing for algorithm modules bundled into hardware service agreements dominates the premium tier, while per-study transactional models serve price-sensitive outpatient networks. Cost compression in the economy tier intensifies because cloud-native vendors compete on inference speed metrics without certification overhead. Imaging centers in India exhibit the highest price sensitivity, whereas integrated delivery networks in the United States show minimal elasticity for FDA-cleared stroke and lung nodule detection protocols.
Supply Chain Analysis
NVIDIA GPU fabrication concentration at TSMC foundries in Taiwan underwrites the entire deep learning training and inference stack for diagnostic algorithm vendors. Algorithm development draws from concentrated semiconductor supply chains in Taiwan, South Korea, and the United States, with specialized DICOM processing hardware sourced from German and Japanese precision manufacturers. Single-source vulnerability at the advanced node GPU level exposes vendors to export control volatility and allocation rationing. Distribution runs through radiology AI marketplaces integrated into hospital PACS infrastructure and cloud-native teleradiology platforms serving tier-two hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions and imaging modalities creates white-space opportunities for specialized algorithm vendors, as federated learning architectures compress the traditional data moat advantage of large integrated delivery networks.
For Market Incumbents: Compound hardware-software bundling advantages by integrating AI modules directly at the point of CT and MRI image acquisition, capturing recurring revenue through service agreements rather than per-study licensing. Defend against cloud-native specialists by deepening federated learning partnerships with academic medical centers in Germany and the United States. Prioritize CE marking investment under EU AI Act high-risk system classifications to maintain European market access. For New Entrants and Emerging Players: Differentiate on neurology MRI subspecialty depth, where unmet diagnostic precision needs in Alzheimer's and Parkinson's classification face complex reimbursement structures that deter hardware-integrated incumbents. Target India's tier-two hospital digitization through teleradiology platform partnerships, leveraging cloud-native deployment to bypass costly PACS middleware development. Pursue go-to-market angles anchored to automated radiology report generation, as health systems prioritize operational efficiency metrics. For Investors and Strategic Acquirers: Standalone algorithm vendors with federated learning capabilities and NMPA approval pathways in China represent the most defensible acquisition archetype for platform consolidation plays. Long-term viability hinges on reimbursement code expansion for autonomous AI reads versus physician-augmented interpretations. Watch payer policy evolution at CMS as the critical inflection signal determining whether algorithm vendors capture value through subscription fees or transactional pricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial entry for Software as a Medical Device developers in the United States. |
| EU AI Act Conformity Assessment | Extends CE marking requirements to diagnostic algorithms previously under lighter MDR pathways. |
| Hospital System Partnership | Enables platform contract consolidation around integrated AI-augmented CT and MRI interpretation tools. |
| Software Companion Development | Supports automated radiology report generation for operational efficiency in high-volume imaging centers. |
| Reimbursement Strategy | Determines value capture mechanism through subscription fees or per-study transactional pricing. |
Study Parameters
The analysis maps deep learning architectures, computer vision pipelines, natural language processing modules, and federated learning frameworks, each validated through radiology department heads, biomedical engineers, hospital purchasing committees, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, NMPA approval databases, EU MDR CE marking records, and hospital procurement databases. Bottom-up algorithm vendor revenue estimates and top-down health system digitization budget analysis provide triangulation consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including imaging modality, technology architecture, clinical application, and end-user deployment model. CAGRs derive from algorithm adoption curves, hardware replacement cycles, and regulatory approval timelines. Industry-specific forecast inputs incorporate GPU supply chain constraints and evolving payer policies for autonomous versus augmented diagnostic reads.
The analysis sits within stated boundaries; outcomes outside FDA clearance acceleration, EU AI Act implementation timelines, or NMPA pathway streamlining would require recalibration. Forecasts reflect documented assumptions about reimbursement code expansion and hospital digitization budget continuity. Practitioners should keep alternative scenarios live as GPU export control regimes and federated learning standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
South America CT Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Digital Radiology Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
Preclinical Brain Imaging Market