
 Funeral Goods and Services Market | 2026-2036
Funeral Goods and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Funeral Goods and Services Market Insights
Market Context
Modular service bundling is repositioning how families configure funeral arrangements across price tiers. Service Corporation International leverages its scale to control cemetery real estate and pre-need insurance channels across North America. Dignity Plc anchors its market presence through vertically integrated funeral homes and crematoria throughout the United Kingdom. Nirvana Asia Ltd. dominates memorial park development and columbarium services across Southeast Asian metropolitan corridors.
Technical Definition and Segment Structure
Funeral goods and services encompass casket manufacturing from 18-gauge steel or solid hardwood, cremation systems operating at 760-1150°C, and memorialization products including granite gravestones and biodegradable urns, all designed to manage human remains with cultural dignity and sanitary compliance. Traditional services retain the largest revenue pool but cremation services command the fastest expansion as urban density rises and religious preferences shift. Pre-need planning captures disproportionate margin through installment financing and insurance-linked contracts, while memorial products face commoditization pressure from imported stone and digital tribute alternatives.
Regulatory Environment
The US FTC Funeral Rule mandates itemized General Price List disclosure, while the UK Funeral Services Market Investigation Order imposes transparency requirements on Dignity Plc and other major operators. Australia's consumer protection frameworks and state-based cemetery regulation through agencies like NSW Cemetery and Crematorium Administration shape how InvoCare Australia Pty Ltd. structures pre-need trusts. Stakeholders must monitor evolving green burial standards and digital asset legacy provisions as cremation rates climb and memorialization formats fragment across generational preferences.
Market Dynamics
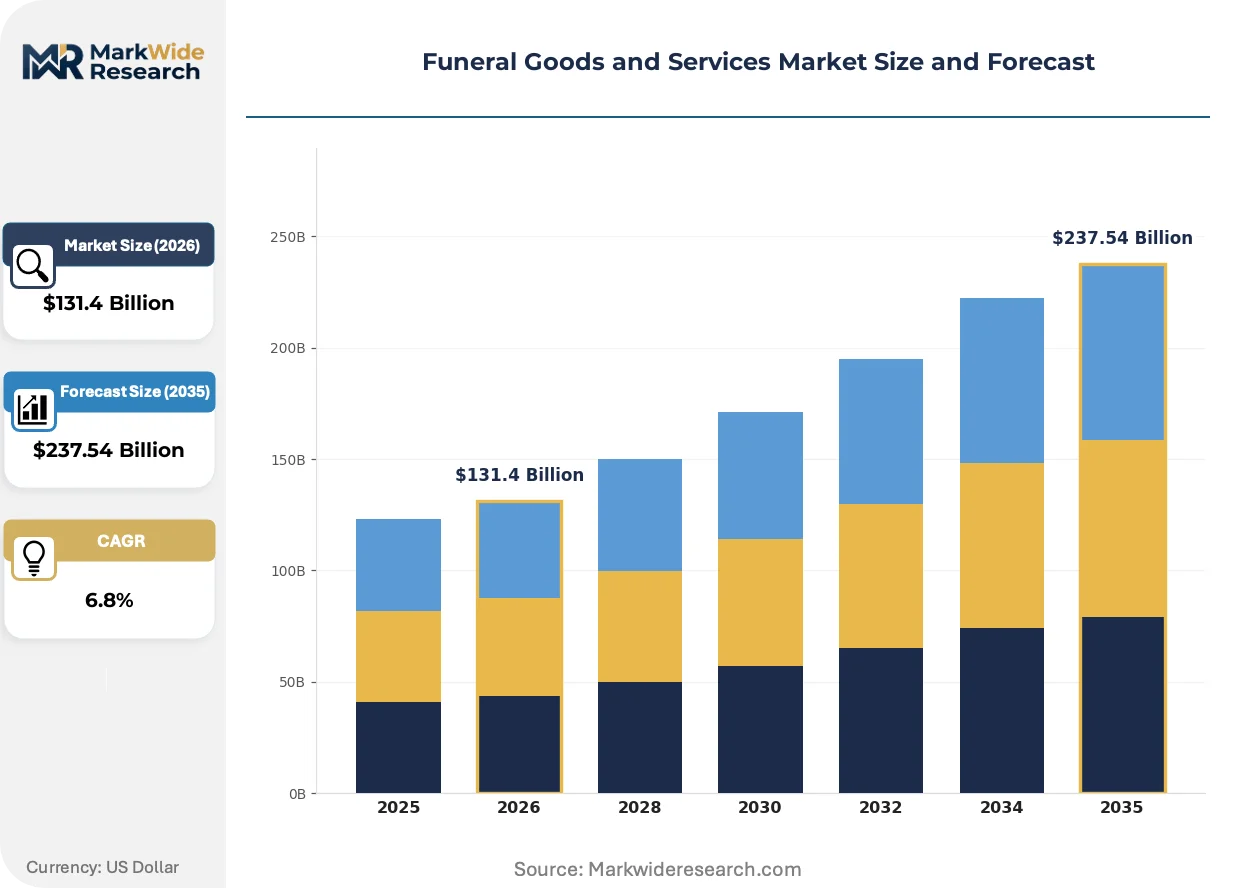
Cremation's rapid ascent from peripheral preference to dominant disposition method is compressing traditional funeral home revenue models and forcing asset reconfiguration across cemetery real estate portfolios.
Growth Catalysts
- Urban density pressures:Metropolitan land scarcity in cities like Sydney, London, and Singapore accelerates demand for columbarium niches and vertical memorialization solutions over horizontal burial plots.
- The US FTC Funeral Rule:Mandatory General Price List disclosure empowers consumer comparison shopping, stimulating competitive service innovation and price transparency across North American funeral homes.
- Biodegradable material advances:Mushroom-based mycelium caskets and salt urns attract environmentally conscious buyers seeking reduced carbon footprint in final disposition choices.
Market Restraints
- Steel price volatility:18-gauge steel casket manufacturing faces margin compression from raw material cost swings, squeezing mid-tier producers without long-term supplier contracts.
- Crematorium concentration:Independent funeral homes in rural United States depend on third-party crematory access, creating capacity bottlenecks during demand surges.
- Religious doctrine friction:Catholic burial requirements and Orthodox Jewish traditions constrain cremation adoption in specific demographic pockets, fragmenting service standardization.
Strategic Opportunities
- Green burial certification expansion:The Green Burial Council's standards create premium positioning for cemeteries offering chemical-free interment and native habitat restoration.
- Digital legacy management:Social media memorialization and cryptocurrency estate planning open ancillary revenue streams for funeral directors expanding into post-death administrative services.
- Pre-need insurance channel growth:Aging populations in Japan and Italy drive installment-funded funeral arrangements, locking future market share through policy-linked service contracts.
Industry Challenges
- Embalmer workforce attrition:Mortuary science program enrollment declines in the United States threaten service capacity as experienced practitioners retire without adequate replacement pipelines.
- Cremation equipment capex cycles:High-efficiency retort installation demands substantial capital outlay, straining independent operators facing simultaneous revenue per-case decline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Funeral Goods and Services Market |
| Market Size in 2026 | $131.4 Billion |
| Market Size in 2035 | $237.54 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caskets, Urns, Memorial Products, Gravestones Service Type: Traditional Services, Cremation Services, Pre-Need Planning, Memorial Services Customer Type: Individual Consumers, Funeral Homes, Religious Organizations, Corporations Distribution Channel: Direct Sales, Online Retail, Funeral Home, Wholesale |
| Companies Covered | Service Corporation International, StoneMor Partners, Carriage Services, Park Lawn Corporation, InvoCare Australia Pty Ltd., Nirvana Asia Ltd., Dignity Plc, OGF, NorthStar Memorial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Funeral Goods and Services Market Trends and Innovations
Digital memorialization platforms and alkaline hydrolysis technology are fragmenting traditional service bundles while regulatory transparency mandates accelerate price competition across established funeral home networks.
Alkaline hydrolysis, a water-based dissolution process operating at 150°C and elevated pressure, offers lower emissions than flame cremation. Canadian provinces and several US states have approved its commercial use, with adoption concentrating in environmentally progressive coastal markets. The technology is decentralizing crematory capacity by enabling smaller-scale installation in existing funeral home facilities rather than centralized industrial sites.
The EU Green Deal's circular economy action plan pressures member states to reduce burial land consumption and hazardous chemical use in embalming. France's national cemetery administration and Germany's federal environmental agency are drafting standards for chemical-free preservation alternatives. Casket manufacturers serving European markets face reformulation requirements for varnishes and metal finishes to meet REACH chemical restrictions.
Direct cremation arrangements arranged through online platforms bypass traditional funeral home consultation rooms, compressing the sales cycle from days to hours. British consumers increasingly select unattended cremation with separate memorial events, fragmenting what was historically a bundled service package. This disintermediation is most visible in Australia's metropolitan corridors where InvoCare's digital pre-need platform competes with independent online brokers.
Funeral Goods and Services Market Segmentation
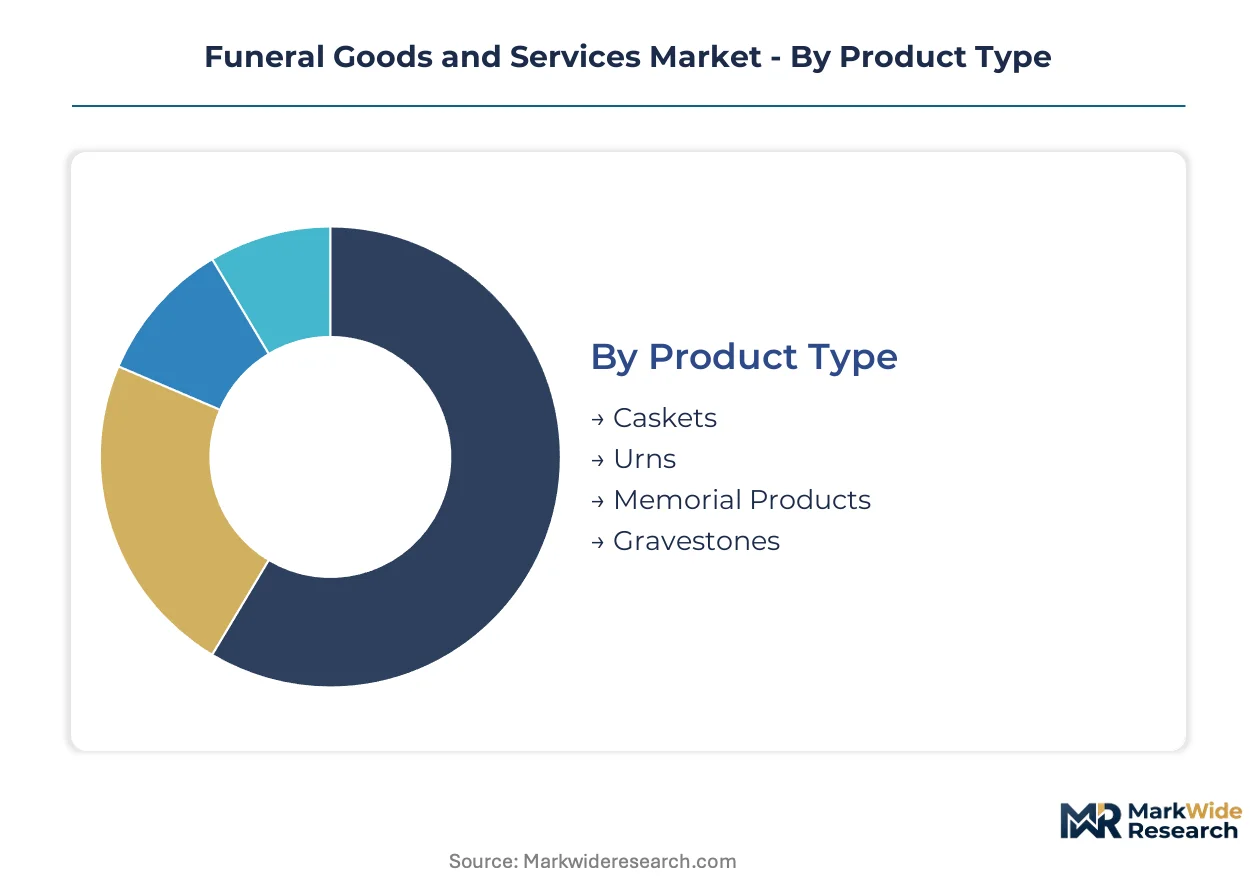
Funeral goods and services fragment across four distinct dimensions, each governed by divergent capital requirements and margin structures. Cremation infrastructure demands heavy retort investment while pre-need planning locks working capital into long-dated insurance contracts.
Product Type:
Casket manufacturing requires the heaviest upfront commitment, with steel stamping lines and hardwood curing facilities demanding seven-figure capital deployment before first unit production.
- Caskets:Fabricated from 18-gauge steel, solid hardwood, or composite materials, with interior fabric selection driving final price positioning. Australian metropolitan corridors and North American suburban markets sustain demand for premium hardwood configurations despite cremation's ascent.
- Urns:Range from cast bronze and cloisonné to biodegradable salt and mycelium formulations. Coastal California and Pacific Northwest consumers gravitate toward ocean-dissolvable options, compressing traditional metal urn margins.
- Memorial Products:Photo-engraved plaques, digital tribute tablets, and keepsake jewelry. Compact production footprint attracts import competition from Asian manufacturing clusters.
- Gravestones:Granite and bronze markers requiring quarry relationships and sandblasting equipment. Indian and Chinese stone imports pressure domestic fabricators on mid-tier contracts.
Caskets absorb the bulk of installed manufacturing capacity; urns are expanding most quickly as cremation rates climb across urban markets.
Service Type:
Revenue stability varies dramatically by contract duration, with pre-need arrangements smoothing cash flow against the lumpiness of at-need traditional services.
- Traditional Services:Full-service arrangements encompassing embalming, viewing, and burial coordination. Catholic and Orthodox Jewish communities in Brooklyn, Montreal, and Melbourne sustain this segment against secular headwinds.
- Cremation Services:Flame-based or alkaline hydrolysis disposition, often unbundled from memorial events. British direct cremation platforms and Australian digital brokers are compressing consultation-to-cremation timelines from days to hours.
- Pre-Need Planning:Installment-funded funeral arrangements backed by insurance-linked trusts. Japanese and Italian aging demographics lock future market share through policy-embedded service contracts.
- Memorial Services:Post-cremation gatherings, scattering ceremonies, and digital tribute events. Fragmenting what was historically bundled, this segment attracts independent celebrants and venue operators outside funeral home control.
Traditional services still command the greatest revenue per case; cremation services are gaining share fastest as metropolitan density rises.
Customer Type:
Procurement sophistication diverges sharply, with corporate and religious buyers extracting volume discounts unavailable to distressed individual consumers.
- Individual Consumers:At-need purchasers facing time pressure and emotional vulnerability. The US FTC Funeral Rule's General Price List mandate empowers comparison shopping, eroding information asymmetry.
- Funeral Homes:Wholesale casket procurement and third-party crematory contracting. Rural independents depend on centralized retort access, creating capacity bottlenecks during demand surges.
- Religious Organizations:Cemetery management and ritual service coordination. Catholic dioceses and Jewish burial societies maintain vertically integrated operations in specific demographic corridors.
- Corporations:Pre-need insurance underwriting and cemetery real estate holding. Service Corporation International and Dignity Plc leverage scale to control pre-need trust administration.
Individual consumers generate the transaction volume; funeral homes concentrate procurement leverage through consolidated buying cooperatives.
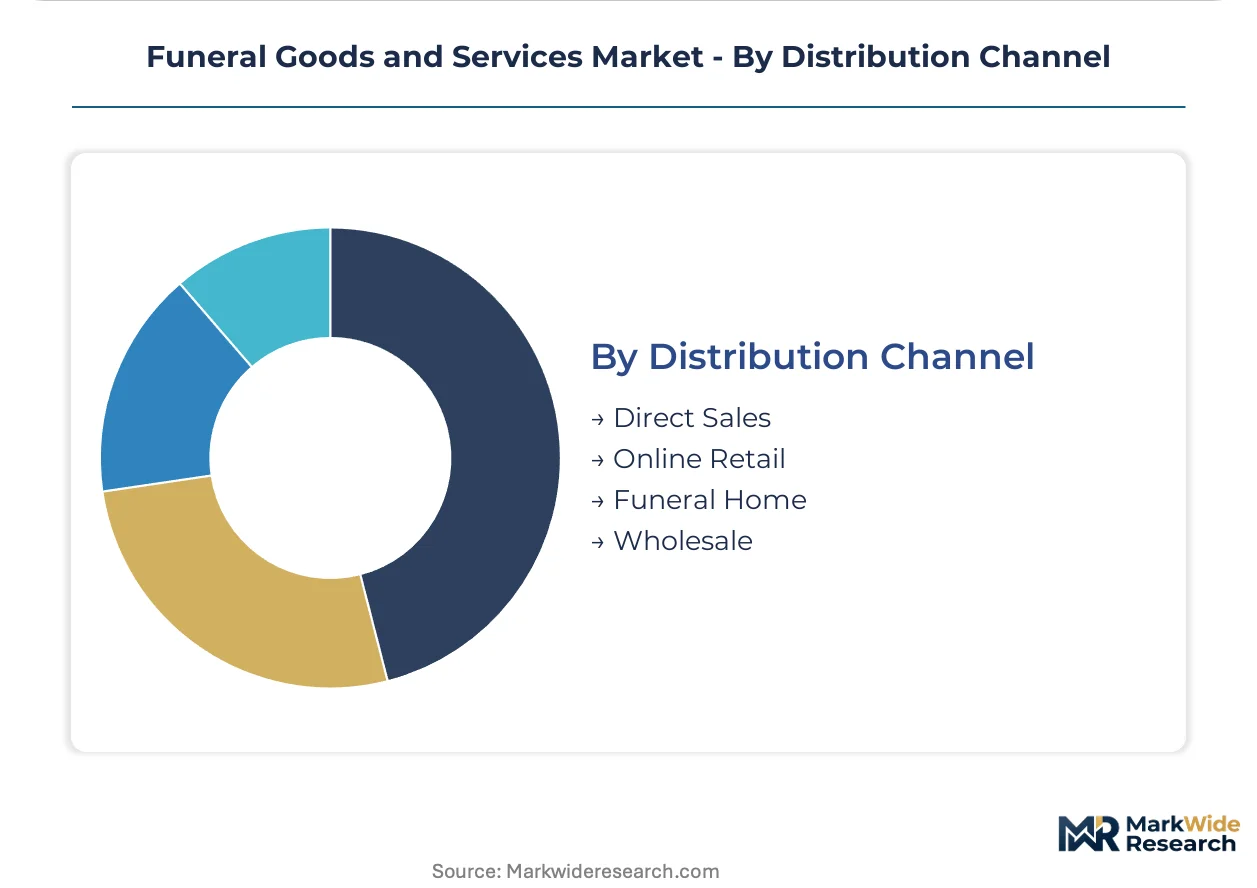
Distribution Channel:
Channel economics reflect inventory carrying costs and consultation intensity, with online platforms slashing overhead against bricks-and-mortar funeral homes.
- Direct Sales:Manufacturer-to-consumer casket shipping, bypassing funeral home markup. Warehouse club retailers and dedicated direct-to-consumer sites exploit regulatory price disclosure to undercut traditional channels.
- Online Retail:Digital urn and memorial product marketplaces with drop-ship fulfillment. Amazon and specialized funeral e-commerce aggregators compete on review transparency and return policies.
- Funeral Home:Consultation-room selection of caskets, urns, and service packages. This channel retains premium positioning through grief counseling and logistical coordination.
- Wholesale:Casket distributor networks and crematory equipment leasing. Independent funeral homes rely on third-party financing for retort installation.
Funeral homes still capture the majority of high-value transactions; online retail is climbing fastest among pre-planned cremation arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of caskets and cremation equipment concentrates in industrial manufacturing zones across China and the United States, while service revenue flows disproportionately toward aging urban populations in Australia, Japan, and Western Europe where metropolitan density accelerates disposition preference shifts.
United States
The FTC Funeral Rule mandates itemized General Price List disclosure, eroding information asymmetry that once protected funeral home margins. Service Corporation International and Carriage Services operate extensive cemetery and funeral home networks across Florida, Texas, and California. Cremation rates now exceed burial in most metropolitan statistical areas, compressing traditional service revenue per case.
Australia
Metropolitan Sydney and Melbourne drive demand for columbarium niches as cemetery land scarcity intensifies. The NSW Cemetery and Crematorium Administration oversees state-based trust structures shaping how InvoCare Australia Pty Ltd. manages pre-need funeral contracts. Urban cremation preference has surpassed burial across all capital cities.
United Kingdom
The Competition and Markets Authority's Funeral Services Market Investigation Order imposes transparency requirements on major operators including Dignity Plc. Direct cremation platforms in London and Manchester fragment historically bundled service packages. British consumers increasingly separate disposition from memorial events.
Japan
Aging demographics and Buddhist temple affiliation decline accelerate cremation adoption beyond metropolitan Tokyo and Osaka. The Ministry of Health, Labour and Welfare oversees funeral industry standards while METI monitors pre-need insurance contract structures. Crematorium capacity constraints in dense urban wards drive alkaline hydrolysis pilot programs.
France
The national cemetery administration drafts standards for chemical-free preservation alternatives under EU Green Deal circular economy pressure. Paris and Lyon metropolitan areas face acute burial plot scarcity. French consumers show growing receptivity to biodegradable casket options and forest burial sites.
Funeral Goods and Services Market Competitive Landscape
The competitive structure tilts toward vertically integrated cemetery-funeral home operators controlling pre-need insurance channels. Consolidation pressure concentrates revenue among multi-location networks while independent operators struggle against cremation equipment capital requirements. Two archetypes dominate: scale-driven cemetery real estate holders and metropolitan cremation specialists. Competitive moves center on pre-need trust acquisition and digital platform deployment for direct cremation booking.
Among North American network operators, Service Corporation International and Carriage Services exemplify the scale-driven archetype through geographic density and cemetery asset control. InvoCare Australia Pty Ltd. anchors the Asia-Pacific integrated model combining funeral homes with crematorium and cemetery verticals. Dignity Plc occupies a position representing European premium-tier consolidation under regulatory transparency pressure.
| Leading Market Players |
|---|
| Service Corporation International |
| StoneMor Partners |
| Carriage Services |
| Park Lawn Corporation |
| InvoCare Australia Pty Ltd. |
| Nirvana Asia Ltd. |
| Dignity Plc |
| OGF |
| NorthStar Memorial Group |
| Others |
Pricing and Supply Chain Analysis
Corporate pre-need insurance underwriters and consolidated funeral home networks command pricing power through volume-backed procurement contracts, while independent operators face margin compression from raw material volatility and third-party crematory access fees. Steel casket manufacturers and cremation equipment suppliers adjust quotations based on buyer scale, with tiered pricing separating national chains from regional independents.
Pricing Analysis
Margin tightening in mid-tier steel casket manufacturing reflects 18-gauge steel input volatility and import competition from Asian fabricators. Three-tier pricing structure across premium hardwood, standard metal, and economy composite configurations dominates funeral home showrooms, with quality grade and brand premium driving final positioning. Cost-down pressure on cremation services accelerates because direct-to-consumer digital platforms bypass traditional consultation markups. Individual at-need consumers exhibit highest price sensitivity, while corporate pre-need trustees lock rates through long-dated insurance-linked contracts.
Supply Chain Analysis
Dual-sourcing requirements from major funeral home chains mandate qualified suppliers across both domestic and offshore manufacturing bases. Casket fabrication concentrates in China, Vietnam, and domestic US industrial zones, while cremation retort manufacturing draws from Italian and US engineering specialists. Raw material dependencies span 18-gauge steel sheet, hardwood lumber, and refractory ceramics for retort linings. Single-source vulnerability concentrates in specialized cremation equipment components. Distribution runs through wholesale distributor networks serving independent funeral homes, with direct manufacturer relationships reserved for high-volume national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkaline hydrolysis technology is displacing flame cremation as the preferred low-emission disposition method, forcing asset reconfiguration across installed crematory infrastructure and opening white-space for equipment specialists.
For Market Incumbents: Anchor market position through pre-need trust acquisition and digital platform deployment for direct cremation booking. Defend against alkaline hydrolysis entrants by retrofitting existing retort facilities for dual-fuel flexibility. Prioritize backward integration into cemetery real estate to capture vertical memorialization revenue as urban density rises. For New Entrants and Emerging Players: Enter via biodegradable casket manufacturing serving coastal metropolitan corridors where environmental certification commands premium positioning. Target green burial certification gaps in Pacific Northwest and New England markets where regulatory pressure on chemical use intensifies. Pursue partnership routes with existing funeral home networks rather than greenfield facility investment. For Investors and Strategic Acquirers: The window for entry favors alkaline hydrolysis equipment specialists and digital pre-need platform operators over traditional funeral home consolidators. Long-term viability hinges on technology transition exposure rather than legacy asset accumulation. Monitor state-level regulatory approval trajectories for water-based cremation as the inflection signal for equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Alkaline Hydrolysis Equipment Deployment | Captures regulatory tailwinds in coastal states approving water-based cremation standards. |
| Pre-Need Digital Platform Integration | Locks future revenue through installment-funded contracts bypassing traditional consultation friction. |
| Green Burial Certification Program | Positions cemetery assets for premium pricing under EU Green Deal circular economy pressure. |
| Biodegradable Product Line Expansion | Addresses mushroom-based mycelium and salt urn demand from environmentally conscious metropolitan buyers. |
| Crematory Capacity Joint Venture | Resolves rural independent funeral home bottlenecks through shared retort infrastructure investment. |
Research Methodology
Independent corroboration across funeral director interviews, cemetery operator consultations, and cremation equipment manufacturer disclosures underwrites the qualitative findings. Primary fieldwork engaged pre-need insurance underwriters, mortuary science program directors, state cemetery regulators, and casket procurement managers at consolidated networks. Secondary validation drew from FTC Funeral Rule compliance filings, state cemetery administration trust reports, crematory operator permit databases, and trade association membership records. Bottom-up service revenue modeling triangulated against top-down demographic disposition trend projections.
Comparable-period anchoring linked historical cremation rate trajectories to metropolitan density indices and religious affiliation surveys across the projection horizon. Segmentation modeling spanned product type, service arrangement structure, customer procurement sophistication, and distribution channel economics. CAGRs derived from installed base replacement cycles, pre-need contract inception rates, and urban land scarcity indices. Forecast inputs incorporated alkaline hydrolysis regulatory approval timelines and green burial certification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated alkaline hydrolysis regulatory approvals or sudden steel price dislocation. Deviation in state-level cremation equipment emissions standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Medical Spa Market