
 Canada Corporate Wellness Market | 2026-2036
Canada Corporate Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Corporate Wellness Market Intelligence
Market Context
Digital health platforms is shifting the economics of corporate wellness delivery away from traditional in-person counseling toward scalable virtual interventions. Dialogue Health Technologies leverages its telemedicine infrastructure to anchor employer contracts across provincial healthcare networks. LifeWorks competes through integrated employee assistance programs that bundle mental health, financial counseling, and organizational consulting. Medcan sustains premium positioning with executive health assessments and on-site clinic management for Fortune 500 Canadian subsidiaries.
Technical Definition and Segment Structure
Corporate wellness encompasses employer-sponsored programs designed to improve workforce physical health, psychological resilience, and productivity through preventive interventions, behavioral coaching, and biometric monitoring. These programs typically incorporate stress assessment protocols, fitness tracking integrations, and chronic disease management frameworks to reduce absenteeism and insurance claims. Mental health services within the service type dimension now command the deepest margin pools as Canadian employers face escalating disability claims and talent retention pressures. Large corporations within the client type segment dominate contract value, though hybrid delivery models are expanding fastest as organizations blend on-site workshops with asynchronous digital coaching to serve distributed workforces.
Regulatory Framework and Outlook
Health Canada, the Canadian Centre for Occupational Health and Safety, and provincial workers' compensation boards collectively shape program standards through psychological safety guidelines and mandatory incident reporting requirements. The Canada Labour Code Part II amendments and Ontario's Working for Workers Act establish employer duties regarding mental health hazard assessment, directly expanding addressable demand for compliant wellness infrastructure. Stakeholders must monitor evolving provincial patchworks of psychological safety regulation and determine whether to standardize national programs or customize jurisdiction-specific offerings.
Market Dynamics
Telemedicine infrastructure investments by Canadian employers are compressing delivery timelines for mental health interventions while fragmenting vendor relationships across provincial healthcare networks.
Growth Catalysts
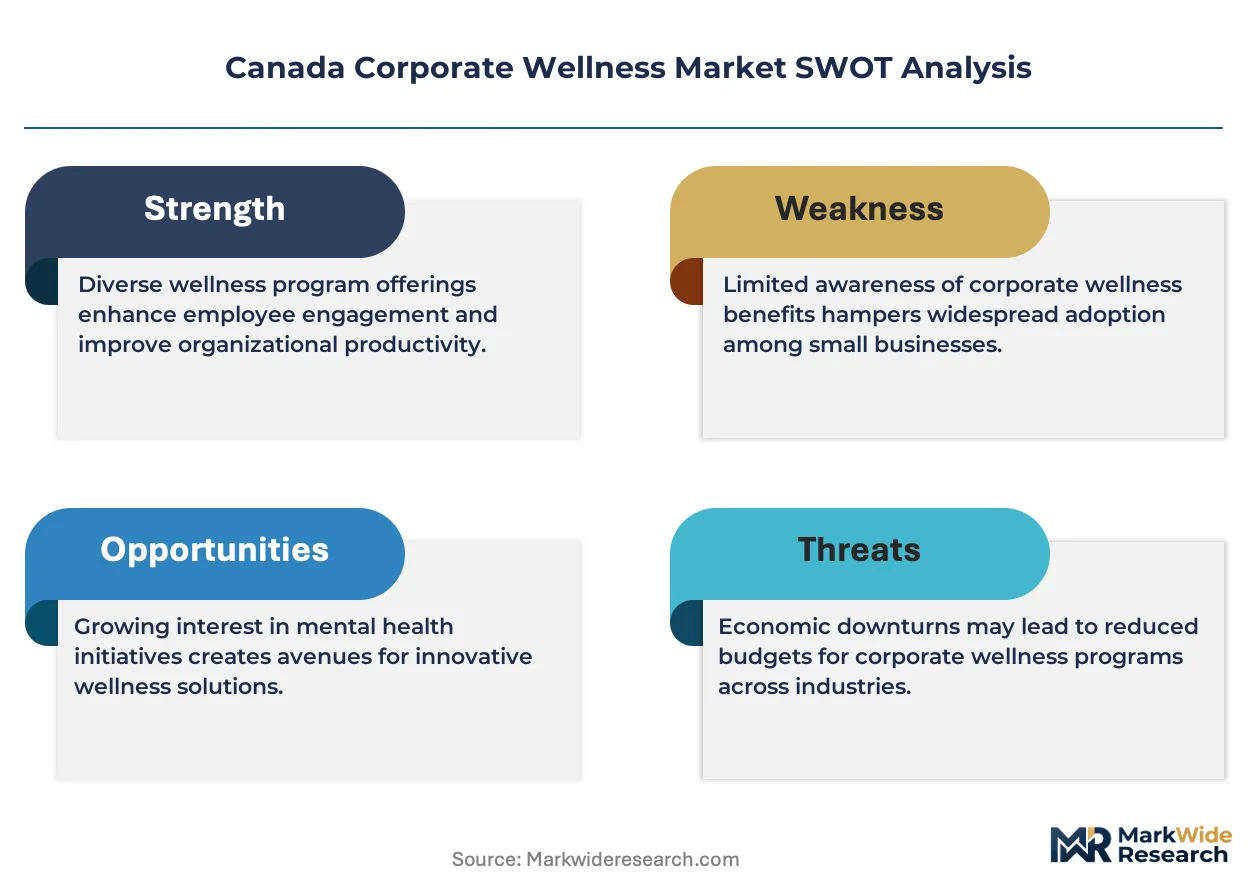
- Canada Labour Code Part II Amendments:Mandatory psychological hazard assessment duties are compelling mid-size employers to procure compliant wellness infrastructure for the first time.
- Technology Sector Burnout Response:Toronto and Vancouver technology employers are expanding wellness budgets to address retention challenges in competitive talent markets.
- Provincial Occupational Health Mandates:Ontario's Working for Workers Act and British Columbia's psychological safety guidelines are accelerating mandatory program adoption across regulated industries.
Market Restraints
- Specialized Clinician Supply Bottlenecks:Shortages of licensed psychologists and occupational therapists in Atlantic Canada limit service expansion outside Ontario and British Columbia.
- Interprovincial Licensing Friction:Variations in professional registration requirements across provincial colleges create compliance overhead for national program standardization.
- Public Healthcare Substitution:Provincial mental health funding expansions in Quebec and Ontario reduce employer urgency for supplemental private wellness spending.
Strategic Opportunities
- Prairie Province Penetration:Alberta and Saskatchewan resource sector employers remain underpenetrated relative to coastal technology and financial services markets.
- Indigenous Workforce Partnerships:Federal procurement mandates for Indigenous-owned wellness providers create preferential contracting pathways in government and Crown corporation supply chains.
- Workers' Compensation Integration:Provincial boards in Manitoba and Nova Scotia are piloting wellness program subsidies that reduce net employer cost burdens.
Industry Challenges
- Credential Verification Complexity:Employers struggle to validate practitioner qualifications across multiple provincial regulatory bodies when deploying national programs.
- ROI Measurement Standardization:Absence of consistent absenteeism and disability claim attribution methodologies complicates vendor performance benchmarking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Corporate Wellness Market |
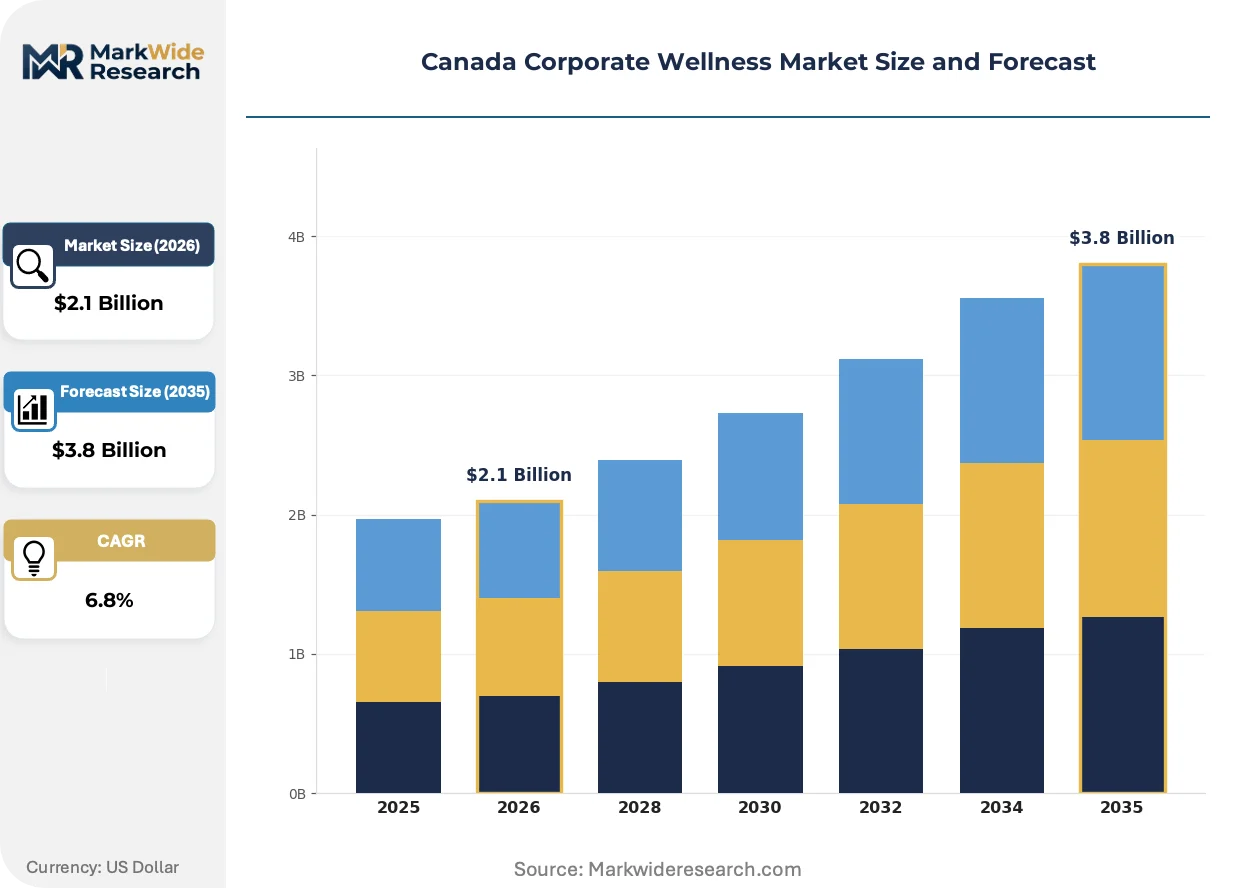
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fitness Programs, Mental Health Services, Nutritional Guidance, Health Screenings Delivery Model: In-Person Sessions, Online Coaching, Hybrid Solutions, Workshops Client Type: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Program Duration: Short-Term Initiatives, Long-Term Engagements, Annual Contracts, One-Time Events |
| Companies Covered | WorkingWell, GreenShield Health, LifeWorks, Nicole Porter Wellness, Dialogue Health Technologies, Medcan, MindBeacon, Fitness World Canada, Meditopia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Corporate Wellness Market Strategic Shifts & Innovations
Canadian employers are reconfiguring wellness delivery around asynchronous digital touchpoints that reduce synchronous counseling dependency while maintaining clinical accountability.
Artificial intelligence triage chatbots are modularizing intake workflows for employee assistance programs. Mid-size manufacturing employers in Ontario are deploying these tools to filter severity levels before human clinician handoff. The technology is modularizing service tier boundaries that previously separated self-guided digital content from live therapeutic intervention.
Health Canada's psychological safety guideline harmonization efforts are creating national baseline standards for workplace mental health program design. The framework reduces provincial compliance fragmentation for multi-jurisdiction employers. Technology sector procurement teams in Toronto are incorporating these standards into vendor evaluation scorecards ahead of formal adoption timelines.
Subscription-based wellness platform procurement is displacing per-employee-per-month pricing in mid-market employer segments. Benefits consultants in Vancouver are bundling digital coaching access with traditional insurance products. This shift is most visible among British Columbia professional services firms with seasonal workforce fluctuations.
Canada Corporate Wellness Market Segmentation
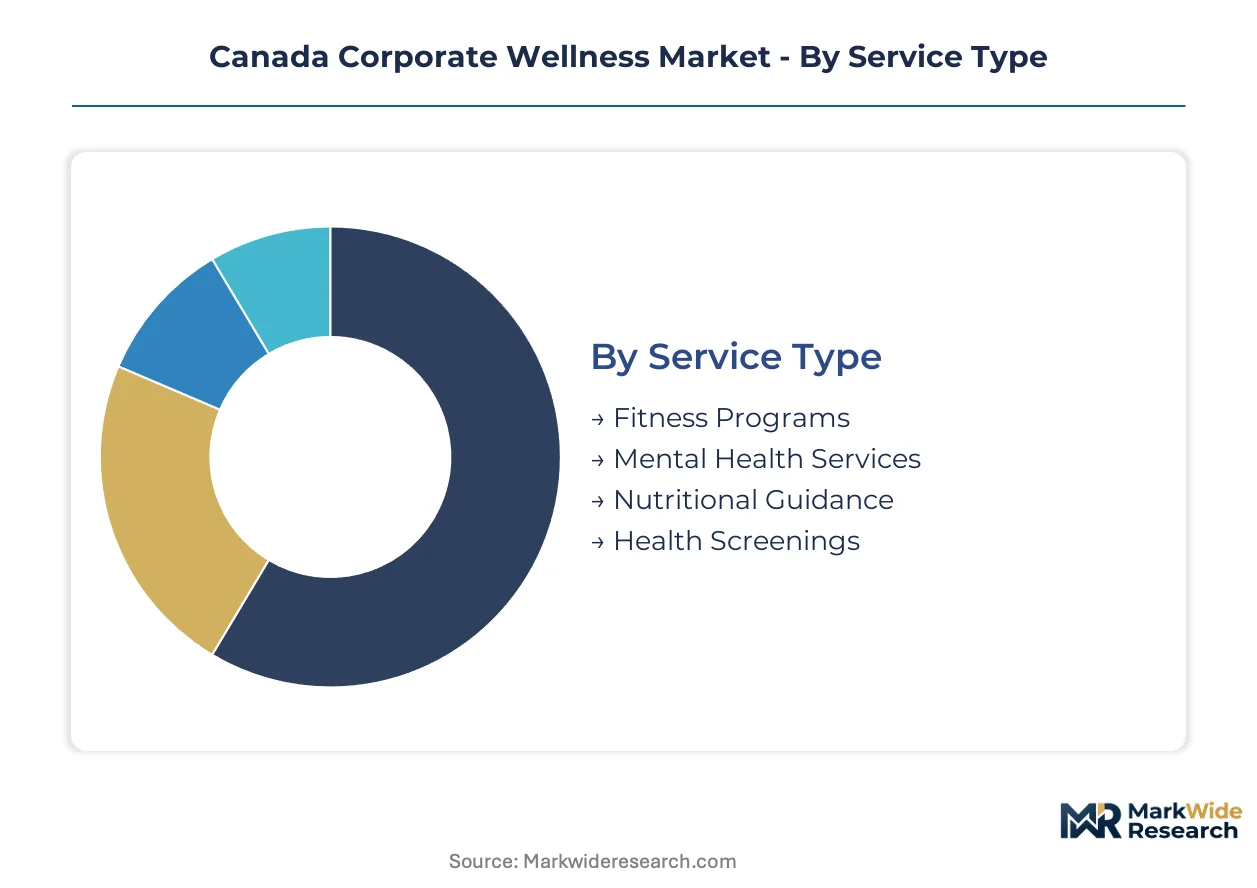
Employer procurement patterns in Canada diverge sharply across service categories and delivery formats, with regulatory mandates and workforce demographics dictating program architecture. Understanding these fault lines reveals where vendor specialization creates sustainable margin pools versus commoditized competition.
Service Type:
Replacement cycles vary by intervention category, with biometric screening protocols refreshing every 18-24 months while mental health service contracts extend 36-48 months due to relationship continuity requirements.
- Mental Health Services:Clinical counseling, crisis intervention, and stress management protocols delivered through licensed psychologists and social workers. Ontario technology employers in Toronto and Ottawa drive premium demand as Canada Labour Code amendments mandate psychological hazard assessments. Disability claim reduction and talent retention pressures deepen employer willingness to fund ongoing therapeutic relationships.
- Fitness Programs:On-site gym facilities, group exercise classes, and activity challenge platforms designed to reduce sedentary behavior and cardiovascular risk. British Columbia resource sector employers in Vancouver and Calgary satellite offices prioritize these investments to address physically demanding job profiles and shift-work health deterioration.
- Health Screenings:Biometric assessments including blood pressure, cholesterol, and glucose monitoring with preventive care referrals. Annual contracting dominates as employers align with benefits renewal cycles.
- Nutritional Guidance:Dietitian consultations, meal planning tools, and metabolic health coaching. Demand concentrates among professional services firms with predominantly desk-based workforces.
Volume placements concentrate in Mental Health Services; the faster expansion belongs to Fitness Programs as hybrid work arrangements disrupt traditional on-site gym utilization models.
Delivery Model:
Cost tier differentiation separates synchronous human-delivered interventions from asynchronous digital platforms, with hybrid architectures commanding 40-60% price premiums over pure-play formats due to coordination complexity.
- Hybrid Solutions:Blended delivery combining scheduled in-person workshops with on-demand digital coaching and telemedicine check-ins. Large corporations with distributed workforces across multiple provinces favor this architecture to satisfy both engagement depth and geographic coverage requirements.
- Online Coaching:Asynchronous video sessions, chat-based behavioral coaching, and AI-triaged mental health platforms. Atlantic Canada employers facing clinician supply shortages adopt these tools to bypass provincial licensing bottlenecks.
- In-Person Sessions:Face-to-face counseling, on-site clinic management, and facility-based fitness programming. Premium positioning persists in executive health assessments for Fortune 500 Canadian subsidiaries.
- Workshops:Single or multi-day group training events on stress management, resilience, or team dynamics. Seasonal demand spikes align with mental health awareness campaigns and benefits enrollment periods.
Customer type distribution favors Hybrid Solutions among mid-market employers; the steepest expansion trajectory belongs to Online Coaching as telemedicine infrastructure investments mature.
Client Type:
Account size determines program customization depth, with annual contract values scaling logarithmically against employee headcount due to fixed implementation costs and regulatory compliance overhead.
- Large Corporations:Organizations with 1,000+ employees operating multi-provincial or national footprints. These employers demand vendor consolidation, dedicated account management, and integration with existing benefits administration platforms.
- Medium Enterprises:Employers with 100-999 employees, typically single-province or regional in scope. This segment exhibits fastest vendor switching behavior as procurement teams evaluate emerging digital platforms against incumbent employee assistance programs.
- Small Businesses:Firms with under 100 employees, often purchasing through insurance broker channels or chamber of commerce consortium arrangements. Price sensitivity limits service breadth to core mental health triage and basic wellness screenings.
- Non-Profits:Charitable organizations, educational institutions, and healthcare providers with mission-constrained budgets. Grant-funded program pilots and provincial subsidy programs partially offset procurement limitations.
Margin concentration sits with Large Corporations; the fastest share gains belong to Medium Enterprises as Canada Labour Code amendments extend compliance obligations downward in employee count thresholds.
Program Duration:
Maturity curves differentiate transactional event-based purchasing from strategic long-term partnerships, with contract length correlating to outcome measurement rigor and vendor accountability frameworks.
- Annual Contracts:12-month renewable agreements with defined service levels and periodic utilization reporting. These structures dominate employer-vendor relationships as benefits departments align wellness spending with fiscal planning cycles.
- Long-Term Engagements:Multi-year partnerships embedding wellness metrics into organizational performance dashboards and executive compensation structures. Provincial workers' compensation board pilot programs in Manitoba and Nova Scotia subsidize these arrangements.
- Short-Term Initiatives:3-6 month targeted interventions addressing specific workforce crises such as post-merger integration or pandemic recovery. Technology sector employers in Vancouver deploy these during hyper-growth hiring surges.
- One-Time Events:Single-session health fairs, mental health awareness days, or biometric screening blitzes. Lowest-margin segment with minimal vendor differentiation.
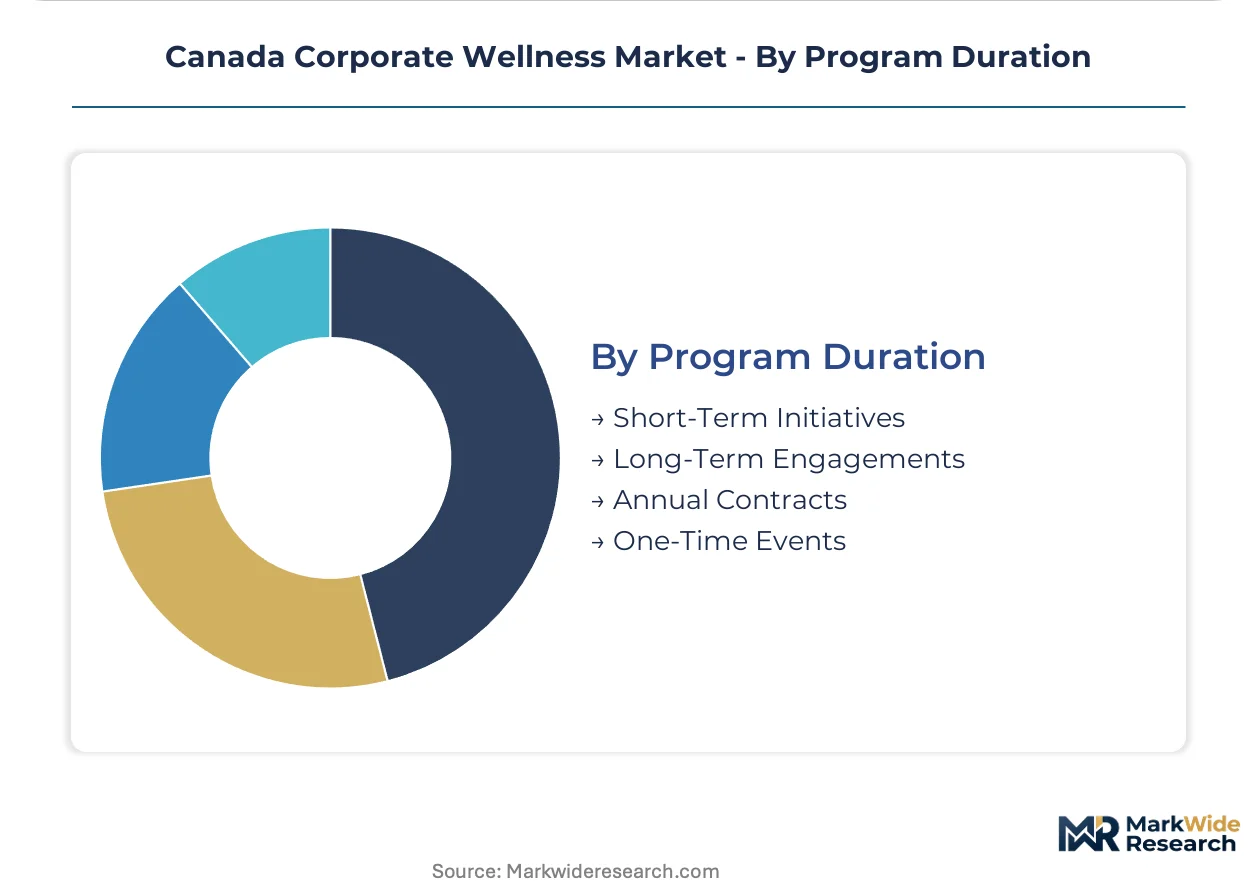
Procurement volume clusters in Annual Contracts; the most rapid format expansion belongs to Long-Term Engagements as ROI measurement methodologies mature and disability claim attribution improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer procurement concentrates in Ontario and British Columbia, where Toronto and Vancouver corporate hubs drive premium wellness service adoption and regulatory compliance investments.
Ontario
Toronto technology employers and Ottawa government contractors anchor demand for mental health infrastructure. The Working for Workers Act mandates psychological hazard assessments, compelling mid-size employers to procure compliant programs. Kitchener-Waterloo technology corridor employers are expanding wellness budgets to address burnout in competitive talent markets.
British Columbia
Vancouver technology and resource sector employers prioritize hybrid delivery models for distributed workforces. Provincial psychological safety guidelines accelerate mandatory program adoption across regulated industries. Victoria government and healthcare employers leverage federal procurement mandates for Indigenous-owned wellness providers.
Alberta
Calgary energy sector employers remain underpenetrated relative to coastal technology markets, creating expansion opportunities for digital platform vendors. The provincial workers' compensation board pilots wellness program subsidies that reduce net employer cost burdens. Edmonton public sector employers are standardizing mental health triage protocols across municipal departments.
Quebec
Montreal financial services and aerospace employers balance wellness spending against provincial healthcare funding expansions that reduce urgency for supplemental private programs. The provincial occupational health regulator enforces French-language service delivery requirements that complicate national vendor standardization. Quebec City government employers favor long-term engagement contracts embedding wellness metrics into organizational performance frameworks.
Atlantic Canada
Halifax and St. John's employers face licensed psychologist and occupational therapist supply bottlenecks that limit service expansion. Atlantic Canada employers adopt online coaching tools to bypass provincial licensing friction. Provincial colleges' variations in professional registration requirements create compliance overhead for national program deployment.
Canada Corporate Wellness Market Key Industry Players
Platform consolidation dominates the current landscape as telemedicine infrastructure investments compress delivery timelines and fragment vendor relationships. The vendor base organizes around three archetypes: integrated employee assistance program bundlers, telemedicine-anchored digital health platforms, and premium executive health assessment specialists. M&A activity concentrates among mid-market digital platforms seeking provincial network scale, while strategic partnerships between wellness vendors and benefits consultants reshape distribution economics.
Among integrated service providers, LifeWorks exemplifies the bundling archetype that combines mental health, financial counseling, and organizational consulting. Dialogue Health Technologies occupies a position within the telemedicine-anchored tier, leveraging virtual care infrastructure for employer contract penetration. Medcan represents premium positioning through executive health assessments and on-site clinic management for large corporate accounts.
| Leading Market Players |
|---|
| WorkingWell |
| GreenShield Health |
| LifeWorks |
| Nicole Porter Wellness |
| Dialogue Health Technologies |
| Medcan |
| MindBeacon |
| Fitness World Canada |
| Meditopia |
| Others |
Cost & Logistics Intelligence
Telemedicine platform maturation is compressing synchronous counseling premiums while fragmenting vendor relationships across provincial healthcare networks, simultaneously eroding price floors for traditional in-person delivery and concentrating procurement power with digital-native providers that can bypass clinician licensing bottlenecks.
Pricing Analysis
Volume placements concentrate in subscription-based wellness platforms displacing per-employee-per-month pricing, while premium margins persist in hybrid solutions commanding 40-60% markups over pure-play formats due to coordination complexity. Price differentiation rests on provincial network coverage breadth and Health Canada psychological safety guideline compliance tier. Cost compression in online coaching is intensifying because AI-triage modularization reduces human clinician dependency. Small businesses purchasing through insurance broker channels exhibit highest price sensitivity; Fortune 500 Canadian subsidiaries show lowest sensitivity due to disability claim reduction ROI visibility.
Supply Chain Analysis
Provincial college licensing requirements for psychologists and occupational therapists function as certification gates constraining clinician supply concentration in Ontario and British Columbia. Raw material dependencies include telemedicine infrastructure software, AI-triage algorithms, and biometric monitoring hardware. Supply chain risk centers on interprovincial licensing friction creating compliance overhead for national program standardization. Distribution runs through benefits consultants bundling digital coaching with traditional insurance products, particularly visible in Vancouver and Toronto corporate procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is accelerating as telemedicine infrastructure investments compress weaker vendors unable to achieve provincial network scale, with Canada Labour Code compliance mandates forcing mid-size employers toward vendor consolidation for the first time.
For Market Incumbents: Acquire telemedicine infrastructure assets to anchor employer contracts across provincial healthcare networks. Integrate backward into AI-triage algorithm development to reduce synchronous counseling dependency and defend margin position against pure-play digital entrants. Consolidate vendor relationships in Ontario and British Columbia before compliance mandates extend to Atlantic Canada. For New Entrants and Emerging Players: Benefits consultants represent the primary channel partner type for bypassing incumbent EAP bundlers. Target Alberta and Saskatchewan resource sector employers where digital platform penetration lags coastal technology markets. Pursue Indigenous-owned wellness provider certification to access federal procurement mandates in government and Crown corporation supply chains. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated employee assistance program bundlers seeking telemedicine capabilities. Long-term viability favors vendors with provincial network scale across multiple Canadian jurisdictions. Watch for Health Canada psychological safety guideline formal adoption as inflection indicator for national program standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Network Expansion | Multi-jurisdiction coverage satisfies Canada Labour Code compliance mandates for distributed workforces. |
| AI-Triage Platform Integration | Modular intake workflows reduce synchronous counseling costs while maintaining clinical accountability standards. |
| Indigenous Partnership Certification | Federal procurement preferences unlock government and Crown corporation supply chain access. |
| Workers' Compensation Board Alignment | Subsidy integration in Manitoba and Nova Scotia reduces net employer cost burdens and accelerates adoption. |
| Hybrid Delivery Model Development | Blended architectures command 40-60% price premiums over pure-play formats due to coordination complexity. |
Research Approach
Document review covered Health Canada regulatory filings, provincial workers' compensation board program documentation, and Canada Labour Code amendment records, complemented by interviews with benefits consultants, HR procurement officers at technology and resource sector employers, licensed psychologists, and telemedicine platform executives. Secondary validation drew from corporate wellness vendor RFP documents, provincial occupational health regulator guidance, and benefits broker market reports. Bottom-up employer spending estimates were triangulated against top-down market sizing from service provider revenue disclosures.
Cross-referencing historical contract value trends against panel input from procurement officers and vendor account managers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, delivery model, client type, program duration, and provincial regulatory cluster. CAGRs were derived from weighted employer budget expansion rates and vendor pricing trajectory assessments. Forecast inputs incorporated Canada Labour Code compliance timeline assumptions and provincial psychological safety guideline adoption curves.
Caveats apply where provincial healthcare funding expansions or interprovincial licensing harmonization efforts could materially shift employer urgency for supplemental private wellness spending. Forecasts reflect assumptions about regulatory enforcement intensity and clinician supply constraints that may revise with policy changes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Outpatient Clinics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Medically Supervised Weight Loss Services Market