
 Vaccine Logistics Market | 2026-2036
Vaccine Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Logistics Market Analytics
Dry ice is decoupling from ultra-cold vaccine shipments as phase-change materials and liquid nitrogen systems cut handling costs. FedEx Corporation leverages its SenseAware monitoring platform to sustain temperature integrity across intercontinental lanes. Kuehne + Nagel anchors European vaccine distribution through dedicated pharmaceutical hubs in Belgium and the Netherlands. DHL Global Forwarding dominates Asia-Pacific lanes with certified life-sciences facilities in Singapore and India.
Vaccine logistics encompasses the temperature-controlled movement, storage, and monitoring of immunobiological products from manufacture to administration, requiring validated cold-chain maintenance between minus eighty degrees Celsius and plus eight degrees Celsius depending on formulation stability. The primary purpose is preserving antigen potency through continuous thermal oversight and documented chain-of-custody protocols. Air freight leads delivery mode revenue due to speed-sensitive pandemic response contracts, while refrigerated warehousing commands the storage type margin pool because of validation-intensive infrastructure. Monitoring services within the service type dimension are expanding fastest as real-time IoT telemetry becomes a contractual default for government procurement.
FDA enforcements on temperature excursion reporting, EU Good Distribution Practice Annex 9 revisions, and WHO Performance Quality and Safety prequalification standards collectively raise compliance barriers for uncertified operators. These frameworks shape demand by limiting tender eligibility to logistics providers with documented qualification protocols and audited thermal mapping. Stakeholders must weigh capital deployment toward passive thermal packaging against active container fleets as product portfolios diversify across mRNA, protein subunit, and live-attenuated platforms.
Market Dynamics
mRNA platform proliferation is forcing wholesale cold-chain infrastructure recalibration across biopharmaceutical distribution networks. Ultra-low temperature requirements are compressing passive packaging viability and accelerating active container fleet investments.
Growth Catalysts
- EU Good Distribution Practice Annex 9:Revised thermal mapping protocols are mandating real-time telemetry integration for cross-border vaccine shipments, elevating demand for validated monitoring services.
- Phase-change material innovation:Advanced salt-hydrate and paraffin formulations are extending passive thermal protection windows, reducing dry ice dependency for minus twenty-five to minus fifteen Celsius products.
- India:Serum Institute and Bharat Biotech manufacturing scale-up is concentrating regional distribution hub development in Mumbai and Hyderabad corridors.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic logistics capacity clusters in Belgium, the Netherlands, and Singapore, creating chokepoint vulnerability for ultra-cold mRNA distribution.
- FDA temperature excursion reporting:Mandatory deviation documentation increases compliance overhead for small and mid-tier logistics operators without automated chain-of-custody systems.
- Passive packaging performance ceiling:Current vacuum-insulated panel technology cannot sustain minus eighty Celsius beyond ninety-six hours without active recharge, limiting last-mile reach in tropical climates.
Strategic Opportunities
- Sub-Saharan Africa last-mile gaps:Solar-powered refrigeration nodes and drone delivery corridors present undeveloped territory for temperature-stable vaccine penetration beyond urban centers.
- WHO Performance Quality and Safety prequalification:Logistics provider certification under this framework unlocks eligibility for Gavi and UNICEF tender participation, a procurement channel distinct from commercial pharmaceutical contracts.
- IoT-Blockchain convergence:Immutable temperature logging combined with real-time geolocation is enabling outcome-based service contracts where payment ties to verified potency preservation.
Industry Challenges
- Thermal validation engineering talent:Qualified professionals capable of executing ISTA 7E protocol design and refrigerated warehouse mapping are in acute shortage relative to facility expansion timelines.
- Multi-platform inventory complexity:Simultaneous handling of minus eighty, minus twenty-five, two-to-eight, and fifteen-to-twenty-five Celsius products within shared facilities demands segregated workflow architecture.
- Legacy WMS integration:Warehouse management systems originally configured for ambient pharmaceuticals require substantial retrofit to accommodate continuous cold-chain telemetry feeds and automated excursion alerting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Logistics Market |
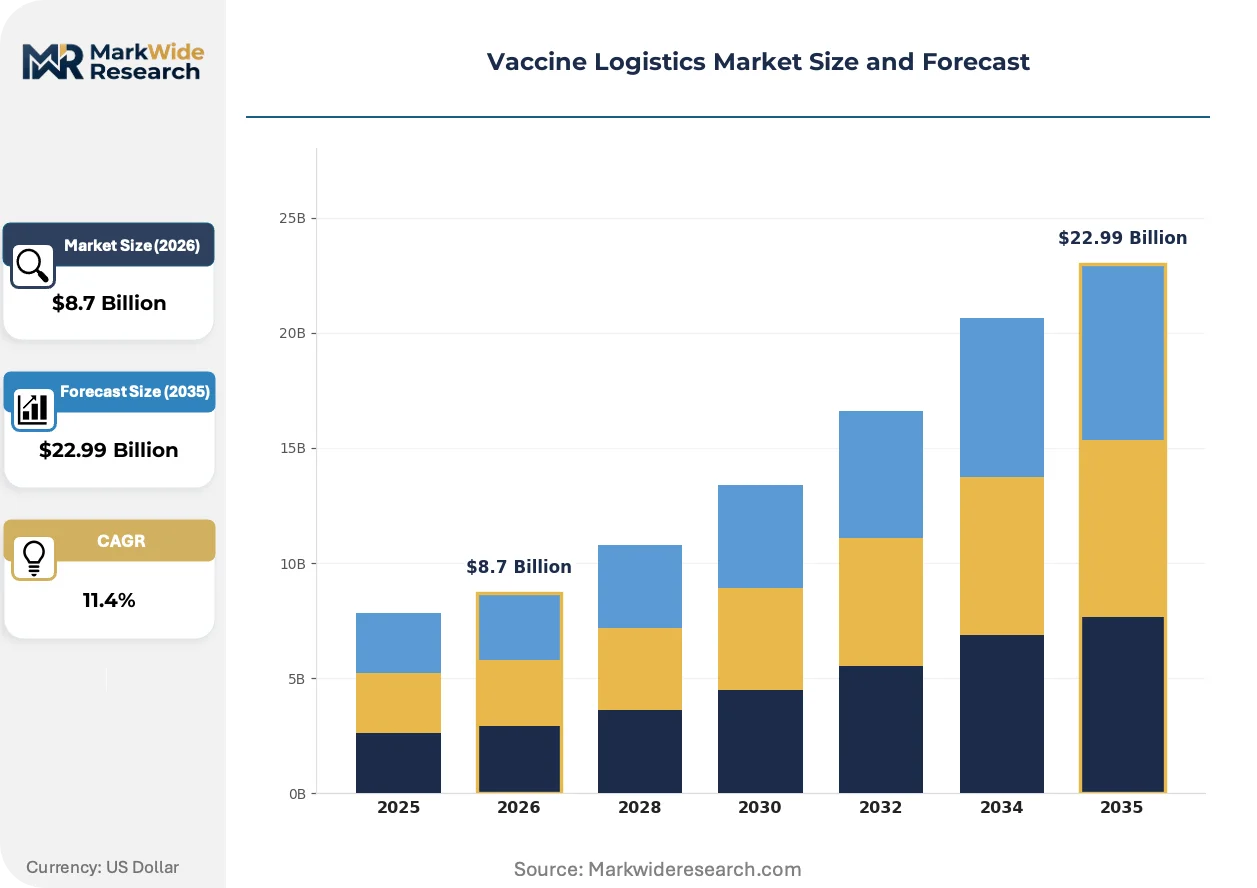
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Road, Air, Sea, Rail Storage Type: Refrigerated Warehousing, Cold Chain, Freezer Storage, Ambient Storage End User: Hospitals, Clinics, Pharmacies, Research Institutions Service Type: Transportation, Distribution, Packaging, Monitoring |
| Companies Covered | AllCargo Logistics, XPO Logistics, DHL Global Forwarding, CEVA Logistics, Kuehne + Nagel, FedEx Corporation, American Airlines, DB Schenker, UPS Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Logistics Market Evolving Landscape
Digital integration is compressing reaction times for temperature deviations while material science advances are extending passive protection durations. These developments are restructuring capital allocation between active and passive thermal systems.
Phase-change materials with tuned melting points are consolidating market share in the minus twenty-five to minus fifteen Celsius segment. Biopharmaceutical manufacturers deploying viral-vector and protein subunit platforms are adopting these systems at accelerating rates. The technology is consolidating demand around standardized pallet shippers and reducing reliance on dry ice replenishment cycles.
WHO updated temperature excursion guidelines are tightening allowable deviation windows for oral polio and rotavirus vaccines. National immunization programs must now deploy continuous data loggers with automated cloud upload to maintain procurement eligibility. African and Southeast Asian ministries of health are responding by consolidating orders through pre-qualified third-party logistics providers rather than fragmented local distributors.
Buyer concentration around government pandemic preparedness stockpiles is displacing fragmented hospital procurement. Large-scale tenders from India's Universal Immunization Programme and Brazil's Ministry of Health are aggregating demand into multi-year contracts with penalty clauses for potency failure. This pattern is most visible in emerging economies where vaccine self-sufficiency targets are centralizing distribution authority under federal agencies.
Vaccine Logistics Market Segmentation
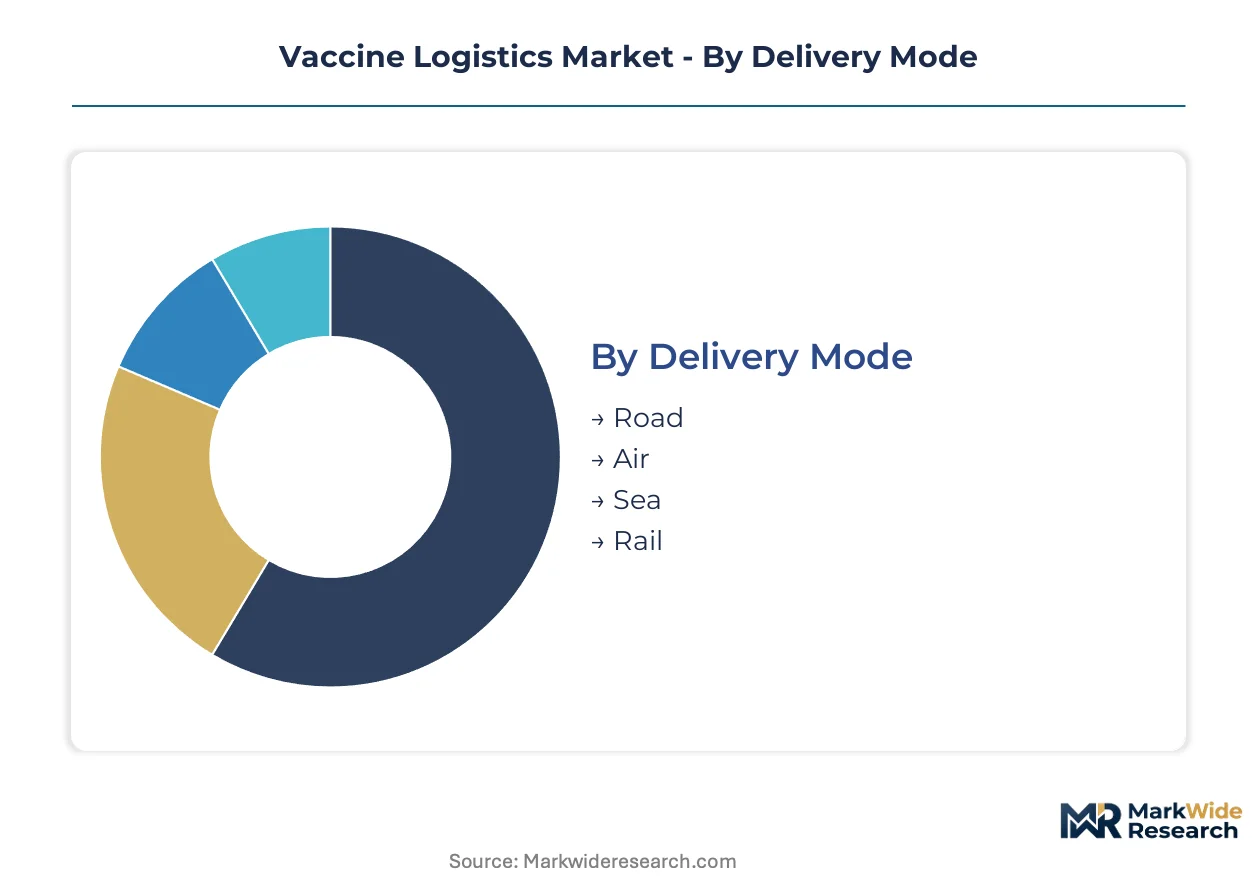
Vaccine logistics segmentation reflects divergent thermal requirements across mRNA, viral-vector, and protein-subunit platforms. Infrastructure investment cycles now favor modular systems capable of rapid reconfiguration between minus eighty and plus eight Celsius setpoints.
Delivery Mode:
Platform-specific temperature demands are forcing carriers to upgrade container fleets and retrain handling crews for ultra-cold protocols.
- Air:Active container systems with real-time telemetry dominate intercontinental lanes for pandemic response contracts. Speed-sensitive mRNA shipments from Belgium to India concentrate demand here, though fuel surcharge volatility compresses margins on non-urgent routes.
- Road:Validated refrigerated trucks with GPS-tracked temperature logging handle last-mile distribution to clinics and pharmacies. Phase-change material shippers are displacing dry ice for minus twenty-five Celsius products on European cross-border lanes.
- Sea:Reefer containers with controlled-atmosphere capabilities serve bulk vaccine shipments to regional distribution hubs. Cost efficiency drives adoption for stable, non-urgent protein subunit vaccines with extended shelf lives.
- Rail:Dedicated pharmaceutical express corridors in India and China connect manufacturing clusters to airport hubs. Modal share remains limited by track gauge incompatibilities and customs clearance delays at borders.
Air sits at the top of the volume ranking for high-value mRNA shipments, with road climbing the fastest as last-mile cold-chain density improves.
Storage Type:
Capital deployment patterns reveal a shift toward flexible infrastructure serving multiple temperature bands rather than single-purpose deep-freeze assets.
- Refrigerated Warehousing:Two-to-eight Celsius facilities with redundant backup power and thermal mapping validation command premium lease rates. India's Serum Institute and Bharat Biotech anchor demand in Mumbai and Hyderabad corridors.
- Cold Chain:End-to-end temperature-controlled networks integrating warehousing, transport, and monitoring services. WHO Performance Quality and Safety prequalification requirements are consolidating procurement around certified third-party operators.
- Freezer Storage:Minus twenty-five to minus fifteen Celsius capacity serves viral-vector and protein subunit vaccines. Phase-change material innovation is reducing energy intensity for this segment.
- Ambient Storage:Fifteen-to-twenty-five Celsius zones handle stable lyophilized formulations and ancillary supplies. Low barrier to entry has attracted fragmented local competition.
Refrigerated warehousing commands the highest margin pool, while cold chain integration is gaining share fastest as tenders demand single-accountability contracting.
End User:
Procurement centralization under government immunization programs is displacing fragmented hospital purchasing and reshaping service requirements.
- Hospitals:Large-scale vaccination centers with on-site ultra-cold freezers for mRNA dose preparation. India's Universal Immunization Programme and Brazil's Ministry of Health aggregate demand through multi-year contracts with potency-failure penalties.
- Clinics:Mid-tier facilities requiring validated cold boxes and temperature loggers for daily patient volumes. Solar-powered refrigeration nodes are penetrating Sub-Saharan African markets beyond urban centers.
- Pharmacies:Retail networks handling stable vaccines within standard two-to-eight Celsius protocols. Chain consolidation is raising compliance barriers for independent operators.
- Research Institutions:Clinical trial sites with stringent chain-of-custody documentation for investigational products. FDA temperature excursion reporting mandates drive automated telemetry adoption.
Hospitals anchor procurement volume, with clinics expanding most quickly as decentralized immunization models gain policy traction.
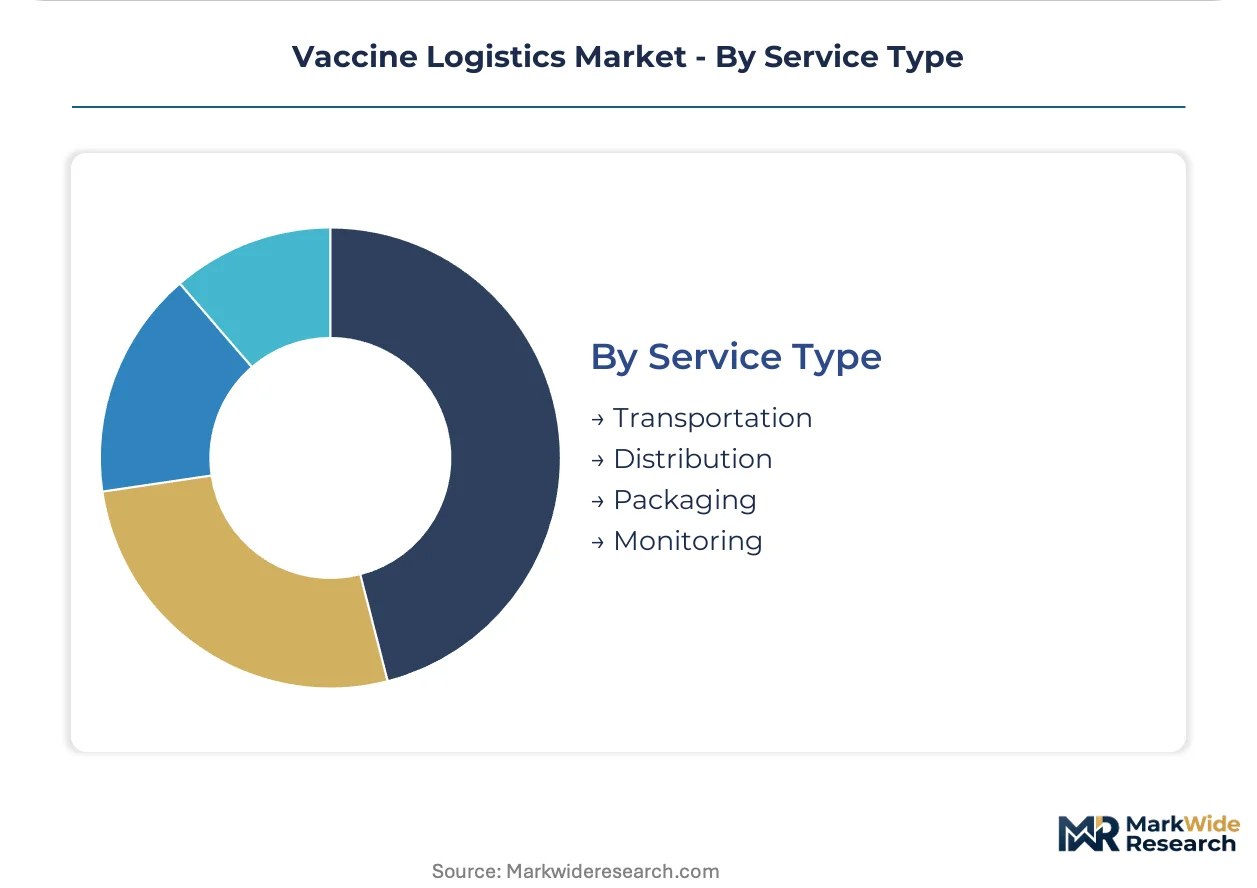
Service Type:
Margin compression in commodity transport is pushing providers toward high-value adjacent services with recurring revenue characteristics.
- Monitoring:Real-time IoT telemetry with automated cloud upload and excursion alerting. EU Good Distribution Practice Annex 9 revisions mandate this capability for cross-border eligibility.
- Transportation:Mode-specific execution of temperature-controlled movements from manufacture to distribution node. Active container fleet investments dominate competitive positioning for ultra-cold lanes.
- Distribution:Hub-and-spoke network management with inventory visibility and order fulfillment. Kuehne + Nagel's Belgian and Dutch pharmaceutical hubs exemplify regional concentration strategies.
- Packaging:Thermal system design spanning passive phase-change materials to active compressor-based containers. Salt-hydrate and paraffin formulations are consolidating share in the minus twenty-five to minus fifteen Celsius band.
Monitoring services deliver the steepest expansion trajectory as telemetry becomes a contractual default, with packaging differentiation climbing as product portfolios diversify across thermal requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's pharmaceutical corridor anchors ultra-cold chain infrastructure for mRNA vaccine distribution. Manufacturing scale-up across Serum Institute and Bharat Biotech is redrawing regional hub concentration toward Indian subcontinent corridors.
United States
FDA temperature excursion reporting mandates compress compliance timelines for cross-state vaccine shipments. The Biomedical Advanced Research and Development Authority stockpiling programs aggregate procurement under federal tenders with potency-failure penalties. Cold-chain density concentrates around Boston-Cambridge biotech clusters and New Jersey pharmaceutical distribution nodes.
Germany
EMA cold-chain guidance revisions elevate validation requirements for viral-vector vaccine transport. The Paul-Ehrlich-Institut enforces batch-release documentation that shapes logistics provider qualification protocols. Frankfurt and Cologne cargo hubs anchor continental redistribution for temperature-sensitive biologics.
India
Universal Immunization Programme centralization shifts procurement authority from state governments to federal agencies. CDSCO manufacturing licensing requirements tighten cold-chain documentation for export-bound vaccines. Mumbai and Hyderabad corridors concentrate dedicated pharmaceutical warehousing capacity serving Serum Institute and Bharat Biotech output.
Singapore
Changi Airport's certified life-sciences cargo infrastructure captures Asia-Pacific transshipment flows for ultra-cold products. The Health Sciences Authority aligns import inspection protocols with WHO Performance Quality and Safety standards. Jurong pharmaceutical free-trade zones host temperature-controlled consolidation facilities for regional distribution.
Brazil
Ministry of Health multi-year tenders displace fragmented hospital procurement with federal aggregation models. ANVISA good distribution practice enforcement raises barriers for uncertified last-mile operators. São Paulo state anchors refrigerated warehousing investment serving southeastern immunization networks.
Vaccine Logistics Market Competitive Landscape
Global majors compete with regional champions across temperature-controlled infrastructure certification. Tier-one integrators deploy active container fleets and real-time telemetry platforms, while mid-tier operators specialize in validated packaging and last-mile compliance documentation. Three archetypes dominate: integrated express carriers with pharmaceutical divisions, dedicated healthcare logistics specialists, and airline cargo units with certified cold-chain capabilities. Capacity expansion and strategic hub placement constitute the primary competitive moves as product portfolios diversify across thermal requirements.
Within the integrated carrier tier, FedEx Corporation and DHL Global Forwarding exemplify scale-driven positioning through intercontinental lane dominance and telemetry platform deployment. Kuehne + Nagel occupies a specialist position among European third-party logistics providers, anchoring regional pharmaceutical hub concentration in Belgium and the Netherlands. These three entities represent divergent strategic postures: express network leverage, global forwarding integration, and dedicated healthcare infrastructure specialization.
| Leading Market Players |
|---|
| AllCargo Logistics |
| XPO Logistics |
| DHL Global Forwarding |
| CEVA Logistics |
| Kuehne + Nagel |
| FedEx Corporation |
| American Airlines |
| DB Schenker |
| UPS Healthcare |
| Others |
Value Network & Pricing Analysis
Dry ice input costs cascade through vaccine logistics pricing tiers, with ultra-cold chain operators passing cryogenic handling premiums to government stockpile buyers while standard two-to-eight Celsius services compete on volume scale. Belgium's liquid nitrogen concentration anchors premium pricing for mRNA distribution, whereas Indian corridor providers compress margins through passive phase-change material standardization.
Pricing Analysis
Input-cost pass-through dominates vaccine logistics pricing, with active container fleet depreciation and real-time telemetry licensing fees embedding into per-shipment rates. Pricing stratifies across WHO Performance Quality and Safety certified premium tiers, EU Good Distribution Practice validated standard tiers, and uncertified economy operators serving ambient-stable products. Pricing pressure stems from fuel surcharge volatility on air freight lanes compressing margins for non-urgent routes. Government immunization programs exhibit lowest price sensitivity due to potency-failure penalty clauses, while independent pharmacies face acute cost compression from chain consolidation.
Supply Chain Analysis
Reverse logistics for temperature-controlled returns and expired vaccine disposal flows through specialized pharmaceutical waste handlers with cryogenic deactivation capabilities. Supply concentrates in Belgium, the Netherlands, and Singapore for ultra-cold infrastructure, while India and Germany anchor standard cold-chain capacity. The network draws from liquid nitrogen production clusters, vacuum-insulated panel manufacturing, and IoT sensor component supply. Single-source vulnerability runs through cryogenic logistics chokepoints in the Benelux corridor. Distribution runs through hub-and-spoke models with regional pharmaceutical free-trade zones consolidating cross-border flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
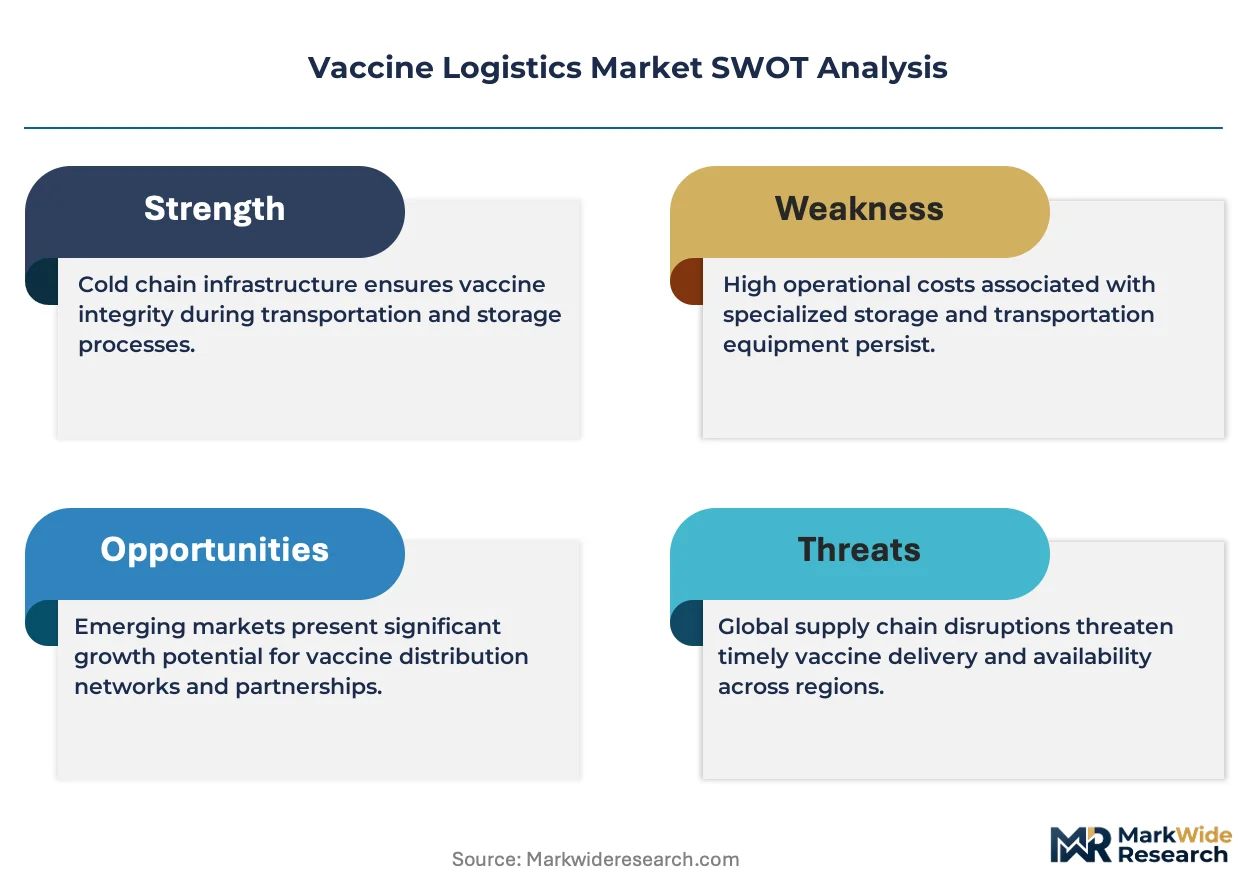
Vaccine logistics functions as a geographic-arbitrage play where EU Good Distribution Practice compliance costs in European lanes exceed Indian operational economics by multiples, rewarding capital deployment toward Mumbai and Hyderabad corridor infrastructure.
For Market Incumbents: Cement hub dominance through backward integration into passive packaging manufacturing and captive liquid nitrogen supply in Belgium. Defend against phase-change material substitution threats by locking multi-year active container lease contracts with Serum Institute and Bharat Biotech. Prioritize certification investment under WHO Performance Quality and Safety frameworks to maintain Gavi tender eligibility.
For New Entrants and Emerging Players: Begin with solar-powered refrigeration node deployment in Sub-Saharan African last-mile corridors where government immunization programs consolidate procurement. Target clinic-tier facilities in decentralized immunization models as the most penetrable segment. Pursue drone delivery corridor partnerships with national ministries of health as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where thermal validation engineering talent scarcity constrains facility expansion timelines against demand growth. Long-term viability favors vertically integrated operators controlling packaging design, warehousing, and monitoring telemetry within single accountability structures. Monitor FDA temperature excursion enforcement intensity and EU Annex 9 revision implementation as inflection indicators for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Performance Quality and Safety Certification | Unlocks Gavi and UNICEF tender participation distinct from commercial pharmaceutical contracts. |
| IoT-Blockchain Convergence Investment | Enables outcome-based contracts tying payment to verified potency preservation through immutable logging. |
| Phase-Change Material Manufacturing Scale-Up | Reduces dry ice dependency for viral-vector and protein subunit vaccine distribution economics. |
| Sub-Saharan African Hub Establishment | Captures solar-powered refrigeration node demand beyond urban centers in last-mile gaps. |
| Active Container Fleet Expansion | Sustains ultra-cold mRNA shipment competitiveness as passive packaging hits ninety-six hour thermal ceilings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold-chain operations directors, regulatory affairs leads at biopharmaceutical manufacturers, government immunization program procurement officers, and thermal packaging engineering specialists with secondary validation against FDA enforcement records, EU Good Distribution Practice guidance documents, WHO Performance Quality and Safety prequalification databases, and customs trade flow data. Bottom-up shipment volume modeling and top-down market sizing triangulated across these sources.
Segment-weighting approaches distributed value and volume across delivery mode, storage type, end user, and service type dimensions, with additional stratification by temperature band requirements and regional regulatory cluster intensity. CAGRs were derived from trajectory fitting to historical infrastructure investment patterns and forward-projected manufacturing capacity announcements. Forecast inputs incorporated mRNA platform proliferation rates, phase-change material adoption curves, and government tender centralization trends.
Several conditions sit outside the modeled scope, including pandemic emergency declarations triggering extraordinary procurement mechanisms, and sovereign vaccine self-sufficiency mandates disrupting cross-border trade assumptions. Practitioners should monitor liquid nitrogen supply concentration events, FDA temperature excursion reporting enforcement actions, and EU Annex 9 thermal mapping protocol revisions for early signals requiring forecast adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
US Care Services Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
India Senior Living Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Aged Care Market
Healthcare Services
US Healthcare Staffing Market