
 Global Virtual Care Market | 2026-2036
Global Virtual Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Care Market Foresight
HIPAA-compliant encryption standards are reorganizing procurement priorities across enterprise health systems. Teladoc Health leverages its direct-to-employer channel network to sustain recurring revenue density. American Well anchors its position through payer partnerships with large insurance networks. Koninklijke Philips differentiates via integrated diagnostic hardware paired with virtual care software.
Virtual care encompasses synchronous video consultation, asynchronous store-and-forward messaging, remote patient monitoring data transmission, and AI-assisted clinical decision support delivered through networked digital infrastructure. Cloud-based solutions dominate deployment architecture due to elastic scaling requirements and multi-tenant security protocols. Telehealth platforms capture the largest revenue pool among product types, while AI diagnostic tools represent the fastest-expanding segment as FDA 510(k) clearances accumulate for algorithm-based triage. Chronic disease management leads application demand, though mental health services are narrowing the gap as reimbursement parity laws expand.
FDA software-as-medical-device oversight, HIPAA privacy and security rules, and the EU AI Act's risk classification framework collectively determine market access conditions for platform vendors. The FDA's evolving pre-certification program for digital health is accelerating time-to-market for validated algorithms while raising compliance barriers for unproven entrants. Stakeholders must monitor how CMS reimbursement code expansions for remote therapeutic monitoring reshape provider economics and platform adoption thresholds.
Market Dynamics
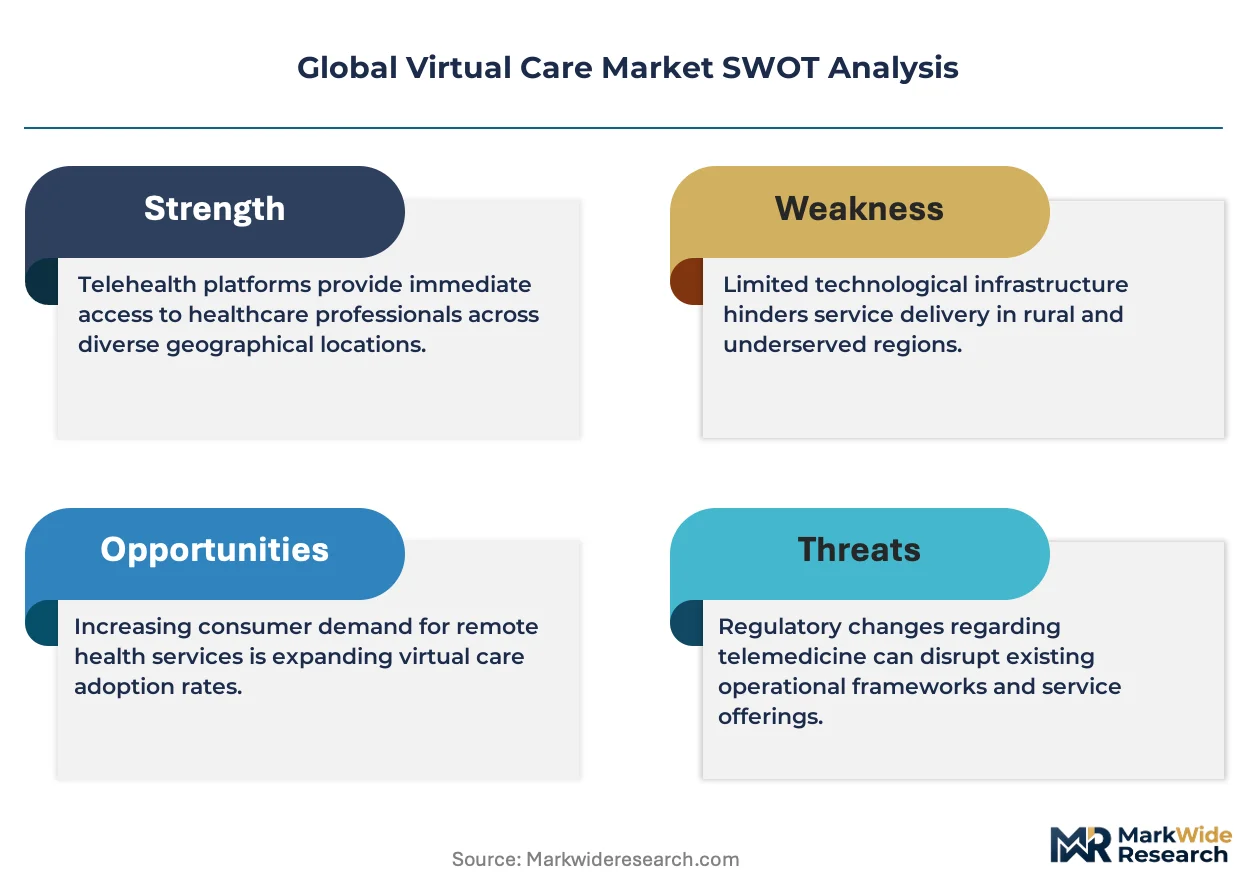
FDA software-as-medical-device pre-certification is compressing time-to-market for validated algorithms while erecting compliance barriers that filter out undercapitalized entrants, fundamentally restructuring competitive viability thresholds across platform categories.
Growth Catalysts
- Reimbursement parity laws:CMS code expansions for remote therapeutic monitoring in the United States are converting pilot programs into sustainable revenue streams for chronic disease management platforms.
- Germany's integrated care networks:Statutory health insurance contracts now mandate digital health integration, creating procurement pull for interoperable virtual care infrastructure.
- Cloud-native architecture:Elastic scaling capabilities and multi-tenant security protocols are enabling hospital systems to deploy enterprise-grade platforms without capital-intensive on-premise infrastructure.
Market Restraints
- HIPAA compliance costs:Encryption standard upgrades and audit requirements impose recurring operational burdens that disproportionately constrain mid-sized platform vendors.
- Specialist physician supply concentration:Dermatology and psychiatry credential bottlenecks in rural United States regions limit service expansion regardless of platform capacity.
- EU AI Act risk classification:High-risk algorithm designations trigger conformity assessment delays that extend market access timelines for diagnostic triage tools.
Strategic Opportunities
- Brazil's unified health system:SUS digital transformation mandates create first-mover advantage for platforms achieving ANVISA software registration.
- Mental health application expansion:Employer-sponsored benefits are broadening coverage scope beyond traditional medical consultations into behavioral health services.
- Remote patient monitoring convergence with diagnostic hardware:Integrated device-software bundles are capturing data transmission revenue streams previously fragmented across separate vendors.
Industry Challenges
- Interoperability certification timelines:HL7 FHIR implementation and health information exchange integration require 12-18 month deployment cycles that strain provider IT resources.
- Algorithm bias validation:FDA 510(k) submissions for AI-assisted triage demand retrospective clinical evidence across diverse demographic cohorts, extending development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Care Market |
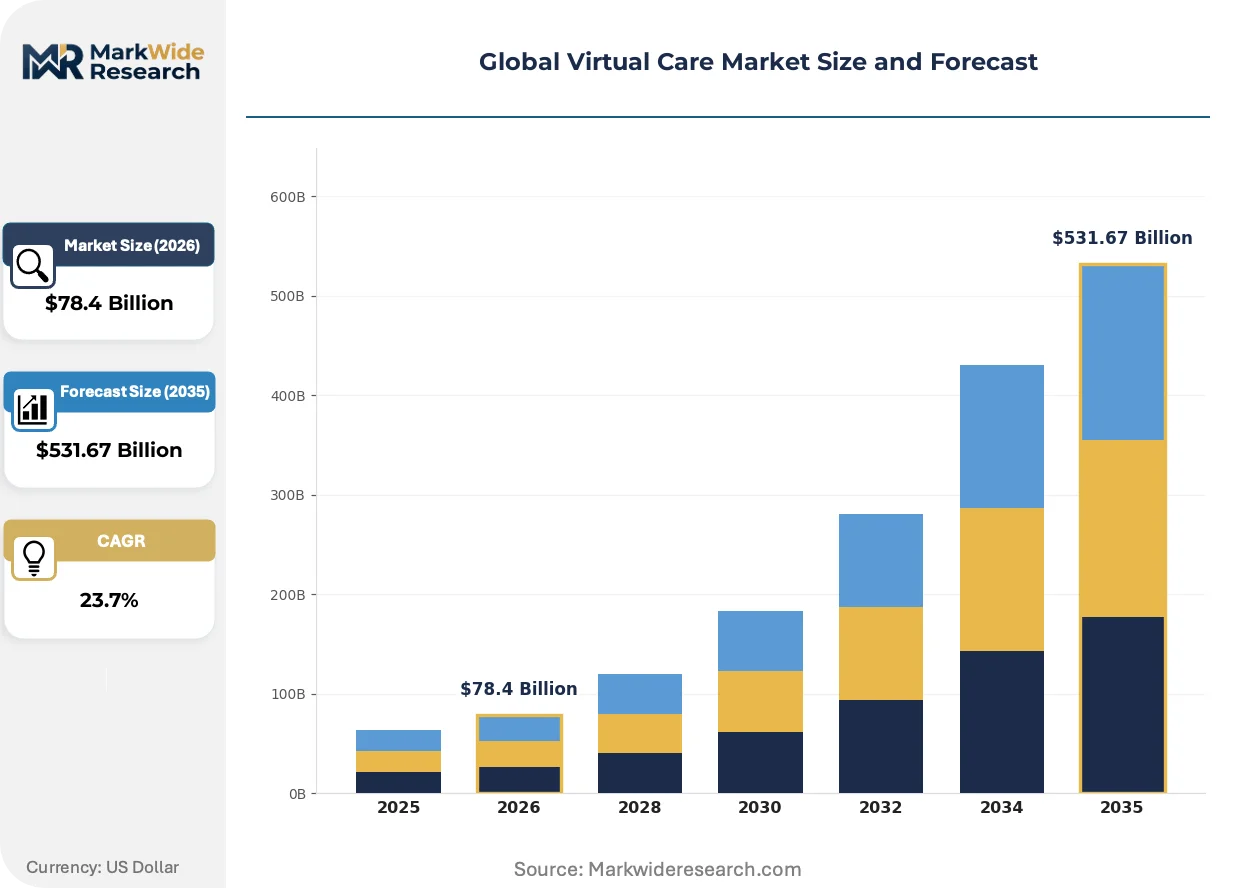
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $531.67 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehealth Platforms, Remote Monitoring Devices, Mobile Health Apps, Virtual Consultation Software, AI Diagnostic Tools, Patient Engagement Solutions Application: Chronic Disease Management, Mental Health Services, Post-Operative Care, Pediatric Care, Geriatric Support, Preventive Health Programs End User: Hospitals, Ambulatory Care Centers, Specialty Clinics, Home Healthcare Providers, Corporate Wellness Programs, Insurance Companies Deployment: Cloud-Based Solutions, On-Premises Installation, Hybrid Systems, SaaS Platforms, Mobile-Optimized Services, API Integrations |
| Companies Covered | Teladoc Health, American Well, CVS Health, MDLIVE, Cerner Corporation, Koninklijke Philips, GE Healthcare, AMD Global Telemedicine, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Care Market Shifts & Advancements
Algorithmic clinical decision support is actively reshaping competitive positioning, with regulatory clearance velocity becoming the primary differentiator separating scalable platforms from point-solution vendors.
AI-assisted diagnostic triage is bifurcating platform architectures into FDA-cleared clinical pathways and wellness-adjacent consumer applications. Large hospital systems in the United States are prioritizing procurement of pre-certified algorithms for dermatology and ophthalmology screening. This technology convergence is compressing margins for undifferentiated video consultation-only vendors while expanding addressable market boundaries for integrated diagnostic platforms.
EU AI Act risk classification frameworks are mandating conformity assessments for algorithmic patient triage systems before CE marking authorization. High-risk designations trigger mandatory human oversight requirements and post-market monitoring obligations. European platform vendors are responding by restructuring product roadmaps to segregate diagnostic features from general wellness functionalities.
Direct-to-employer contracting is displacing traditional payer-channel intermediation for mental health and primary care services. Fortune 500 benefits administrators in the United States are consolidating vendor relationships around platforms offering integrated care navigation. This channel rotation is most visible in technology sector employers seeking to reduce employee absenteeism through immediate-access virtual behavioral health.
Global Virtual Care Market Segmentation
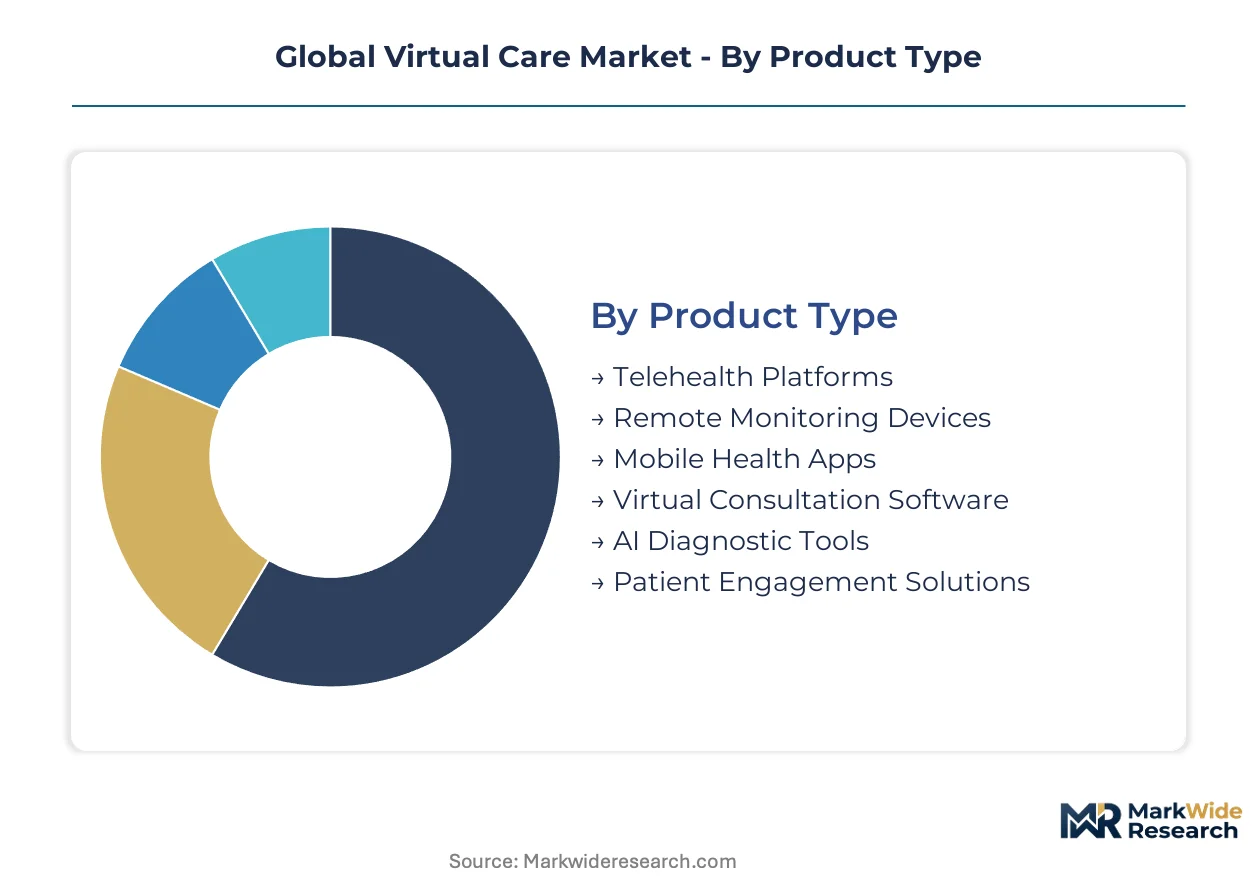
Segmentation in virtual care reveals divergent technology maturities and regulatory pathways across product architectures. Procurement patterns vary sharply between institutional buyers seeking enterprise integration and direct-to-consumer channels prioritizing immediate accessibility. Understanding these divides clarifies where platform vendors must adapt certification strategies versus user experience investments.
Product Type:
Domestic health systems in the United States and Germany anchor demand for regulated clinical-grade platforms, while export-led growth concentrates in mobile-first applications targeting emerging markets with lighter oversight frameworks.
- Telehealth Platforms:Real-time video infrastructure with embedded scheduling, billing, and EHR connectivity serves as the foundational layer for enterprise virtual care delivery. Hospital procurement in the United States concentrates here due to CMS reimbursement code alignment and HIPAA compliance requirements.
- AI Diagnostic Tools:Algorithm-based triage and screening applications require FDA 510(k) or equivalent national regulator clearance before clinical deployment. ANVISA registration in Brazil and PMDA consultation in Japan are becoming critical gating factors for vendors seeking expansion beyond North American and European markets.
- Remote Monitoring Devices:Connected hardware for physiological data capture.
- Mobile Health Apps:Consumer-facing wellness and medication adherence tools.
- Virtual Consultation Software:Lightweight video and messaging infrastructure for smaller providers.
- Patient Engagement Solutions:Automated outreach and care coordination platforms.
Telehealth Platforms command the established base. The steepest expansion runs through AI Diagnostic Tools.
Application:
Cost tier stratification separates high-acuity chronic management requiring continuous monitoring from episodic mental health consultations with lower per-session infrastructure demands.
- Chronic Disease Management:Continuous glucose monitoring integration, hypertension tracking, and heart failure surveillance demand persistent data pipelines and clinician dashboard workflows. Germany's integrated care networks mandate this capability for statutory insurance contracting.
- Mental Health Services:On-demand therapy matching, crisis intervention protocols, and employer-sponsored benefit administration prioritize immediate accessibility over clinical data depth. United States reimbursement parity laws are compressing the historical coverage gap with medical services.
- Post-Operative Care:Surgical recovery monitoring and complication flagging protocols.
- Pediatric Care:Family-centered interfaces and school-based health coordination.
- Geriatric Support:Fall detection integration and caregiver notification systems.
- Preventive Health Programs:Population screening and lifestyle intervention delivery.
Chronic Disease Management retains the deepest revenue base. Mental Health Services are climbing the fastest.
End User:
Volume concentration tracks toward hospital systems with multi-year enterprise contracts, while margin expansion concentrates in specialty clinics and corporate wellness programs with faster procurement cycles.
- Hospitals:Enterprise-grade platforms requiring HL7 FHIR interoperability, single sign-on integration, and 24/7 technical support commitments. United States health systems prioritize FDA pre-certified modules to accelerate internal governance approval.
- Home Healthcare Providers:Distributed nursing and therapy coordination across patient residences demands mobile-optimized field workflows and offline capability. Brazil's SUS digital transformation is creating procurement pull for Portuguese-language platforms with ANVISA registration.
- Ambulatory Care Centers:Same-day surgery and urgent care virtual follow-up.
- Specialty Clinics:Dermatology, ophthalmology, and cardiology focused diagnostics.
- Corporate Wellness Programs:Employer-sponsored preventive and behavioral health access.
- Insurance Companies:Payer-integrated care navigation and prior authorization support.
Hospitals anchor procurement volume. Home Healthcare Providers are gaining share fastest.
Deployment:
Customer type divides between cloud-native adopters prioritizing scalability and hybrid-system holdouts in regulated jurisdictions requiring local data residency.
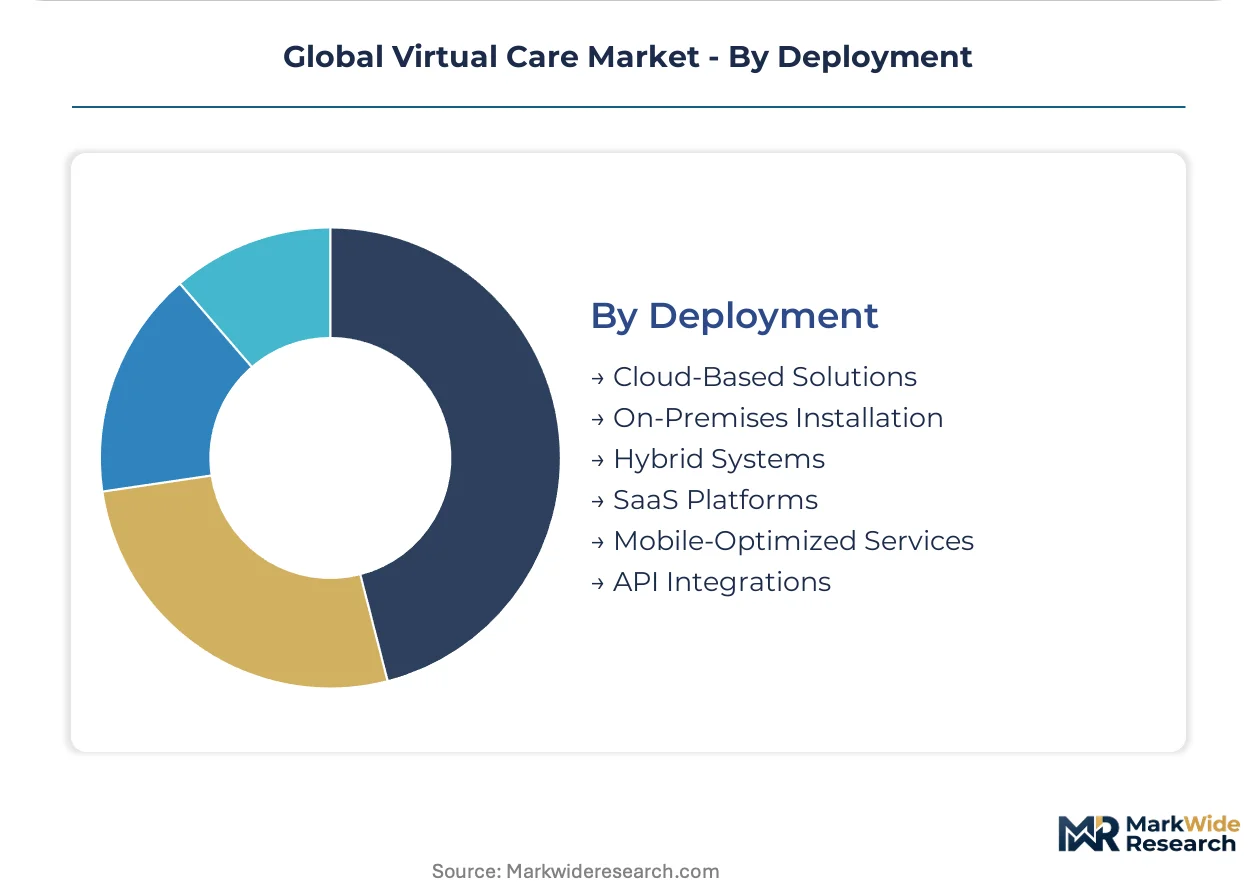
- Cloud-Based Solutions:Multi-tenant architecture with elastic compute scaling and automated security patching dominates North American and Western European deployments. EU AI Act high-risk algorithm classifications are forcing vendors to segregate European data processing from global infrastructure.
- Hybrid Systems:Local edge processing for sensitive diagnostic data combined with cloud analytics and storage accommodates China's NMPA data localization requirements and Saudi Arabia's SFDA emerging guidance. Japanese hospital systems under METI digital health initiatives are piloting similar architectures.
- On-Premises Installation:Capital-intensive dedicated hardware for maximum control.
- SaaS Platforms:Subscription-based access with standardized feature sets.
- Mobile-Optimized Services:Native iOS and Android applications for patient access.
- API Integrations:Embedded connectivity for existing EHR and practice management systems.
Cloud-Based Solutions dominate current deployment. Hybrid Systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led platform vendors concentrate licensing revenue in the United States and Germany while importing regulatory compliance expertise from Switzerland and Israel. Trade in virtual care services flows through cloud infrastructure hubs in Ireland and Singapore, with data localization requirements fragmenting cross-border delivery models.
United States
Hospital system procurement drives enterprise platform demand, with CMS reimbursement code expansions converting pilot programs into recurring revenue streams. FDA software-as-medical-device pre-certification compresses time-to-market for validated algorithms while filtering undercapitalized entrants. The Boston-Cambridge cluster anchors digital health venture formation, with Massachusetts General Brigham and Partners Healthcare piloting integrated diagnostic-telehealth workflows.
Germany
Statutory health insurance contracts now mandate digital health integration, creating procurement pull for interoperable virtual care infrastructure. The EU AI Act's high-risk algorithm classifications trigger conformity assessments that extend market access timelines for diagnostic triage tools. Berlin's Charité hospital network and Munich's university medical centers are accelerating HL7 FHIR implementation across integrated care networks.
Brazil
SUS digital transformation mandates create first-mover advantage for platforms achieving ANVISA software registration, with home healthcare providers gaining share fastest. The country's national pharmaceutical regulator is aligning software medical device pathways with FDA precedents to accelerate foreign vendor entry. São Paulo's Hospital Israelita Albert Einstein and Rio de Janeiro's Rede D'Or are deploying Portuguese-language platforms with offline mobile capability for field nursing workflows.
Japan
METI digital health initiatives are piloting hybrid cloud-edge architectures to accommodate data localization preferences among hospital systems. PMDA consultation requirements for AI diagnostic tools are becoming critical gating factors for vendors seeking expansion beyond North American and European markets. Tokyo's University of Tokyo Hospital and Osaka's National Cerebral and Cardiovascular Center are prioritizing pre-certified modules to accelerate internal governance approval.
China
NMPA data localization requirements and MIIT cloud service regulations are forcing vendors to segregate domestic processing from global infrastructure. The national medical products administration is tightening software-as-medical-device oversight for algorithm-based triage applications. Shanghai's Fudan University Zhongshan Hospital and Beijing's Peking Union Medical College Hospital are deploying multi-tenant platforms with elastic compute scaling for chronic disease management at population scale.
Global Virtual Care Market Competitive Landscape
Concentration sits with diversified health technology conglomerates and pure-play telehealth platforms, with mid-sized vendors facing compliance barriers that restructure competitive viability thresholds. The vendor base organizes around three archetypes: integrated diagnostic-hardware bundlers, direct-to-employer channel specialists, and payer-anchored platform operators. Dominant competitive moves include M&A activity targeting AI diagnostic capabilities and strategic partnerships with large insurance networks to secure recurring revenue density.
Within the payer-anchored tier, Teladoc Health and American Well exemplify contrasting channel strategies—one leveraging direct-to-employer networks, the other securing large insurance partnerships. Koninklijke Philips occupies a position among integrated diagnostic-hardware bundlers, pairing virtual care software with physiological monitoring devices. These three companies represent the archetypal positioning that separates scalable platforms from undifferentiated video consultation vendors in procurement decisions.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| CVS Health |
| MDLIVE |
| Cerner Corporation |
| Koninklijke Philips |
| GE Healthcare |
| AMD Global Telemedicine |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month HL7 FHIR implementation cycles concentrate procurement leverage with hospital systems capable of absorbing extended deployment timelines, compressing margins for vendors lacking pre-certified interoperability modules. This lead-time band stratifies pricing power across cloud-native platform tiers, with FDA-cleared algorithms commanding premium positioning against undifferentiated video consultation infrastructure.
Pricing Analysis
Hospital systems anchor SaaS-tiered subscription structures across enterprise virtual care platforms. Price differentiation separates FDA 510(k)-cleared clinical modules from wellness-adjacent consumer applications, with certification grade and embedded diagnostic hardware bundling as primary tiering mechanisms. Pricing pressure stems from mid-sized vendors competing on per-seat rates against scaled incumbents. Employer-sponsored benefits administrators demonstrate highest price sensitivity; integrated care networks in Germany exhibit lowest sensitivity due to statutory contracting mandates.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure provisioning for enterprise health systems, while Ireland and Singapore concentrate cross-border data transmission hubs. Software development draws from specialized engineering pools in Israel and Switzerland, with diagnostic hardware components sourced from Dutch and Japanese device manufacturers. Single-source vulnerability concentrates in FDA pre-certification consulting capacity. Distribution runs through direct-to-employer channel networks and large insurance payer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global virtual care is cycling through a reimbursement-parity expansion phase, with CMS code conversions for remote therapeutic monitoring sustaining revenue stream durability beyond pilot program dependencies.
For Market Incumbents: Secure payer partnership density to defend recurring revenue streams against direct-to-employer channel displacement. Invest in FDA pre-certification velocity for AI diagnostic modules to maintain procurement advantage as EU AI Act conformity assessments extend competitor timelines. Vertical integration into physiological monitoring hardware captures data transmission revenue previously fragmented across separate vendors. For New Entrants and Emerging Players: FDA software-as-medical-device pre-certification fast-tracks offer entry acceleration for algorithm-based triage vendors targeting dermatology and ophthalmology screening gaps. Brazil's ANVISA registration pathway and SUS digital transformation mandates present the most penetrable geography for Portuguese-language platforms with offline mobile capability. Home healthcare provider procurement in São Paulo and Rio de Janeiro offers immediate channel access. For Investors and Strategic Acquirers: Carve-out targets emerge from health technology conglomerates divesting non-core virtual care software assets amid diagnostic-hardware bundling strategies. Long-term viability centers on platforms achieving regulatory clearance velocity across FDA, EU AI Act, and PMDA frameworks simultaneously. Signal to monitor: CMS reimbursement code expansions for remote therapeutic monitoring categories beyond chronic disease management into post-operative and mental health applications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Investment | Accelerates time-to-market for AI diagnostic algorithms while filtering undercapitalized competitors from clinical procurement pools. |
| EU AI Act Conformity Assessment | Triggers mandatory human oversight requirements that reshape product roadmaps for algorithmic patient triage systems. |
| Diagnostic Hardware Integration | Captures data transmission revenue streams previously fragmented across separate device and software vendors. |
| Direct-to-Employer Channel Expansion | Displaces traditional payer intermediation for mental health services among Fortune 500 benefits administrators. |
| HL7 FHIR Interoperability Certification | Enables enterprise platform adoption by hospital systems requiring single sign-on and EHR connectivity. |
Research Methodology
A standing panel of hospital CIOs, health system procurement directors, FDA regulatory affairs specialists, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS reimbursement code databases, EU AI Act implementation guidance, and hospital procurement contract registries. Bottom-up demand modeling across deployment tiers triangulated with top-down market sizing from cloud infrastructure expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. Segmentation modeling incorporated product architecture, clinical application, end-user institution type, and deployment model dimensions. CAGRs derived from algorithmic fitting to historical adoption curves, with inputs including regulatory clearance velocity, reimbursement code expansion schedules, and health system IT capital allocation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained CMS reimbursement parity and stable FDA pre-certification program scope; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in regulatory clearance timelines and statutory insurance contracting mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
India Telehealth Services Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Teledermatology Market
Telemedicine
US Virtual Visits Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
Tele-ICU Services Market
Telemedicine
India Telemedicine Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Telestroke Services Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Online Doctor Consultation Market