
 Blood Bank Market | 2026-2036
Blood Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Bank Market Intelligence
Hospital procurement consolidation is rebalancing purchasing power toward integrated delivery networks across major metropolitan markets. Vitalant leverages its national footprint to sustain contract volume with large health systems. Grifols anchors plasma-derived therapeutic supply through specialized collection infrastructure. Fresenius SE & Co. KGaA competes in automated collection technology for high-throughput donation centers.
Blood banking encompasses the collection, processing, testing, storage, and distribution of whole blood and blood components for therapeutic transfusion, requiring maintenance at 1-6°C for red cell viability and frozen storage below -30°C for plasma. Blood testing equipment dominates capital expenditure as nucleic acid testing platforms displace serological methods for pathogen screening. Pathogen reduction technology represents the fastest-growing technology segment as regulatory pressure mounts for proactive safety intervention. Hospitals remain the largest end-user category, though emergency medical services are expanding pre-hospital transfusion capability.
FDA blood banking regulations, AABB accreditation standards, and EU MDR device classification collectively govern product entry and operational compliance across major markets. The FDA's draft guidance on bacterial risk control in platelets is forcing infrastructure upgrades at collection facilities. Stakeholders must monitor pathogen reduction technology cost curves against incremental regulatory mandates to optimize capital deployment timing.
Market Dynamics
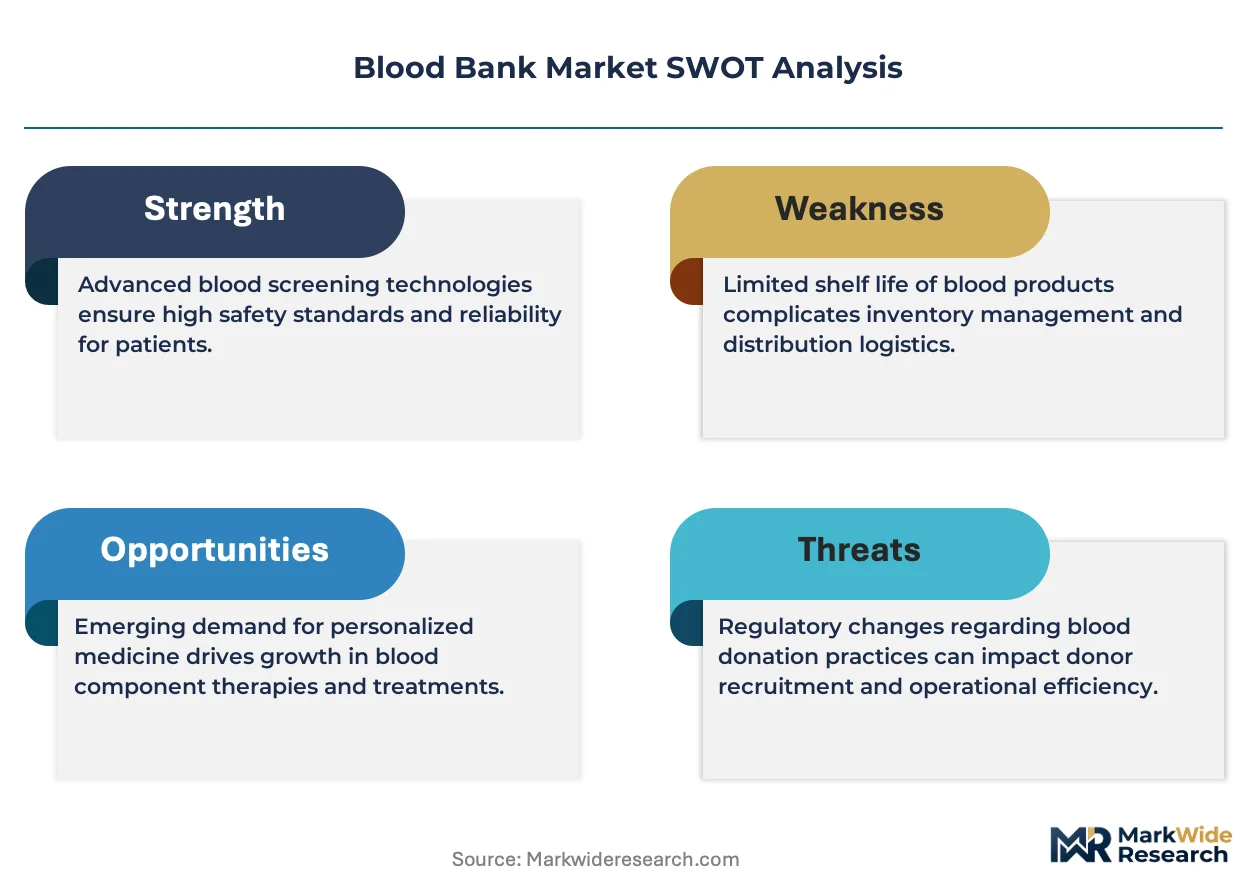
Hospital procurement consolidation is concentrating purchasing power into integrated delivery networks, while FDA pathogen reduction guidance forces simultaneous infrastructure upgrades across collection facilities.
Growth Catalysts
- Nucleic acid testing platforms:Academic medical centers are replacing serological screening methods with NAT systems for enhanced pathogen detection sensitivity.
- Pre-hospital transfusion capability:Emergency medical services in metropolitan trauma corridors are expanding blood component storage and administration protocols.
- FDA bacterial risk control guidance:The agency's draft recommendations for platelet safety are mandating proactive intervention systems at collection sites.
Market Restraints
- Plasma supply concentration:Specialized collection infrastructure limits geographic diversification of plasma-derived therapeutic feedstock.
- Pathogen reduction technology cost curves:Capital deployment timing remains uncertain against incremental regulatory mandates without volume guarantees.
- Red cell cold chain requirements:Maintenance at 1-6°C restricts distribution radius and creates spoilage exposure during logistics reconfiguration.
Strategic Opportunities
- Automated collection technology:High-throughput donation centers in underserved metropolitan markets present equipment upgrade potential.
- Frozen plasma logistics:Storage below -30°C creates regional hub opportunities for specialized cold chain operators.
- AABB accreditation differentiation:Voluntary standards exceeding baseline FDA requirements enable premium positioning with academic medical centers.
Industry Challenges
- NAT platform integration:Laboratory information systems require reconfiguration to accommodate nucleic acid testing workflow protocols.
- Platelet bacterial detection staffing:Extended culture-based testing windows demand specialized microbiology expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Bank Market |
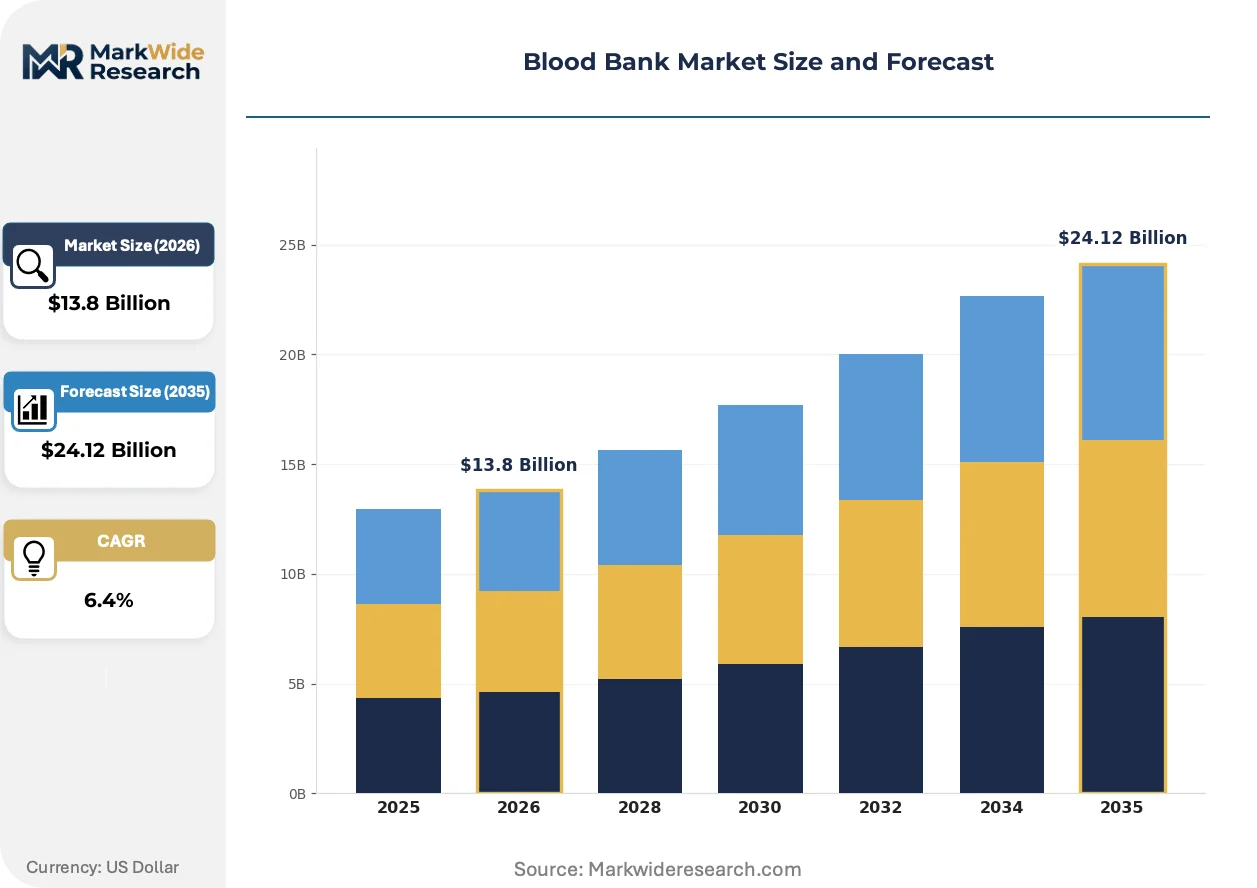
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Collection Bags, Blood Testing Equipment, Refrigeration Systems, Blood Storage Solutions End User: Hospitals, Blood Donation Centers, Research Laboratories, Emergency Medical Services Technology: Automated Blood Collection, Blood Management Software, Pathogen Reduction Technology, Point-of-Care Testing Application: Transfusion Medicine, Apheresis, Hematopoietic Stem Cell Transplantation, Research Studies |
| Companies Covered | The American Red Cross, Vitalant, Haemonetics Corporation, Grifols, Terumo Corporation, Canadian Blood Services, New York Blood Center, Australian Red Cross, Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Bank Market Strategic Shifts & Innovations
Pathogen reduction systems are rewriting collection protocols while regulatory pressure accelerates capital replacement cycles across testing infrastructure.
Pathogen reduction technology is rewriting safety standards for platelet and plasma components by inactivating residual bacterial and viral contaminants during processing. Blood centers with high-volume hospital contracts are adopting these systems defensively ahead of finalized FDA guidance. The technology is rewriting capital allocation priorities as facilities defer other infrastructure investments to secure compliance positioning.
EU MDR device classification for blood banking equipment is extending certification timelines and expanding technical documentation requirements for nucleic acid testing platforms. Manufacturers are restructuring quality management systems to accommodate notified body scrutiny of software-driven diagnostic algorithms. Automated collection devices face reclassification pressure that favors established suppliers with regulatory affairs scale.
Integrated delivery networks are consolidating transfusion service contracts across multi-hospital systems, compressing vendor management overhead into centralized procurement functions. Blood centers are responding with dedicated account structures and inventory guarantee commitments that mirror pharmaceutical supply chain terms. This concentration is most visible in United States metropolitan markets where three-hospital systems represent minimum viable contract scale.
Blood Bank Market Segmentation
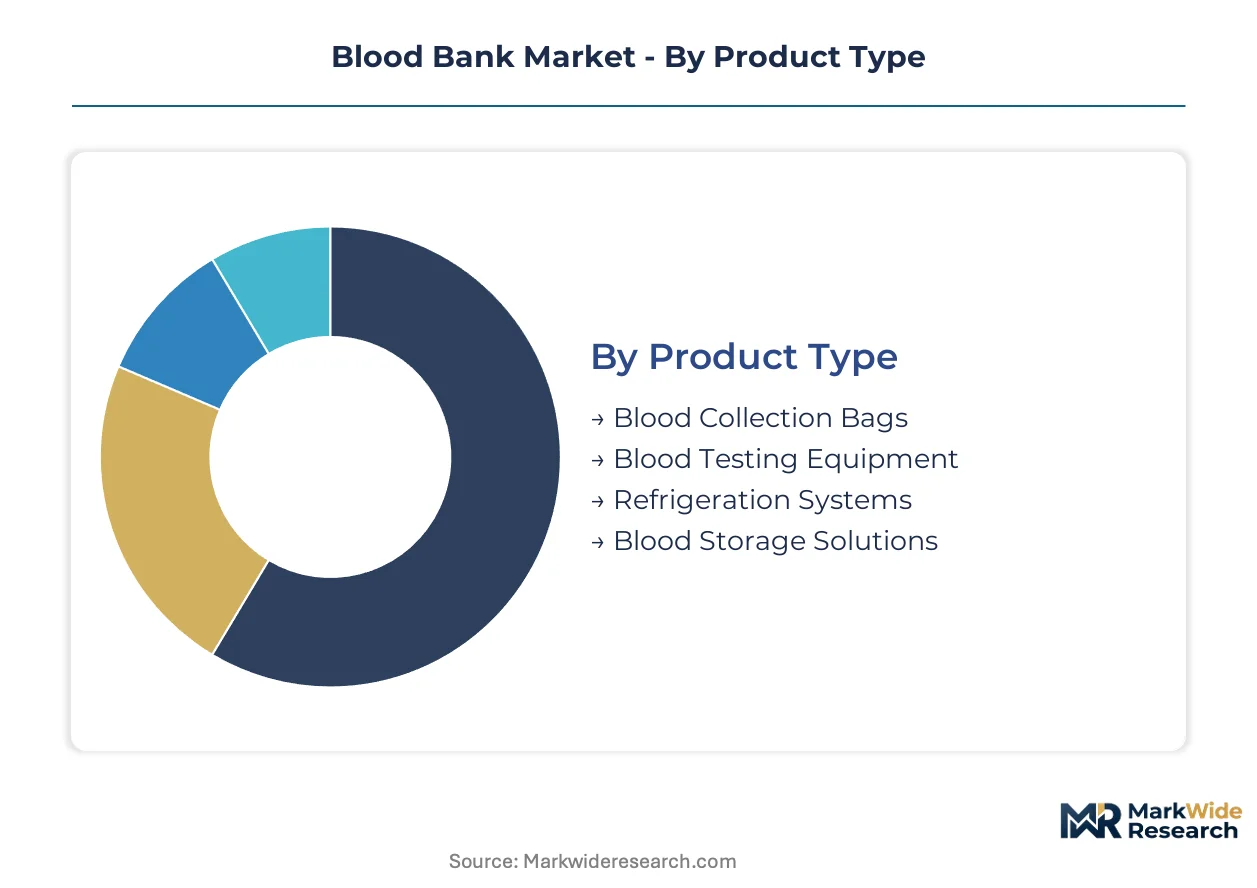
Blood bank market segmentation reveals divergent capital requirements across product categories, with testing infrastructure demanding heavy upfront investment while software solutions scale with marginal incremental cost. Understanding these investment profiles enables suppliers to align R&D allocation with customer procurement cycles.
Product Type:
Capital intensity varies dramatically across this category, with nucleic acid testing platforms requiring seven-figure installation commitments versus consumables that scale with collection volume.
- Blood Collection Bags:Single-use sterile containers manufactured from PVC or polyolefin materials with anticoagulant pre-fill options. Demand concentrates at high-volume donation centers in the United States as hospital networks consolidate procurement through national blood center contracts. Cold chain compatibility specifications are tightening as extended platelet storage protocols gain regulatory traction.
- Blood Testing Equipment:Nucleic acid testing platforms and automated immunoassay systems dominate capital expenditure budgets at collection facilities. Academic medical centers in metropolitan United States markets are displacing serological methods with NAT systems for enhanced pathogen detection sensitivity.
- Refrigeration Systems:Specialized units maintaining 1-6°C for red cell viability with continuous temperature monitoring and alarm systems. Blood centers upgrading to FDA bacterial risk control compliance are replacing legacy cold storage infrastructure.
- Blood Storage Solutions:Additive solutions extending red cell shelf life combined with cryopreservation media for plasma and stem cell components. Research laboratories in the United States are driving demand for specialized formulations supporting rare blood type archiving.
Blood testing equipment absorbs the bulk of installed capacity; pathogen reduction compatible collection systems are expanding most quickly.
End User:
Customer concentration patterns determine contract structure complexity, with integrated delivery networks demanding enterprise-level service agreements versus fragmented research laboratory procurement.
- Hospitals:Transfusion services at academic medical centers and community hospitals requiring guaranteed component availability with AABB-accredited processing protocols. Three-hospital systems in United States metropolitan markets represent minimum viable contract scale for blood center vendors.
- Blood Donation Centers:Community-based collection facilities and regional blood centers managing donor recruitment through component manufacturing. Vitalant's national footprint sustains contract volume with large health systems through dedicated account structures.
- Research Laboratories:Academic and commercial facilities conducting hematology research requiring specialized blood components with detailed donor demographic data. Cell therapy manufacturing applications are expanding demand for leukapheresis-derived starting material.
- Emergency Medical Services:Pre-hospital providers in metropolitan trauma corridors expanding blood component storage and administration protocols. Helicopter and ground ambulance services in the United States are deploying thawed plasma and red cell units for field transfusion.
Hospitals command the largest procurement volumes; emergency medical services are gaining share fastest as pre-hospital transfusion protocols mature.
Technology:
Technology maturity curves separate established automated collection from emerging pathogen reduction systems still navigating regulatory validation.
- Automated Blood Collection:Apheresis platforms separating whole blood into components during donation with software-controlled separation parameters. Fresenius SE & Co. KGaA competes in this segment for high-throughput donation center equipment upgrades.
- Blood Management Software:Laboratory information systems and inventory optimization platforms tracking component location, compatibility, and expiration. Hospital networks are consolidating vendor management overhead into centralized procurement functions for enterprise software licensing.
- Pathogen Reduction Technology:Psoralen-based or riboflavin-based systems inactivating residual bacterial and viral contaminants in platelet and plasma components. Blood centers with high-volume hospital contracts are adopting these systems defensively ahead of finalized FDA guidance.
- Point-of-Care Testing:Rapid compatibility and infectious disease screening devices enabling transfusion decisions outside centralized laboratories. Emergency medical services deployment is driving demand for ruggedized portable units with extended battery operation.
Automated blood collection holds the deepest installed base; pathogen reduction technology is climbing the fastest as regulatory pressure accelerates capital replacement cycles.
Application:
Application segmentation tracks clinical utility from routine transfusion support through specialized cellular therapy manufacturing with vastly different margin profiles.
- Transfusion Medicine:Routine red cell, platelet, and plasma support for surgical, oncologic, and trauma indications. Demand concentrates in the United States as academic medical centers expand transfusion services and blood management programs.
- Apheresis:Therapeutic plasma exchange, red cell exchange, and stem cell collection procedures requiring specialized equipment and operator training. Grifols anchors plasma-derived therapeutic supply through specialized collection infrastructure supporting this application.
- Hematopoietic Stem Cell Transplantation:Mobilized peripheral blood stem cell collection and processing for autologous and allogeneic transplant protocols. United States transplant centers are driving demand for CD34+ selection technologies and cryopreservation services.
- Research Studies:Controlled access to blood components for clinical trial endpoints and biomarker discovery programs. Academic medical centers with NIH funding concentration represent the primary customer base with stringent chain-of-custody documentation requirements.
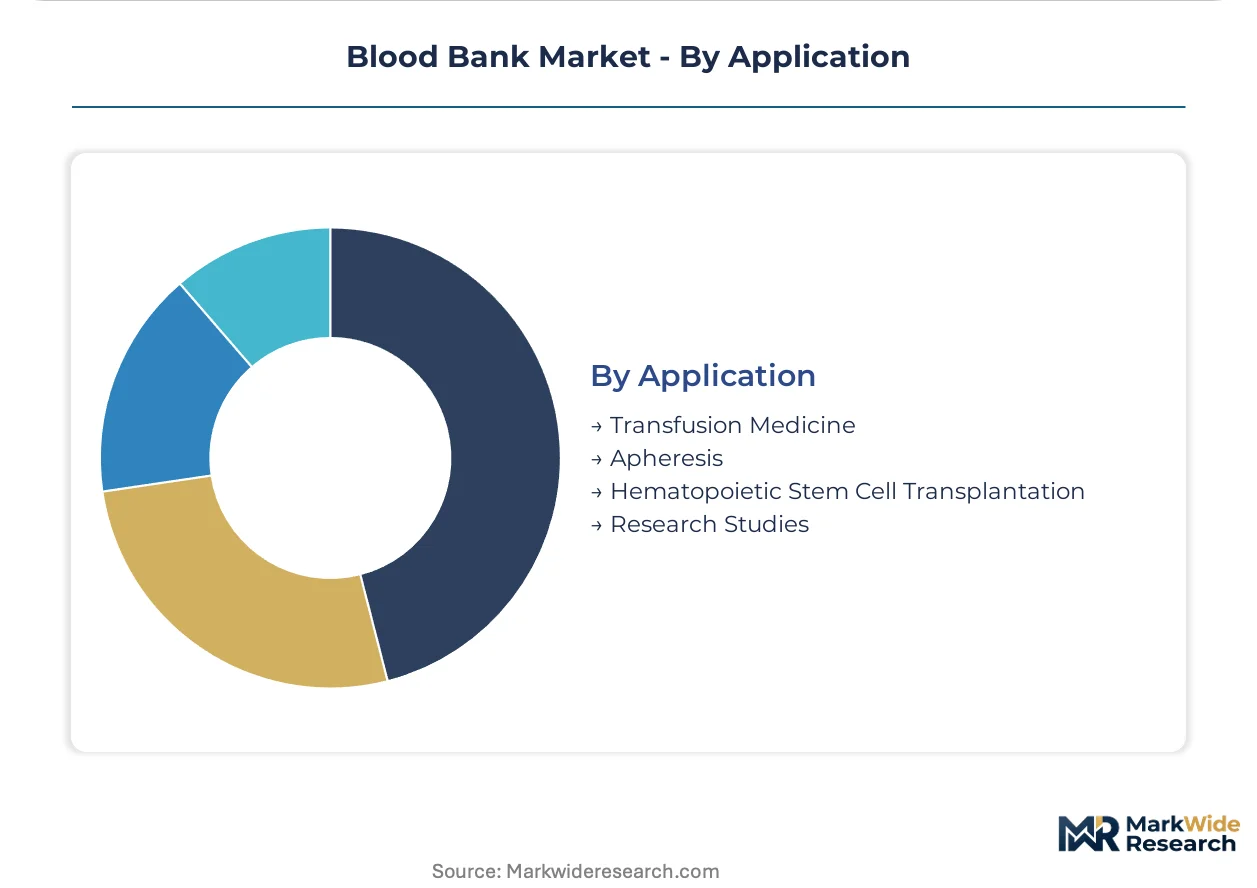
Transfusion medicine consumes the greatest component volume; hematopoietic stem cell transplantation is gaining share fastest as CAR-T manufacturing expands apheresis collection demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States absorb the highest transfusion service volumes, while procurement consolidation across hospital networks is redistributing purchasing power toward integrated delivery networks in major metropolitan corridors.
United States
Hospital network consolidation and pre-hospital transfusion expansion in metropolitan trauma corridors are concentrating demand. The FDA's draft guidance on bacterial risk control in platelets is mandating infrastructure upgrades at collection facilities. Three-hospital systems in Chicago, Houston, and Atlanta represent minimum viable contract scale for blood center vendors securing integrated delivery network agreements.
Germany
EU MDR device classification timelines are extending certification requirements for nucleic acid testing platforms. The country's national pharmaceutical regulator is enforcing expanded technical documentation for software-driven diagnostic algorithms. Industrial clusters in Baden-Württemberg and Bavaria host automated collection device manufacturers restructuring quality management systems for notified body scrutiny.
Japan
Aging demographics and surgical volume concentration in metropolitan hospitals are sustaining component demand. METI guidelines on medical device software validation are shaping nucleic acid testing platform procurement protocols. The Kansai region around Osaka anchors plasma-derived therapeutic manufacturing infrastructure serving domestic transfusion medicine requirements.
Australia
Research laboratory demand for specialized blood components with detailed donor demographic data is expanding. The TGA is aligning blood banking equipment registration requirements with EU MDR technical documentation standards. Sydney and Melbourne academic medical centers are driving demand for leukapheresis-derived starting material in cell therapy manufacturing applications.
India
CDSCO regulatory harmonization with international standards is accelerating nucleic acid testing platform adoption at tertiary care hospitals. Government hospital blood bank modernization programs are expanding automated collection infrastructure in Maharashtra and Karnataka. Mumbai and Bangalore medical institutions are establishing AABB-accredited processing protocols for premium positioning with international research collaborators.
Blood Bank Market Key Industry Players
United States producers anchor one tier; European and Japanese specialists hold differentiated positions in automated collection technology and pathogen reduction systems. The vendor base organizes around three strategic archetypes: national blood center networks with integrated collection and distribution infrastructure, diversified medical technology conglomerates with automated equipment portfolios, and specialized plasma fractionators with captive collection infrastructure. Competitive moves concentrate on strategic partnerships with integrated delivery networks and technology licensing agreements for pathogen reduction systems.
Within the national network tier, Vitalant and the American Red Cross occupy positions defined by geographic coverage scale and hospital contract concentration. Grifols exemplifies the specialized plasma fractionator archetype through its vertically integrated collection infrastructure. Haemonetics Corporation represents the automated equipment specialist segment, with its corporate structure indicating dedicated focus on blood component separation technologies.
| Leading Market Players |
|---|
| The American Red Cross |
| Vitalant |
| Haemonetics Corporation |
| Grifols |
| Terumo Corporation |
| Canadian Blood Services |
| New York Blood Center |
| Australian Red Cross |
| Fresenius SE & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Polyolefin resin indices and specialized cold-storage alloy pricing cascade through blood bag manufacturing into three-tier pricing structures across premium, standard, and economy levels. Hospital procurement consolidation amplifies volume leverage, compressing margins for collection consumables while preserving premium capture for pathogen reduction systems and NAT platforms.
Pricing Analysis
High-volume red cell and plasma components operate on thin per-unit margins sustained by collection scale, while pathogen reduction technology and nucleic acid testing platforms command premium pricing tied to FDA compliance positioning. Price differentiation rests on AABB accreditation tier and integrated service bundling rather than commodity specifications alone. Pricing pressure stems from integrated delivery network procurement centralization demanding inventory guarantees and extended payment terms. Community hospital systems exhibit acute price sensitivity; academic medical centers prioritize compliance assurance over unit cost.
Supply Chain Analysis
FDA device establishment registrations and EU MDR technical documentation requirements gate supplier qualification, extending lead times for nucleic acid testing platform sourcing. Manufacturing concentrates in the United States, Germany, and Japan for automated collection equipment; China and Malaysia anchor blood bag consumable production. Raw material dependencies include medical-grade PVC resins, cryopreservation dimethyl sulfoxide, and diagnostic reagent chemistries. Single-source vulnerability persists for riboflavin-based pathogen reduction photochemicals. Distribution runs through regional blood center hubs maintaining cold chain integrity to hospital transfusion services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood bank market sits in a technology-transition phase where pathogen reduction systems are displacing legacy bacterial detection cultures as the FDA finalizes proactive intervention mandates.
For Market Incumbents: Hedge NAT platform obsolescence risk by accelerating software companion development for laboratory information system integration. Secure backward integration into riboflavin photochemical supply through exclusive sourcing agreements with specialized chemical manufacturers. Prioritize AABB accreditation maintenance as integrated delivery networks consolidate contracts around compliance-verified suppliers. For New Entrants and Emerging Players: The FDA's draft bacterial risk control guidance in the United States opens a window for point-of-care testing device specialists to penetrate emergency medical services deployment. Target pre-hospital transfusion capability expansion in metropolitan trauma corridors where ruggedized portable units face limited incumbent saturation. Pursue software-as-a-service blood management platforms for mid-sized hospital systems seeking enterprise functionality without capital-intensive infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated collection technology specialists in Germany facing EU MDR certification timeline compression. Long-term viability centers on equipment manufacturers with regulatory affairs scale to navigate notified body scrutiny of software-driven diagnostic algorithms. Watch FDA guidance finalization timing as the inflection signal for pathogen reduction technology capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Reduction Technology Licensing | FDA guidance alignment secures defensive positioning ahead of mandatory compliance deadlines. |
| Hospital System Partnership | Integrated delivery network contracts guarantee volume against procurement consolidation pressure. |
| Automated Collection Platform Upgrade | High-throughput donation centers in underserved metros present equipment replacement demand. |
| Cold Chain Logistics Expansion | Regional frozen plasma hubs below -30°C address distribution radius constraints. |
| Software Companion Development | Laboratory information system integration resolves NAT platform workflow reconfiguration challenges. |
Research Approach
Document review covered FDA guidance filings, EU MDR technical documentation standards, AABB accreditation protocols, and hospital procurement database records, complemented by interviews with blood center operations directors, hospital transfusion service chiefs, biomedical equipment procurement managers, and regulatory affairs specialists at diagnostic platform manufacturers. Secondary validation drew from CMS Medicare transfusion data, GPO contract repositories, and SEC 10-K disclosures from listed medical technology suppliers. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-level projections across product type, end user, technology, and application dimensions were generated through installed base modeling and replacement cycle analysis over the projection horizon. CAGRs were derived from regression-weighted scenario outputs incorporating regulatory mandate timing, hospital consolidation trajectories, and technology adoption S-curves. Industry-specific inputs included FDA guidance implementation schedules, AABB accreditation renewal patterns, and blood component utilization rates at academic medical centers.
The model assumes a particular technology adoption path; alternative pathways for pathogen reduction system penetration would alter the outlook if FDA guidance delays or cost curves flatten. Forecasts reflect documented assumptions regarding hospital network consolidation velocity and EU MDR certification timeline extensions. A model refresh is warranted upon material change in FDA bacterial risk control guidance finalization or major integrated delivery network merger activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Hair Restoration Services Market