
 US Concierge Medicine Market | 2026-2036
US Concierge Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
US Concierge Medicine Market Intelligence
Retainer-based patient relationships is rewriting the economics of primary care delivery in the United States. MDVIP leverages its franchise network to extend geographic coverage across suburban markets. SignatureMD anchors its model on physician practice conversion rather than de novo clinic construction. PartnerMD competes through hybrid payment structures that blend membership fees with traditional insurance billing.
US concierge medicine denotes a direct-primary-care arrangement where patients pay periodic retainers for enhanced access, extended consultations, and proactive health management, typically covering 600 to 800 patients per physician compared to 2,500-plus in conventional panels. The primary commercial purpose centers on reducing physician burnout while capturing premium reimbursement for personalized, unhurried care delivery. Primary Care retainers dominate current revenue pools, though Preventive Care and Wellness Programs segments accelerate fastest as employers seek measurable reductions in downstream claims costs. Telemedicine integration within the Technology Utilization dimension now functions as a baseline expectation rather than a premium differentiator.
The Office of the National Coordinator for Health Information Technology and state medical boards govern data interoperability requirements and physician licensing standards that shape operational compliance costs across multi-state concierge networks. The Stark Law and Anti-Kickback Statute, administered by CMS and the HHS Office of Inspector General, constrain how concierge practices structure referral arrangements and fee-sharing with specialist networks. Stakeholders must monitor whether Medicare Advantage expansion into supplemental concierge benefits will open or foreclose addressable patient populations.
Market Dynamics
The Affordable Care Act's coverage mandates and evolving state-level scope-of-practice rules are compressing operational flexibility for concierge networks while simultaneously legitimizing retainer-based care as a parallel delivery channel.
Growth Catalysts
- Employer-sponsored executive health plans:Fortune 500 firms in Florida, Texas, and California are expanding concierge access to C-suite populations, creating enterprise-scale demand anchors.
- HIPAA-compliant telemedicine infrastructure:Remote monitoring platforms now satisfy federal data security requirements, enabling virtual-first membership models.
- Physician burnout mitigation:Panel size reduction from 2,500-plus to 600-800 patients is attracting primary care doctors into conversion arrangements.
Market Restraints
- Stark Law referral constraints:CMS and HHS Office of Inspector General restrictions on fee-sharing with specialist networks limit care coordination revenue streams.
- State licensing fragmentation:Multi-state concierge networks face compliance cost multiplication as medical boards maintain non-uniform telemedicine standards.
- Traditional insurance substitution:High-deductible health plans with health savings accounts compete for the same affluent, health-conscious consumer segment.
Strategic Opportunities
- Medicare Advantage supplemental benefits:CMS demonstration projects testing concierge wraparound coverage could unlock retiree populations in Arizona and Nevada.
- Preventive care outcome guarantees:Employer contracts tying membership fees to measurable downstream claims reductions represent white-space contracting models.
- AI-driven risk stratification:Machine learning integration with electronic health records enables proactive intervention targeting for high-cost chronic conditions.
Industry Challenges
- Interoperability certification timelines:Office of the National Coordinator for Health Information Technology compliance deadlines strain smaller practice conversions.
- Physician recruitment bottlenecks:Limited supply of primary care doctors willing to abandon fee-for-service panels constrains de novo clinic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Concierge Medicine Market |
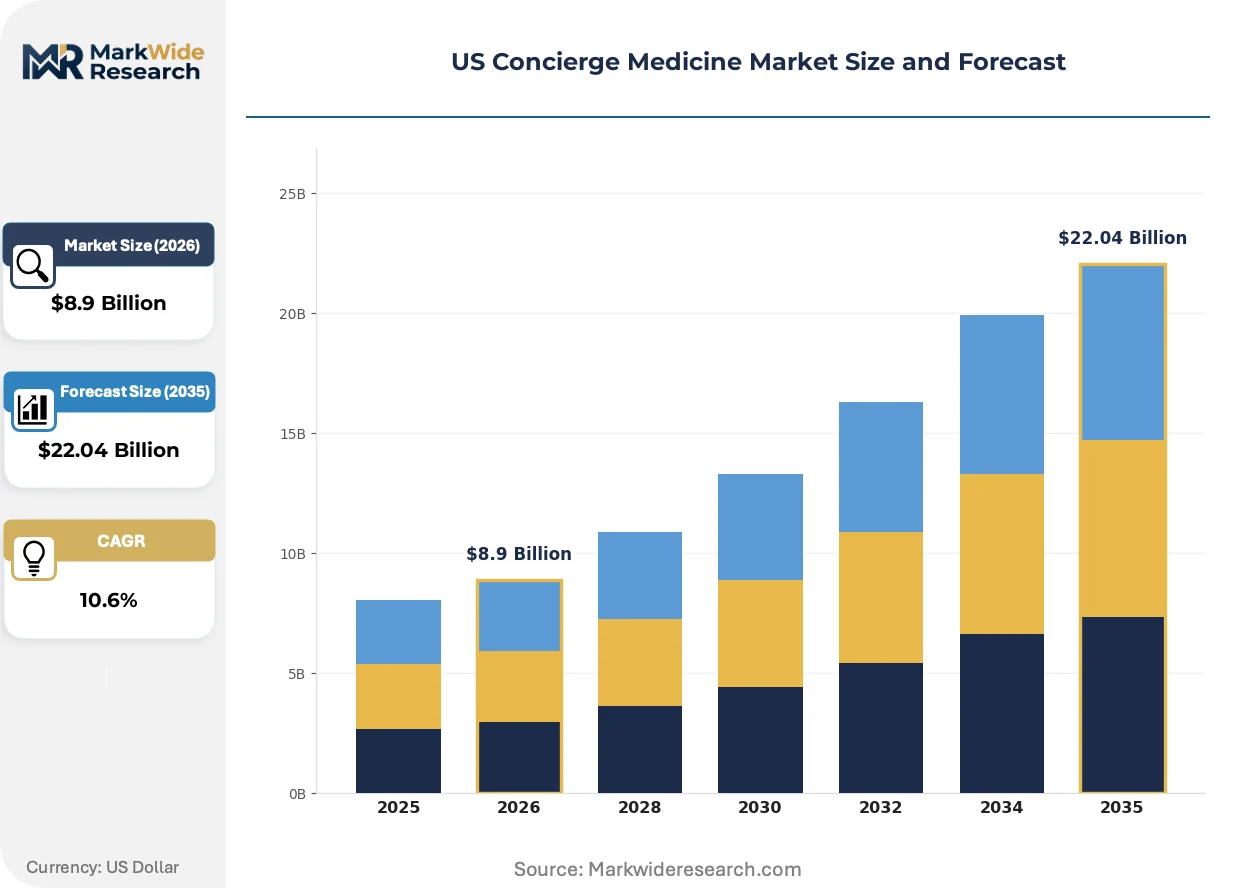
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $22.04 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Care, Specialty Care, Preventive Care, Wellness Programs Payment Model: Direct Pay, Insurance-Based, Retainer, Hybrid Client Type: Individuals, Corporations, Families, High-Net-Worth Clients Technology Utilization: Telemedicine, EHR Systems, Mobile Apps, Wearable Devices |
| Companies Covered | MDVIP, SignatureMD, PartnerMD, Priority Physicians, Inc., Castle Connolly Private Health Partners, Specialdocs Consultants, Crossover Health, Sollis Health, Peninsula Doctor Concierge Medicine, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Concierge Medicine Market Strategic Shifts & Innovations
Technology deployment and payment model experimentation are converging to redefine how concierge practices acquire, retain, and monetize patient relationships across suburban and exurban markets.
Remote patient monitoring hardware is migrating from boutique wellness applications to standard membership inclusions. Cardiology and endocrinology practices adopting concierge models are deploying continuous glucose monitors and blood pressure cuffs as baseline equipment. This technology diffusion is compressing the differentiation window for early telemedicine adopters.
The Anti-Kickback Statute safe harbor expansions proposed by HHS are creating structural openings for specialist network partnerships. Concierge practices are restructuring referral arrangements to capture care coordination fees without triggering federal enforcement. California and New York physician groups are most aggressively testing these revised compliance frameworks.
Patients are demanding unbundled service tiers that separate urgent access from comprehensive wellness programming. Subscription fatigue in other consumer categories is reshaping expectations for healthcare retainers. Texas and Florida markets show the strongest preference for à-la-carte menu structures over all-inclusive membership fees.
US Concierge Medicine Market Segmentation
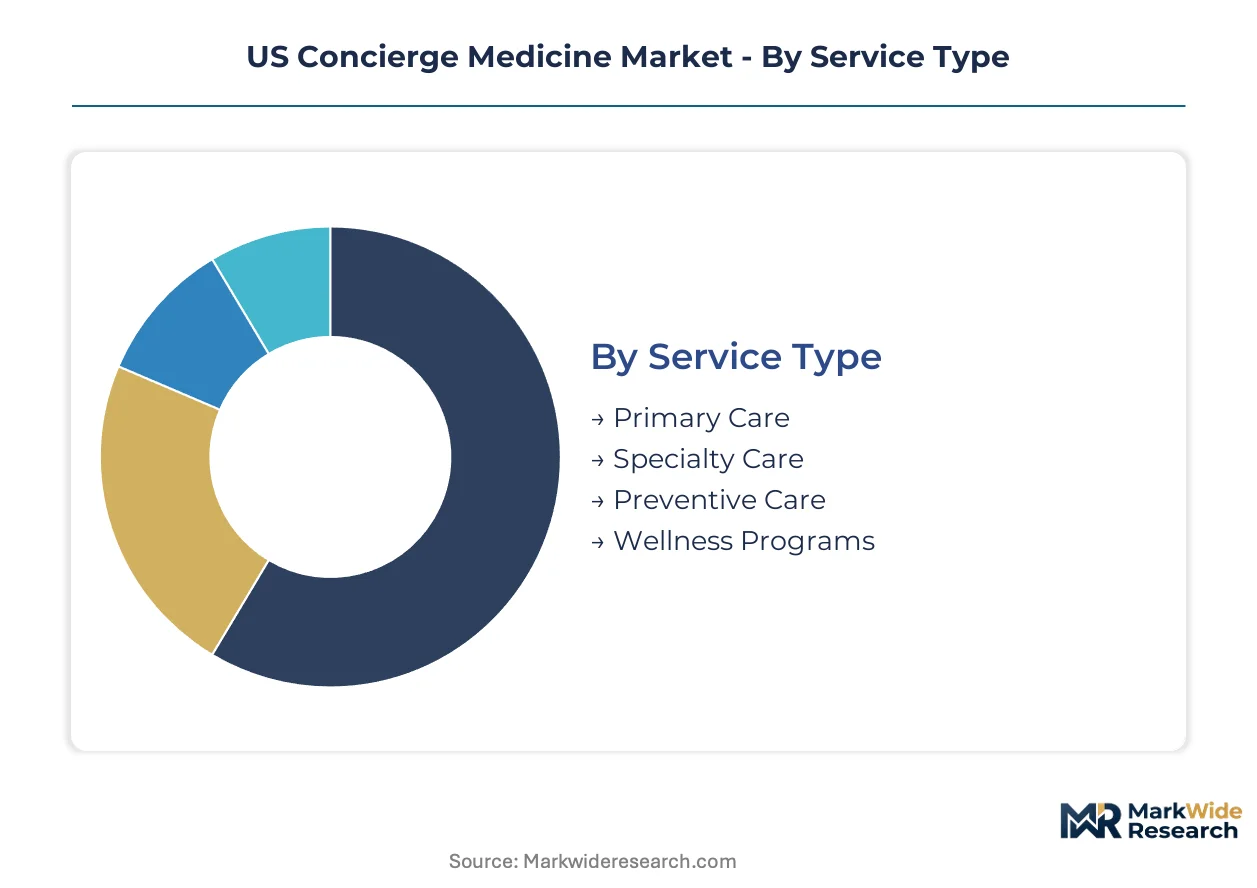
Service configuration and payment architecture determine patient acquisition economics and physician panel sustainability across US concierge networks. Segment boundaries increasingly blur as hybrid models proliferate and technology becomes table stakes rather than differentiation.
Service Type:
Clinical intensity and episode frequency span routine wellness to complex chronic management across the service spectrum.
- Primary Care:Comprehensive generalist services covering acute complaints, chronic disease management, and care coordination form the volume foundation of most concierge practices. Demand concentrates in Florida and Texas suburban markets where Medicare Advantage penetration creates stable reimbursement pools and physician supply constraints elevate access premiums.
- Preventive Care:Proactive screening protocols, lifestyle counseling, and risk-factor modification programs attract employer-sponsored populations seeking measurable downstream claims reductions. Texas and California enterprise contracts favor this segment for executive health assessments and biometric monitoring.
- Specialty Care:Cardiology, endocrinology, and geriatric medicine practices convert to retainer models for complex condition management.
- Wellness Programs:Nutrition coaching, stress management, and fitness integration target affluent self-pay individuals in California coastal markets.
Established volume favors Primary Care; emerging adoption favors Preventive Care.
Payment Model:
Revenue predictability and administrative burden trade off across fee structures with varying insurance integration.
- Retainer:Fixed periodic fees paid directly by patients eliminate claims processing overhead and enable panel size reduction to 600-800 patients per physician. Florida and Arizona retiree populations favor this model for predictable out-of-pocket budgeting and unrestricted specialist access.
- Hybrid:Blended structures combining membership fees with traditional insurance billing maximize addressable patient pools while preserving premium positioning. California and Texas practices lead adoption as HIPAA-compliant infrastructure enables seamless dual-track administration.
- Direct Pay:Pure fee-for-service arrangements without insurance intermediation serve ultra-high-net-worth segments.
- Insurance-Based:Supplemental concierge benefits wrapped around commercial or Medicare Advantage plans.
Margin stability favors Retainer; patient pool expansion favors Hybrid.
Client Type:
Contract scale and decision-making authority concentrate differently across consumer and institutional purchasers.
- Corporations:Fortune 500 firms and mid-market employers sponsor executive health programs as retention tools and productivity investments. Demand clusters in Texas energy sector and California technology corridors where C-suite recruitment competition is most acute.
- High-Net-Worth Clients:Individuals with investable assets exceeding defined thresholds purchase family-wide memberships for privacy, access, and comprehensive coordination. Florida retirement communities and California coastal counties anchor this segment.
- Individuals:Self-directed purchasers seeking alternatives to rushed conventional primary care.
- Families:Multi-generational memberships spanning pediatric through geriatric care.
Contract value favors Corporations; growth velocity favors High-Net-Worth Clients.
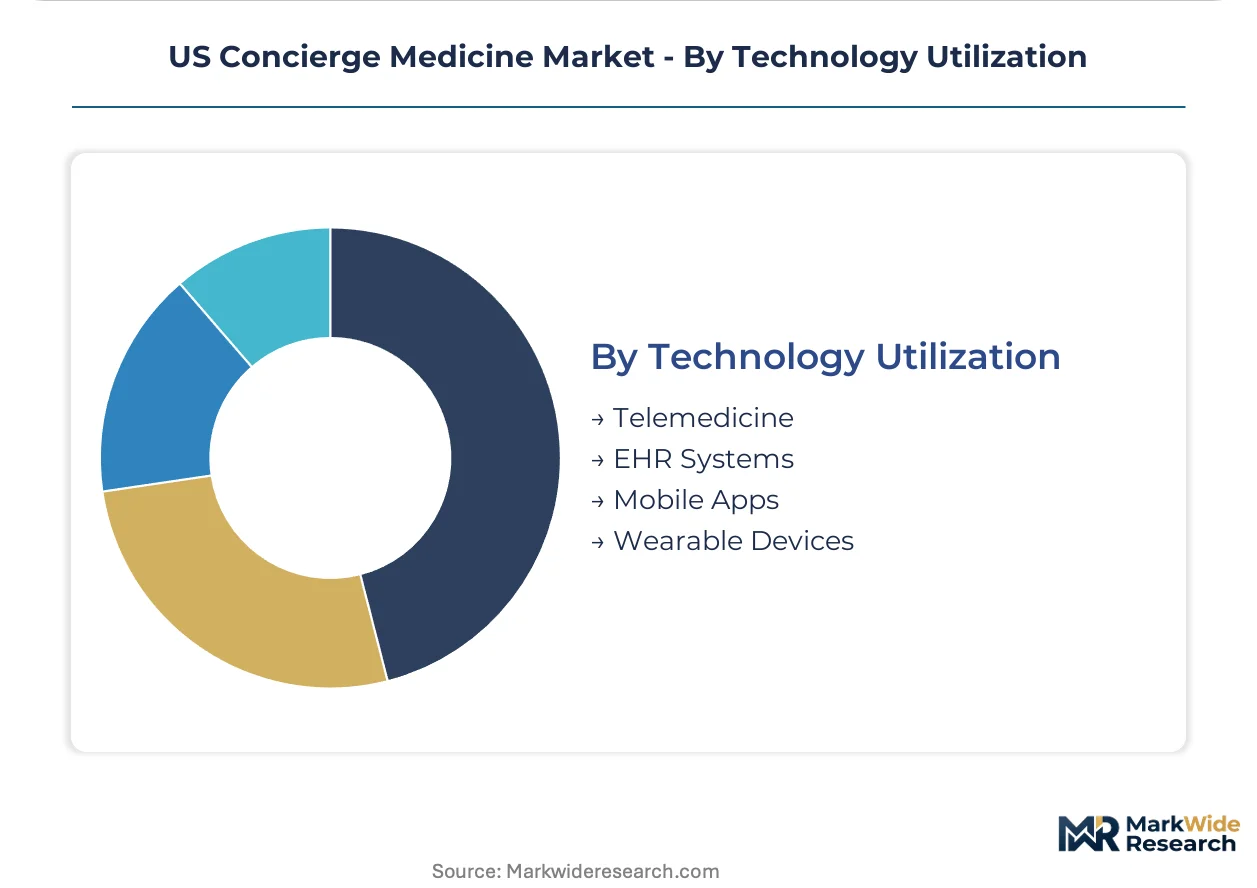
Technology Utilization:
Digital infrastructure maturity now separates viable operations from patient acquisition failures in competitive markets.
- Telemedicine:HIPAA-compliant video consultation platforms enable virtual-first membership tiers and after-hours access extensions. California and Texas regulatory clarity on interstate licensing accelerates multi-state network deployment.
- Wearable Devices:Continuous glucose monitors, blood pressure cuffs, and activity trackers generate real-time biometric streams for proactive intervention. Cardiology and endocrinology practices in Florida deploy these as standard equipment rather than premium add-ons.
- EHR Systems:Interoperability-certified electronic health records satisfy Office of the National Coordinator for Health Information Technology mandates.
- Mobile Apps:Patient-facing scheduling, messaging, and prescription management tools.
Operational necessity favors Telemedicine; differentiation compression favors Wearable Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US markets. Florida retirees accept premium retainers for unrestricted access. California employers negotiate outcome-based contracts. Texas energy executives prioritize immediate availability over cost containment.
Florida
Aging demographics and Medicare Advantage penetration drive demand in retirement corridors. State scope-of-practice rules enable nurse practitioner autonomy, expanding panel capacity. The Naples-Sarasota corridor hosts dense concentrations of retainer-based practices serving seasonal residents.
Texas
Energy sector executive recruitment fuels employer-sponsored concierge expansion. Texas Medical Board telemedicine standards remain permissive, enabling virtual-first membership tiers. Houston and Dallas-Fort Worth anchor hybrid model adoption, blending corporate contracts with individual memberships.
California
Technology sector competition for talent drives Silicon Valley and San Francisco employers toward preventive care outcome guarantees. Department of Managed Health Care oversight shapes insurance integration requirements. Los Angeles and Orange County practices lead wearable device deployment for biometric monitoring.
Arizona
Retiree migration and Medicare Advantage growth create addressable populations for supplemental concierge benefits. Arizona Medical Board licensing clarity supports multi-state network expansion. The Phoenix-Scottsdale corridor attracts conversion arrangements from fee-for-service primary care practices.
Northeast Corridor
High-net-worth density in New York and Boston sustains direct-pay models for privacy-conscious clients. State-level Stark Law enforcement variations complicate specialist referral fee structures. Manhattan and Greenwich anchor ultra-premium segments serving family-office clientele.
US Concierge Medicine Market Key Industry Players
Franchise networks and practice conversion specialists split the market between geographic expansion and physician recruitment strategies. The vendor base concentrates around three archetypes: national franchise operators, regional conversion platforms, and hybrid payment innovators. Consolidation pressure favors acquisition of suburban practices over de novo clinic construction. Technology licensing partnerships now precede most multi-state network launches.
Within the franchise tier, MDVIP anchors suburban market penetration through its distributed physician network. SignatureMD exemplifies the conversion-specialist archetype, targeting established practices rather than new market entry. PartnerMD occupies a hybrid positioning, blending membership fees with traditional insurance billing to maximize addressable patient pools. These three represent distinct strategic responses to regulatory fragmentation and employer contract complexity.
| Leading Market Players |
|---|
| MDVIP |
| SignatureMD |
| PartnerMD |
| Priority Physicians, Inc. |
| Castle Connolly Private Health Partners |
| Specialdocs Consultants |
| Crossover Health |
| Sollis Health |
| Peninsula Doctor Concierge Medicine |
| Others |
Cost & Logistics Intelligence
Undercapacity in physician supply across Florida, Texas, and California is compressing panel availability while elevating retainer pricing power for established practices. This utilization squeeze simultaneously constrains de novo clinic expansion and rewards conversion-focused supply strategies that bypass new market entry costs.
Pricing Analysis
After-sales revenue from wellness program extensions and biometric monitoring subscriptions now drives lifetime patient value beyond initial membership fees. Three-tier pricing structure across comprehensive, primary-care-only, and virtual-access tiers segments buyers by service intensity. Pricing pressure stems from high-deductible health plans competing for affluent consumers through health savings account compatibility. Employer-sponsored populations exhibit lowest price sensitivity; self-directed individual purchasers in suburban Texas markets show highest elasticity.
Supply Chain Analysis
Upstream feedstock of licensed primary care physicians concentrates supply acquisition competition across Florida, Texas, and California where training program output lags demand growth. Practice conversion specialists and franchise networks draw from this same limited talent pool while competing for HIPAA-compliant telemedicine infrastructure vendors. Single-source vulnerability in physician recruitment creates bottlenecks that favor acquisition over organic expansion. Distribution runs through regional medical boards and employer benefits consultants who gate network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in employer-sponsored preventive care contracts, where outcome-based pricing models remain undersupplied relative to Fortune 500 demand for measurable claims reduction.
For Market Incumbents: Pre-empt hybrid payment competitors by securing exclusive Medicare Advantage supplemental benefit contracts in Arizona and Nevada before CMS demonstration project expansion. Backward integration into remote patient monitoring hardware procurement locks in wearable device cost advantages. Physician recruitment bottlenecks threaten panel scalability; anchor retention through equity participation in conversion arrangements. For New Entrants and Emerging Players: Establish a beachhead in corporate wellness outcome guarantees, the segment where established players maintain weakest pricing discipline. Texas energy sector employers offer lowest competitive density for preventive care contracts tied to biometric monitoring. Lead with AI-driven risk stratification capabilities that incumbent EHR integrations cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual-first membership tiers as telemedicine infrastructure commoditizes. Long-term viability favors platforms with hybrid billing capabilities that maximize addressable patient pools across insurance and direct-pay segments. Acquisition targets should demonstrate multi-state licensing compliance and existing employer contract relationships. Watch Medicare Advantage supplemental benefit policy signals as inflection indicator for retiree market addressability.| Strategic Initiative | Industry Significance |
|---|---|
| Physician Practice Conversion | Franchise networks accelerate geographic coverage without de novo construction costs in supply-constrained markets. |
| Hybrid Payment Infrastructure | Seamless dual-track administration enables patient pool expansion while preserving premium positioning against insurance-only competitors. |
| Remote Patient Monitoring Integration | Continuous biometric streams from CMS-cleared devices differentiate proactive intervention capabilities in cardiology and endocrinology segments. |
| Employer Outcome Guarantee Contracts | Measurable downstream claims reduction commitments unlock Fortune 500 executive health program budgets in Texas and California. |
| Multi-State Licensing Compliance | Uniform telemedicine standards across Arizona, Nevada, and Texas enable virtual-first membership tiers with regulatory clarity. |
Research Approach
Initial hypotheses were tested against primary input from concierge practice operators, employer benefits directors, physician recruitment specialists, and Medicare Advantage plan administrators and refined through secondary validation. Primary interviews triangulated with hospital procurement databases, GPO contracts, CMS Medicare data, and state medical board licensing records. Bottom-up practice-level capacity estimates and top-down employer spending analysis were reconciled across the modeling period.
Demand-supply-balance framing anchored the analytical framework across service type, payment model, client type, and technology utilization dimensions. CAGRs were derived from panel size economics and membership fee trajectories observed in conversion arrangements. Forecast inputs incorporated physician burnout migration rates, employer-sponsored program adoption curves, and Medicare Advantage penetration assumptions.
Sensitivities concentrate around Medicare Advantage supplemental benefit policy shifts and state-level scope-of-practice rule changes that could accelerate or constrain nurse practitioner panel expansion. Forecasts reflect documented assumptions regarding physician recruitment feasibility and employer contract renewal rates. Cross-checking against CMS demonstration project enrollment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Hospice Market
Healthcare Services
European Union Cross Border Healthcare Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Medical Spa Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Health Care Supply Chain Management Market