
 Active Phased Array Radar (APAR) Market | 2026-2036
Active Phased Array Radar (APAR) Market Size, Share, and Industry Trends Forecast 2026-2036
Active Phased Array Radar (APAR) Market Analysis
Gallium nitride performance tiers are rotating toward the center of procurement specifications, displacing legacy gallium arsenide architectures in frontline naval and airborne programs. Thales Group leverages in-house semiconductor foundry partnerships to sustain GaN module yield rates above industry norms. Raytheon Technologies anchors its APAR portfolio around digital beamforming architectures that integrate with Aegis combat systems. Northrop Grumman dominates next-generation space radar bids through specialized antenna array designs optimized for orbital debris tracking and satellite self-defense.
Active Phased Array Radar employs electronically steered transmit-receive modules arranged in planar or conformal arrays to steer radio-frequency beams without mechanical gimbals, typically operating in X-band through S-band frequencies with instantaneous bandwidth exceeding 500 MHz for multi-target resolution. The technology serves military and civil operators requiring simultaneous search, track, and fire-control functions under electromagnetic countermeasure conditions. Naval radar systems occupy the largest installed base among system type categories, reflecting decade-long shipbuilding cycles and retrofit mandates across major fleets. Digital beamforming represents the fastest-expanding technology segment, as software-defined waveform processing enables single-array multi-mission flexibility that hardware-steered alternatives cannot match. Missile guidance applications concentrate the highest unit-value contracts, where seeker-integrated APAR arrays command premium pricing tied to hit-to-kill accuracy thresholds.
FAA certification standards for civil airspace integration and ITAR export controls administered by the US State Department jointly shape vendor market access and foreign customer eligibility. ESA and national space agencies in Europe impose debris-mitigation design requirements that filter into APAR specifications for orbital platforms. China's MIIT and SAMR enforce domestic frequency allocation and encryption standards that condition technology transfer terms for foreign suppliers operating within its procurement ecosystem. Stakeholders must weigh sovereign content mandates against modular open-architecture commitments when positioning for multi-national program bids.
Market Dynamics
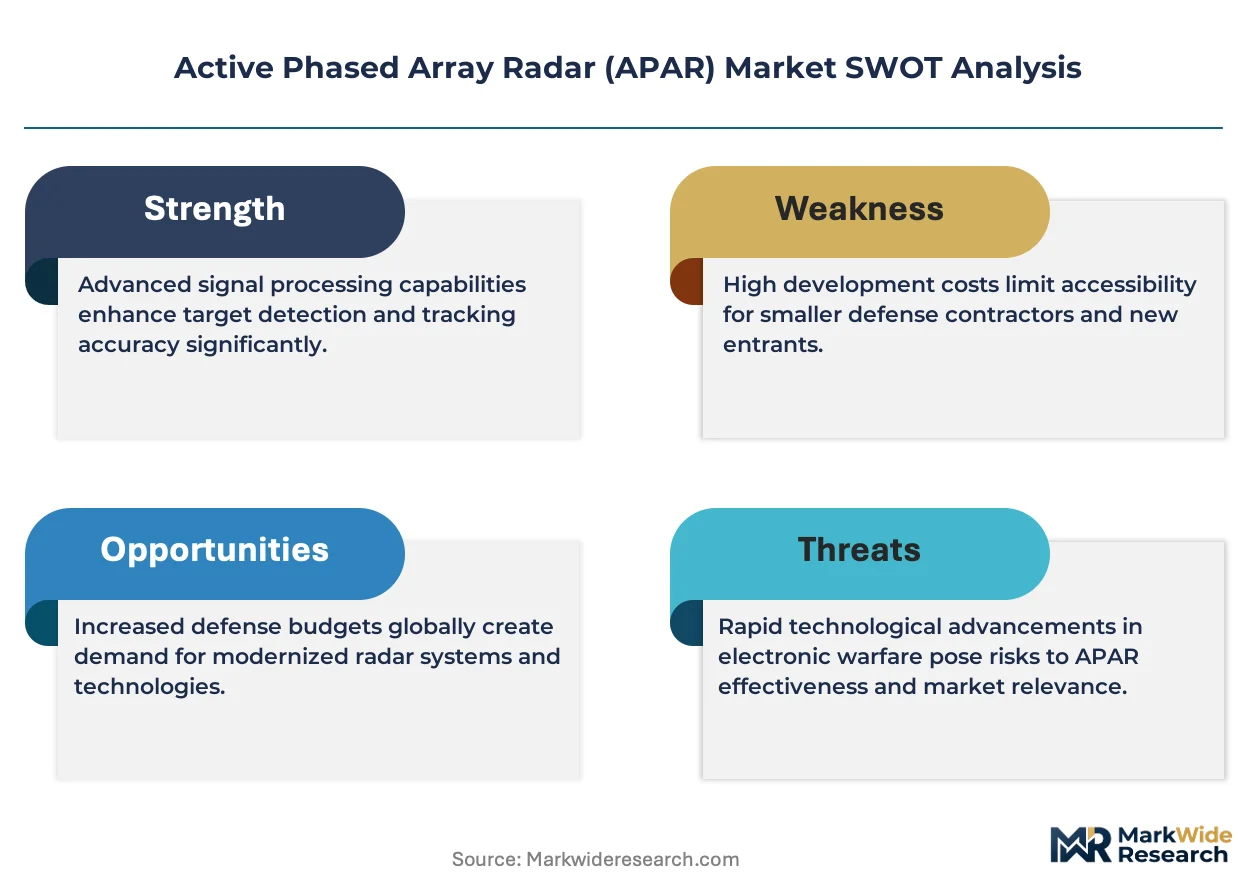
GaN semiconductor fabrication advances are compressing transmit-receive module costs while extending operational lifecycles, fundamentally restructuring procurement economics for naval and airborne radar programs across NATO and Indo-Pacific defense budgets.
Growth Catalysts
- Naval Modernization Mandates:NATO member states are accelerating multi-function APAR procurement through dedicated shipbuilding programs and fleet retrofit schedules. The US Navy's DDG(X) program and UK Type 26 frigate builds exemplify this capital allocation pattern.
- REACH and RoHS Material Standards:European environmental compliance frameworks are filtering hazardous substance restrictions into semiconductor packaging specifications, creating demand for compliant GaN foundry outputs that legacy gallium arsenide suppliers struggle to match.
- Dual-Use Spectrum Allocation:Civil aviation authorities in the US, Japan, and Australia are releasing X-band and S-band frequencies for weather radar and air traffic management, expanding addressable demand beyond military procurement.
Market Restraints
- Substrate Supply Concentration:High-purity silicon carbide substrates for GaN epitaxy concentrate among Japanese and US specialty material suppliers, creating input cost volatility and qualification bottlenecks for second-tier module manufacturers.
- ITAR Export Control Friction:US State Department administered controls restrict transmit-receive module technology transfer to specific foreign end-users, fragmenting vendor addressable markets and complicating multinational program participation.
- Thermal Management Limitations:Power-density thresholds in compact airborne arrays remain constrained by cooling system mass budgets, capping instantaneous bandwidth for fighter-integrated fire-control radars below theoretical semiconductor limits.
Strategic Opportunities
- Orbital Debris Tracking Satellites:ESA and national space agencies are mandating debris-mitigation sensor payloads for new satellite constellations, creating demand for specialized space-qualified APAR arrays with ultra-low power consumption profiles.
- Indo-Pacific Littoral Surveillance:Island-chain defense strategies in the Philippines, Indonesia, and Vietnam are driving coastal radar network investments where solid-state APAR replaces mechanically scanned legacy systems for multi-target tracking.
- Software-Defined Waveform Convergence:Digital beamforming architectures are merging with artificial intelligence-driven signal processing, enabling single-array multi-mission flexibility that hardware-steered alternatives cannot replicate.
Industry Challenges
- GaN Foundry Talent Scarcity:Compound semiconductor process engineering expertise concentrates among a narrow cohort of specialists trained at specific US and Japanese research institutions, constraining production scale-up for qualified module suppliers.
- Aegis Combat System Integration Complexity:Naval APAR procurement requires backward compatibility with existing combat management architectures, extending certification timelines and freezing architectural innovation for programs locked into legacy interfaces.
- Patent Thicket Navigation:Digital beamforming algorithm IP and phased array calibration methods fragment across defense primes and university research licensing offices, complicating freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Phased Array Radar (APAR) Market |
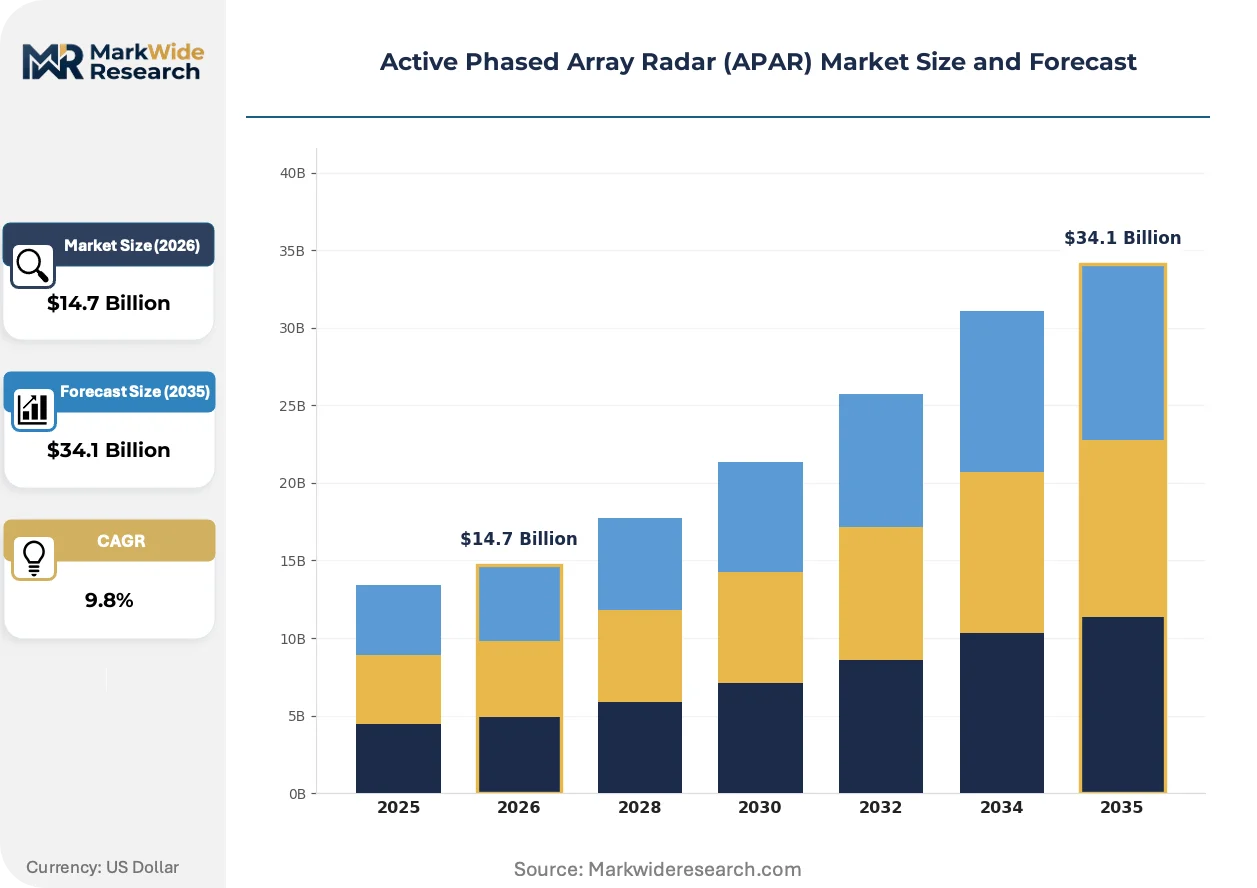
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $34.1 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Naval Radar, Airborne Radar, Ground-Based Radar, Space Radar Application: Surveillance, Target Tracking, Missile Guidance, Weather Monitoring End User: Defense Agencies, Civil Aviation, Research Institutions, Commercial Operators Technology: Solid State, Digital Beamforming, Frequency Modulation, Multi-Function |
| Companies Covered | Thales Group, Leonardo S.p.A., Raytheon Technologies, L3Harris Technologies, Saab AB, Northrop Grumman, BAE Systems, China Electronics Technology Group Corporation, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Phased Array Radar (APAR) Market Emerging Trajectories
Radio-frequency semiconductor material transitions and software-defined processing architectures are converging to reshape radar system procurement specifications, compressing development cycles while expanding multi-mission flexibility requirements.
Gallium nitride high-electron-mobility transistors are displacing legacy gallium arsenide monolithic microwave integrated circuits in frontline naval and airborne fire-control radars. US and European defense primes are adopting GaN modules for active electronically scanned arrays at accelerating qualification pace. This displacement is enabling higher power-aperture products within fixed antenna volume constraints, compressing competitive differentiation around thermal management rather than raw transmit power.
EU AI Act risk classification frameworks are extending algorithmic transparency requirements into military-adjacent dual-use radar signal processing. European defense procurement agencies are embedding explainability mandates for automated target recognition subsystems. Naval surface combatant programs in France, Germany, and Italy are most affected, with Thales and Hensoldt restructuring software development workflows to satisfy documentation burdens.
Defense procurement agencies are consolidating vendor relationships around modular open-architecture commitments that unbundle hardware from software upgrade paths. Long-term performance-based logistics contracts are displacing transactional spare-part purchasing for APAR lifecycle support. This consolidation is most visible in US Navy and Royal Australian Navy shipbuilding programs, where prime contractors absorb subsystem integration risk across multi-decade service intervals.
Active Phased Array Radar (APAR) Market Segmentation
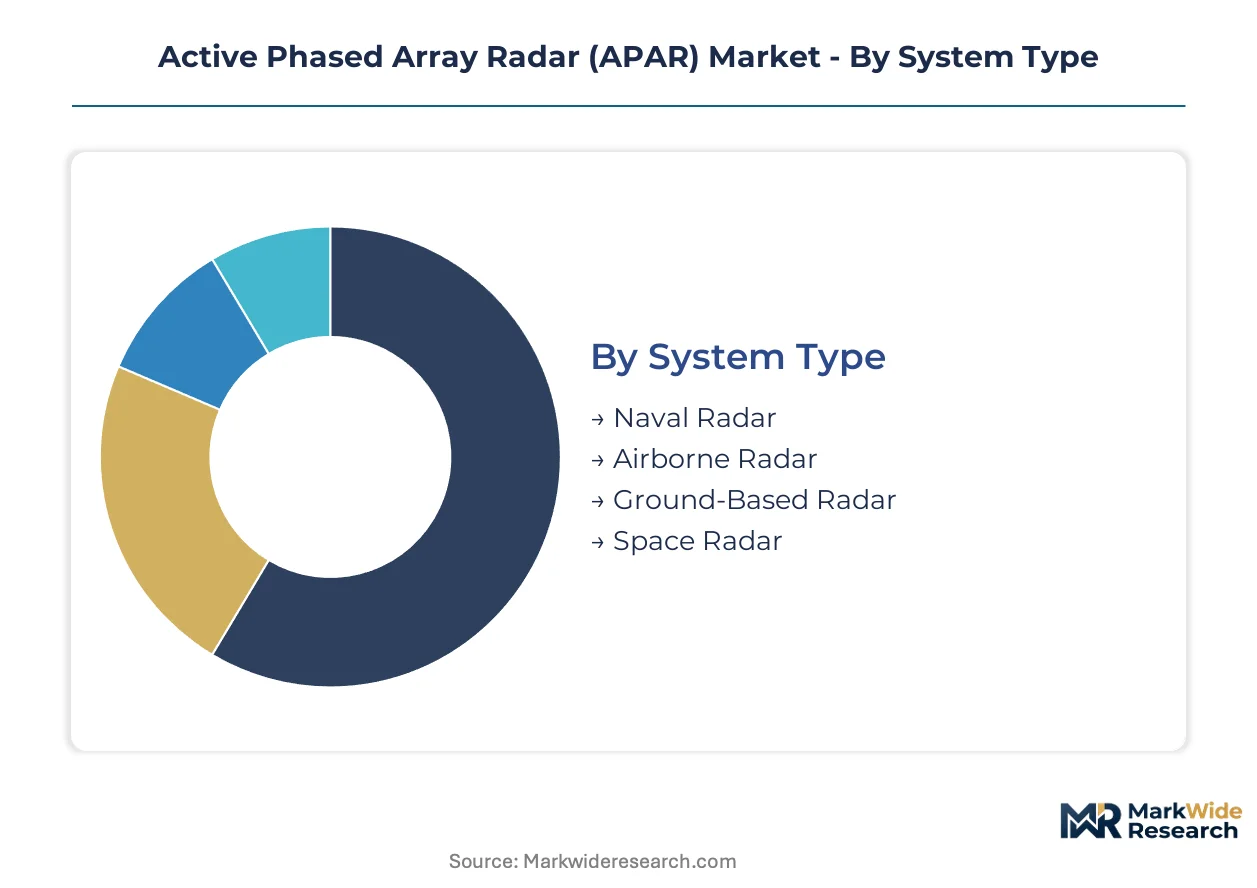
APAR procurement patterns diverge sharply across operational domains, with naval and airborne platforms commanding premium unit economics while ground-based and space applications reshape supplier capability requirements. Semiconductor material transitions and software-defined architectures are fragmenting vendor specializations along technology lines.
System Type:
Naval and airborne platforms face intensifying substitution pressure from unmanned sensor networks and satellite constellations, forcing incumbent suppliers to defend installed-base positions through mid-life upgrade programs.
- Naval Radar:Multi-function arrays integrated into combat management architectures for search, track, and fire-control missions. Demand concentrates in US, UK, and Australian shipbuilding programs where DDG(X) and Type 26 frigate builds mandate solid-state replacements for mechanically scanned legacy systems. NATO fleet retrofit schedules sustain aftermarket module demand across 30-year service lifecycles.
- Airborne Radar:Fighter-integrated fire-control arrays and wide-area surveillance pods operating under severe thermal and mass constraints. Procurement clusters in Indo-Pacific defense budgets where F-35 and regional fighter programs drive GaN module qualification timelines. Cooling system mass budgets cap instantaneous bandwidth below theoretical semiconductor limits.
- Ground-Based Radar:Coastal and border surveillance networks replacing rotating antenna systems with fixed-face solid-state alternatives. Island-chain defense strategies in Philippines and Vietnam accelerate littoral network investments.
- Space Radar:Ultra-low-power arrays for orbital debris tracking and satellite self-defense payloads. ESA debris-mitigation mandates filter into specifications for new constellation deployments.
Naval Radar retains volume leadership; Space Radar holds the steepest expansion curve.
Application:
Cost tier stratification separates mission-critical defense applications from civil meteorological systems, with missile guidance commanding unit-value premiums that weather monitoring cannot approach.
- Surveillance:Wide-area search and early warning functions requiring simultaneous multi-target resolution. Coastal networks in Indonesia and littoral zones drive procurement concentration.
- Target Tracking:Precision angle and range estimation for fire-control handoff. Naval surface combatant programs anchor demand through integration with Aegis combat systems.
- Missile Guidance:Seeker-integrated arrays for terminal homing and hit-to-kill accuracy. Unit pricing ties directly to accuracy thresholds and electronic counter-countermeasure resilience.
- Weather Monitoring:Dual-use civil aviation deployments under FAA and Japan CAA spectrum allocations. X-band and S-band frequency releases expand addressable demand beyond military procurement.
Surveillance absorbs the largest procurement volumes; Missile Guidance captures the highest margin tier.
End User:
Customer type determines certification burden and technology transfer restrictions, with defense agencies imposing ITAR compliance that commercial operators escape.
- Defense Agencies:Military procurement through national shipbuilding and aircraft programs. US State Department export controls fragment vendor addressable markets.
- Civil Aviation:Air traffic management and weather radar under FAA and national aviation authority certification. Dual-use spectrum allocations expand procurement eligibility.
- Research Institutions:Experimental arrays for atmospheric and space science. ESA and national space agencies impose debris-mitigation design requirements.
- Commercial Operators:Satellite constellation operators procuring space-qualified subsystems. Sovereign content mandates condition supplier selection for multi-national bids.
Defense Agencies dominate absolute spending; Commercial Operators are climbing the fastest.
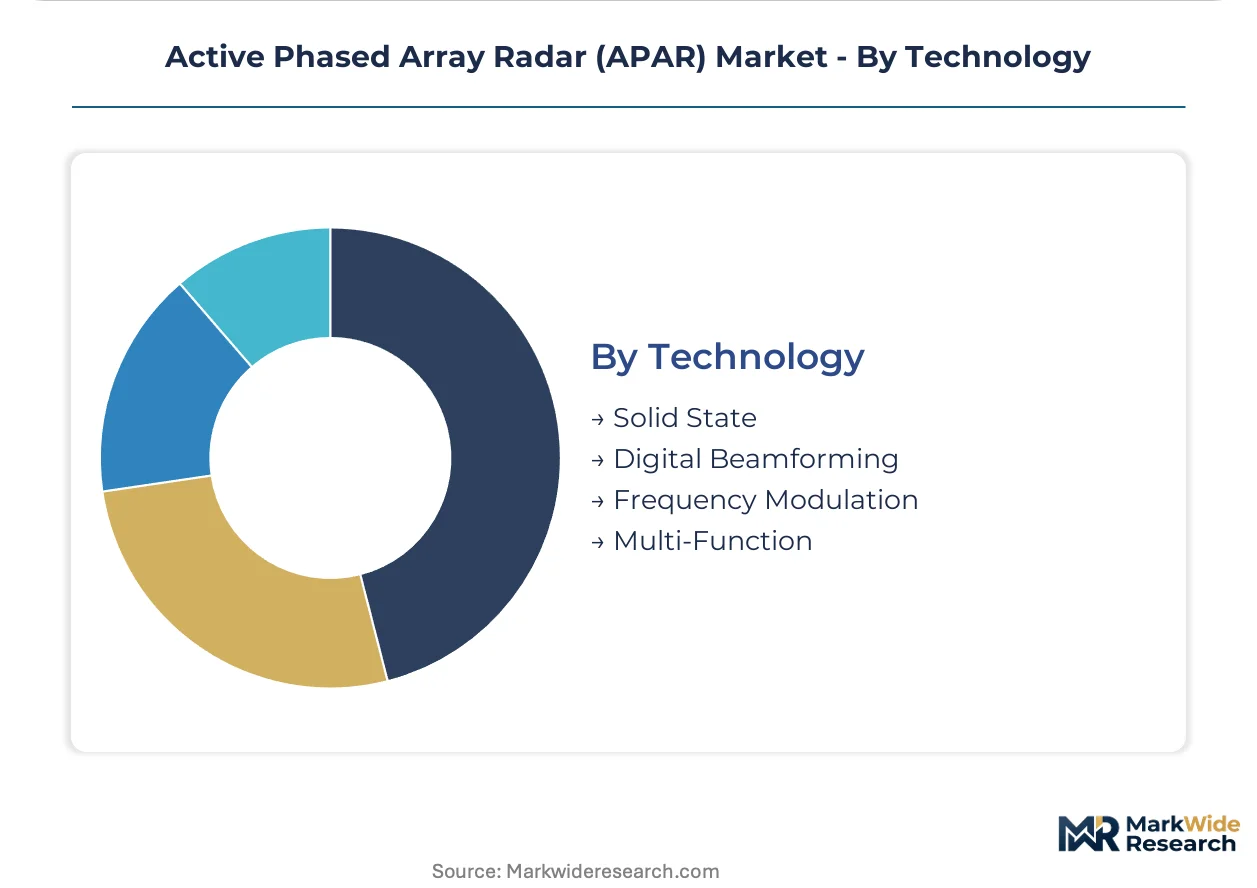
Technology:
Supply concentration in GaN foundry capacity and digital signal processing IP is concentrating competitive advantage among vertically integrated primes.
- Solid State:Transmit-receive module architectures displacing vacuum-tube legacy systems. GaN fabrication advances compress costs while extending operational lifecycles.
- Digital Beamforming:Software-defined waveform processing enabling single-array multi-mission flexibility. AI-driven signal processing merges with EU AI Act explainability mandates.
- Frequency Modulation:Linear frequency-modulated continuous-wave techniques for compact short-range applications. Limited to specialized naval and airborne auxiliary roles.
- Multi-Function:Combined search-track-fire-control capability through time-energy management algorithms. Procurement specifications increasingly mandate this architecture for new naval builds.
Solid State commands installed-base dominance; Digital Beamforming is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply by geography. Indo-Pacific buyers prioritize capability over unit cost, while European programs emphasize lifecycle economics under fiscal consolidation pressures.
United States
Naval modernization drives demand through DDG(X) destroyer builds and Aegis combat system retrofits. The FAA administers civil spectrum allocations for dual-use weather radar applications. Defense primes cluster around Washington DC, Boston, and Southern California corridors where Pentagon procurement offices and semiconductor foundries maintain proximity.
China
Island-chain defense strategies and indigenous naval shipbuilding sustain procurement volumes. MIIT and SAMR enforce domestic frequency allocation and encryption standards that condition technology transfer terms. State-owned conglomerates concentrate manufacturing in Yangtze River Delta and Pearl River Delta industrial zones.
United Kingdom
Type 26 frigate construction and Royal Navy fleet renewal anchor naval radar demand. REACH and RoHS material standards filter hazardous substance restrictions into semiconductor packaging specifications. Defense electronics suppliers concentrate in Bristol, Portsmouth, and Glasgow shipbuilding corridors.
Germany
Naval surface combatant programs and NATO interoperability requirements drive multi-function array procurement. The KBA and federal procurement offices enforce sovereign content mandates for military systems. Industrial clusters in Bavaria and North Rhine-Westphalia host radar subsystem integrators and compound semiconductor research facilities.
Australia
Hunter-class frigate builds and Indo-Pacific littoral surveillance networks expand solid-state radar deployments. The TGA and defense procurement agencies mandate modular open-architecture commitments for long-term support contracts. Defense industrial activity concentrates in Adelaide shipyards and Canberra procurement offices.
Active Phased Array Radar (APAR) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated defense primes control GaN foundry partnerships and digital beamforming IP, while specialized subsystem suppliers compete on module qualification speed. Three archetypes dominate: semiconductor-integrated primes, platform-locked integrators, and state-affiliated national champions. Consolidation concentrates around M&A for GaN foundry access and strategic partnerships for Aegis combat system integration.
Within the vertically integrated tier, Thales Group and Raytheon Technologies exemplify archetypes combining in-house semiconductor capabilities with combat system integration depth. Northrop Grumman occupies a specialized position in space-qualified arrays. State-affiliated structures include China Electronics Technology Group Corporation, representing national champion models with captive domestic demand.
| Leading Market Players |
|---|
| Thales Group |
| Leonardo S.p.A. |
| Raytheon Technologies |
| L3Harris Technologies |
| Saab AB |
| Northrop Grumman |
| BAE Systems |
| China Electronics Technology Group Corporation |
| Lockheed Martin |
| Others |
Supply Flow & Price Mechanics
Gallium nitride module substitution for legacy gallium arsenide architectures simultaneously redraws supply geography toward Japanese and US substrate foundries while compressing unit economics across NATO naval procurement programs. This material transition concentrates pricing power among vertically integrated primes with captive GaN epitaxy partnerships, locking second-tier suppliers into margin-squeezing module qualification races.
Pricing Analysis
Performance-based logistics contracts spanning multi-decade naval service intervals generate lifetime value that dwarfs initial hardware transactions. Three-tier pricing structure across mission-critical defense, dual-use civil aviation, and research-grade experimental tiers separates Aegis-integrated naval arrays from FAA-certified weather radar and ESA debris-tracking payloads. Cost compression in solid-state transmit-receive modules intensifies as GaN fabrication yields improve, though missile guidance seekers retain premium pricing immunity. Civil aviation operators exhibit acute price sensitivity compared to defense agencies prioritizing electronic counter-countermeasure resilience over unit cost.
Supply Chain Analysis
Inbound logistics costs for high-purity silicon carbide substrates hinge on container availability through transpacific trade lanes serving Japanese specialty material suppliers. GaN epitaxy draws from substrate concentrations in Japan and the USA, with compound semiconductor packaging feeding from German and South Korean precision manufacturing hubs. Single-source vulnerability pervades silicon carbide substrate supply, where qualification timelines exceed two years for alternative vendors. Distribution runs through prime contractor-led subsystem integration chains terminating at national shipbuilding yards and aircraft final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent radar suppliers face sustained substitution pressure from software-defined radio architectures and satellite-based sensor networks that threaten to displace traditional phased array installations. Defense primes must navigate this threat through strategic repositioning across three stakeholder categories.
For Market Incumbents: Consolidate GaN foundry partnerships through exclusive supply agreements or equity stakes in Japanese substrate specialists, insulating module cost structures from input volatility. Deepen backward integration into digital beamforming algorithm IP through targeted university licensing acquisitions, neutralizing patent thicket exposure that delays new program entry. Lock in Aegis combat system integration moats by absorbing subsystem certification risk across DDG(X) and Type 26 program lifecycles. For New Entrants and Emerging Players: Lead with software-defined waveform processing as a service layer atop commoditized hardware, penetrating the gap between prime contractor platforms and end-user customization demands. Target ground-based coastal surveillance networks in Indonesia and Vietnam where island-chain defense budgets outstrip qualified supplier capacity. Pursue ESA debris-mitigation payload qualifications as a beachhead into satellite constellation procurement cycles with lower incumbent saturation than naval programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compound semiconductor foundries holding GaN process expertise trained at specific US and Japanese research institutions. Five-to-ten year viability hinges on sustained naval modernization procurement through NATO and Indo-Pacific defense budgets rather than cyclical civil aviation demand. Monitor ITAR export control relaxation signals as the inflection indicator for addressable market expansion beyond current State Department restricted end-user lists.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership Acquisition | Captive substrate supply secures module cost advantage for DDG(X) and Type 26 competitions. |
| Digital Beamforming IP Licensing | Algorithm portfolios from university research offices unlock Aegis integration compliance. |
| Performance-Based Logistics Contracting | Multi-decade service commitments transform transactional spare-part revenue into predictable annuities. |
| ESA Debris-Mitigation Payload Qualification | Ultra-low-power array certification opens satellite constellation procurement beyond naval saturation. |
| Modular Open-Architecture Certification | Unbundled hardware-software upgrade paths satisfy Royal Australian Navy and US Navy procurement mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense procurement databases, SEC contractor filings, and ESA technical specifications. Interviews with radar subsystem procurement officers at national shipbuilding agencies, GaN foundry process engineering directors, and Aegis combat system integration managers inform demand-side validation. Customs trade data for silicon carbide substrates, ITAR license disclosure records, and FAA certification registries provide supply-side triangulation against bottom-up module shipment estimates.
Segmentation dimensions modeled span system type, application mission, end-user category, and semiconductor technology across the projection horizon. Naval radar, airborne fire-control, ground-based surveillance, and space-qualified arrays constitute system-type splits. Surveillance, target tracking, missile guidance, and weather monitoring define application segments. Defense agencies, civil aviation authorities, research institutions, and commercial satellite operators capture end-user heterogeneity. Solid-state, digital beamforming, frequency modulation, and multi-function architectures differentiate technology trajectories. CAGRs derive from shipbuilding program schedules, fleet retrofit timelines, and satellite constellation deployment cadences.
The analysis sits within stated boundaries; outcomes outside sustained NATO naval modernization commitments, stable ITAR export control frameworks, and continued GaN yield improvements would require recalibration. Forecasts reflect assumptions regarding defense budget elasticity, compound semiconductor talent pipeline depth, and dual-use spectrum allocation permanence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Airborne ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Asia-Pacific C4ISR Market
ISR
North America C5ISR Market
ISR
United States C4ISR Market
ISR
Land Based C4ISR Market
ISR
C5ISR Market
ISR
Brazil C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
NATO C4ISR Market
ISR
Europe C5ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Low Altitude Radar Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Australia C4ISR Market