
 Naval Radar Market | 2026-2036
Naval Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Radar Market Analysis
The US Department of Defense's updated electromagnetic environmental effects requirements under MIL-STD-461 is broadening the cost-of-entry calculus for naval radar suppliers. Thales Group leverages its GaN transmitter foundry investments to sustain competitive positioning in multi-function phased arrays. BAE Systems anchors its naval portfolio through integrated radar-electronic warfare suites for the UK Royal Navy's Type 26 frigates. RTX Corporation differentiates via software-defined radar architectures that reduce hardware swap costs across ship classes.
Naval radar denotes shipboard electromagnetic detection systems operating across X-band, S-band, and L-band frequencies, typically generating peak powers from kilowatts to megawatts through solid-state or vacuum tube transmitters to detect, track, and classify surface and aerial contacts beyond the visual horizon. Surface radar configurations dominate current procurement volumes due to ballistic missile defense and anti-ship missile warning requirements aboard destroyers and frigates. Synthetic aperture radar variants represent the fastest-expanding technology segment as navies prioritize all-weather, high-resolution surface imaging for littoral operations. The end-user base concentrates heavily among tier-one navies, though coast guard organizations in middle-power states are emerging as incremental volume purchasers for exclusive economic zone patrol.
The US Navy's Naval Sea Systems Command enforces stringent MIL-STD-810 environmental qualification and MIL-STD-461 electromagnetic compatibility standards that filter out suppliers lacking defense-grade manufacturing infrastructure. European procurement operates under NATO STANAG interoperability mandates and the EU's developing defense industrial strategy, while China's State Administration for Market Regulation imposes GB standards on dual-use radar exports. Stakeholders must monitor how AUKUS technology-sharing protocols reshape supplier eligibility across US, UK, and Australian naval programs.
Market Dynamics
GaN transmitter technology is compressing incumbent vacuum tube supply chains while MIL-STD-461 electromagnetic compatibility standards are disqualifying suppliers lacking defense-grade manufacturing infrastructure. These twin forces are restructuring competitive eligibility across NATO and Indo-Pacific naval programs.
Growth Catalysts
- AUKUS Technology-Sharing Protocols:The trilateral security pact between Australia, the United Kingdom, and the United States is consolidating procurement specifications for integrated multi-function radar systems across three major naval modernization programs.
- Ballistic Missile Defense Mandates:Surface combatant radar suites aboard destroyers and frigates face expanded detection and tracking requirements against hypersonic and maneuvering reentry vehicle threats.
- Exclusive Economic Zone Patrol Expansion:Coast guard organizations in Indonesia, Vietnam, and the Philippines are acquiring naval-grade surface search radars for maritime domain awareness missions.
Market Restraints
- GaN Substrate Supply Concentration:High-purity gallium nitride wafer production concentrates among Japanese and US semiconductor foundries, creating single-source vulnerability for transmitter module manufacturers.
- MIL-STD-461 Qualification Burden:Electromagnetic environmental effects testing requirements under this US military standard impose multi-year certification timelines that freeze out commercial-industrial radar suppliers.
- Active Electronically Scanned Array Cost Structure:Thousands of transmit-receive modules per array drive unit costs that constrain procurement volumes for middle-power navies.
Strategic Opportunities
- Synthetic Aperture Radar for Littoral Operations:All-weather, high-resolution surface imaging capabilities are opening new mission profiles for naval aviation and unmanned surface vessels in contested near-shore environments.
- Software-Defined Architectures:Programmable waveform generation and digital beamforming are enabling hardware commonality across ship classes, reducing logistics footprints for fleet operators.
- EU Defense Industrial Strategy Procurement Alignment:The European Union's developing framework for joint capability development is creating pooled demand mechanisms for multi-national frigate programs.
Industry Challenges
- Electromagnetic Spectrum Certification Bottlenecks:National frequency allocation authorities in major procurement markets impose site-specific interference studies that extend delivery schedules by 18-24 months.
- Legacy System Integration Complexity:Shipboard combat management systems from prior generations require custom interface development for new radar data formats, inflating non-recurring engineering costs.
- Specialized RF Engineering Talent Scarcity:Microwave and phased array design expertise concentrates among aging workforce cohorts at prime contractors and specialized research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Radar Market |
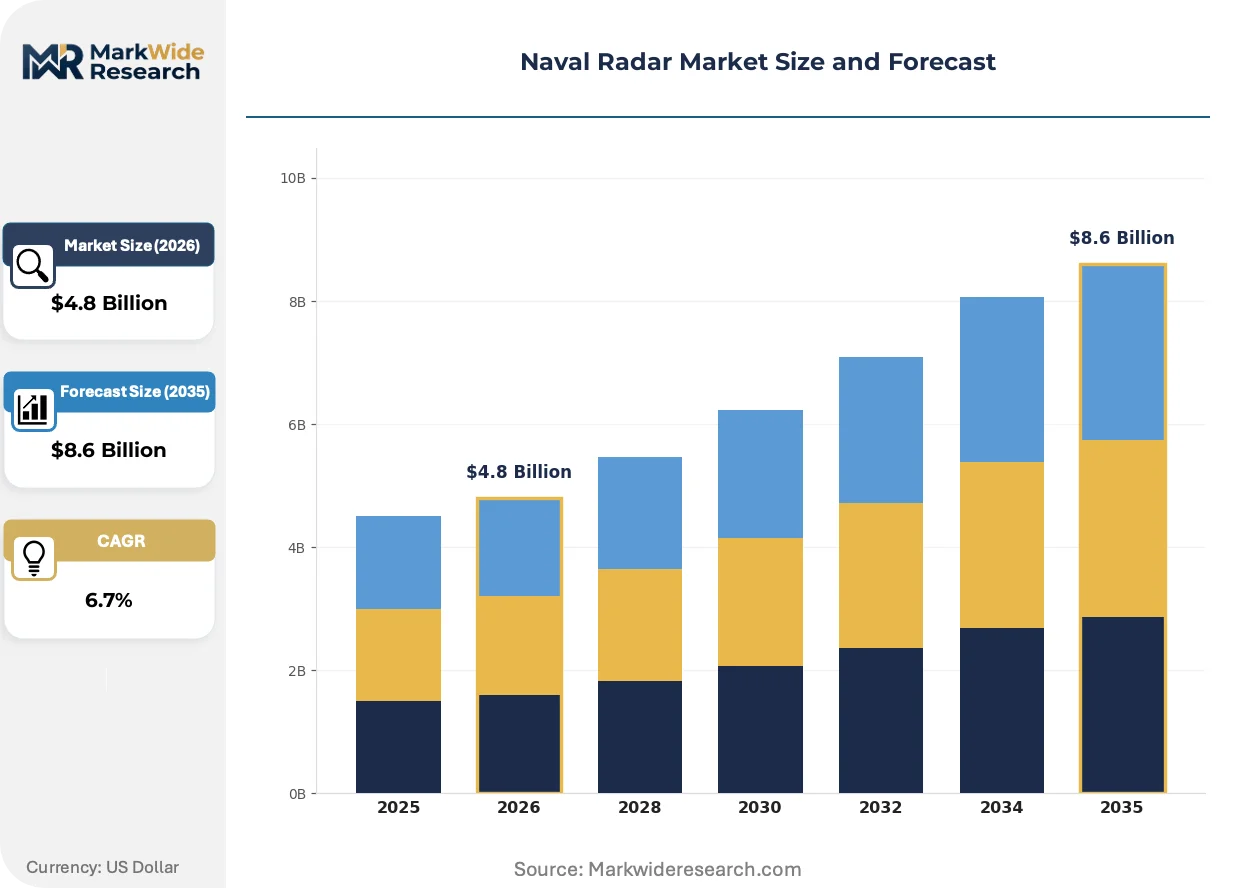
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Radar, Surface Radar, Ground-Based Radar, Space-Based Radar Technology: Pulsed Radar, Continuous Wave Radar, MIMO Radar, Synthetic Aperture Radar End User: Navy, Coast Guard, Commercial Vessels, Defense Contractors Application: Surveillance, Navigation, Target Acquisition, Search and Rescue |
| Companies Covered | Thales Group, BAE Systems plc, RTX Corporation, Saab AB, Leonardo S.p.A., Lockheed Martin Corporation, HENSOLDT AG, L3Harris Technologies, Inc., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Radar Market Emerging Trajectories
Digital beamforming and solid-state transmitter modules are displacing analog architectures and vacuum tube power sources. These shifts are compressing hardware refresh cycles while expanding software upgrade pathways.
Gallium nitride power amplifiers are decentralizing radar transmitter manufacturing away from specialized traveling-wave tube suppliers toward semiconductor fabrication facilities. Major surface combatant programs in the United States, United Kingdom, and Australia are mandating GaN-based active electronically scanned arrays for next-generation destroyers and frigates. This semiconductor transition is collapsing the historical separation between radar and electronic warfare hardware suppliers.
The European Union's developing defense industrial strategy is mandating cross-border component sourcing and joint qualification testing for naval systems procured under pooled funding mechanisms. This regulatory framework is forcing non-EU suppliers to establish EU-based manufacturing or partnership structures to compete for Type 26 frigate derivative programs. French, Italian, and Spanish naval procurement agencies are aligning previously national certification requirements under this emerging structure.
Naval customers are unbundling hardware procurement from through-life support contracts, creating separate competitive arenas for initial system delivery and sustainment services. This purchasing pattern shift is compressing margins on original equipment while expanding recurring revenue pools for integrated logistics support providers. The UK Royal Navy's Type 26 program and US Navy's DDG(X) program both exhibit this bifurcated contracting structure.
Naval Radar Market Segmentation
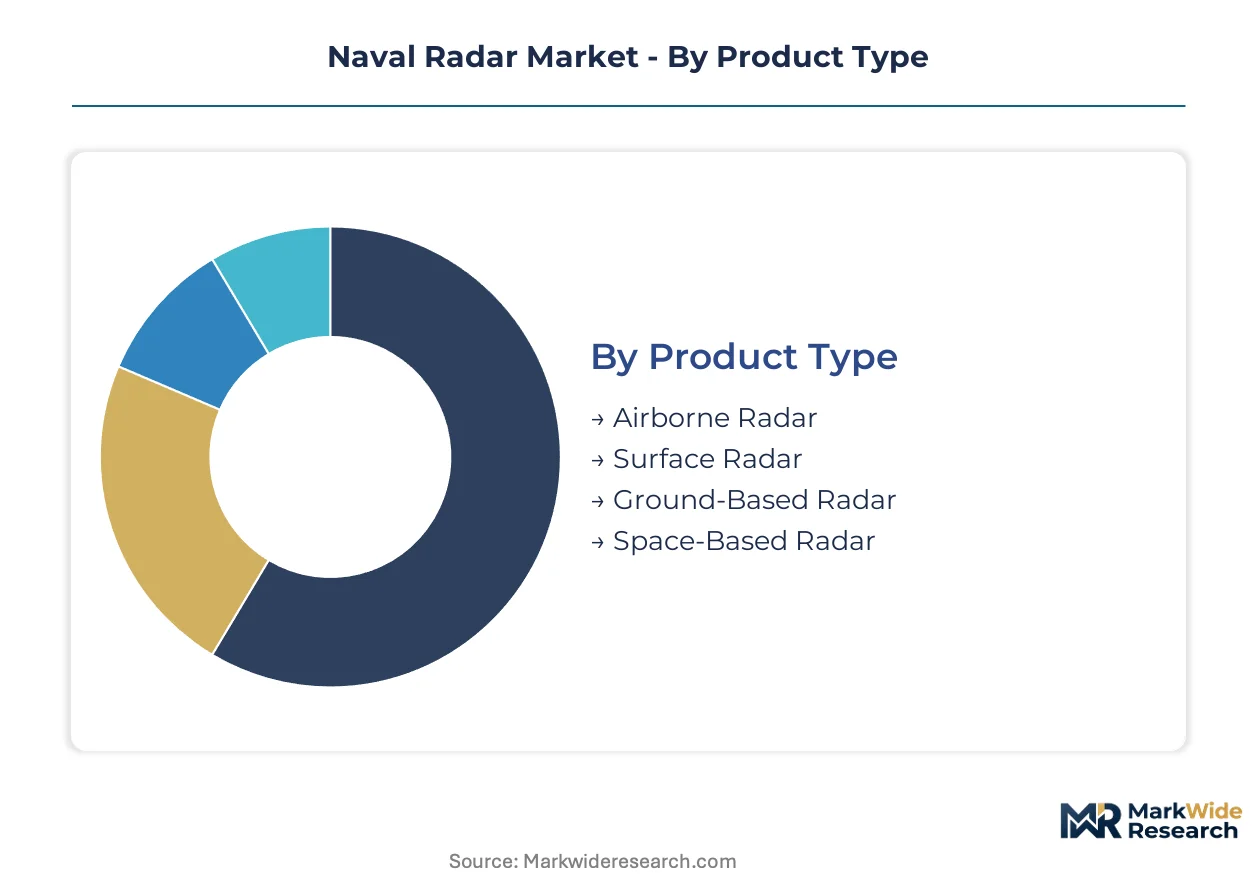
Procurement officers in naval programs segment radar acquisitions by mission environment, signal processing architecture, and operational authority. Each dimension shapes qualification requirements, integration complexity, and through-life support obligations differently.
Product Type:
Platform selection determines transmitter power budgets, antenna aperture constraints, and environmental qualification severity.
- Surface Radar:Shipborne systems operating across S-band and X-band frequencies with active electronically scanned arrays for ballistic missile defense and anti-ship missile warning. The US Navy's DDG(X) program and UK Royal Navy's Type 26 frigates concentrate procurement volumes here, driven by integrated multi-function radar mandates under AUKUS protocols.
- Airborne Radar:Helicopter and maritime patrol aircraft systems prioritizing lightweight synthetic aperture modes for littoral surface imaging. Naval aviation units in Australia and the United Kingdom are expanding procurement for anti-submarine warfare and exclusive economic zone patrol missions.
- Ground-Based Radar:Coastal surveillance and harbor defense installations with fixed or transportable configurations. Port authorities in Indonesia and Vietnam are acquiring these systems for maritime domain awareness.
- Space-Based Radar:Satellite constellations providing over-the-horizon detection and ocean surface monitoring. Intelligence agencies and national space commands represent concentrated demand for broad-area maritime surveillance.
Surface radar leads on scale; airborne radar leads on momentum.
Technology:
Signal generation methods differentiate hardware refresh cycles, software upgrade pathways, and supplier qualification barriers.
- Synthetic Aperture Radar:Coherent processing of multiple radar returns generates high-resolution imagery independent of weather or illumination conditions. Unmanned surface vessel programs and naval aviation units in contested littoral environments are accelerating procurement of these all-weather imaging systems.
- Pulsed Radar:Traditional pulse-compression techniques with vacuum tube or solid-state transmitters for long-range detection and tracking. Legacy destroyer and frigate programs continue specifying these architectures for ballistic missile defense missions.
- Continuous Wave Radar:Uninterrupted transmission enabling Doppler processing for moving target indication. Coastal surveillance and harbor traffic management applications favor these systems for low-power, continuous operation.
- MIMO Radar:Multiple-input multiple-output architectures using spatial diversity for improved resolution and clutter suppression. Research institutions and experimental naval programs are evaluating these configurations for next-generation distributed sensor networks.
Pulsed radar dominates installed base; synthetic aperture radar climbs the fastest.
End User:
Operational authority shapes threat spectrum, interoperability requirements, and budget cycle predictability.
- Navy:Tier-one naval forces with multi-billion-dollar modernization programs specifying integrated radar-electronic warfare suites. The US Navy, UK Royal Navy, and Royal Australian Navy enforce MIL-STD-461 and MIL-STD-810 qualification standards that filter supplier eligibility.
- Coast Guard:Maritime law enforcement agencies acquiring naval-grade surface search radars for exclusive economic zone patrol. Organizations in Indonesia, Vietnam, and the Philippines represent incremental volume growth for littoral surveillance missions.
- Commercial Vessels:Merchant marine operators specifying navigation and collision avoidance radars under International Maritime Organization regulations. Container shipping lines and offshore energy operators drive replacement demand for aging X-band systems.
- Defense Contractors:System integrators procuring radar subsystems for platform integration and export programs. Prime contractors competing for NATO and Indo-Pacific naval programs source transmitter modules and antenna arrays from specialized suppliers.
Navy commands the largest procurement budgets; coast guard organizations are gaining share fastest.
Application:
Mission function determines waveform diversity, track file capacity, and human-machine interface complexity.
- Surveillance:Broad-area detection and track maintenance against air and surface threats. Destroyer and frigate combat management systems integrate these functions with electronic warfare and fire control for integrated air and missile defense.
- Target Acquisition:Precision tracking for weapon engagement with high update rates and low latency. Aegis combat system upgrades and comparable European programs concentrate investment here for hypersonic threat response.
- Navigation:Surface picture compilation for collision avoidance and piloting in restricted waters. Commercial vessels and naval auxiliaries specify these capabilities under international maritime safety conventions.
- Search and Rescue:Specialized waveforms and processing for detecting small targets and distress beacons. Coast guard organizations and naval aviation units prioritize these modes for humanitarian and disaster response missions.
Surveillance absorbs the greatest development investment; target acquisition shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval radar manufacturing traces its modern lineage to Cold War-era defense industrial bases in the United States and United Kingdom, where integrated combat system architectures first consolidated detection, tracking, and engagement functions aboard surface combatants.
United States
The US Navy's DDG(X) program and AUKUS submarine modernization concentrate procurement of multi-function phased arrays under Naval Sea Systems Command oversight. MIL-STD-461 electromagnetic compatibility standards filter supplier eligibility through defense-grade manufacturing requirements. Massachusetts and Maryland host prime contractor engineering clusters developing software-defined radar architectures for next-generation destroyers.
United Kingdom
The Royal Navy's Type 26 frigate program anchors integrated radar-electronic warfare suite procurement under NATO STANAG interoperability mandates. The UK's developing defense industrial strategy aligns cross-border component sourcing with pooled European funding mechanisms. Scotland's shipbuilding yards and southern England's defense electronics corridor concentrate subsystem integration and combat management system development.
Australia
AUKUS technology-sharing protocols reshape Royal Australian Navy procurement specifications for surface combatant and submarine radar suites. The country's national defense regulator enforces electromagnetic environmental effects standards harmonized with US MIL-STD frameworks. South Australian shipyards and Victoria's defense technology precinct coordinate platform integration with US and UK industrial partners.
France
The French Navy's FREMM and future frigate programs sustain demand for active electronically scanned arrays under national procurement agency direction. ANSM and defense procurement authorities coordinate certification with NATO interoperability requirements. Brittany's naval base infrastructure and Paris-region electronics clusters support combat system integration for domestic and export programs.
Japan
Japan Maritime Self-Defense Force destroyer modernization accelerates procurement of GaN-based radar systems under METI industrial policy coordination. JIS standards and national frequency allocation authorities impose site-specific electromagnetic certification timelines. Yokosuka naval infrastructure and Kansai-region electronics manufacturing concentrate platform integration and transmitter module production.
Naval Radar Market Vendor Landscape
The competitive structure tilts toward systems integrators with captive defense-grade manufacturing infrastructure. Prime contractors anchor procurement through multi-decade platform relationships, while specialized transmitter module suppliers occupy sub-tier positions. Three archetypes dominate: vertically integrated combat system houses, semiconductor foundry-backed radar specialists, and software-defined architecture pioneers. Consolidation pressure intensifies through GaN substrate supply concentration and electromagnetic qualification barriers that freeze out commercial-industrial entrants.
Within the integrated systems tier, Thales Group, BAE Systems plc, and RTX Corporation exemplify contrasting strategic positions. Thales leverages European foundry investments in GaN transmitter technology. BAE Systems anchors UK and Commonwealth naval programs through combat management system integration. RTX Corporation occupies a position emphasizing software-defined architectures that reduce hardware refresh burdens across ship classes. These three represent how geographic defense industrial bases and technology specialization create differentiated competitive vectors in naval radar procurement.
| Leading Market Players |
|---|
| Thales Group |
| BAE Systems plc |
| RTX Corporation |
| Saab AB |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| HENSOLDT AG |
| L3Harris Technologies, Inc. |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Gallium nitride transmitter module production is collapsing the historical cost separation between radar and electronic warfare hardware suppliers while concentrating manufacturing among Japanese and US semiconductor foundries. This semiconductor transition simultaneously compresses unit economics for active electronically scanned arrays and eliminates multi-source competition for high-purity GaN substrates.
Pricing Analysis
The bundled hardware-through-life support contract split is restructuring competitive arenas for naval radar procurement. Three-tier pricing structure across MIL-STD-461 qualified, NATO STANAG compliant, and commercial-industrial grades reflects certification burden differentiation. Pricing pressure stems from coast guard organizations in Indonesia and Vietnam demanding naval-grade capabilities at reduced procurement volumes. Navy tier-one programs exhibit lowest price sensitivity due to integrated combat system mandates.
Supply Chain Analysis
Regional distribution centers in Yokosuka, Scotland, and South Australia coordinate hub-and-spoke patterns for classified transmitter modules and antenna arrays. Manufacturing concentrates in Japan, the United States, and the United Kingdom for defense-grade GaN foundry output. Raw material dependencies include high-purity gallium nitride wafers, specialized RF substrates, and rare earth magnetic components. Single-source vulnerability in Japanese GaN substrate production creates supply chain risk. Distribution runs through national naval procurement agencies with site-specific electromagnetic certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval radar procurement is shifting toward margin expansion as software-defined architectures reduce hardware refresh frequency and expand recurring upgrade revenue. GaN transmitter standardization across AUKUS programs creates premium-tier pricing power for qualified suppliers.
For Market Incumbents: Deepen captive GaN foundry investments to defend against semiconductor fabrication entrants lacking MIL-STD-461 qualification infrastructure. Expand software-defined radar architecture deployment across DDG(X) and Type 26 programs to lock in through-life support contracts. Vertical integration into transmitter module production addresses single-source substrate vulnerability while compressing competitor margin space. For New Entrants and Emerging Players: Digital-channel route through unmanned surface vessel programs offers lowest qualification barriers for synthetic aperture radar specialists. Coast guard organizations in Vietnam and the Philippines represent most penetrable demand segment for naval-grade surface search capabilities. Partnership structures with established combat system integrators provide fastest path to NATO STANAG certification. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized RF engineering firms with aging workforce demographics and limited succession planning. Long-term viability over the next decade hinges on GaN fabrication capability consolidation and electromagnetic spectrum certification asset ownership. Acquisition target archetype: mid-tier transmitter module suppliers with existing defense-grade manufacturing infrastructure. Signal to watch: AUKUS technology-sharing protocol expansions beyond Australia, United Kingdom, and United States.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive substrate production at Japanese and US facilities reduces single-source vulnerability for Thales and RTX transmitter modules. |
| Software-Defined Architecture Deployment | Programmable waveform generation enables hardware commonality across US Navy DDG(X) and UK Royal Navy Type 26 destroyer classes. |
| MIL-STD-461 Certification Investment | Defense-grade electromagnetic compatibility qualification filters commercial-industrial radar suppliers from NATO naval procurement pools. |
| Synthetic Aperture Radar Product Launch | All-weather imaging capabilities address Royal Australian Navy requirements for littoral unmanned surface vessel operations. |
| AUKUS Technology Partnership Structure | Trilateral coordination harmonizes procurement specifications across US, UK, and Australian multi-function phased array programs. |
Methodological Framework
Bottom-up naval program modeling reconciled against top-down GaN transmitter supply tracking forms the analytical core of this study. Primary interviews with naval procurement officers at NAVSEA and Royal Australian Navy, combat system integrators at BAE Systems and Thales, RF engineering directors at specialized transmitter module suppliers, and coast guard fleet managers in Indonesia and Vietnam combined with secondary validation. Secondary sources include US Department of Defense budget justification documents, NATO STANAG certification registries, UK Ministry of Defence equipment plans, Japanese METI industrial production statistics, and customs records for GaN substrate trade flows.
Historical trendline analysis of active electronically scanned array procurement volumes across surface combatant programs established baseline growth patterns. The forecast framework segments by platform type, signal processing architecture, operational authority, and mission function while modeling technology transition curves for GaN transmitter adoption. CAGRs derive from program-level procurement timelines for DDG(X), Type 26, and AUKUS submarine modernization. Industry-specific inputs include shipyard delivery schedules, electromagnetic spectrum certification timelines, and defense industrial base capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for vacuum tube transmitter retention would alter the outlook for incumbent traveling-wave tube suppliers. Forecasts reflect documented assumptions regarding AUKUS protocol implementation pace, GaN substrate manufacturing yield improvements, and NATO interoperability mandate enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Combat Management System Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Anti-Ship Missile Defense System Market