
 Airborne ISR Market | 2026-2036
Airborne ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne ISR Market Intelligence
The US Department of Defense's JADC2 mandate is rebalancing contractor qualification requirements toward modular, open-architecture systems. Lockheed Martin Corporation leverages its Skunk Works division to sustain rapid prototyping pipelines for next-generation ISR airframes. Northrop Grumman Corporation dominates high-altitude long-endurance segments through its specialized unmanned platforms. BAE Systems plc anchors European NATO interoperability by navigating divergent national certification standards across member air forces.
Airborne ISR encompasses intelligence, surveillance, and reconnaissance missions conducted from aerial platforms equipped with sensor payloads operating at altitudes from tactical low-level to stratospheric regimes, typically integrating electro-optical, radar, and signals intelligence collection in real-time data networks. Synthetic Aperture Radar technology leads platform capability investments due to its all-weather, day-night operational envelope, while drone platforms represent the fastest-expanding segment as militaries prioritize attritable systems over manned asset risk. Fixed-Wing Aircraft still occupy the largest value pool in current procurement cycles, though rotary-wing configurations retain critical utility in littoral and mountainous terrain access.
The US Federal Aviation Administration coordinates unmanned system airspace integration with DoD operational authorities, while NATO's STANAG standards shape transnational equipment interoperability requirements. The European Union's developing defense industrial strategy through the European Defence Fund is creating parallel certification pathways that compete with traditional national procurement frameworks. Stakeholders must monitor how export control regimes under the US International Traffic in Arms Regulations evolve to determine market access for foreign platform integrators and subsystem suppliers.
Market Dynamics
The Pentagon's Joint All-Domain Command and Control mandate is forcing defense contractors toward open-architecture sensor integration, dismantling proprietary lock-in that historically protected incumbent platform suppliers.
Growth Catalysts
- JADC2 Architecture Mandate:The US Department of Defense's interoperability directive compels modular payload standards across manned and unmanned fleets, accelerating subsystem refresh cycles independent of airframe replacement.
- Attritable Systems Doctrine:Military end-users prioritize low-cost unmanned platforms for contested airspace, redirecting procurement toward drone swarms and disposable sensor carriers.
- NATO STANAG Harmonization:Standardized certification protocols across allied air forces reduce duplicate testing burdens, enabling cross-border maintenance networks and pooled fleet availability.
Market Restraints
- Gallium Nitride Supply Concentration:China controls raw material refining for advanced radar components, exposing prime contractors to export restriction vulnerabilities in high-performance Synthetic Aperture Radar production.
- FAA Airspace Integration Friction:Civil-military coordination delays for beyond-visual-line-of-sight unmanned operations compress operational tempo for domestic training missions.
- Electro-Optical Sensor Saturation:Mature infrared focal plane array technology faces substitution pressure from multi-spectral imaging systems in next-generation payload competitions.
Strategic Opportunities
- European Defence Fund Parallel Certification:EU industrial strategy creates alternative qualification pathways for non-US suppliers, fragmenting traditional national procurement monopolies in France, Germany, and Italy.
- AI-Enabled Sensor Fusion:Machine learning convergence with signals intelligence processing enables real-time target recognition without ground station relay, opening tactical edge applications.
- Commercial Space Data Integration:Low-earth orbit satellite constellations offer complementary persistence layers, creating hybrid airborne-space architectures for time-critical targeting.
Industry Challenges
- Embedded Software Security Certification:Airworthiness authorities demand formal verification for autonomous decision algorithms, extending development timelines for intelligent payload systems.
- Legacy Platform Sensor Retrofit Complexity:Analog-era airframes require digital backbone reconstruction to host modern open-architecture payloads, straining depot maintenance capacity.
- Signals Intelligence Specialist Scarcity:Electromagnetic spectrum warfare expertise concentrates in national intelligence agencies, limiting contractor access to cleared personnel for classified payload development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne ISR Market |
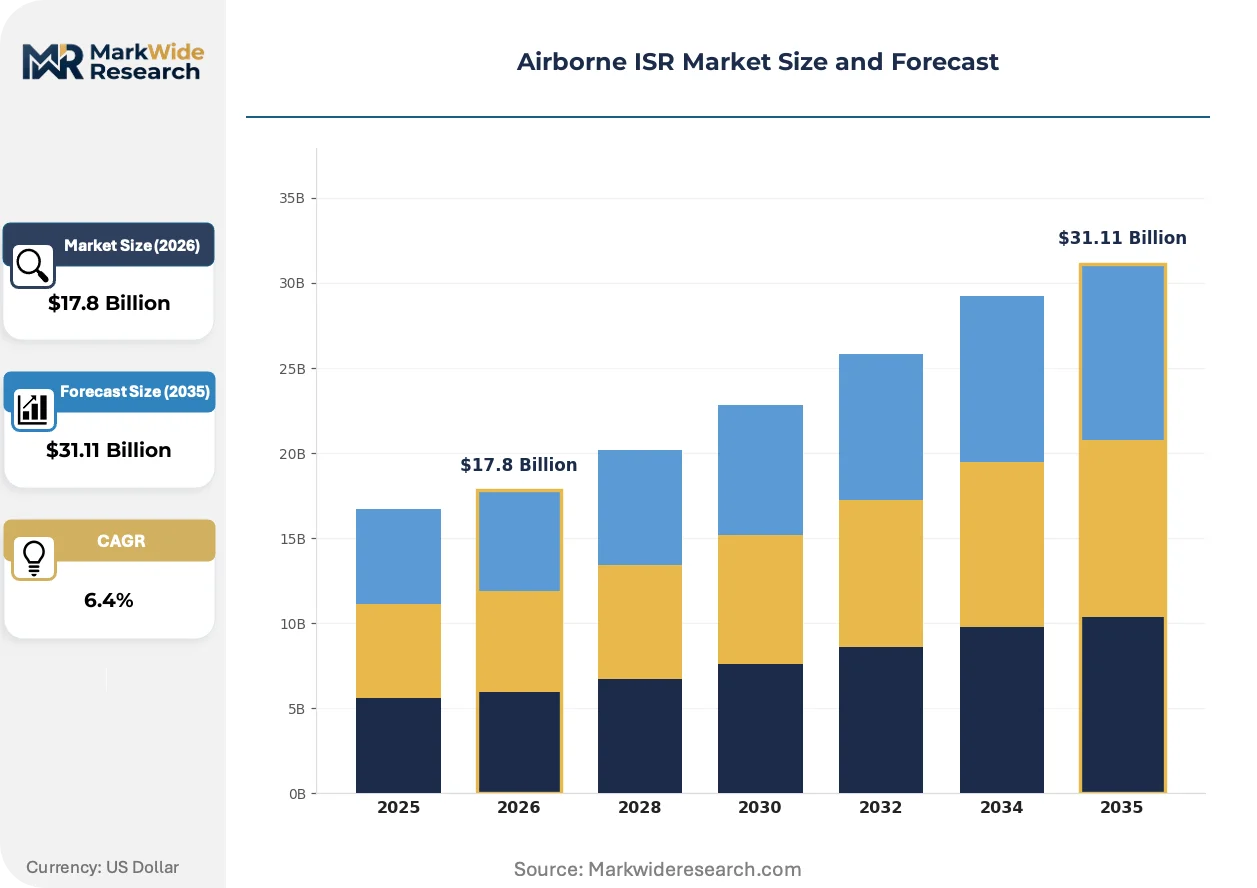
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Fixed-Wing Aircraft, Rotary-Wing Aircraft, Drones, Balloons Technology: Electro-Optical Sensors, Synthetic Aperture Radar, Comms Relay, Signals Intelligence End User: Defense, Homeland Security, Government Agencies, Private Sector Application: Surveillance, Reconnaissance, Search & Rescue, Disaster Management |
| Companies Covered | BAE Systems plc, General Dynamics Corporation, Lockheed Martin Corporation, Elbit Systems Ltd, Thales Group, Northrop Grumman Corporation, Raytheon Technologies, Teledyne Technologies, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne ISR Market Strategic Shifts & Innovations
Active electronically scanned array technology is modularizing across platform classes, compressing the historical separation between strategic and tactical radar capabilities while regulatory fragmentation accelerates dual-track certification strategies.
Synthetic Aperture Radar hardware is modularizing through software-defined waveform architectures. Tactical commanders now field reconfigurable sensor pods previously restricted to strategic bomber fleets. This compression of capability tiers is modularizing supplier hierarchies, enabling subsystem specialists to compete against integrated platform primes.
REACH chemical registration requirements in Europe are constraining thermal management fluid formulations for high-altitude sensor cooling systems. Manufacturers reformulate heat transfer compounds to maintain performance under stricter substance restrictions. Long-endurance unmanned segments face the steepest compliance cost escalation, accelerating near-shoring of final assembly to EU member states.
Defense procurement offices now unbundle sensor payload contracts from airframe prime awards, reversing decades of sole-source platform bundling. Tier-2 subsystem vendors establish direct contracting relationships with military program offices, bypassing traditional prime contractor markup structures. This disintermediation is most visible in US Special Operations Command acquisitions, where rapid fielding authorities compress traditional acquisition cycle timelines.
Airborne ISR Market Segmentation
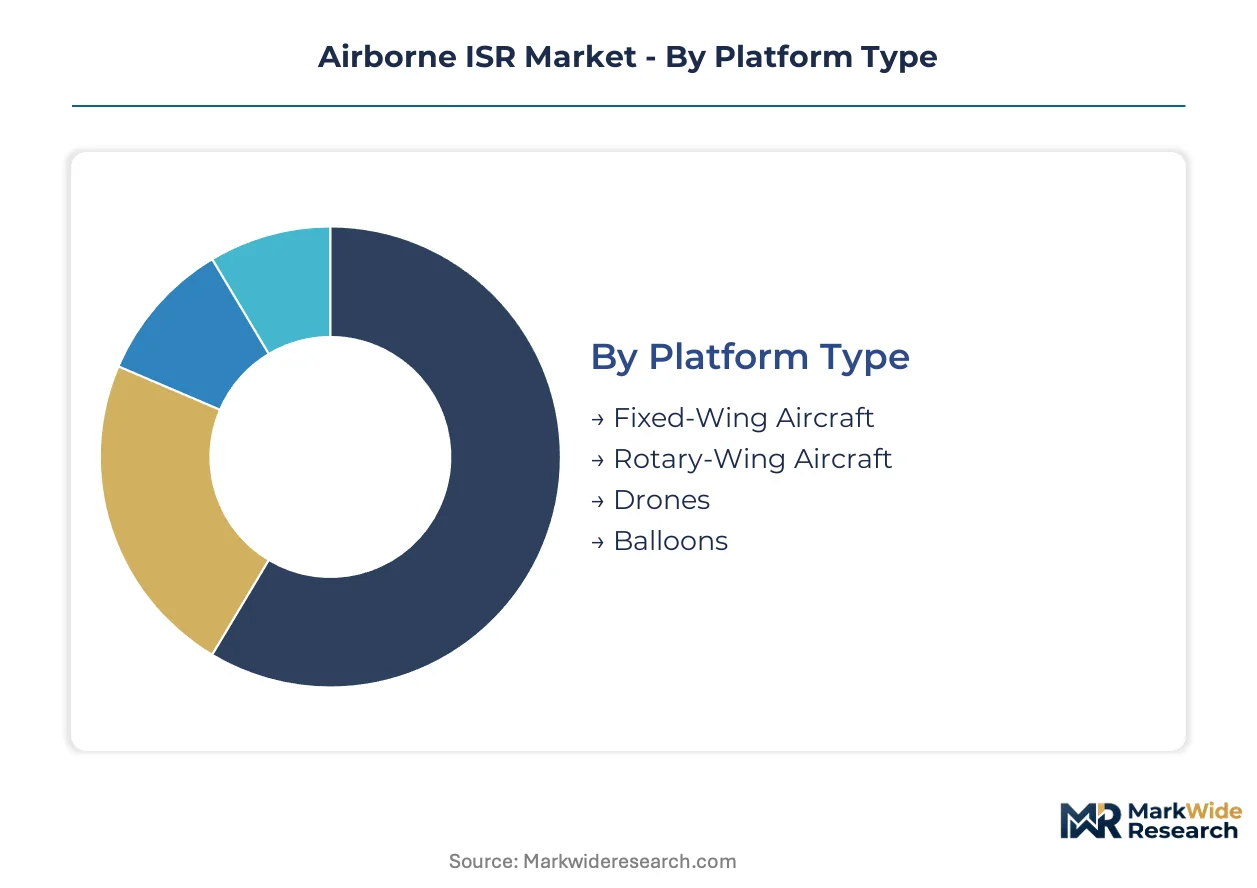
Segmentation in airborne ISR reveals how procurement authority fragments across military services, civilian agencies, and commercial operators, each imposing distinct certification burdens on platform integrators. The divergence in operational tempos—tactical immediacy versus strategic persistence—drives subsystem specialization that resists one-size-fits-all platform economics.
Platform Type:
FAA airworthiness certificates govern manned fixed-wing and rotary-wing platforms, while DoD operational authorities coordinate with the FAA on unmanned system integration; balloons operate under experimental waivers with minimal standardized certification pathways.
- Fixed-Wing Aircraft:High-altitude manned platforms integrate multi-sensor suites on proven airframes requiring full FAA type certification or military equivalent. The Pentagon accounts for dominant procurement volume, though NATO allies sustain parallel fleet modernization programs under STANAG interoperability mandates.
- Drones:Unmanned platforms span tactical hand-launched systems to strategic high-altitude long-endurance assets, with certification bifurcated between civil FAA Part 107 waivers and military airworthiness boards. Attritable systems doctrine redirects demand toward disposable sensor carriers for contested electromagnetic environments.
- Rotary-Wing Aircraft:Vertical takeoff capability enables littoral and mountainous terrain access where fixed-wing runway dependency creates operational vulnerability. Naval aviation services and coast guard organizations concentrate procurement for over-the-horizon targeting and search missions.
- Balloons:Stratospheric platforms operate at extreme altitude with minimal propulsion, carrying lightweight signals intelligence payloads on extended-duration station-keeping profiles. Experimental status limits standardized procurement channels to specialized research and national intelligence applications.
Leading the category by volume: Fixed-Wing Aircraft. Expanding most quickly: Drones.
Technology:
Cost tiers separate strategic-grade sensor investments from tactical payload refresh cycles, with prime contractors defending platform-integrated positions against disintermediating subsystem specialists.
- Synthetic Aperture Radar:Active electronically scanned arrays deliver all-weather, day-night imaging independent of ambient illumination or weather conditions. Gallium nitride component supply concentration in Chinese refining operations exposes prime contractors to export restriction vulnerabilities in high-performance radar production.
- Electro-Optical Sensors:Infrared focal plane arrays and multi-spectral imagers provide real-time video exploitation for target identification and battle damage assessment. Mature technology faces substitution pressure from hyperspectral systems in next-generation payload competitions.
- Signals Intelligence:Electronic warfare receivers and direction-finding equipment intercept, geolocate, and classify electromagnetic emissions across congested spectrum environments. National intelligence agency personnel clearance requirements limit contractor access to specialized development expertise.
- Comms Relay:Aerial networking nodes extend beyond-line-of-sight connectivity for disaggregated ground forces and maritime units. JADC2 architecture mandates accelerate modular radio integration independent of legacy platform replacement schedules.
Dominating procurement value: Synthetic Aperture Radar. Gaining share fastest: Signals Intelligence.
End User:
Customer type determines funding stability and acquisition cycle velocity, with defense appropriations offering multi-year commitment against civilian agency annual budget volatility.
- Defense:Military services operate the preponderance of airborne ISR assets across tactical through strategic mission profiles. Joint All-Domain Command and Control interoperability directives compel modular payload standards across service-specific fleets.
- Homeland Security:Border surveillance and maritime domain awareness missions sustain dedicated rotary-wing and unmanned patrol operations. Domestic airspace integration friction with FAA authorities compresses operational tempo for training and contingency response.
- Government Agencies:National intelligence and law enforcement organizations operate specialized platforms outside standard military procurement channels. Classified budget lines restrict vendor visibility into requirement evolution and competitive positioning.
- Private Sector:Commercial operators provide contracted aerial survey, infrastructure monitoring, and environmental assessment services. Liability frameworks and insurance costs constrain sensor payload sophistication relative to government-operated equivalents.
Commanding expenditure share: Defense. Emerging fastest: Private Sector.
Application:
Maturity gradients separate established surveillance mission profiles from expanding disaster response and humanitarian assistance roles that leverage common sensor infrastructure.
- Surveillance:Persistent area monitoring for border security, maritime patrol, and counter-terrorism operations constitutes the foundational ISR mission set. Platform endurance and sensor resolution specifications drive procurement prioritization across military and civilian operators.
- Reconnaissance:Time-sensitive targeting and deep-strike support missions demand rapid sensor tasking against mobile or concealed objectives. Real-time data link integration with strike platforms compresses sensor-to-shooter timelines below historical ground station relay dependencies.
- Search & Rescue:Distressed personnel location and extraction coordination leverages thermal imaging and signals detection in challenging terrain and weather conditions. Coast guard and alpine rescue services concentrate specialized rotary-wing platform procurement.
- Disaster Management:Post-event infrastructure assessment and displaced population tracking deploy rapidly repositionable aerial assets. International humanitarian organizations increasingly contract commercial drone operators for rapid damage survey deployment.
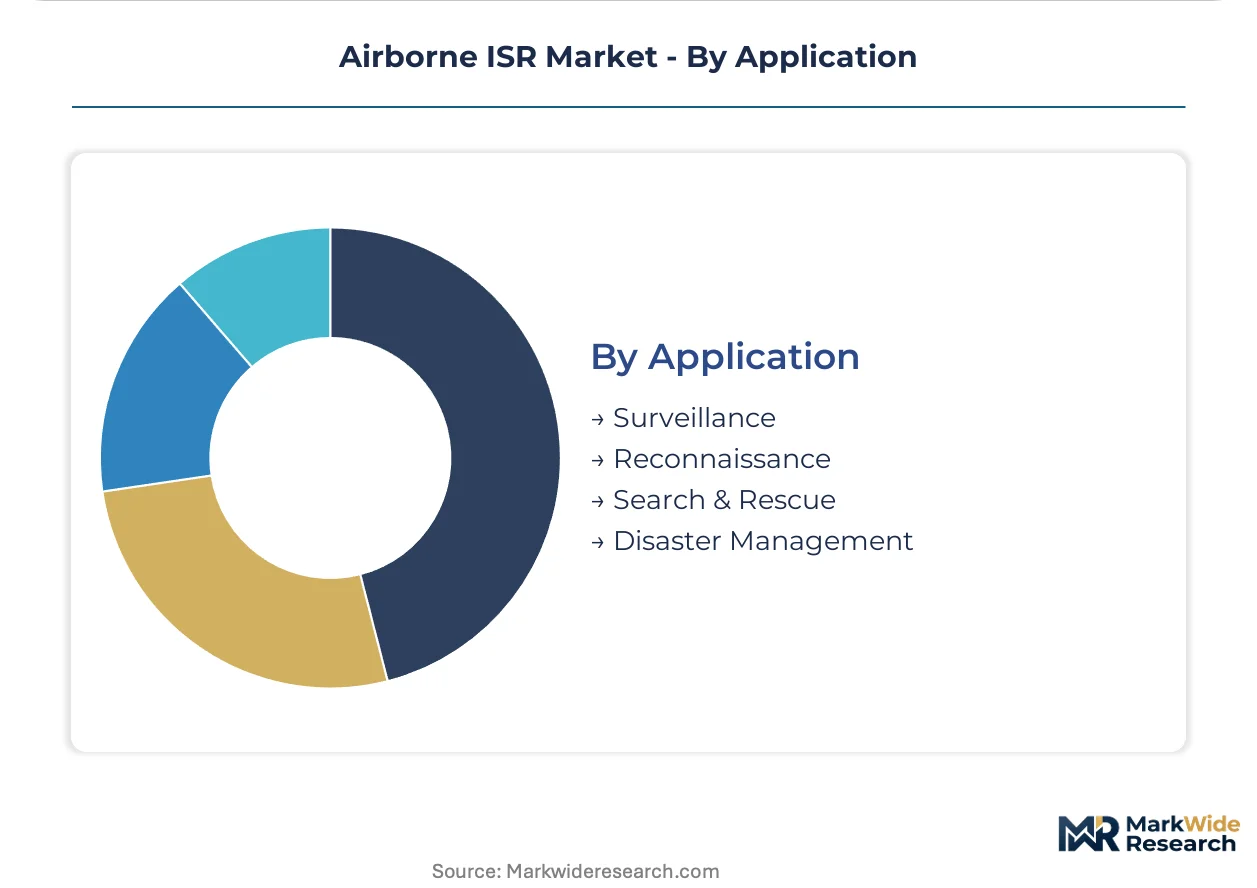
Highest mission volume: Surveillance. Steepest expansion trajectory: Disaster Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in the United States concentrate prime contractor headquarters and flight-test corridors. Special economic incentives for aerospace manufacturing in multiple jurisdictions sustain platform assembly and sensor integration clusters.
United States
The Pentagon's JADC2 architecture mandates drive open-systems procurement across Air Force, Navy, and Army aviation programs. FAA coordination with DoD operational authorities shapes unmanned system airspace integration protocols. California's aerospace corridor hosts rapid prototyping facilities for next-generation ISR payloads, while Texas sustains depot-level maintenance networks for legacy platform sensor retrofits.
United Kingdom
RAF ISTAR modernization programs sustain demand for multi-sensor integration on proven airframes. Ministry of Defence procurement through the Defence Equipment and Support organization imposes UK-specific certification requirements on NATO-standard platforms. BAE Systems plc anchors the Warton-Samlesbury aerospace cluster, where unmanned systems development intersects with European fighter program supply chains.
Germany
Luftwaffe fleet renewal prioritizes signals intelligence and electronic warfare capabilities for contested electromagnetic environments. Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support manages complex multinational procurement frameworks. Bavaria's defense industrial base concentrates sensor subsystem specialists serving both domestic programs and NATO collaborative initiatives.
Israel
Israel Defense Forces operational tempo drives continuous iteration in unmanned platform and payload miniaturization. Ministry of Defense Directorate of Defense Research and Development channels procurement toward dual-use technologies with export potential. Tel Aviv metropolitan engineering clusters specialize in electro-optical and radar subsystem integration for tactical drone applications.
France
DGA procurement sustains sovereign capability in high-altitude long-endurance platforms and signals intelligence architectures. Direction Générale de l'Armement certification requirements shape European interoperability standards alongside NATO STANAG protocols. Toulouse aerospace engineering networks support both military ISR programs and adjacent civil unmanned system development.
Airborne ISR Market Key Industry Players
United States primes anchor the integrated platform tier; European specialists hold subsystem and certification expertise. Market structure concentrates around five to seven major defense contractors with established military airworthiness qualifications, while tier-2 sensor vendors disintermediate traditional prime bundling through direct program office relationships. Strategic archetypes include full-spectrum platform integrators, sensor payload specialists, and rapid-prototyping defense innovation units. Competitive moves center on open-architecture consortium formation and accelerated foreign military sales channel development.
Within the integrated platform tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions exemplifying contrasting specialization vectors—manned strategic assets versus unmanned high-altitude persistence. BAE Systems plc represents the European NATO interoperability anchor, navigating divergent national certification requirements across member air forces. These three entities collectively illustrate how geographic origin and program heritage shape competitive positioning under transnational procurement frameworks.
| Leading Market Players |
|---|
| BAE Systems plc |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| Elbit Systems Ltd |
| Thales Group |
| Northrop Grumman Corporation |
| Raytheon Technologies |
| Teledyne Technologies |
| The Boeing Company |
| Others |
Cost & Logistics Intelligence
The Pentagon's JADC2 mandate for open-architecture interoperability is compelling prime contractors to unbundle sensor payloads from airframe awards, fragmenting traditional sole-source pricing power and forcing subsystem specialists to compete on modular refresh cycles rather than platform replacement timelines.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as military program offices accelerate fielding schedules under rapid acquisition authorities. Pricing stratifies across strategic-grade SAR systems, standard multi-spectral EO packages, and economy-tier attritable drone sensors. Cost compression in tactical unmanned segments intensifies as disposable platform doctrine redirects procurement toward lowest-unit-cost alternatives. Defense ministries exhibit lowest price sensitivity for strategic high-altitude persistence assets, while homeland security agencies face congressional scrutiny on per-unit expenditures.
Supply Chain Analysis
Direct-to-prime channels handle classified payload integration, while tier-2 subsystem vendors increasingly contract directly with program offices. Gallium nitide substrate refining concentrates in China, with secondary sourcing from Japan and the United States. Advanced radar components, infrared focal plane arrays, and flight-certified computing modules anchor bill-of-materials exposure. Single-source vulnerability in Chinese rare earth processing creates tariff and export restriction risk. Distribution runs through defense primes for integrated platforms and specialized distributors for commercial-off-the-shelf subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airborne ISR market is becoming a vertical-integration race as contractors pursue captive control over gallium nitride component supply and AI-enabled sensor fusion software stacks to defend margin positions against disintermediating subsystem specialists.
For Market Incumbents: Hedge against prime-contractor disintermediation by acquiring tier-2 sensor specialists with FAA military airworthiness qualifications. Lock in gallium nitride supply through long-term offtake agreements with Japanese and domestic substrate refiners to offset Chinese concentration risk. Prioritize embedded software security certification investments to extend development timelines that protect incumbent positions. For New Entrants and Emerging Players: Enter via the European Defence Fund parallel certification pathway, where EU industrial strategy fragments traditional national procurement monopolies in France, Germany, and Italy. Target signals intelligence payload development for Luftwaffe electronic warfare modernization, leveraging Bavaria's sensor subsystem cluster. Pursue direct contracting relationships with US Special Operations Command rapid fielding authorities. For Investors and Strategic Acquirers: The window for entry favors tier-2 subsystem specialists with open-architecture software stacks and existing military airworthiness qualifications. Long-term viability hinges on positioning for JADC2-compliant modular refresh cycles independent of airframe replacement. Monitor FAA-DoD unmanned airspace integration agreements as inflection indicator for domestic training mission tempo expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Substrate Supply | Captive sourcing from Japanese refiners mitigates Chinese export restriction exposure for SAR production. |
| Open-Architecture Payload Certification | FAA military airworthiness qualifications enable direct program office contracting bypassing prime markup. |
| AI-Enabled Sensor Fusion Development | Machine learning convergence with SIGINT processing opens tactical edge applications without ground relay. |
| European Defence Fund Qualification | Parallel EU certification pathways fragment French, German, and Italian national procurement monopolies. |
| Attritable Platform Manufacturing Scale-Up | Disposable drone production for contested environments redirects procurement from manned asset risk. |
Research Approach
Independent corroboration across platform program managers, sensor subsystem engineers, and defense procurement officers underwrites the qualitative findings in this study. Primary fieldwork incorporated structured interviews with military airworthiness board representatives, tier-1 prime contractor business development leads, and tier-2 payload specialist technical directors. Secondary validation drew from DoD budget justification documents, FAA unmanned system integration notices, NATO STANAG publication archives, and EU Defence Fund program announcements. Bottom-up segment sizing triangulated against top-down defense appropriation trend analysis.
Rate-of-change decomposition across platform replacement cycles, payload refresh timelines, and regulatory harmonization phases shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include platform type, sensor technology tier, end-user funding stability, and mission application maturity. CAGRs derived from defense budget trajectory correlation with historical procurement cycle elasticity. Industry-specific forecast inputs encompass JADC2 implementation velocity and FAA-DoD airspace coordination progress.
Revisions become necessary when gallium nitride export restrictions intensify, JADC2 interoperability mandates accelerate, or European Defence Fund certification pathways diverge from NATO STANAG standards. Forecasts reflect documented assumptions regarding defense appropriation continuity and allied fleet modernization commitment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
C5ISR Market
ISR
NATO C4ISR Market
ISR
Low Altitude Radar Market
ISR
Air Based C4ISR Market
ISR
United States C4ISR Market
ISR
C6ISR Market
ISR
North America C5ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Eastern Europe C4ISR Market
ISR
North America Airborne ISR Market
ISR
Australia C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Japan C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
Brazil C4ISR Market