
 North America C5ISR Market | 2026-2036
North America C5ISR Market Size, Share, and Industry Trends Forecast 2026-2036
North America C5ISR Market Insights
The United States is tilting toward multi-domain integration architectures that fuse air, land, sea, space, and cyber operations into unified command layers. Lockheed Martin leverages its satellite communications heritage to anchor classified space-ground relay programs. Northrop Grumman sustains long-range radar and electronic warfare portfolios through sustained R&D commitments. L3Harris Technologies specializes in tactical radio networks that bridge legacy and next-generation waveforms.
C5ISR denotes the integrated framework of command, control, communications, computers, cyber, intelligence, surveillance, and reconnaissance systems engineered to operate across contested electromagnetic environments with sub-second latency thresholds and hardened encryption protocols. Its primary purpose is to compress the sensor-to-shooter timeline while maintaining decision superiority against peer adversaries. Communication Systems and Cybersecurity segments attract disproportionate investment as military networks confront sophisticated electronic attack and software-defined threat vectors. Intelligence Gathering applications command premium pricing due to specialized personnel requirements and clearance-constrained delivery channels. The Maintenance service category generates recurring revenue streams that offset cyclical procurement volatility in hardware platforms.
The U.S. Department of Defense, Defense Counterintelligence and Security Agency, and Canadian Department of National Defence shape procurement through security clearance mandates, ITAR export controls, and cross-border information-sharing agreements that restrict vendor eligibility and system architecture choices. NIST cybersecurity frameworks and CMMC certification tiers increasingly gate contract access for subsystem suppliers. Stakeholders must weigh the capital intensity of cleared facility expansion against the strategic necessity of participating in classified program ecosystems.
Market Dynamics
The Joint All-Domain Command and Control initiative is forcing prime contractors to re-architect proprietary systems into interoperable, open-standards platforms that can fuse sensor data across air, land, sea, space, and cyber domains in sub-second cycles.
Growth Catalysts
- CMMC certification mandates:The U.S. Department of Defense's Cybersecurity Maturity Model Certification tiers are creating a gated supply chain that rewards early-compliant subsystem vendors with sole-source eligibility on classified programs.
- Electronic warfare modernization:Peer adversary signal sophistication in the Pacific theater is accelerating procurement of software-defined radio and cognitive jamming payloads for tactical aircraft and naval platforms.
- Southwestern test range clustering:Concentrated aerospace validation infrastructure across New Mexico, Arizona, and southern California is compressing development timelines for next-generation space-ground relay architectures.
Market Restraints
- ITAR-controlled component scarcity:Export-controlled microelectronics and radiation-hardened semiconductors face single-source domestic fabrication constraints that extend lead times for satellite payload integration.
- Cleared facility capital intensity:SCIF construction and personnel security clearance backlogs impose fixed-cost barriers that exclude mid-tier suppliers from classified program participation.
- Legacy waveform interoperability:Decades-old tactical radio protocols in Army and Marine Corps inventories create technical debt that slows unified network fielding.
Strategic Opportunities
- Canadian Arctic surveillance gaps:NORAD modernization funding is opening procurement channels for over-the-horizon radar and polar-orbiting sensor constellations to monitor northern approaches.
- AI-enabled predictive maintenance:Machine learning algorithms applied to aircraft and shipboard C5ISR systems are creating performance-based logistics contracts that replace transactional spare-part sales.
- Commercial space integration:Low Earth orbit satellite megaconstellations are converging with military terminals to provide resilient backup communications during contested space operations.
Industry Challenges
- Polygraph and clearance pipeline constraints:Counterintelligence screening backlogs at the Defense Counterintelligence and Security Agency are stretching program staffing timelines for specialized signals intelligence engineers.
- System-of-systems integration complexity:Vendor-agnostic middleware development for JADC2 architectures demands software engineering capabilities that legacy hardware primes are acquiring through painful capability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America C5ISR Market |
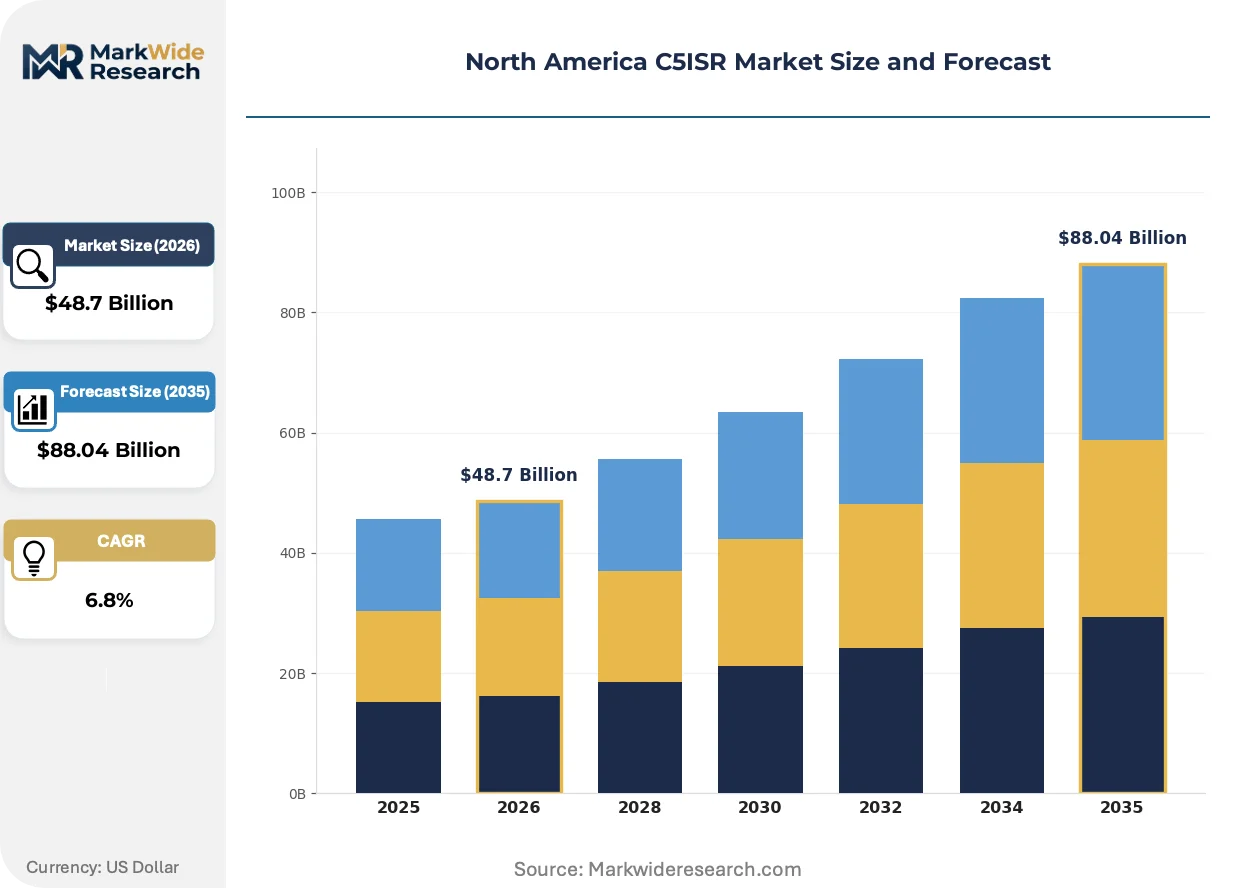
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Communication Systems, Satellite, Cybersecurity Application: Military Operations, Intelligence Gathering, Surveillance, Reconnaissance End User: Defense Agencies, Government Bodies, Security Forces, Contractors Service Type: Maintenance, Support, Training, Integration |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, L3Harris Technologies Inc., BAE Systems, Thales Group, CACI International Inc., Leidos, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America C5ISR Market Trends and Innovations
Software-defined architectures are displacing hardware-fixed systems across every layer of the C5ISR stack, compressing upgrade cycles from years to months and enabling rapid reconfiguration against evolving electronic threats.
Multi-static radar networks are migrating from experimental testbeds to operational deployment across the U.S. Air Force's Advanced Battle Management System. These distributed sensor webs trade single-platform vulnerability for collective detection resilience against stealth and jamming. Prime integrators are recompeting subsystem contracts around open mission systems standards that force interoperability.
CMMC 2.0 implementation timelines issued by the U.S. Department of Defense are mandating third-party cybersecurity audits for every subcontractor handling controlled unclassified information. The regulation is fragmenting the supplier base into cleared and non-cleared tiers, with architecture decisions increasingly driven by security eligibility rather than technical merit alone. Small satellite component vendors in Colorado and California are absorbing compliance costs to maintain access.
Defense agencies are consolidating previously stovepiped program offices into integrated product teams that manage end-to-end sensor-to-shooter chains rather than discrete platforms. This structural reorganization is compressing vendor engagement models from transactional equipment sales to multi-year system-of-systems performance contracts. The U.S. Army's Futures Command exemplifies this shift in Austin and Boston innovation hubs.
North America C5ISR Market Segmentation
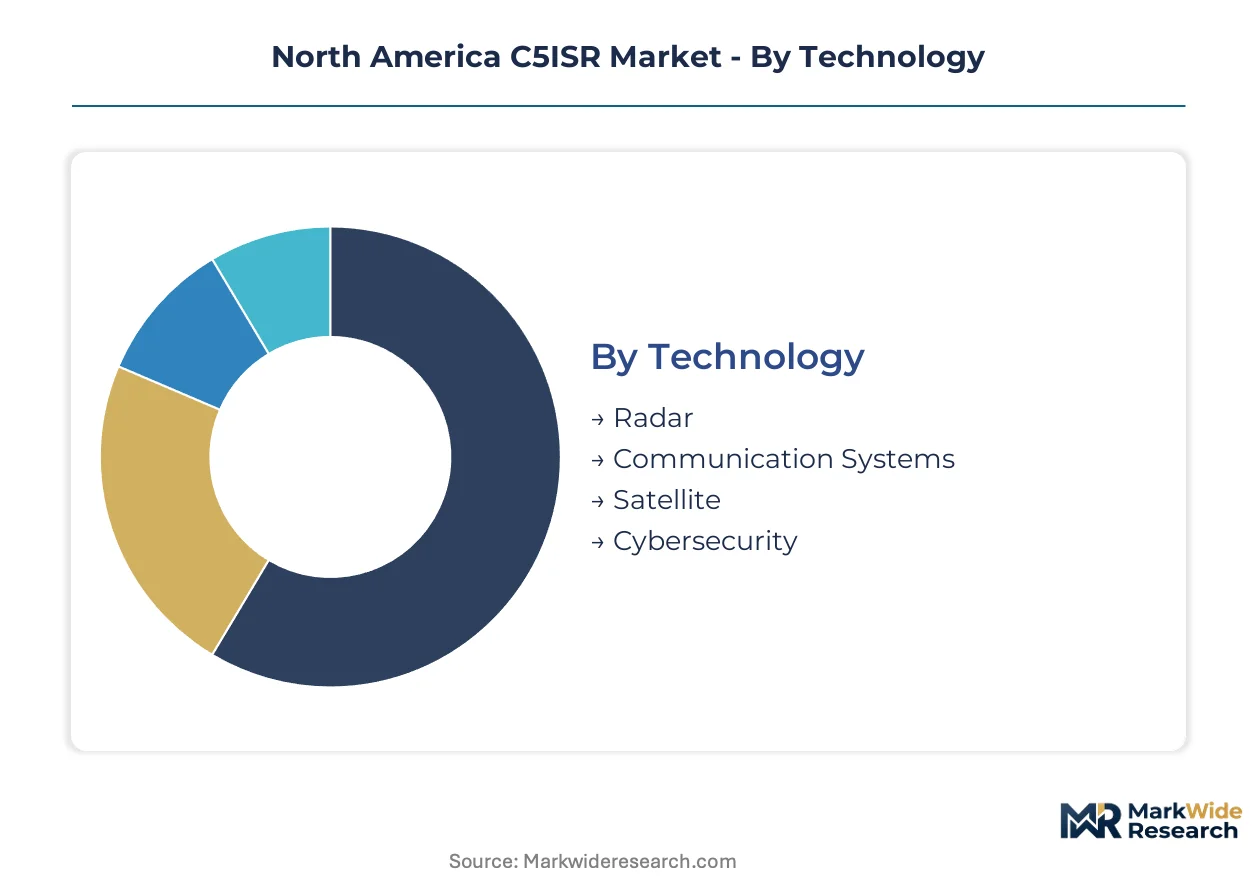
Segmentation of the North America C5ISR market reveals how procurement priorities diverge across technology readiness, operational urgency, and contractual complexity. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor positioning across the United States and Canada.
Technology:
After-sales-service intensity varies sharply across technology layers, with software-defined systems demanding continuous firmware patching and hardware platforms requiring depot-level overhaul cycles.
- Communication Systems:Tactical radio networks bridge legacy waveforms with next-generation software-defined architectures. Pentagon procurement concentrates in the southwestern United States test corridor, where New Mexico and Arizona facilities validate multi-band interoperability against electronic attack scenarios.
- Cybersecurity:Encryption modules and zero-trust network architectures harden command nodes against software-defined threats. CMMC certification mandates from the U.S. Department of Defense are gating contract access for subsystem vendors handling controlled unclassified information.
- Radar:Active electronically scanned arrays and multi-static sensor webs support long-range air and missile defense.
- Satellite:Space-ground relay payloads and resilient constellations address contested orbital environments.
By volume, Communication Systems leads procurement tallies. By growth pace, Cybersecurity is climbing the fastest as CMMC tiers harden supply chain eligibility.
Application:
Cost tier stratification separates premium-priced intelligence contracts from standardized surveillance platforms, with clearance-constrained delivery channels commanding substantial pricing premiums.
- Intelligence Gathering:Signals intelligence and human intelligence fusion platforms require specialized personnel with active security clearances. Delivery channels concentrate around Washington D.C. and Fort Meade corridors, where clearance backlogs at the Defense Counterintelligence and Security Agency stretch staffing timelines.
- Military Operations:Command-and-control systems compress sensor-to-shooter timelines across joint force structures. Joint All-Domain Command and Control requirements are forcing re-architecture of proprietary platforms into interoperable open-standards systems.
- Reconnaissance:Long-range unmanned platforms and penetrating sensor systems collect targeting data in denied airspace.
- Surveillance:Persistent wide-area motion imagery and border monitoring systems support homeland defense missions.
By contract value, Intelligence Gathering dominates. By expansion trajectory, Military Operations is gaining share fastest as JADC2 integration accelerates.
End User:
Customer type determines procurement rhythm, with defense agencies driving multi-year program-of-record cycles and contractors absorbing compliance costs for classified facility access.
- Defense Agencies:The U.S. Department of Defense and Canadian Department of National Defence anchor procurement through security clearance mandates and ITAR export controls. Cross-border information-sharing agreements under NORAD modernization restrict vendor eligibility and system architecture choices.
- Contractors:Prime integrators and subsystem suppliers compete for sole-source eligibility on classified programs. SCIF construction and personnel clearance pipelines impose fixed-cost barriers that fragment the supplier base into cleared and non-cleared tiers.
- Government Bodies:Homeland security and federal law enforcement agencies procure interoperable systems for domestic threat response.
- Security Forces:State and provincial-level organizations acquire tactical communications for emergency management.
By program scale, Defense Agencies lead. By contract velocity, Contractors are expanding most quickly as performance-based logistics models displace transactional hardware sales.
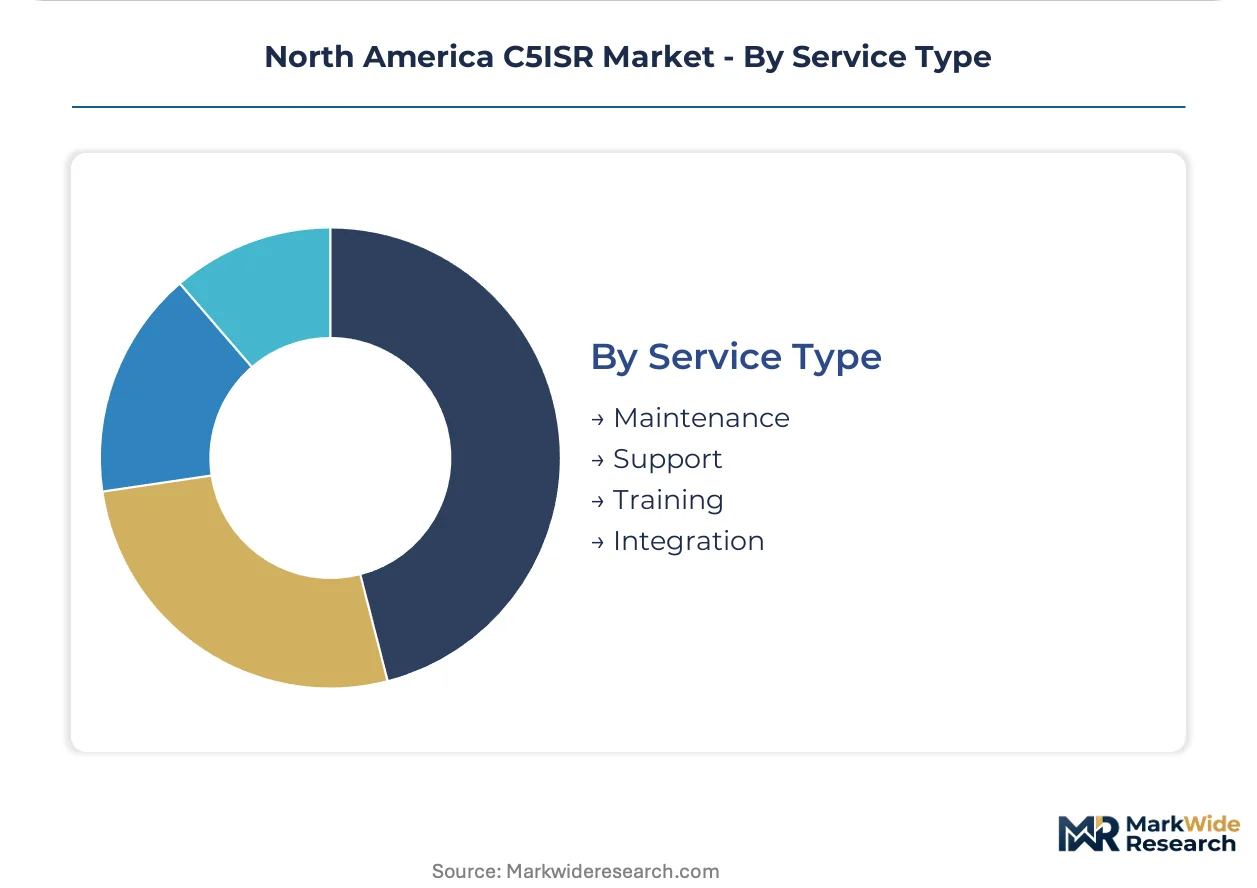
Service Type:
Margin profiles favor recurring revenue streams that offset cyclical procurement volatility, with integration services capturing upfront value and maintenance contracts extending program lifecycles.
- Maintenance:Performance-based logistics contracts apply AI-enabled predictive algorithms to aircraft and shipboard C5ISR systems. The U.S. Army's Futures Command in Austin exemplifies the shift from spare-part sales to outcome-based sustainment models.
- Integration:System-of-systems middleware development for JADC2 architectures demands software engineering capabilities that legacy hardware primes are acquiring through targeted capability investments.
- Support:Field service representatives and depot-level engineering sustain operational readiness across distributed force structures.
- Training:Simulation-based instruction and live-range certification prepare operators for contested electromagnetic environments.
By revenue stability, Maintenance leads. By growth pace, Integration is climbing the fastest as open mission systems standards force vendor-agnostic architecture decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The White Sands Missile Range and adjacent aerospace corridors anchor southwestern validation infrastructure that compresses development timelines for space-ground relay architectures across the continent.
United States
The Joint All-Domain Command and Control initiative and CMMC certification mandates drive procurement concentration in defense agencies. The U.S. Department of Defense gates contract access through tiered cybersecurity audits for controlled unclassified information handlers. New Mexico and Arizona host concentrated test facilities where multi-band tactical radio interoperability undergoes electronic attack validation.
Canada
NORAD modernization funding targets Arctic surveillance gaps with over-the-horizon radar and polar-orbiting sensor constellations. The Canadian Department of National Defence coordinates cross-border information-sharing agreements that restrict vendor eligibility for northern approach monitoring systems. Ottawa and the Prairie Provinces anchor procurement offices managing classified facility access for prime integrators.
Mexico
Border security and homeland defense missions generate demand for persistent wide-area surveillance and interoperable tactical communications. The Secretariat of National Defense procures systems compatible with U.S. Joint All-Domain architectures under bilateral security frameworks. Northern border states concentrate installation and field service operations for cross-border threat response coordination.
North America C5ISR Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radiation-hardened semiconductors and encryption modules. The vendor base stratifies into cleared primes with SCIF access and mid-tier suppliers facing capital barriers to classified program participation. Two archetypes dominate: legacy hardware primes acquiring software engineering capabilities and satellite communications heritage holders anchoring space-ground relay programs. Competitive moves center on open mission systems standard adoption and performance-based logistics contract conversion.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform-scale positioning, while L3Harris Technologies Inc. occupies a specialist role bridging legacy and next-generation waveform architectures. These entities represent the cleared-facility tier where security eligibility gates contract access more tightly than technical differentiation alone.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| L3Harris Technologies Inc. |
| BAE Systems |
| Thales Group |
| CACI International Inc. |
| Leidos |
| Others |
Pricing and Supply Chain Analysis
ITAR-controlled microelectronics scarcity determines both pricing tier spreads and supply chain shape across North American C5ISR procurement. Single-source domestic fabrication constraints for radiation-hardened semiconductors compress margins at the subsystem tier while amplifying pricing power for cleared prime integrators with captive foundry relationships.
Pricing Analysis
Volume-discount tiering structures separate sole-source classified programs from competitive unclassified procurement. Pricing stratifies across premium, standard, and economy tiers based on CMMC certification level and security clearance depth. Cost compression in the mid-tier subsystem vendor base is intensifying because SCIF construction and personnel clearance backlogs impose fixed-cost barriers that exclude price-competitive challengers. Defense agencies demonstrate lowest price sensitivity on intelligence gathering contracts requiring active clearance-constrained delivery channels, while standardized tactical radio platforms face acute price pressure from open mission systems standard mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from prime integrators tether component vendors to program-of-record cycles. Geographic supply concentration centers on the United States for radiation-hardened semiconductors and encryption modules, with secondary sourcing from Canada for polar-orbiting sensor subsystems and limited Mexican integration for field service logistics. Raw material dependencies include gallium nitride substrates for active electronically scanned arrays, rare earth elements for precision magnetics, and ITAR-controlled microelectronics for satellite payload integration. Single-source vulnerability pervades domestic radiation-hardened foundry capacity. Distribution runs through cleared prime integrators with SCIF access rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
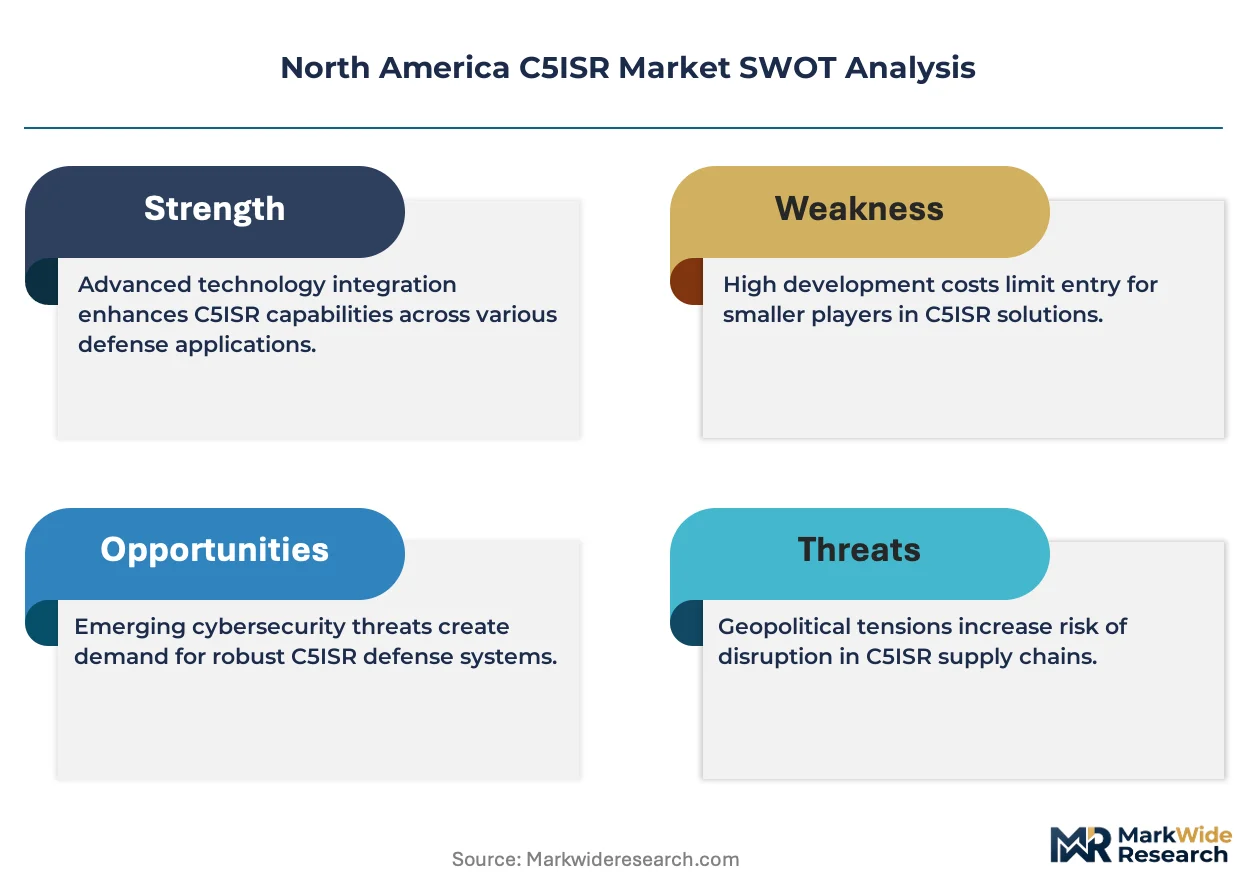
The North America C5ISR market functions as a defensive-moat story where regulatory entrenchment through CMMC certification tiers and security clearance mandates creates structural barriers that protect incumbent positioning against technical disruption.
For Market Incumbents: Harden cleared facility networks against emerging AI-enabled predictive maintenance competitors by accelerating performance-based logistics contract conversion across Army Futures Command programs. Deepen backward integration into radiation-hardened semiconductor fabrication to offset ITAR-controlled component scarcity risks. Prioritize open mission systems standard adoption to capture JADC2 middleware integration value that software-native challengers threaten. For New Entrants and Emerging Players: Establish a beachhead in Canadian Arctic surveillance gaps where NORAD modernization funding creates procurement channels absent entrenched U.S. prime relationships. Target commercial space integration segments where Low Earth orbit megaconstellations converge with military terminals outside traditional cleared supply chains. Pursue AI-enabled predictive maintenance as a go-to-market angle that displaces transactional spare-part incumbents through outcome-based sustainment models. For Investors and Strategic Acquirers: CMMC 2.0 implementation timelines reshape the acquisition landscape by fragmenting the supplier base into cleared and non-cleared tiers with divergent contract eligibility. Long-term viability across the analysis window favors targets with established SCIF infrastructure and active personnel clearance pipelines rather than pure technology plays. Monitor Defense Counterintelligence and Security Agency polygraph processing rates as the critical signal for program staffing timeline compression that would accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Certification Investment | Tiered cybersecurity audits from the U.S. Department of Defense gate sole-source eligibility on classified programs. |
| Open Mission Systems Adoption | Vendor-agnostic middleware standards force interoperability that re-architects proprietary prime platforms. |
| Performance-Based Logistics Conversion | AI-enabled predictive algorithms at Army Futures Command displace transactional spare-part revenue models. |
| Cleared Facility Expansion | SCIF construction in New Mexico and Arizona compresses development timelines for space-ground relay validation. |
| Commercial Space Integration | Low Earth orbit megaconstellations provide resilient backup communications during contested orbital operations. |
Research Methodology
A spread of perspectives from program managers at the U.S. Department of Defense, subsystem procurement leads at prime integrators, security clearance processing officials at the Defense Counterintelligence and Security Agency, and test range operations directors in New Mexico converged on the working assumptions. Secondary validation drew from DoD budget justification materials, CMMC implementation guidance, NORAD modernization funding disclosures, and SEC filings from cleared defense contractors. Bottom-up segment sizing and top-down macro constraint checks were triangulated to establish forecast boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology layer, application mission type, end-user procurement authority, and service delivery model. CAGRs were derived from program-of-record funding trajectories and capability fielding timelines rather than extrapolated trend fitting. Industry-specific forecast inputs incorporated JADC2 architecture deployment schedules and CMMC audit completion rates.
Stress conditions across ITAR export control stringency, security clearance pipeline throughput, and radiation-hardened semiconductor foundry capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about program funding continuity and cross-border information-sharing agreement stability. Macroeconomic contraction, regulatory delay, or adversary electronic warfare capability surprise would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
IFF System Market
ISR
Asia-Pacific C4ISR Market
ISR
C4ISR Market
ISR
Low Altitude Radar Market
ISR
C6ISR Market
ISR
Airborne ISR Market
ISR
Brazil C4ISR Market
ISR
Australia C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
United States C4ISR Market
ISR
Europe C5ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Active Phased Array Radar (APAR) Market
ISR
North America Airborne ISR Market