
 United States C4ISR Market | 2026-2036
United States C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
United States C4ISR Market Analytics
Modular system bundling is consolidating procurement decisions across the United States C4ISR Market as buyers shift from standalone platforms to integrated mission suites. Lockheed Martin leverages its satellite communication heritage to anchor prime contractor positions on multi-billion dollar programs. Northrop Grumman sustains dominance in radar and electronic warfare through sustained R&D investment in distributed aperture systems. L3Harris specializes in tactical radio networks that connect dismounted soldiers to aerial and space layers.
C4ISR denotes the military architecture integrating Command, Control, Communications, Computers, Intelligence, Surveillance, and Reconnaissance into unified operational networks, typically operating across classified and unclassified frequency spectra with encryption standards governed by NSA-approved Type 1 algorithms. Its primary purpose enables real-time decision superiority by fusing sensor data into actionable intelligence for joint force commanders. Satellite Communication represents the most mature revenue pool within the technology dimension, while Cybersecurity captures the fastest expansion as zero-trust architectures displace perimeter-based defenses. The Military end user segment dominates absolute spending, though Defense Contractors absorb growing shares through Other Transaction Authority vehicles that bypass traditional FAR-based procurement.
FAA regulations governing unmanned systems airspace integration, NSA cryptographic certification requirements, and DoD 8140 workforce standards collectively shape product development cycles and vendor qualification barriers. The Department of Defense CMMC framework now mandates cybersecurity maturity levels for all supply chain participants, effectively filtering market access. Stakeholders must monitor how the Space Development Agency's proliferated constellation strategy reallocates sensor investment from exquisite platforms to distributed architectures.
Market Dynamics
The Pentagon's Joint All-Domain Command and Control mandate is forcing prime contractors to abandon stovepiped platforms in favor of open-architecture mission suites that interoperate across air, land, sea, space, and cyber domains.
Growth Catalysts
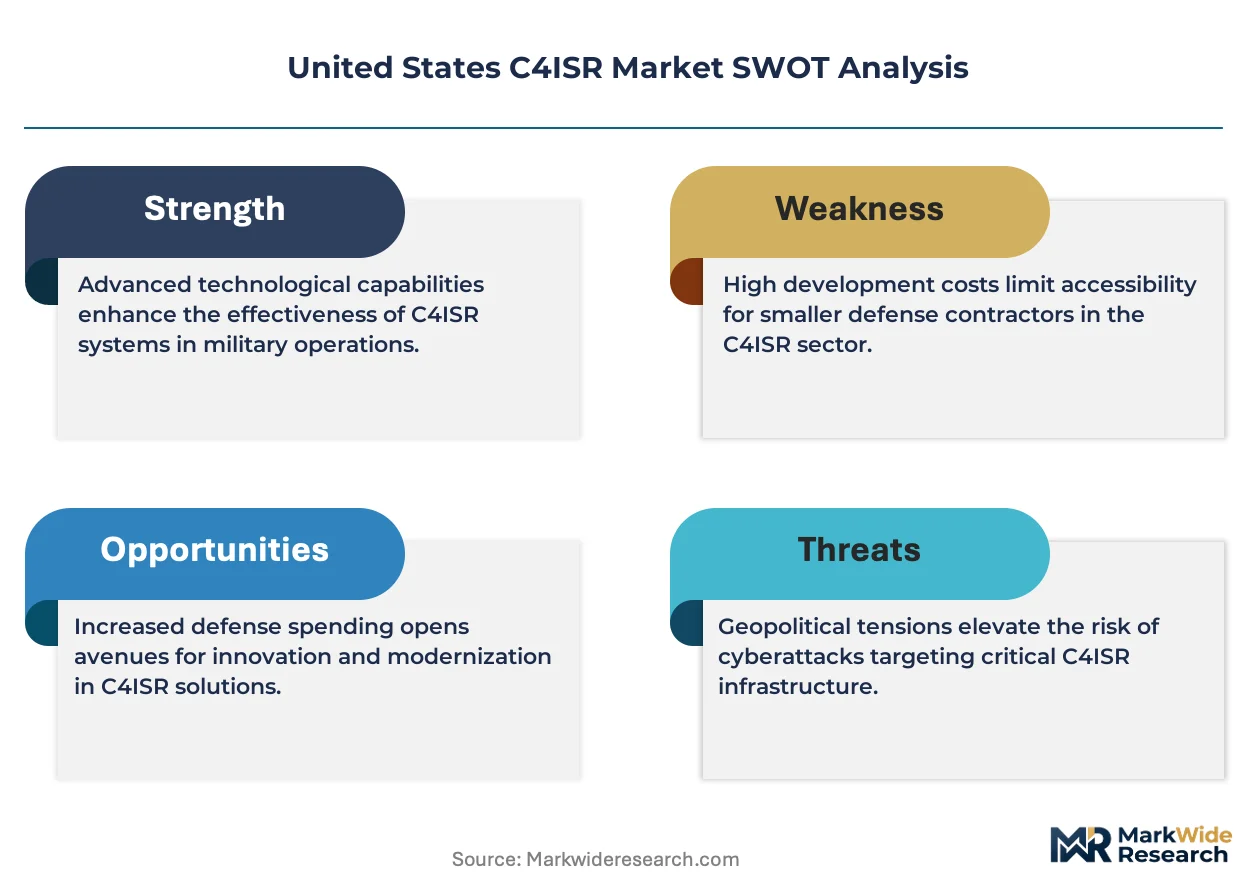
- DoD CMMC framework:Cybersecurity maturity certification requirements now filter subcontractor access, concentrating procurement among qualified vendors capable of meeting Level 2 and 3 standards across the defense industrial base.
- Space Development Agency proliferated constellations:Distributed low-earth orbit sensor networks reduce reliance on exquisite geostationary platforms, opening procurement to non-traditional satellite manufacturers.
- Tactical radio modernization:Army's Integrated Tactical Network program replaces legacy single-band radios with multi-channel software-defined systems connecting dismounted soldiers to aerial layers.
Market Restraints
- Gallium nitride foundry concentration:Domestic production of wide-bandgap semiconductors for radar and electronic warfare remains limited to a single qualified foundry, creating single-source vulnerability for critical transmit-receive modules.
- NSA Type 1 certification timelines:Cryptographic module validation for classified networks averages 18-24 months, compressing product refresh cycles and freezing architecture decisions.
- Legacy system integration debt:Decades of proprietary protocols in fielded command systems resist middleware abstraction, inflating engineering hours for interoperability retrofits.
Strategic Opportunities
- Other Transaction Authority vehicles:Defense contractors bypass FAR-based procurement through rapid prototyping agreements, accelerating technology insertion from Silicon Valley entrants.
- Zero-trust architecture mandates:OMB memoranda requiring microsegmentation and continuous authentication create replacement demand across existing perimeter-based network infrastructure.
- Artificial intelligence and sensor fusion convergence:Edge-deployed machine learning models processing multi-intelligence feeds enable predictive targeting without bandwidth-heavy backhaul to centralized processing nodes.
Industry Challenges
- Cleared workforce scarcity:TS/SCI-cleared software engineers and systems architects remain concentrated in Northern Virginia and Maryland corridors, constraining program scaling outside the National Capital Region.
- Supply chain reconfiguration friction:Section 889 prohibitions on Chinese telecommunications components force redesigns of tactical radio and satellite terminal subsystems mid-production.
- Interoperability certification complexity:Multi-vendor integration testing for JADC2 compliance consumes 30-40% of program schedule before operational assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States C4ISR Market |
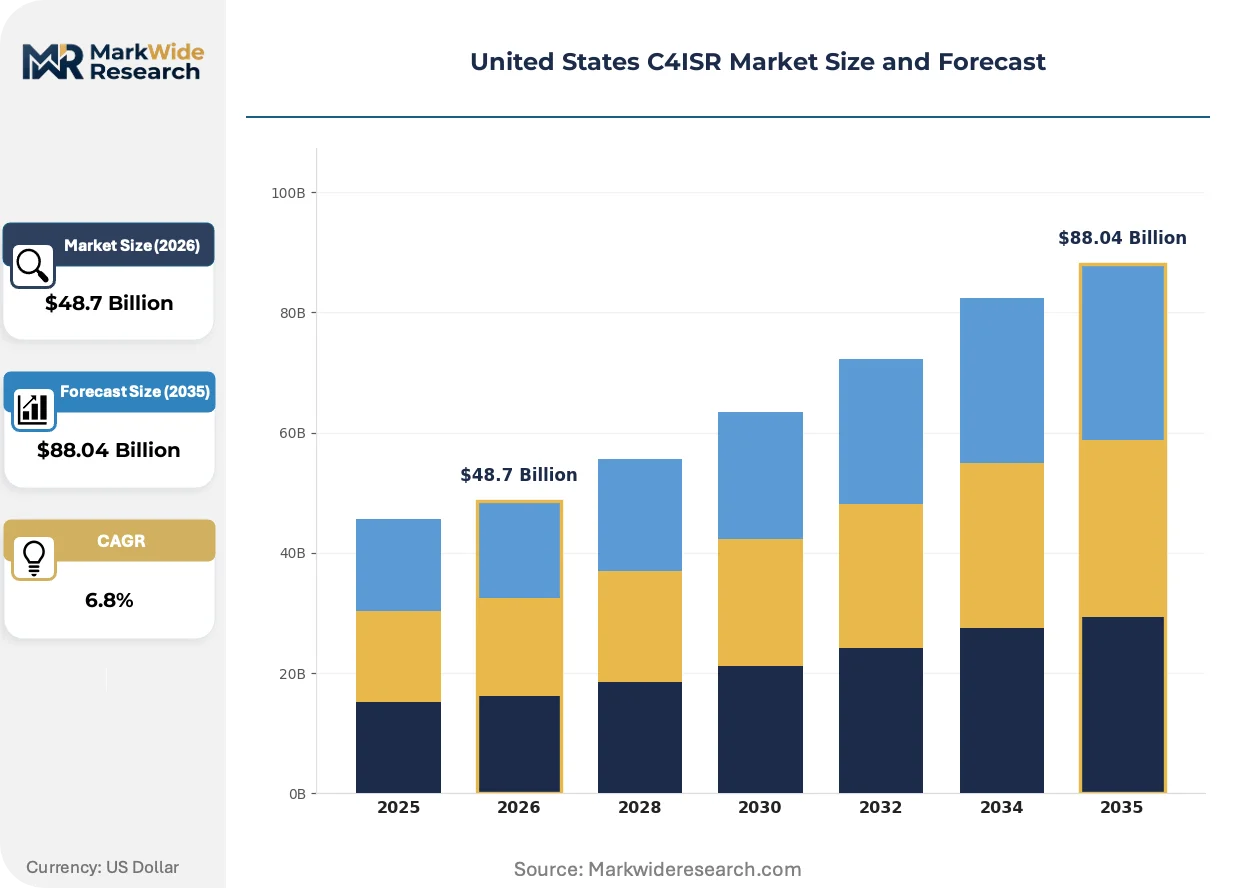
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Satellite Communication, Radar Systems, Sensor Fusion, Cybersecurity End User: Military, Government Agencies, Defense Contractors, First Responders Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solution: Command & Control, Intelligence Gathering, Surveillance Systems, Data Analysis |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Inc., BAE Systems plc, RTX Corporation, General Dynamics Corporation, The Boeing Company, CACI International Inc., Leidos Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States C4ISR Market Evolving Landscape
Software-defined everything is dissolving hardware boundaries in military communications, with programmable radios and virtualized network functions replacing fixed-purpose equipment across tactical formations.
Software-defined radio architectures are unifying previously separate waveform implementations onto common hardware platforms. Army brigade combat teams now field multi-channel radios that switch between SATCOM, MANET, and legacy narrowband modes through firmware updates rather than hardware swaps. This compression of multiple single-purpose boxes into one programmable unit is unifying supplier tiers and reducing logistics tail for forward-deployed units.
FAA regulations governing unmanned systems beyond-visual-line-of-sight operations are tightening integration requirements for ISR platforms. Commercial UAS manufacturers must now certify detect-and-avoid systems and command-link redundancy before military adoption, slowing technology transfer from consumer drone advances. The small tactical UAS segment is responding by segregating domestic and export product lines to isolate certification scope.
Defense buyers are consolidating vendor relationships through enterprise software licensing rather than platform-specific purchases. Major commands now negotiate department-wide seats for mission planning and intelligence analysis tools, displacing point-solution contracts that previously fragmented procurement. This concentration is most visible in Air Force and Navy intelligence communities, where single-vendor cloud contracts for geospatial analytics have replaced stovepiped imagery exploitation workstations.
United States C4ISR Market Segmentation
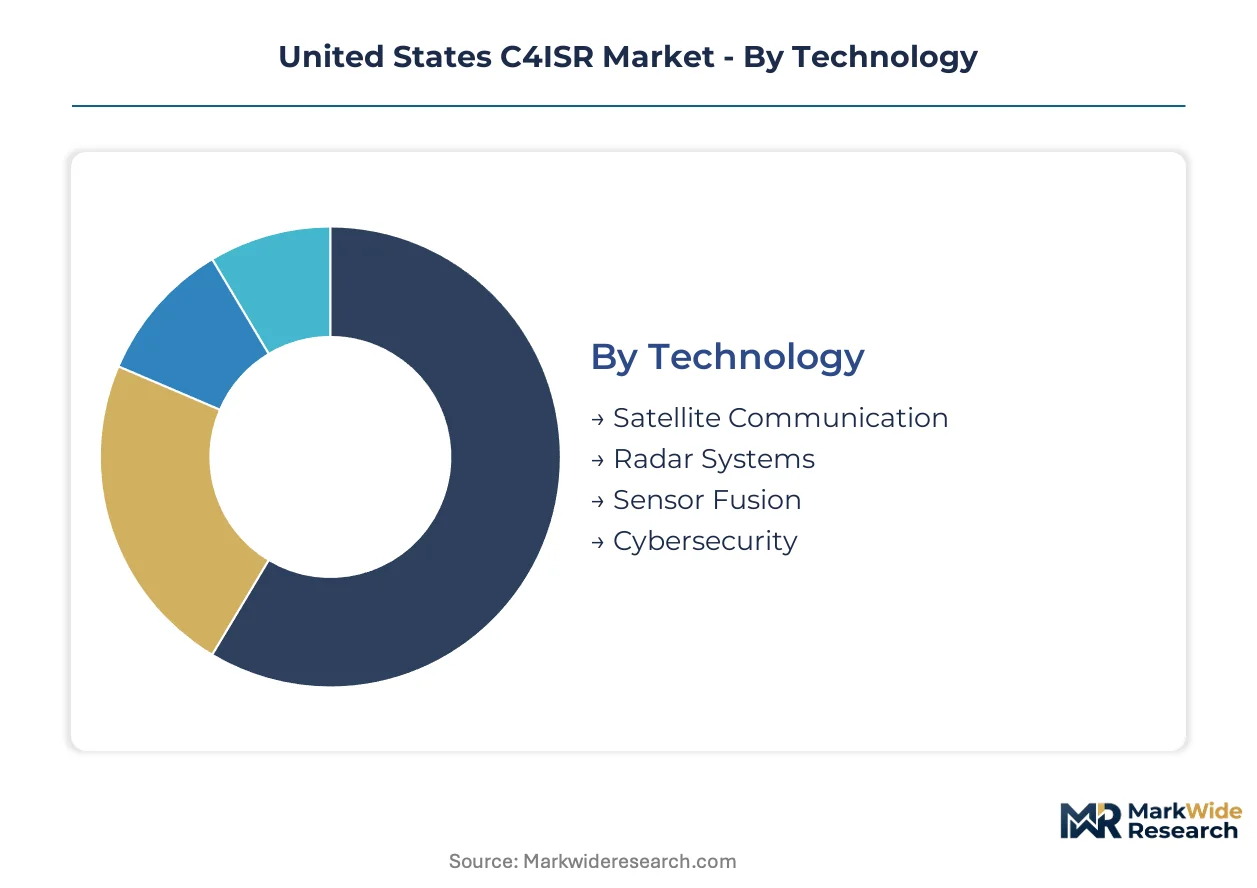
C4ISR procurement patterns diverge sharply between legacy platform upgrades and next-generation network architectures. Understanding these segment boundaries clarifies where defense dollars concentrate versus where new vendor entry remains viable.
Technology:
Satellite Communication commands the largest installed base, while Cybersecurity captures the steepest expansion trajectory as zero-trust mandates displace perimeter defenses.
- Satellite Communication:Mature wideband and protected tactical terminals link ground forces to geostationary and proliferated low-earth orbit constellations. Pentagon spending concentrates on Virginia's defense corridor, driven by Space Development Agency constellation deployment schedules and Army's need for beyond-line-of-sight connectivity in contested environments.
- Cybersecurity:Zero-trust architectures, microsegmentation tools, and continuous authentication systems harden classified networks against insider threats and supply chain compromise. NSA Type 1 certification requirements filter vendor access, concentrating procurement among cleared integrators capable of meeting CMMC Level 3 standards.
- Radar Systems:Active electronically scanned arrays and distributed aperture sensors provide multi-domain target tracking.
- Sensor Fusion:Edge-deployed algorithms integrate electro-optical, signals intelligence, and synthetic aperture radar feeds into unified tracks.
Mature deployment sits with Satellite Communication. Newer deployment is concentrated in Cybersecurity.
End User:
Volume procurement flows through Military commands, though Defense Contractors absorb growing shares via Other Transaction Authority vehicles that accelerate Silicon Valley technology insertion.
- Military:Joint force commands, service component headquarters, and tactical echelons from brigade to squad level consume integrated battle management systems. Army modernization programs in Texas and California drive demand for software-defined radios and command post computing environments.
- Defense Contractors:Prime integrators and subsystem suppliers purchase development environments, test ranges, and security infrastructure for classified program execution. OTAs bypass traditional FAR procurement, enabling rapid prototyping agreements with non-traditional vendors.
- Government Agencies:Intelligence community elements and homeland security departments acquire specialized collection and analysis platforms.
- First Responders:State and local emergency management organizations adopt military-derived situational awareness tools for disaster response.
Established procurement authority rests with Military end users. Emerging flexibility concentrates in Defense Contractors.
Deployment:
On-Premises infrastructure retains dominance for classified processing, while Hybrid architectures gain traction where missions span multiple security enclaves.
- On-Premises:Air-gapped data centers and tactical shelters host Top Secret//SCI workloads with physical isolation from commercial networks. NSA encryption requirements and TEMPEST shielding specifications constrain vendor qualification to cleared facility operators concentrated in Maryland and Northern Virginia.
- Hybrid:Classified enclaves connect to unclassified cloud infrastructure through cross-domain guards and data diode architectures. DISA's milCloud and C2S contracts enable this pattern, with demand concentrating where commands must fuse open-source intelligence with sensitive compartmented information.
- Cloud-Based:Unclassified development, test, and training environments leverage commercial infrastructure.
- Mobile:Vehicle-mounted and dismounted soldier systems extend network access to tactical edge.
Security-certified deployment centers on On-Premises. Architectural innovation clusters in Hybrid.
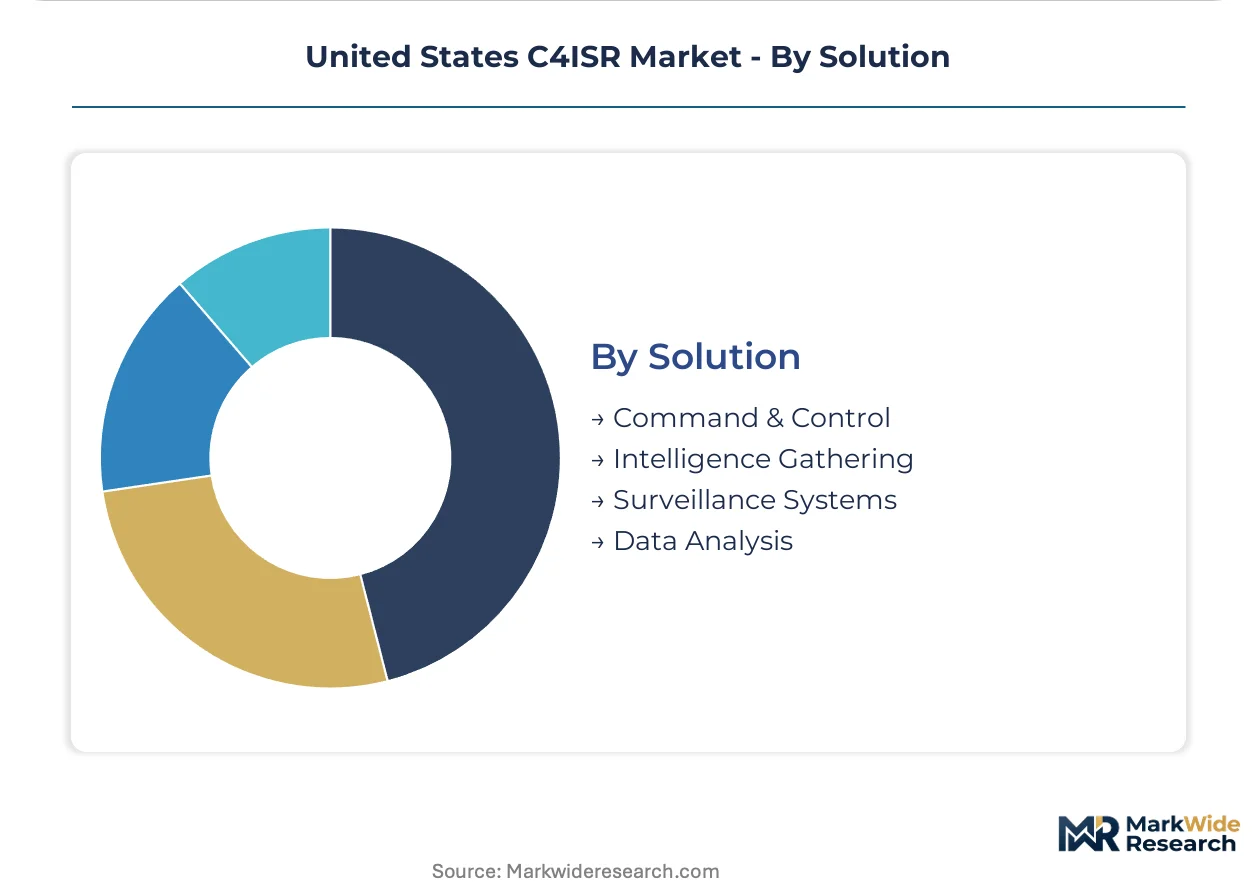
Solution:
Command & Control solutions anchor program budgets, though Data Analysis capabilities expand fastest as artificial intelligence migrates to operational decision support.
- Command & Control:Joint All-Domain Command and Control platforms integrate air, land, sea, space, and cyber situational awareness into unified operational pictures. Air Force and Navy program offices in the Pentagon corridor drive standardization efforts, with Lockheed Martin and Northrop Grumman anchoring prime contractor positions.
- Data Analysis:Machine learning pipelines process multi-intelligence feeds into predictive targeting and anomaly detection. Edge deployment reduces bandwidth requirements for contested logistics, with demand concentrating in Army Futures Command and Special Operations Command technology incubators.
- Intelligence Gathering:Human intelligence, signals intelligence, and geospatial intelligence collection systems.
- Surveillance Systems:Persistent wide-area motion imagery and ground moving target indication platforms.
Program-of-record investment concentrates in Command & Control. Capability experimentation accelerates in Data Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States C4ISR Market concentrates production in defense corridors while consumption distributes across military installations and contractor facilities. Virginia's Pentagon-adjacent cluster generates prime contractor engineering output. California and Texas absorb modernization procurement through Army Futures Command and service laboratories.
Virginia
Defense procurement commands concentrate in Northern Virginia's corridor adjacent to the Pentagon and intelligence agency headquarters. NSA Type 1 certification requirements filter vendor access to cleared facilities in Fairfax and Loudoun counties. Lockheed Martin and Northrop Grumman anchor prime contractor positions on multi-billion dollar JADC2 programs in this cluster.
California
Army Futures Command technology incubators and Space Force acquisition offices drive demand for software-defined radios and proliferated constellation ground systems. FAA regulations governing unmanned systems airspace integration shape product development for ISR platforms tested at Mojave Desert ranges. Palmdale and El Segundo host radar and electronic warfare engineering centers.
Texas
Army modernization programs at Fort Hood and Redstone Arsenal accelerate procurement of integrated battlefield management systems. DoD CMMC framework implementation concentrates cleared subcontractor facilities in Dallas-Fort Worth and Austin corridors. L3Harris maintains tactical radio manufacturing and test capabilities in this region.
Maryland
NSA cryptographic certification timelines and TEMPEST shielding specifications constrain vendor qualification to cleared facility operators concentrated in Fort Meade corridor. Cybersecurity zero-trust architecture mandates generate replacement demand for microsegmentation tools across intelligence community enclaves. Annapolis Junction anchors supply chain participants meeting CMMC Level 3 standards.
Florida
Special Operations Command technology incubators at MacDill Air Force Base drive experimentation in edge-deployed sensor fusion and predictive targeting. DISA milCloud contracts enable hybrid deployment architectures connecting classified enclaves to unclassified infrastructure. Orlando simulation clusters support command post computing environment development.
United States C4ISR Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supplier layers. Prime integrators anchor program-of-record positions through sustained R&D investment and cleared facility infrastructure. Mid-tier subsystem vendors concentrate in specific technology domains. Competitive moves center on open-architecture consortium participation and rapid prototyping agreement capture through Other Transaction Authority vehicles.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions exemplifying sustained dominance through satellite communication heritage and distributed aperture radar investment respectively. L3Harris Technologies, Inc. represents the specialized tactical communications archetype. These three entities anchor the vendor structure through prime contractor roles on JADC2-aligned programs.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems plc |
| RTX Corporation |
| General Dynamics Corporation |
| The Boeing Company |
| CACI International Inc. |
| Leidos Inc. |
| Others |
Value Network & Pricing Analysis
Software-defined radio architectures compress multiple single-purpose hardware boxes into programmable units, simultaneously collapsing unit economics and concentrating procurement leverage among cleared integrators capable of NSA Type 1 certification. This technological transition rewards vendors with existing cryptographic validation pipelines while squeezing margins for hardware-only suppliers locked out of firmware-upgrade revenue streams.
Pricing Analysis
Margin tightening in tactical radio tiers reflects the Army's Integrated Tactical Network program consolidating multi-channel software-defined procurement under enterprise licensing. Three-tier pricing structure across Type 1 certified, provisional, and commercial-grade encryption levels differentiates offerings, with certification grade commanding substantial premiums. Cost-down pressure on unclassified subsystems accelerates because Section 889 prohibitions force mid-production redesigns. Defense Contractors absorbing OTA vehicles demonstrate lowest price sensitivity; state and local First Responders exhibit highest.
Supply Chain Analysis
Domestic-content mandates including Section 889 and DoD CMMC Level 3 requirements reshape sourcing toward qualified U.S. foundries and cleared facility operators. Gallium nitride wafer production draws from a single qualified domestic foundry for radar transmit-receive modules, while tactical radio chipsets rest on Taiwan and South Korea fabrication. Single-source vulnerability in wide-bandgap semiconductors constitutes the dominant structural risk. Distribution runs through prime contractor tier-one integration cells in Northern Virginia and Texas corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TS/SCI-cleared software engineering capacity constraints prop pricing power for qualified vendors, as workforce scarcity in Maryland and Northern Virginia corridors limits program scaling regardless of budget availability.
For Market Incumbents: Acquire cleared facility infrastructure and TS/SCI-cleared engineering teams to consolidate prime contractor positions on JADC2-aligned programs. Defend against Silicon Valley entrants leveraging OTA rapid prototyping by deepening cryptographic certification pipelines and anchoring open-architecture consortium leadership. Vertical integration into gallium nitride foundry partnerships mitigates single-source supply risk. For New Entrants and Emerging Players: Begin with zero-trust cybersecurity microsegmentation tools and edge-deployed sensor fusion algorithms where CMMC Level 3 barriers remain lower than Type 1 certification requirements. Unmanned systems detect-and-avoid systems for FAA beyond-visual-line-of-sight operations represent the most penetrable segment. Go-to-market through OTA vehicles with Army Futures Command or Special Operations Command technology incubators bypasses traditional FAR procurement friction. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of mid-tier subsystem specialists possessing NSA Type 1 certification pipelines and cleared facility infrastructure. Long-term viability favors vendors with sustained R&D investment in distributed aperture systems and proliferated constellation ground segments. Watch Space Development Agency constellation deployment schedules as inflection indicator for sensor investment reallocation from exquisite platforms to distributed architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Level 3 Certification Investment | Filters subcontractor access and concentrates procurement among qualified defense industrial base participants. |
| Zero-Trust Architecture Deployment | OMB memoranda mandate microsegmentation replacement of perimeter-based network infrastructure across classified enclaves. |
| Proliferated Constellation Ground System Integration | Space Development Agency schedules drive demand for low-earth orbit sensor network connectivity solutions. |
| Software-Defined Radio Platform Consolidation | Army's Integrated Tactical Network program replaces legacy single-band radios with multi-channel programmable systems. |
| OTA Rapid Prototyping Agreement Capture | Bypasses FAR-based procurement to accelerate Silicon Valley technology insertion into classified programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across program managers at Army Futures Command, NSA cryptographic certification leads, prime contractor business development executives, and DISA milCloud procurement officers. Defense budget justification documents, DoD CMMC framework implementation guidance, and Space Development Agency constellation deployment schedules provided additional validation. Bottom-up segment sizing and top-down budget authority reconciliation ensured cross-check integrity.
Reconciliation of shipment data, procurement announcements, and facility investment disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology maturity tier, end-user procurement authority, deployment security classification, and solution functional category. CAGRs derived from budget trajectory analysis and program-of-record scheduling. JADC2 interoperability certification timelines and NSA Type 1 validation pipelines constituted industry-specific forecast inputs.
Underlying measurement precision varies by segment; Satellite Communication and Command & Control carry tighter precision given established program-of-record visibility, while Cybersecurity and Data Analysis reflect greater uncertainty given rapid zero-trust mandate evolution. Forecasts reflect assumptions regarding congressional defense appropriation continuity and Space Development Agency funding profiles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
C6ISR Market
ISR
Europe C5ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
North America Airborne ISR Market
ISR
North America C5ISR Market
ISR
Air Based C4ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Naval ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
C4ISR Market
ISR
Low Altitude Radar Market
ISR
Airborne ISR Market
ISR
Japan C4ISR Market