
 Saudi Arabia C4ISR Market | 2026-2036
Saudi Arabia C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia C4ISR Market Analytics
Defense procurement channels in Saudi Arabia are reshaping as the General Authority for Military Industries enforces local content thresholds. Raytheon Technologies Corporation leverages its established radar maintenance footprint to sustain long-term service contracts. SAMI Advanced Electronics anchors indigenous production through its partnership with international primes. BAE Systems competes by specializing in naval combat management integrations for the Royal Saudi Naval Forces.
C4ISR denotes the integrated architecture of command, control, communications, computers, intelligence, surveillance, and reconnaissance systems that fuse sensor data into actionable decision support across multi-domain operations. These systems typically operate on encrypted IP-based networks with latency thresholds under 50 milliseconds for real-time targeting cycles. Communication Systems command the largest installed base given the kingdom's priority on resilient tactical datalinks across desert and maritime theaters. Surveillance Systems represent the fastest-expanding segment as aerostat and UAV-mounted EO/IR payloads proliferate along the Yemeni border. Intelligence Gathering applications concentrate margin pools where multi-INT fusion platforms require continuous software refresh cycles.
SFDA and the General Authority for Military Industries jointly shape market access through dual-use technology licensing and cybersecurity certification requirements for imported subsystems. The National Cybersecurity Authority mandates sovereign data residency for classified C4ISR networks, forcing foreign vendors into local hosting partnerships. Stakeholders must monitor how Vision 2030 localization quotas redefine supplier eligibility for future defense tenders.
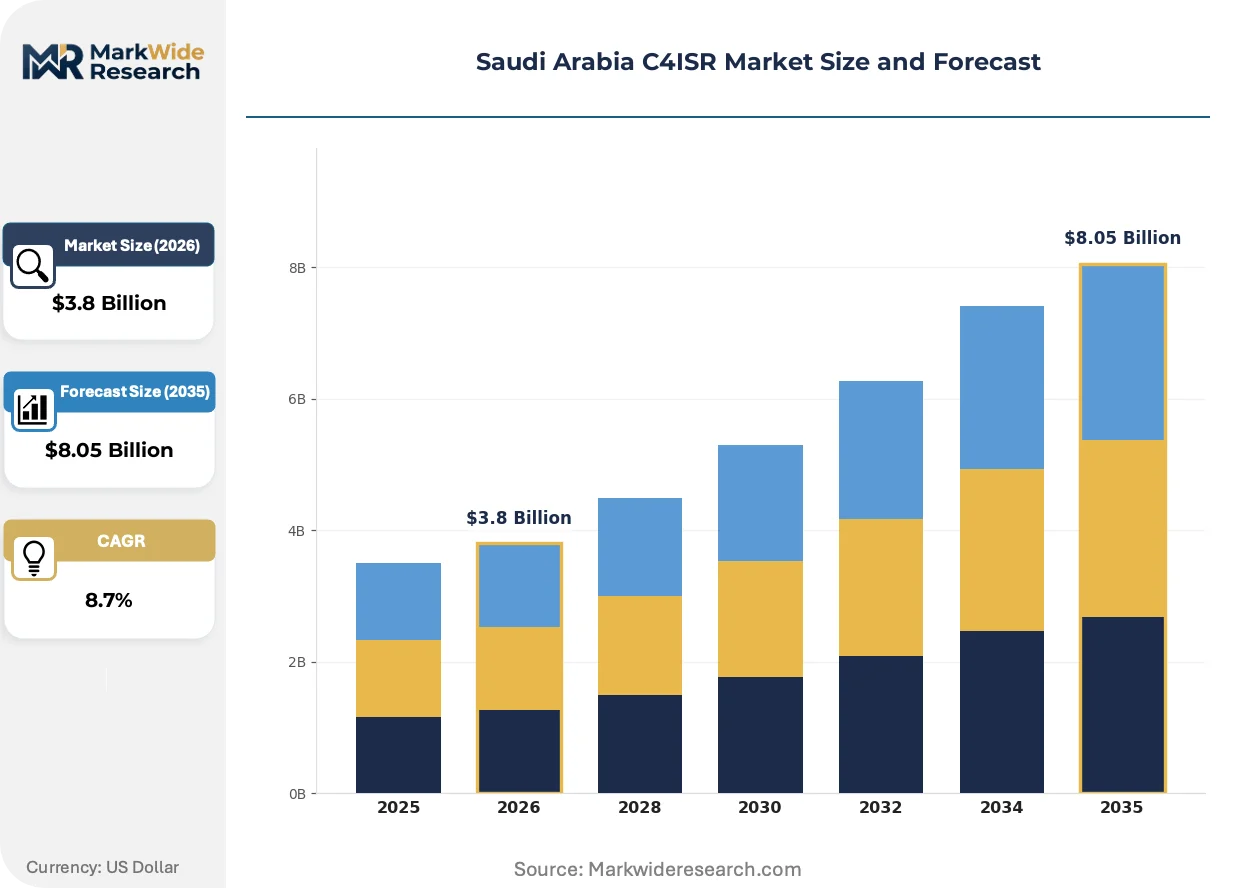
Market Dynamics
Vision 2030 localization mandates are restructuring supplier eligibility across Saudi defense procurement, forcing foreign primes into joint ventures with SAMI and redirecting technology transfer obligations toward sovereign production corridors.
Growth Catalysts
- Border Surveillance Modernization:Aerostat and UAV-mounted EO/IR payloads are proliferating along the Yemeni frontier, generating sustained demand for multi-INT fusion platforms and real-time datalink infrastructure.
- GAMI Localization Thresholds:The General Authority for Military Industries enforces escalating local content requirements that redirect foreign OEM investment toward Riyadh-based assembly and software development facilities.
- Networked Command Suites:The Royal Saudi Air Force is accelerating procurement of integrated battle management systems that compress sensor-to-shooter timelines below 50 milliseconds.
Market Restraints
- Semiconductor Import Dependency:Advanced FPGA and GaN components for radar signal processing remain concentrated in US and European supply chains, exposing programs to export control volatility.
- Cybersecurity Certification Friction:The National Cybersecurity Authority mandates sovereign data residency for classified networks, extending vendor onboarding timelines by 12-18 months.
- Technical Talent Scarcity:Indigenous engineering capacity for AI-driven intelligence analytics lags procurement schedules, forcing reliance on expatriate labor for system integration.
Strategic Opportunities
- Eastern Province Industrial Cluster:King Salman Energy Park offers tax-advantaged zones for C4ISR component manufacturing serving both defense and adjacent energy security applications.
- Dual-Use Technology Licensing:SFDA and GAMI joint frameworks enable commercial satellite communication providers to pivot encrypted payload capabilities toward military datalink markets.
- AI-Enabled Predictive Maintenance:Convergence of digital twin architectures with sovereign cloud infrastructure creates white space for indigenous software vendors in platform sustainment.
Industry Challenges
- Legacy System Integration Complexity:Royal Saudi Naval Forces operate mixed fleets of Western and Eastern-origin combat management systems that resist seamless interoperability without costly middleware development.
- Specialized Workforce Pipeline Gaps:Universities in Riyadh and Dhahran produce insufficient graduates in RF engineering and cryptographic protocol design to meet localization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia C4ISR Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, Communication Systems, Surveillance Systems, Reconnaissance Systems Application: Military Operations, Border Security, Disaster Management, Intelligence Gathering End User: Defense Agencies, Government Security, Intelligence Agencies, Private Security Firms Service Type: Maintenance Services, Integration Services, Training Services, Consulting Services |
| Companies Covered | Raytheon Technologies Corporation, SAMI Advanced Electronics, Saudi Arabian Military Industries, BAE Systems, Northrop Grumman Corporation, General Dynamics IS&T Arabia, L3Harris Technologies Inc., Thales, Lockheed Martin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia C4ISR Market Evolving Landscape
Software-defined architectures are displacing hardware-centric legacy platforms across Saudi C4ISR procurement, compressing upgrade cycles and enabling incremental capability insertion without platform replacement.
Virtualized ground control stations are virtualizing traditional hardware-based UAV piloting infrastructure. The Royal Saudi Air Force is fielding these systems for Reaper and indigenous Saqr fleet operations. This shift is virtualizing maintenance footprints and enabling multi-aircraft control from dispersed nodes.
GAMI's offset policy framework now mandates technology transfer ratios for all foreign primes exceeding SAR 500 million in contract value. Industrial consequence includes compulsory joint venture formation with SAMI Advanced Electronics for radar and electronic warfare subsystem production. Naval combat management integrators face the most compressed compliance timelines given the Royal Saudi Naval Forces' accelerated modernization schedule.
Consolidated platform-as-a-service contracting is replacing discrete hardware purchases across Saudi defense procurement. The Ministry of Defense is unbundling sensor hardware from software refresh and sustainment obligations. This pattern is most visible in Riyadh's defense industrial corridor, where primes now compete on lifecycle cost rather than unit acquisition price.
Saudi Arabia C4ISR Market Segmentation
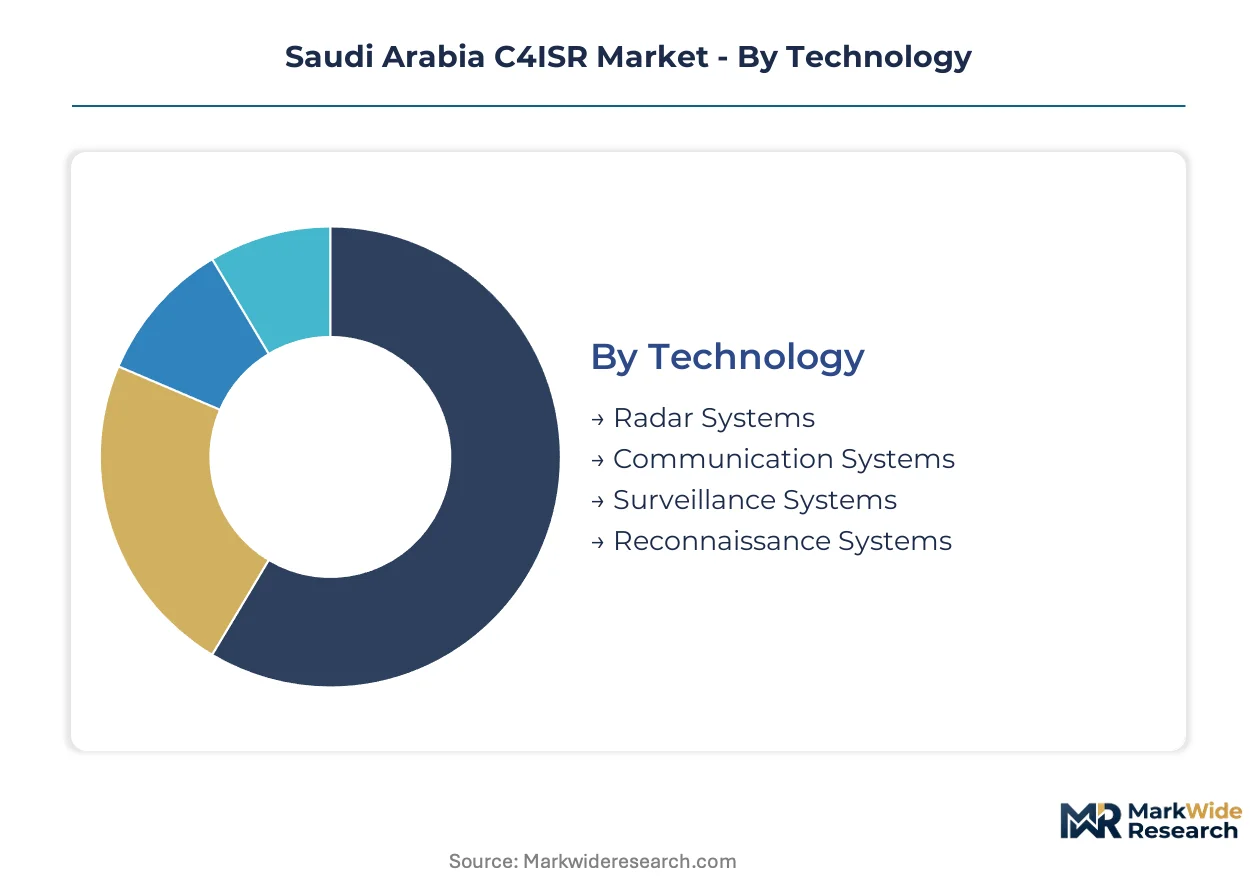
C4ISR procurement in Saudi Arabia fragments across operational domains, with each segment exhibiting distinct technical requirements and localization pressures. Understanding these divisions clarifies where Vision 2030 mandates reshape supplier eligibility and technology transfer obligations.
Technology:
Use-case spectrum spans from fixed-site air defense radars to mobile UAV control stations, with each technology tier demanding different sovereign production capabilities and cybersecurity certification pathways.
- Communication Systems:Encrypted IP-based tactical datalinks operating under 50-millisecond latency thresholds form the backbone of multi-domain coordination. The Royal Saudi Air Force's networked command suite procurement concentrates demand in Riyadh's defense industrial corridor, where SAMI Advanced Electronics anchors indigenous production partnerships.
- Surveillance Systems:Aerostat and UAV-mounted EO/IR payloads along the Yemeni border generate sustained procurement volume for multi-INT fusion platforms. GAMI localization thresholds are redirecting foreign OEM investment toward sovereign assembly facilities with escalating local content requirements.
- Radar Systems:Advanced FPGA and GaN components for signal processing remain import-dependent, exposing programs to US and European export control volatility.
- Reconnaissance Systems:Manned and unmanned platforms with SIGINT and ELINT payloads serve intelligence agencies and defense agencies across the kingdom's operational theaters.
Established volume favors Communication Systems; emerging adoption favors Surveillance Systems.
Application:
Cost tier differentiation separates sustained military modernization programs from discretionary border security investments and emergency-response capabilities.
- Military Operations:Integrated battle management systems compressing sensor-to-shooter timelines anchor the largest procurement budgets. The Royal Saudi Air Force and Royal Saudi Naval Forces drive platform-as-a-service contracting that unbundles hardware from software refresh obligations.
- Intelligence Gathering:Multi-INT fusion platforms requiring continuous software refresh cycles command premium margin pools. The National Cybersecurity Authority's sovereign data residency mandates extend vendor onboarding timelines for classified network deployments.
- Border Security:Aerostat and UAV surveillance along the Yemeni frontier represents the steepest expansion trajectory among application categories.
- Disaster Management:Dual-use communication and surveillance assets serve civil defense coordination under SFDA and GAMI joint licensing frameworks.
Defense procurement dominates absolute spending; intelligence applications concentrate margin capture.
End User:
Customer type determines security clearance requirements, localization flexibility, and contracting vehicle preferences across Saudi defense procurement channels.
- Defense Agencies:The Ministry of Defense and service branches operate consolidated platform-as-a-service contracts with lifecycle cost competition. GAMI offset policies mandate technology transfer ratios exceeding SAR 500 million in contract value.
- Intelligence Agencies:Specialized procurement channels operate under National Cybersecurity Authority oversight with sovereign data residency requirements for classified C4ISR networks.
- Government Security:Ministry of Interior units require interoperable systems with defense agency networks, creating middleware integration complexity.
- Private Security Firms:Commercial satellite communication providers pivot encrypted payload capabilities toward military datalink markets under dual-use technology licensing.
Defense agencies anchor procurement volume; intelligence agencies impose the strictest compliance barriers.
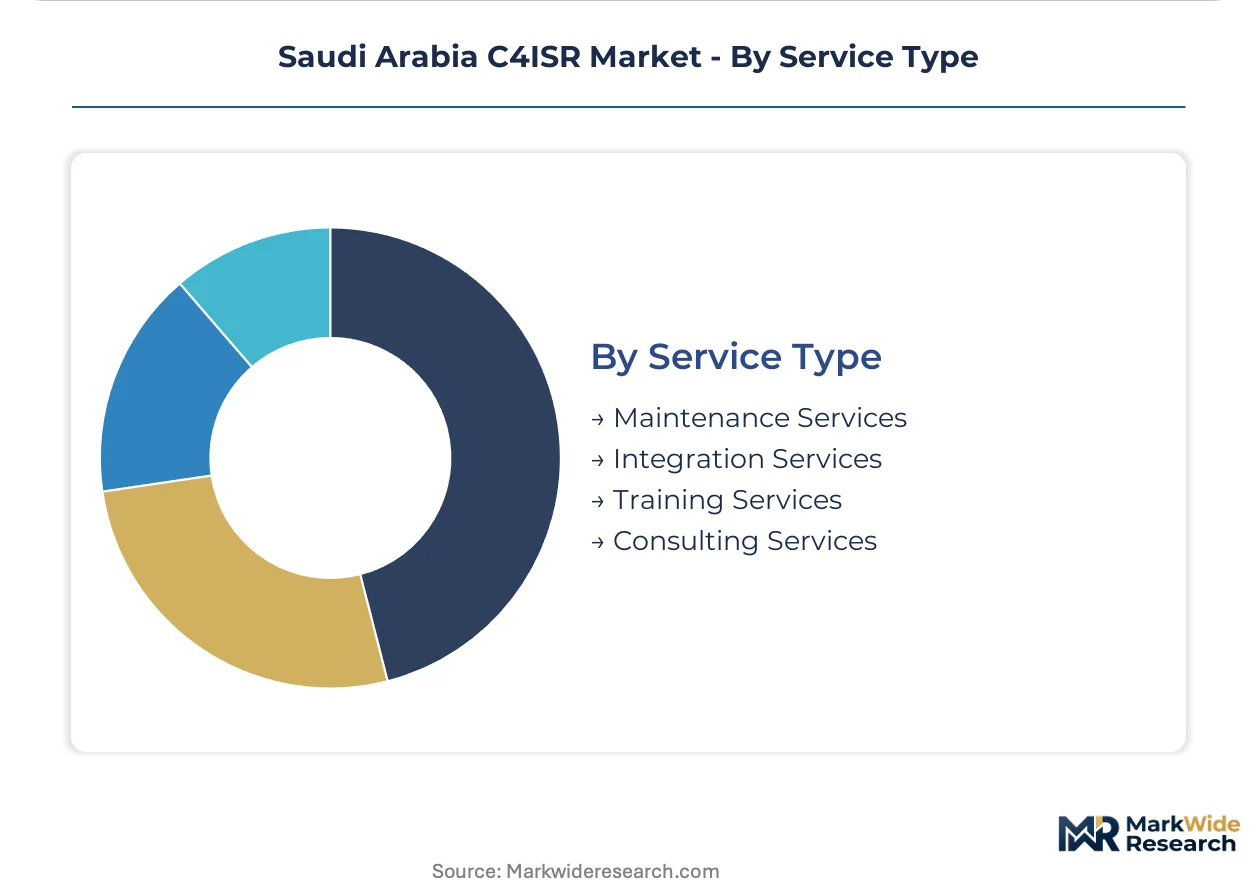
Service Type:
Margin concentration shifts from hardware integration toward software sustainment and sovereign cloud infrastructure as platform-as-a-service contracting displaces discrete purchases.
- Integration Services:Middleware development for mixed Western and Eastern-origin combat management systems in the Royal Saudi Naval Forces generates specialized demand. Legacy system interoperability resists seamless integration without costly custom development.
- Maintenance Services:AI-enabled predictive maintenance leveraging digital twin architectures creates white space for indigenous software vendors. King Salman Energy Park offers tax-advantaged zones for component manufacturing serving adjacent sustainment applications.
- Training Services:Universities in Riyadh and Dhahran produce insufficient RF engineering and cryptographic protocol graduates to meet localization timelines, forcing reliance on expatriate labor.
- Consulting Services:Cybersecurity certification navigation and GAMI compliance advisory support foreign vendor market entry.
Maintenance services capture recurring revenue; integration services face compressed margins from technical talent scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council Interconnection Grid underpins regional energy security coordination that extends into defense infrastructure planning across the Arabian Peninsula.
Eastern Province
King Salman Energy Park anchors tax-advantaged manufacturing zones for C4ISR component production serving adjacent energy security applications. The General Authority for Military Industries enforces localization thresholds that redirect foreign OEM investment toward Dhahran-based assembly facilities. SAMI Advanced Electronics operates sovereign production partnerships with international primes in the industrial corridor between Dammam and Jubail.
Riyadh
The Royal Saudi Air Force accelerates procurement of networked command suites that compress sensor-to-shooter timelines below 50 milliseconds. The National Cybersecurity Authority mandates sovereign data residency for classified networks, forcing foreign vendors into local hosting partnerships. Riyadh's defense industrial corridor concentrates platform-as-a-service contracting that unbundles hardware from software refresh obligations.
Western Region
The Red Sea coastal corridor supports naval combat management modernization for the Royal Saudi Naval Forces operating mixed Western and Eastern-origin fleets. SFDA and GAMI joint frameworks enable dual-use technology licensing for commercial satellite communication providers pivoting toward military datalink markets. Jeddah hosts middleware development facilities addressing legacy system interoperability complexity.
NEOM Northwest
The $500 billion giga-project incorporates integrated surveillance and communications infrastructure as foundational urban planning elements. Vision 2030 localization mandates require technology transfer ratios for contractors exceeding SAR 500 million in project value. The zone attracts AI-enabled predictive maintenance vendors leveraging digital twin architectures with sovereign cloud infrastructure.
Border Regions
Aerostat and UAV-mounted EO/IR payloads proliferate along the Yemeni frontier, generating sustained procurement volume for multi-INT fusion platforms. The Ministry of Interior requires interoperable systems with defense agency networks, creating middleware integration demand. Universities in Tabuk and Jazan produce insufficient RF engineering graduates to meet localization timelines for border surveillance modernization.
Saudi Arabia C4ISR Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in semiconductor and RF subsystems. The Saudi C4ISR market exhibits tiered consolidation around prime contractors fulfilling GAMI offset obligations, with mid-tier specialists competing for subsystem integration roles. Two strategic archetypes dominate: foreign primes operating through SAMI joint ventures, and indigenous entities capturing sovereign production mandates. Competitive moves concentrate on technology transfer compliance and local facility establishment rather than price-based rivalry.
Among US-based defense conglomerates, Raytheon Technologies Corporation and Northrop Grumman Corporation exemplify the prime-contractor archetype navigating GAMI localization requirements through established in-country maintenance footprints. SAMI Advanced Electronics anchors the indigenous tier, representing the sovereign production mandate that foreign primes must accommodate through compulsory joint venture structures. These three entities occupy positions that illustrate the market's fundamental restructuring around Vision 2030 industrial policy objectives.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| SAMI Advanced Electronics |
| Saudi Arabian Military Industries |
| BAE Systems |
| Northrop Grumman Corporation |
| General Dynamics IS&T Arabia |
| L3Harris Technologies Inc. |
| Thales |
| Lockheed Martin Corporation |
| Others |
Value Network & Pricing Analysis
US and European semiconductor foundries concentrate production of advanced FPGA and GaN components for radar signal processing, anchoring margin pools in software sustainment and sovereign cloud infrastructure downstream. Foreign primes absorb import volatility through lifecycle contracting that bundles hardware with localized service delivery.
Pricing Analysis
Volume-discount tiering structures dominate platform-as-a-service contracts across the Ministry of Defense, with pricing stratifying across integrated battle management systems, subsystem upgrades, and standalone maintenance services. Cost differentiation rests on certification grade for National Cybersecurity Authority compliance and localization depth mandated by GAMI thresholds. Margins are tightening in hardware-only tiers as sovereign production quotas compress procurement flexibility. Intelligence agencies exhibit lowest price sensitivity given classified network requirements; border security units face highest budget pressure from accelerated aerostat deployment schedules.
Supply Chain Analysis
Contract manufacturing capacity for C4ISR subsystems concentrates with SAMI Advanced Electronics and its joint venture partners in Riyadh and Dhahran, feeding sovereign assembly requirements. Advanced RF components draw from US, UK, and German supplier bases; encrypted datalink hardware sources from domestic facilities under technology transfer agreements. Single-source vulnerability persists in GaN foundry capacity subject to export control volatility. Distribution runs through GAMI-certified procurement channels with local content verification at contract milestones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-as-a-service contracting transforms hardware procurement into recurring-revenue relationships, with AI-enabled predictive maintenance and sovereign cloud hosting expanding faster than sensor hardware sales. Foreign primes must anchor positioning in software refresh cycles and digital twin architectures to capture sustained margin pools.
For Market Incumbents: Pre-empt margin erosion in hardware tiers by deepening sovereign cloud partnerships with National Cybersecurity Authority-certified hosting providers. Consolidate middleware development capabilities for Royal Saudi Naval Forces mixed-fleet integration before emerging specialists capture naval combat management modernization contracts. Lock in multi-year software sustainment obligations through digital twin platform deployments at King Salman Energy Park facilities.
For New Entrants and Emerging Players: Tabuk and Jazan border regions offer underpenetration in RF engineering talent pipelines and aerostat maintenance infrastructure. Target Ministry of Interior interoperability requirements as the most penetrable application segment, where middleware gaps between defense and security networks resist prime-contractor consolidation. Enter through GAMI joint venture structures with SAMI Advanced Electronics to satisfy localization thresholds for surveillance subsystem production.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense services firms holding expatriate-heavy integration workforces and GAMI compliance advisory practices. Five-to-ten year viability hinges on successful technology transfer execution and indigenous engineering pipeline development. Monitor King Salman Energy Park tenant announcements and SAMI Advanced Electronics partnership formations as inflection indicators for sovereign production capacity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| SAMI Joint Venture Formation | GAMI mandates technology transfer ratios exceeding SAR 500 million for foreign prime market access. |
| Sovereign Cloud Infrastructure Deployment | National Cybersecurity Authority data residency requirements force local hosting partnerships for classified networks. |
| AI-Enabled Predictive Maintenance Platform | Digital twin architectures with indigenous software vendors capture recurring sustainment revenue streams. |
| Middleware Development for Naval Integration | Royal Saudi Naval Forces mixed Western and Eastern-origin fleets demand specialized interoperability solutions. |
| RF Engineering Talent Pipeline Investment | Universities in Riyadh and Dhahran produce insufficient graduates to meet GAMI localization timelines. |
Research Methodology
Initial hypotheses were tested against primary input from Ministry of Defense procurement officers, SAMI Advanced Electronics program managers, National Cybersecurity Authority certification leads, and foreign prime contractor country directors, then refined through secondary validation against GAMI policy frameworks, SFDA dual-use licensing records, and Vision 2030 industrial localization directives. Bottom-up segmentation modeling across technology tiers and application domains triangulated with top-down macroeconomic projections for defense expenditure.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling procurement volume against sovereign production capacity buildout in Riyadh's defense industrial corridor and King Salman Energy Park. Segmentation dimensions spanned communication, surveillance, radar, and reconnaissance technologies; military, intelligence, border security, and disaster management applications; and defense agency, intelligence agency, government security, and private security end users. CAGRs derived from contracted program timelines and GAMI offset policy implementation schedules, with sensor-to-shooter latency requirements and cybersecurity certification pathways as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive localization acceleration by GAMI or sudden export control tightening by US and European regulators would shift outcomes beyond modeled ranges. Quarterly review of SAMI partnership announcements, National Cybersecurity Authority certification backlog durations, and King Salman Energy Park occupancy rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
IFF System Market
ISR
Japan C4ISR Market
ISR
C5ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Australia C4ISR Market
ISR
C6ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Infrared Suppression Systems Market
ISR
NATO C4ISR Market
ISR
C4ISR Market
ISR
United States C4ISR Market
ISR
Europe C5ISR Market
ISR
North America C5ISR Market
ISR
Brazil C4ISR Market