
 Eastern Europe C4ISR Market | 2026-2036
Eastern Europe C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Eastern Europe C4ISR Market Foresight
Artificial intelligence integration into command-and-control architectures is narrowing the gap between sensor data collection and actionable battlefield decisions. Rostec leverages its domestic industrial base to sustain captive production of electronic warfare modules. Elbit Systems Ltd. anchors its regional position through specialized soldier systems and unmanned platform integration. Rheinmetall AG competes aggressively on ground-based reconnaissance and armored vehicle sensor suites.
C4ISR denotes the military technical architecture combining command, control, communications, computers, intelligence, surveillance, and reconnaissance into networked decision-support systems, typically operating across satellite-linked data protocols with sub-second latency requirements for targeting cycles. Its primary purpose is compressing the sensor-to-shooter timeline while fusing multi-domain inputs into unified operational pictures. Intelligence systems capture the deepest margin pools as sovereign data analytics capabilities become non-negotiable for Eastern European states. Surveillance systems represent the fastest-growing product category, driven by persistent border monitoring demands along NATO's eastern flank. Communication systems remain structurally mature but require continuous refresh as legacy Soviet-era equipment phases out.
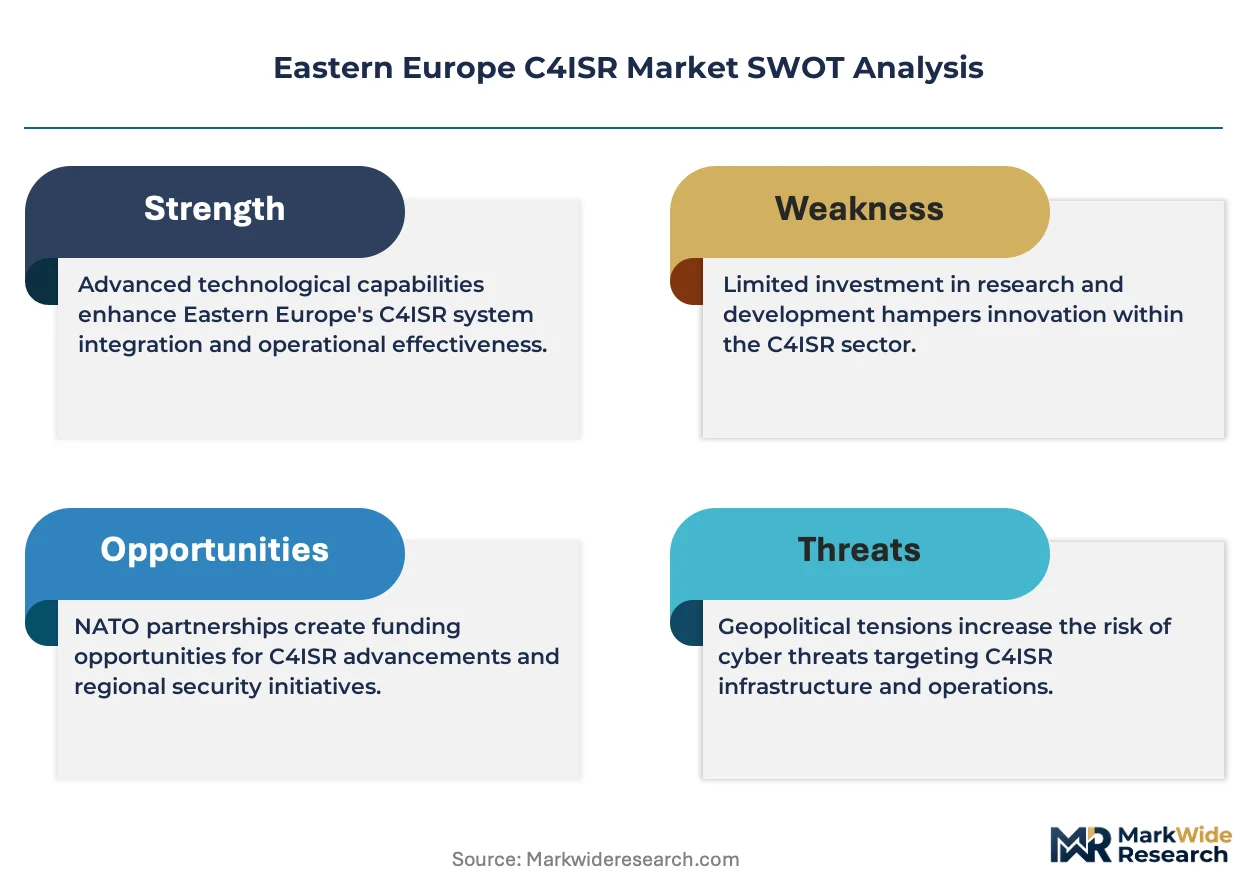
Poland's national military procurement regulator and the EU's European Defence Fund shape local contract eligibility, while NATO's STANAG standardization protocols dictate cross-border equipment interoperability. CE marking under the EU's Radio Equipment Directive constrains subsystem certification pathways for non-European suppliers. Stakeholders must weigh sovereign capability development against alliance integration imperatives when allocating R&D budgets across the coming procurement cycles.
Market Dynamics
NATO's STANAG standardization protocols are compressing procurement timelines across Eastern European defense ministries while mandating cross-border equipment interoperability as a non-negotiable contract term.
Growth Catalysts
- EU Defence Industrial Strategy:The framework redirects procurement budgets toward EU-based suppliers, creating preferential access for Polish and Baltic state contractors bidding on C4ISR modernization programs.
- Poland:Warsaw's accelerated defense spending is generating concentrated demand for integrated command systems across land, air, and maritime domains.
- Artificial intelligence:Machine learning integration into sensor fusion architectures is shortening targeting cycles and justifying premium system upgrades.
Market Restraints
- Semiconductor supply concentration:Dependence on East Asian foundries for advanced chips creates vulnerability in radar processing module production.
- CE marking under EU Radio Equipment Directive:Certification pathways impose 12-18 month delays on non-European subsystem suppliers seeking contract eligibility.
- Legacy Soviet-era equipment:Proprietary communication protocols in existing inventories obstruct seamless integration with NATO-standard architectures.
Strategic Opportunities
- Romania:Underpenetrated relative to Poland, Bucharest's Black Sea surveillance requirements present untapped demand for maritime reconnaissance platforms.
- Cross-domain sensor fusion:Convergence of signals intelligence with unmanned aerial systems is opening new contract categories for integrated battlefield management.
- NATO interoperability mandates:Alliance procurement standards are creating captive demand for STANAG-certified communication subsystems across multiple member states.
Industry Challenges
- Cybersecurity certification:EU Common Criteria evaluation timelines extend product qualification periods, compressing vendor cash conversion cycles.
- Systems integration complexity:Merging legacy analog infrastructure with digital IP-based networks demands specialized engineering capacity that Eastern European contractors struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eastern Europe C4ISR Market |
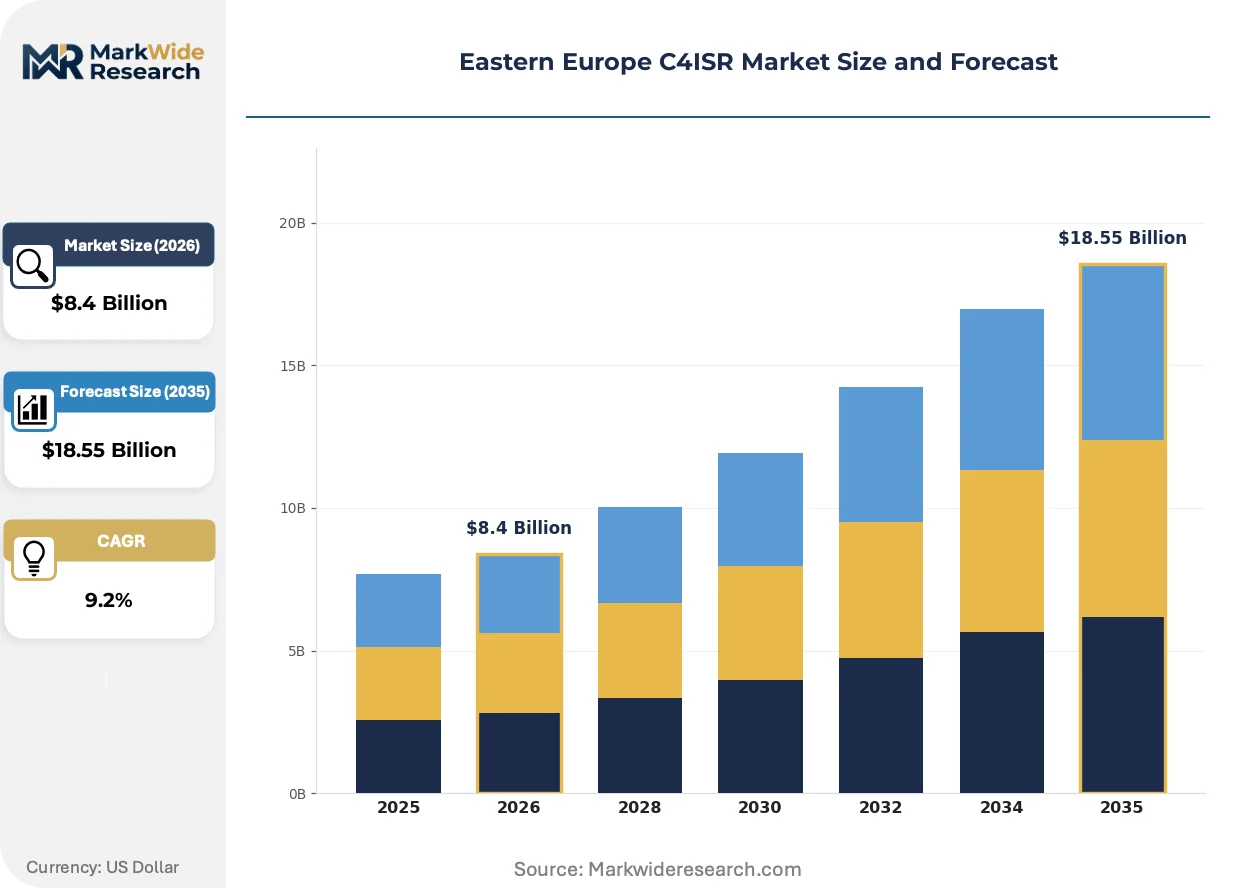
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Systems, Intelligence Systems, Reconnaissance Systems, Surveillance Systems Application: Military Operations, Civil Defense, Border Security, Resource Management End User: Government Agencies, Defense Contractors, Law Enforcement, NGOs Technology: Satellite Communication, Radar Systems, Sensor Networks, Cybersecurity |
| Companies Covered | Rostec, Elbit Systems Ltd., BAE Systems plc, Rheinmetall AG, Leonardo S.p.A., Thales Group, Saab AB, L3Harris Technologies, Inc., Lockheed Martin Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eastern Europe C4ISR Market Shifts & Advancements
Software-defined architectures are displacing hardware-centric legacy systems across Eastern European defense procurement, enabling faster capability upgrades without platform replacement.
Edge computing architectures are digitizing tactical data processing at the battalion level. Polish land forces are fielding these systems in priority mechanized brigades. This compression of decision latency is digitizing the traditional division between strategic and tactical intelligence layers.
CE marking requirements under the EU's Radio Equipment Directive are tightening electromagnetic compatibility standards for battlefield communication equipment. Non-compliant legacy inventories face accelerated obsolescence. Baltic state procurement offices are prioritizing pre-certified subsystems to avoid integration delays.
Consolidated platform purchasing is displacing fragmented subsystem acquisitions across Eastern European defense ministries. National procurement regulators in Warsaw and Tallinn are mandating prime-contractor accountability for full system integration. This shift concentrates contract value with integrated solution providers capable of spanning sensor-to-shooter architectures.
Eastern Europe C4ISR Market Segmentation
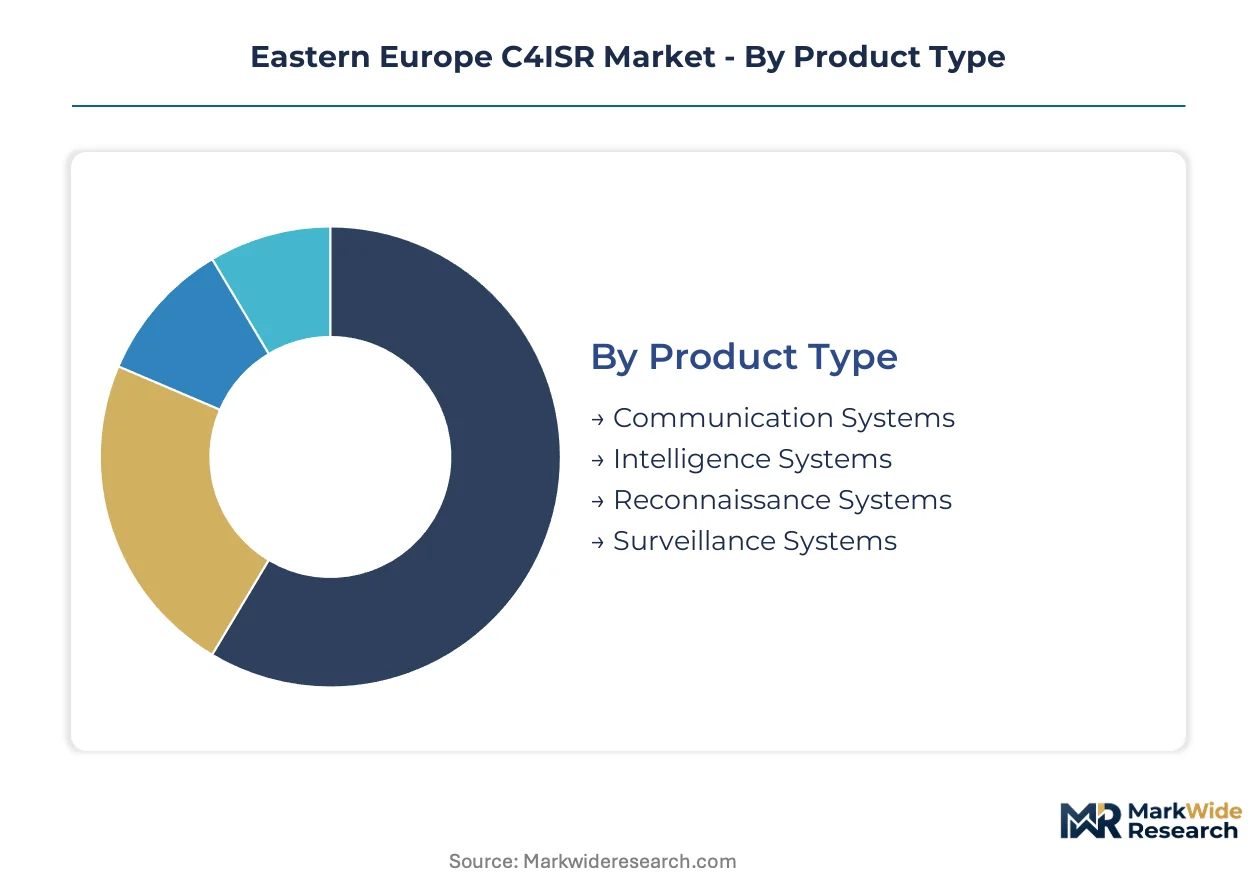
C4ISR procurement patterns in Eastern Europe diverge sharply by product lifecycle and operational criticality. Intelligence and surveillance systems refresh on compressed cycles driven by threat evolution, while communication infrastructure exhibits extended replacement horizons due to NATO interoperability lock-in.
Product Type:
Surveillance systems turn over fastest as persistent border monitoring demands strain sensor endurance. Intelligence systems follow with multi-year analytics platform refresh cycles. Communication and reconnaissance assets exhibit the longest in-service horizons.
- Intelligence Systems:Multi-source data fusion platforms integrating signals, imagery, and open-source feeds into actionable assessments. Polish defense modernization concentrates procurement here as sovereign analytics capabilities become non-negotiable for operational autonomy.
- Surveillance Systems:Persistent electro-optical and radar platforms for border and battlespace monitoring. Baltic state ministries prioritize these for NATO's eastern flank, where terrain awareness requirements outpace legacy platform capabilities.
- Communication Systems:Secure voice and data networks operating across satellite, terrestrial, and tactical waveforms.
- Reconnaissance Systems:Manned and unmanned platforms for target acquisition and battle damage assessment.
Communication systems dominate installed base. Surveillance systems are where expansion concentrates.
Application:
Cost tiering separates sovereign defense applications from civil implementations, with military programs commanding premium system specifications and accelerated certification timelines.
- Military Operations:Integrated command architectures spanning joint force coordination and real-time targeting. Warsaw's mechanized brigade modernization drives concentrated demand for battalion-level battle management systems.
- Border Security:Persistent monitoring of terrestrial and maritime frontiers using fused sensor networks. Romania's Black Sea coastline presents underpenetrated demand relative to Polish and Baltic priorities.
- Civil Defense:Emergency coordination and disaster response communication networks.
- Resource Management:Infrastructure protection and environmental monitoring applications.
Military operations capture premium pricing tiers. Border security is climbing the fastest as NATO perimeter states accelerate procurement.
End User:
Volume concentration sits with government direct procurement, while defense contractors intermediate subsystem integration and technology transfer obligations.
- Government Agencies:National defense ministries and interior security directorates specifying system requirements and managing prime contracts. Poland's national military procurement regulator shapes regional tender structures and eligibility criteria.
- Defense Contractors:Prime integrators and subsystem specialists delivering STANAG-certified solutions. Elbit Systems and Rheinmetall AG anchor regional presence through localized production and offset agreements.
- Law Enforcement:National police and gendarmerie units requiring tactical communication and surveillance capabilities.
- NGOs:Humanitarian and observer organizations operating in conflict-adjacent environments.
Government agencies dominate contract flow. Defense contractors are where technology transfer requirements concentrate.
Technology:
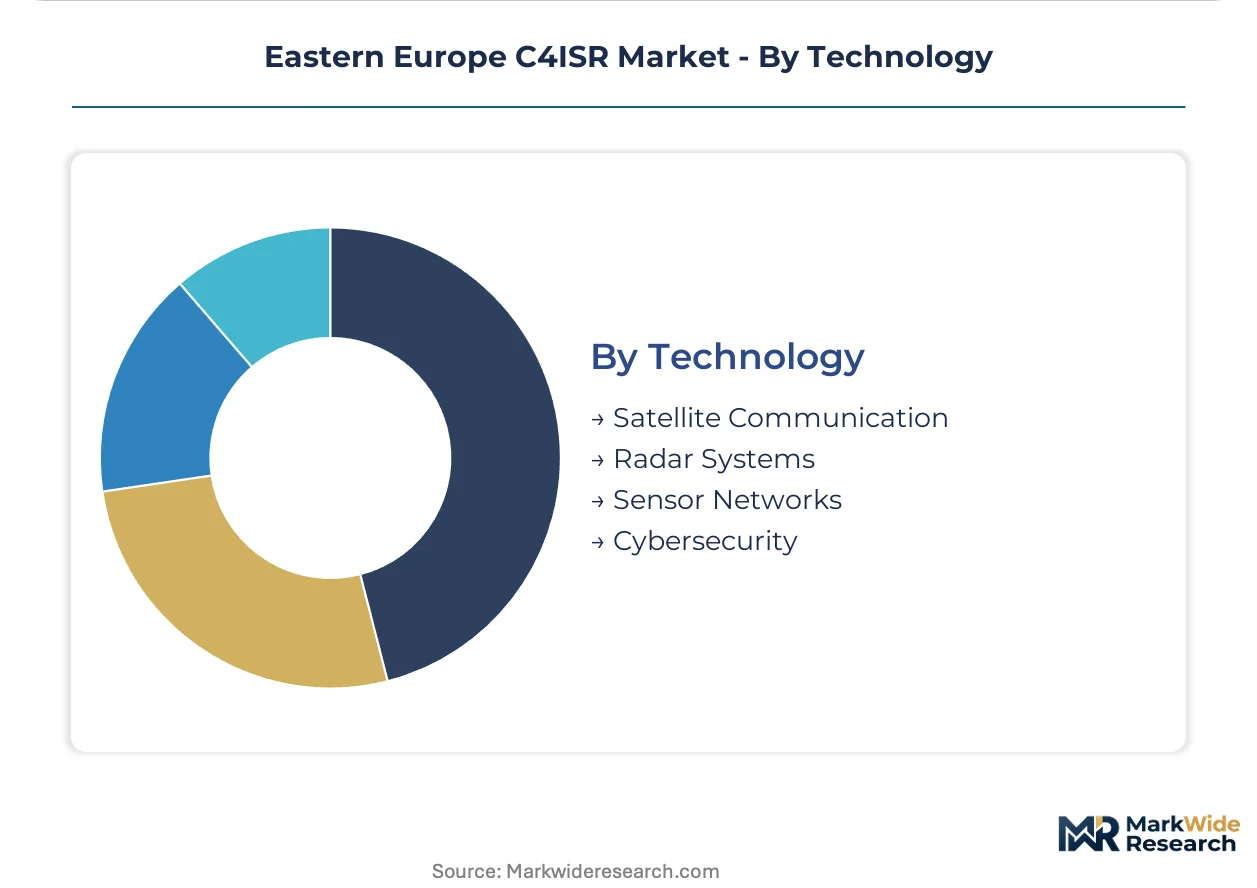
Supply concentration varies by technology maturity, with satellite communication exhibiting vendor consolidation and cybersecurity fragmenting across specialized niche providers.
- Cybersecurity:Encryption, intrusion detection, and secure protocol implementations protecting C4ISR networks from electronic attack. EU Common Criteria evaluation timelines extend qualification periods for subsystem vendors.
- Sensor Networks:Distributed acoustic, seismic, and chemical detection arrays for area denial and early warning. Edge computing architectures are digitizing tactical data processing at the battalion level in Polish priority formations.
- Satellite Communication:Beyond-line-of-sight data links and position-navigation-timing services.
- Radar Systems:Ground-based and airborne platforms for target detection and tracking.
Satellite communication anchors long-term infrastructure. Cybersecurity is expanding most quickly as electronic warfare threats intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in Warsaw, Tallinn, and Bucharest concentrate buyer authority for C4ISR modernization across NATO's eastern flank. National military regulators in each capital shape contract eligibility through localized offset requirements and technology transfer mandates.
Poland
Warsaw's mechanized brigade modernization drives concentrated demand for battalion-level battle management systems and sensor fusion platforms. Poland's national military procurement regulator mandates STANAG certification for all communication subsystems entering tender processes. The Wrocław-Toruń industrial corridor hosts emerging domestic integrators partnering with Western primes on co-production agreements.
Romania
Bucharest's Black Sea surveillance requirements present underpenetrated demand for maritime reconnaissance and coastal radar networks relative to Polish and Baltic priorities. The country's national defense procurement agency prioritizes NATO interoperability in all naval modernization tenders. Constanța anchors regional maritime C4ISR development through port infrastructure and naval base expansion.
Estonia
Tallinn's cyber defense command structures generate specialized demand for signals intelligence and electronic warfare integration. Estonia's Ministry of Defense mandates EU Common Criteria evaluation for all cybersecurity subsystems entering national inventories. The Tartu-Tallinn technology corridor concentrates startup activity in tactical data analytics and edge computing applications.
Latvia
Riga prioritizes persistent border monitoring along its eastern frontier through fused electro-optical and radar sensor networks. Latvia's State Border Guard coordinates procurement with NATO's Force Integration Unit standards. The Riga-Jelgava axis hosts maintenance and integration facilities supporting regional surveillance platform sustainment.
Lithuania
Vilnius accelerates command system upgrades for its Iron Wolf mechanized brigade under NATO enhanced forward presence commitments. Lithuania's Ministry of National Defence requires CE marking compliance under the EU Radio Equipment Directive for all tactical communication equipment. The Kaunas free economic zone attracts subsystem assembly operations from Western European primes seeking regional market access.
Eastern Europe C4ISR Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Eastern European defense procurement, with prime integrators capturing consolidated platform contracts while niche vendors supply certified subsystems. The market structure tiers between full-system providers capable of spanning sensor-to-shooter architectures and component specialists focused on single-domain capabilities. Two strategic archetypes dominate: integrated solution providers leveraging offset agreements for market access, and technology specialists monetizing proprietary encryption or sensor processing IP. Competitive moves concentrate on strategic partnerships with local primes and capacity expansion through licensed production arrangements.
Within the integrated solution tier, Elbit Systems Ltd., Rheinmetall AG, and Thales Group exemplify positioning strategies built on localized production and NATO certification depth. Elbit Systems anchors regional presence through specialized soldier systems and unmanned platform integration. Rheinmetall AG occupies a position defined by ground-based reconnaissance and armored vehicle sensor suites. Thales Group sits within the secure communications and satellite ground segment specialization. These three represent contrasting geographic origins—Israeli, German, and French respectively—illustrating how EU Defence Industrial Strategy preferences and NATO interoperability mandates shape competitive access across Warsaw Pact successor states.
| Leading Market Players |
|---|
| Rostec |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Rheinmetall AG |
| Leonardo S.p.A. |
| Thales Group |
| Saab AB |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for advanced semiconductors funnels margin pools toward radar processing module integrators capable of securing allocation priority. Defense procurement offices in Warsaw and Tallinn translate silicon scarcity into cost-plus contract structures with NATO-certified subsystem vendors.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate prime integrator agreements, with semiconductor wafer pricing clauses triggering quarterly adjustments. Three-tier pricing structure across STANAG-certified, CE-marked, and legacy-equipment tiers separates NATO-compliant systems from transitional configurations. Cost compression in communication subsystem tiers is intensifying because Baltic procurement offices are consolidating platform purchases under single-prime accountability. Government defense ministries exhibit lowest price sensitivity due to sovereign capability imperatives, while law enforcement end-users face strict budget ceilings.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended terms have become standard for East Asian semiconductor distributors serving Eastern European defense integrators. Taiwan, South Korea, and Germany concentrate supply for advanced radar processors, secure encryption chipsets, and precision sensor components. Production draws from gallium nitride substrates, indium phosphide wafers, and radiation-hardened FPGA modules. Single-source vulnerability in EUV lithography equipment creates procurement risk for next-generation electronic warfare systems. Distribution runs through prime contractor-led integration hubs in Wrocław, Tallinn, and Bucharest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized systems engineering capacity for merging legacy Soviet analog infrastructure with NATO-standard digital architectures remains scarce across the regional contractor base. This capability gap constrains execution velocity for modernization programs.
For Market Incumbents: Entrench market position through captive production facilities in Poland's Wrocław-Toruń corridor and accelerated CE marking pre-certification for communication subsystems. Vertical integration into radar processing module assembly mitigates East Asian foundry allocation risk. Offset agreement depth with Warsaw's national military procurement regulator secures tender priority against emerging Israeli and French primes. For New Entrants and Emerging Players: Build out maritime surveillance capabilities targeting Romania's underpenetrated Black Sea coastline, where coastal radar and unmanned reconnaissance platform demand exceeds local integrator capacity. Cross-domain sensor fusion contracts for Iron Wolf brigade modernization present accessible entry points. Go-to-market execution should anchor on Tartu-Tallinn technology corridor partnerships for edge computing subsystem integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier cybersecurity specialists holding EU Common Criteria evaluation depth but lacking platform integration scale. Five-to-ten year viability hinges on NATO interoperability mandate durability and EU Defence Industrial Strategy enforcement consistency. Acquisition targeting should prioritize STANAG certification portfolio breadth. The signal to monitor is Polish defense ministry consolidation of battalion-level battle management system tenders under single-prime structures.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Pre-Investment | CE marking and NATO interoperability standards compress procurement timelines for certified vendors in Warsaw tender processes. |
| Localized Production Partnerships | Offset agreements with Polish and Baltic state regulators unlock contract eligibility under EU Defence Industrial Strategy preferences. |
| Edge Computing Subsystem Development | Battalion-level tactical data processing demand from Polish mechanized brigade modernization creates specialized contract categories. |
| Maritime Surveillance Platform Expansion | Romania's Black Sea requirements present underpenetrated demand relative to established Polish and Baltic markets. |
| Cybersecurity Certification Acceleration | EU Common Criteria evaluation timelines extend qualification periods, rewarding early investment in certification infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, systems integration engineers, and national military regulator officials; and secondary validation against NATO STANAG documentation, EU Defence Industrial Strategy policy releases, and national tender databases. Primary fieldwork encompassed procurement directors at Eastern European defense ministries, prime contractor program managers, and subsystem vendor sales executives. Secondary sources included EU Radio Equipment Directive certification records, CE marking registries, and customs trade data for radar and communication equipment. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Forecast inputs considered technology refresh cycles, NATO interoperability mandate phasing, and EU funding mechanism deployment patterns across the projection horizon. Segmentation dimensions modeled encompassed product type, application domain, end-user category, and technology layer. CAGRs were derived from weighted scenario analysis across procurement acceleration and budget constraint cases. Industry-specific inputs included Polish defense modernization program timelines and Baltic state border surveillance procurement schedules.
Stress conditions across semiconductor supply disruption, EU regulatory timeline extension, and NATO standard revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about alliance commitment durability and industrial strategy enforcement. Macroeconomic contraction, regulatory pathway alteration, or technological disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Japan C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Europe C5ISR Market
ISR
C5ISR Market
ISR
North America Airborne ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
NATO C4ISR Market
ISR
Land Based C4ISR Market
ISR
Airborne ISR Market
ISR
C6ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Air Based C4ISR Market
ISR
IFF System Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
C4ISR Market
ISR
North America C5ISR Market