
 Spain Satellite-Based Earth Observation Market | 2026-2036
Spain Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Satellite-Based Earth Observation Market Insights
Subscription-based data analytics is decoupling raw imagery from value-added intelligence in Spain's earth observation sector. GMV Aerospace and Defence leverages its flight dynamics heritage to dominate mission control software for national programs. SATLANTIS anchors the commercial smallsat segment through compact optical payloads designed for Mediterranean agricultural coverage. Hisdesat competes in radar services with government-backed maritime surveillance contracts.
Satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial data captured by orbiting platforms carrying optical, synthetic aperture radar, or hyperspectral sensors operating at altitudes typically between 400 and 800 kilometers, with spatial resolutions ranging from sub-meter to tens of meters depending on payload configuration. Its primary commercial purpose centers on delivering actionable intelligence for resource management, infrastructure planning, and environmental compliance verification. Optical satellites lead current Spanish procurement volumes due to maturity in agricultural and urban applications, while hyperspectral platforms represent the fastest-growing category as precision viticulture and carbon sequestration monitoring expand in Castilla-La Mancha and La Rioja. Government agencies remain the dominant end-user channel, though commercial enterprises are capturing margin pools through vertically integrated analytics offerings that bypass traditional institutional procurement cycles.
Spain's national space strategy aligns with ESA funding commitments and EU Green Deal implementation frameworks, directing public procurement toward climate resilience and drought monitoring capabilities. The Spanish Ministry of Science and Innovation coordinates with CDTI to set domestic payload standards and prioritize national industry participation in Copernicus downstream services. Stakeholders must monitor how forthcoming EU space program budgets and Spain's aerospace technology consolidation agenda redistribute contract opportunities between established defense primes and emerging NewSpace ventures.
Market Dynamics
The EU Green Deal is redirecting Spanish public procurement toward climate monitoring infrastructure while subscription analytics decouple raw imagery from value-added intelligence, restructuring how government agencies and agricultural cooperatives purchase earth observation services.
Growth Catalysts
- EU Green Deal implementation:The framework mandates enhanced environmental monitoring across member states, channeling public funds into drought surveillance and carbon sequestration verification systems for Spanish agricultural regions.
- Precision viticulture expansion:Wineries in La Rioja and Castilla-La Mancha are commissioning hyperspectral crop health assessments to optimize irrigation and harvest timing.
- Copernicus downstream services:Spain's national recovery plans prioritize domestic industry participation in EU earth observation programs, accelerating payload development contracts for local aerospace suppliers.
Market Restraints
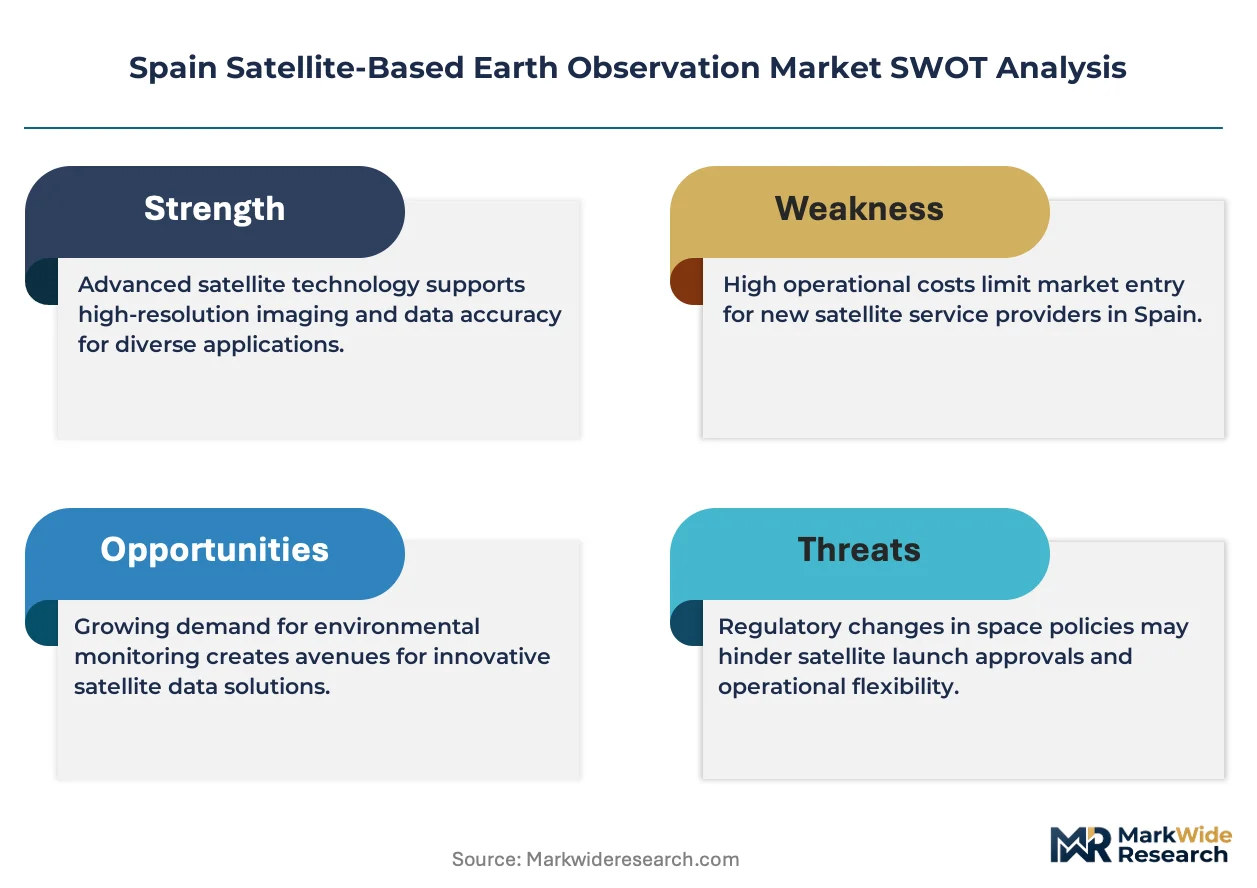
- Launch cost volatility:Dependence on foreign heavy-lift providers exposes Spanish smallsat operators to schedule disruptions and pricing fluctuations in rideshare markets.
- Optical sensor limitations:Cloud cover persistence over northern Spain degrades image acquisition reliability, forcing supplementary radar investments that inflate program budgets.
- REACH compliance burdens:European chemical regulations restrict certain thermal management materials in satellite component manufacturing, extending qualification timelines for new payload designs.
Strategic Opportunities
- Andalusian irrigation modernization:The region's water-stressed agricultural belt presents concentrated demand for evapotranspiration monitoring and leakage detection services.
- Maritime surveillance mandates:Hisdesat's government-backed radar contracts demonstrate replicable models for fisheries enforcement and border monitoring applications.
- AI-ML analytics convergence:Machine learning integration with multispectral data streams is enabling automated yield forecasting that commands premium pricing from agricultural cooperatives.
Industry Challenges
- Flight dynamics expertise scarcity:Mission control software development requires specialized orbital mechanics talent that Spanish universities produce in limited volumes.
- CDTI certification timelines:National payload standards impose extended validation protocols that delay commercial deployment of innovative sensor configurations.
- Legacy ground station integration:New satellite constellations must interface with aging infrastructure in the Madrid-Barcelona corridor, complicating data throughput optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Satellite-Based Earth Observation Market |
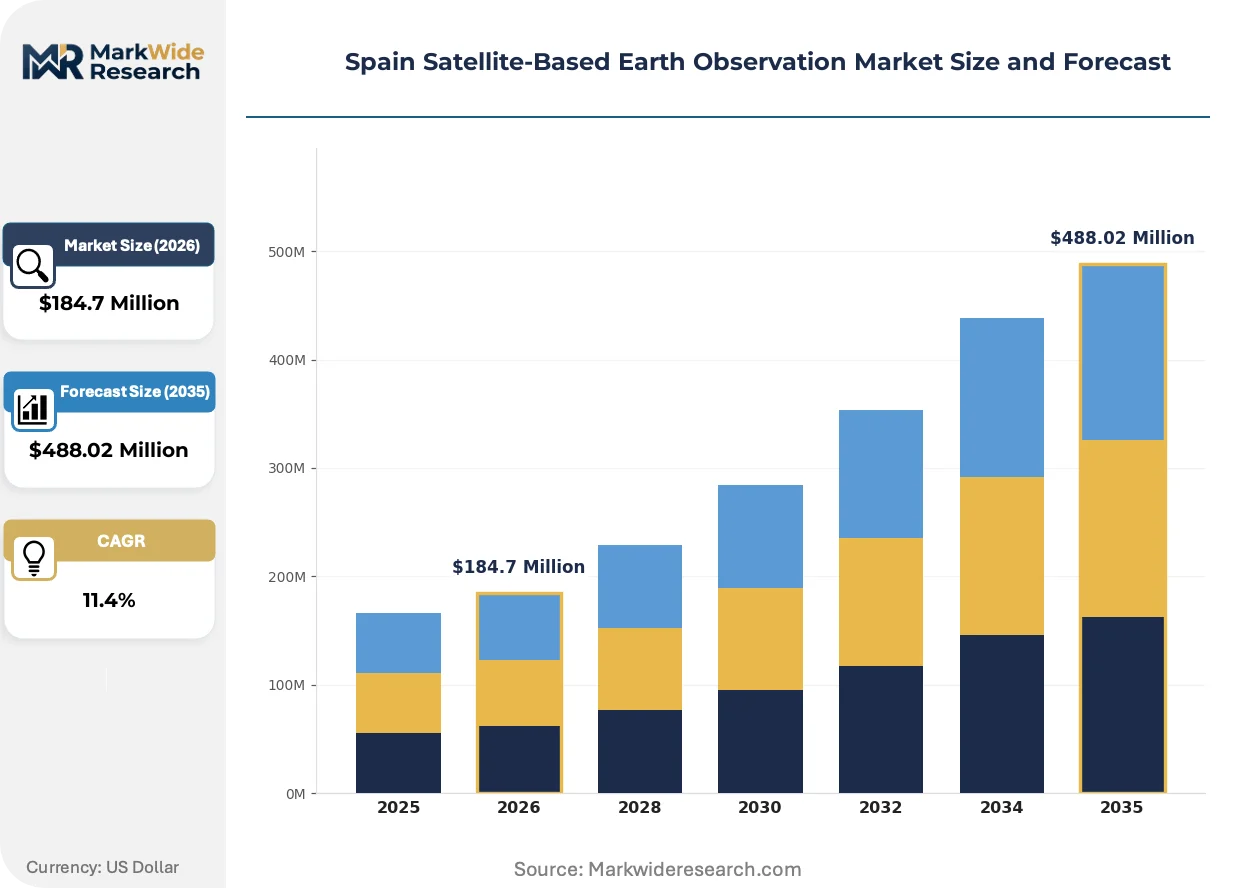
| Market Size in 2026 | $184.7 Million |
| Market Size in 2035 | $488.02 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Multispectral Satellites, Hyperspectral Satellites Application: Agriculture Monitoring, Urban Planning, Disaster Management, Climate Change Monitoring Technology: Remote Sensing, GIS Integration, Data Analytics, Imaging Technology End User: Government Agencies, Research Institutions, Environmental Organizations, Commercial Enterprises |
| Companies Covered | Indra Sistemas S.A., GMV Aerospace and Defence, Deimos Space, Hisdesat, SATLANTIS, Alén Space, Open Cosmos Ltd, Thales Alenia Space España, Airbus Defence and Space, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Satellite-Based Earth Observation Market Trends and Innovations
Spanish earth observation is pivoting from institutional procurement cycles toward vertically integrated service models, with analytics platforms absorbing functions previously performed by government technical teams.
Onboard edge computing architectures are automating image preprocessing and feature extraction before downlink, reducing bandwidth requirements and enabling real-time anomaly detection for agricultural monitoring. Cooperatives in Andalusia are deploying these capabilities for immediate irrigation adjustment recommendations. The technology is automating decision workflows that previously required days of manual analyst review.
The EU Green Deal's monitoring mandates are tightening data quality standards for climate verification services, forcing providers to demonstrate traceable calibration chains and uncertainty quantification. Spanish operators must now document sensor drift corrections and atmospheric compensation methodologies to qualify for public contracts. Agricultural applications face the steepest compliance adjustments as carbon credit certification demands rigorous measurement protocols.
Cooperatives are consolidating purchasing power through shared service platforms that aggregate demand across multiple farming operations. These platforms displace individual farm-level satellite imagery subscriptions with pooled analytics licenses negotiated at volume discounts. The Madrid-Barcelona corridor hosts the dominant procurement intermediaries, though Andalusian agricultural associations are building competing collective bargaining structures.
Spain Satellite-Based Earth Observation Market Segmentation
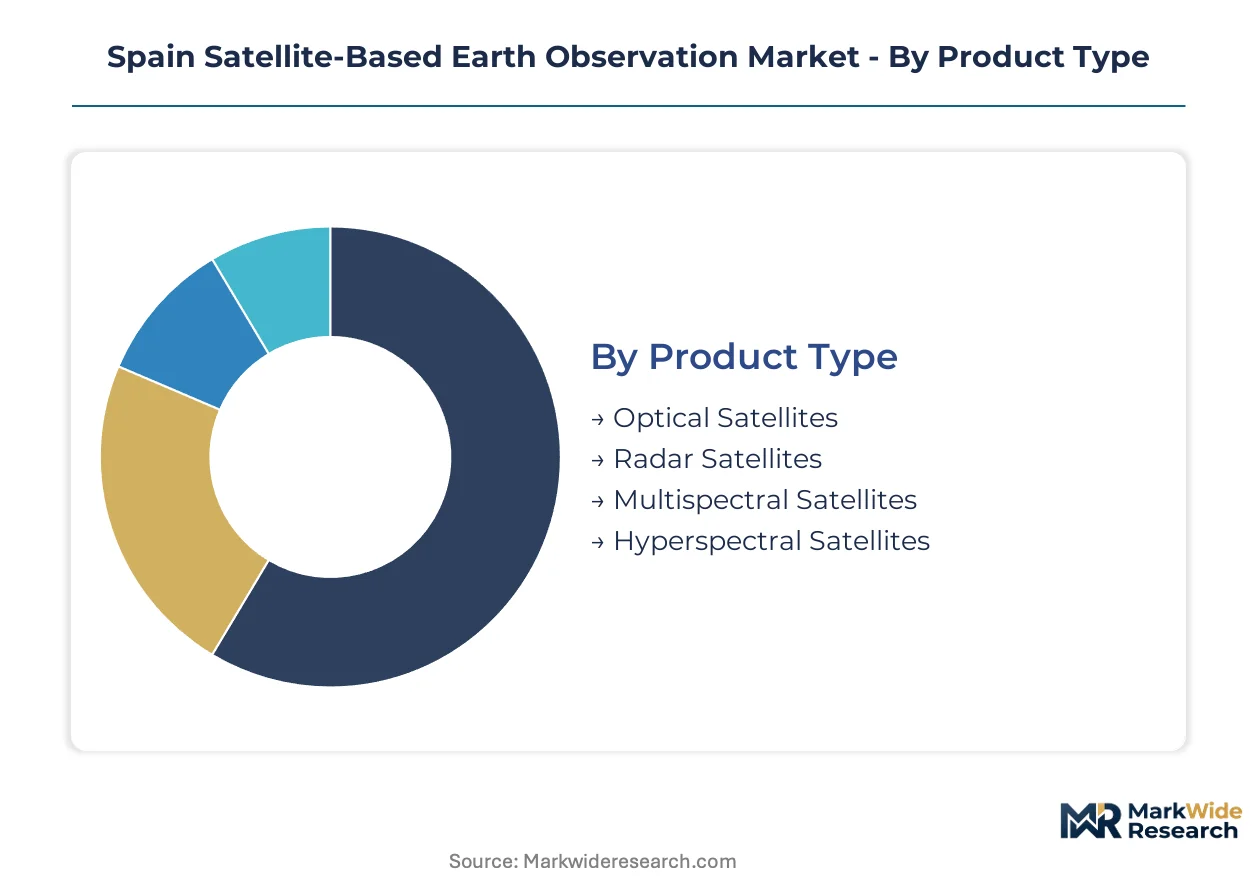
Earth observation procurement in Spain fragments across sensor technologies, application domains, and institutional buyer types. Understanding these divisions reveals where public recovery funds concentrate and where commercial service models displace traditional government procurement.
Product Type:
Capital intensity varies sharply across sensor platforms, with radar constellations demanding the heaviest upfront investment in power systems and antenna arrays.
- Optical Satellites:These platforms capture visible and near-infrared imagery using silicon-based detector arrays at spatial resolutions from sub-meter to 10 meters. Spanish agricultural cooperatives in Andalusia drive procurement volumes for crop health monitoring, though cloud cover persistence over northern provinces degrades acquisition reliability and forces costly rescheduling.
- Hyperspectral Satellites:Instruments with 100+ narrow spectral bands enable material identification through unique spectral signatures. Precision viticulture operations in La Rioja and Castilla-La Mancha commission these services for irrigation optimization and harvest timing, with carbon sequestration verification emerging as a secondary revenue stream under EU Green Deal compliance frameworks.
- Radar Satellites:Synthetic aperture radar penetrates cloud cover and operates day-night, requiring heavier power infrastructure and larger deployable antennas than optical alternatives.
- Multispectral Satellites:Four to ten spectral bands balance cost against analytical utility for broad-acre agricultural coverage.
Most installed capacity flows through optical platforms. Expansion is steepest in hyperspectral configurations.
Application:
Demand concentration tracks Spain's geographic vulnerabilities and EU funding priorities, with climate-linked applications capturing the steepest budget allocations.
- Agriculture Monitoring:Multispectral and hyperspectral data streams support irrigation scheduling, yield forecasting, and pest pressure mapping across Spain's water-stressed growing regions. Andalusian cooperatives aggregate purchasing power through shared service platforms that displace individual farm subscriptions with pooled analytics licenses.
- Climate Change Monitoring:Drought surveillance, carbon sequestration verification, and ecosystem health assessment command premium pricing under EU Green Deal implementation. Spanish operators must document sensor drift corrections and atmospheric compensation methodologies to qualify for public contracts in this category.
- Urban Planning:High-resolution optical imagery supports infrastructure development and land use compliance in the Madrid-Barcelona corridor.
- Disaster Management:Rapid response capabilities for wildfire mapping and flood assessment rely on integrated radar-optical constellations.
Public procurement concentrates in climate monitoring. Agricultural cooperatives are expanding their share fastest.
Technology:
Margin capture shifts upstream from raw imagery toward analytics layers that automate interpretation previously performed by government technical teams.
- Data Analytics:Machine learning integration with multispectral streams enables automated yield forecasting and anomaly detection. Spanish platforms are absorbing functions previously performed by CDTI technical teams, with vertically integrated offerings commanding premium pricing from agricultural cooperatives.
- Remote Sensing:Core acquisition capabilities spanning optical, radar, and hyperspectral modalities form the foundational infrastructure layer.
- GIS Integration:Spatial data fusion with cadastral and hydrological datasets supports precision agriculture and infrastructure planning workflows.
- Imaging Technology:Sensor calibration chains and onboard processing architectures determine data quality for certification-eligible applications.
Analytics layers are capturing margin pools fastest. Remote sensing infrastructure maintains the largest installed base.
End User:
Procurement authority is fragmenting as commercial intermediaries aggregate demand from smaller agricultural operators previously served through direct government programs.
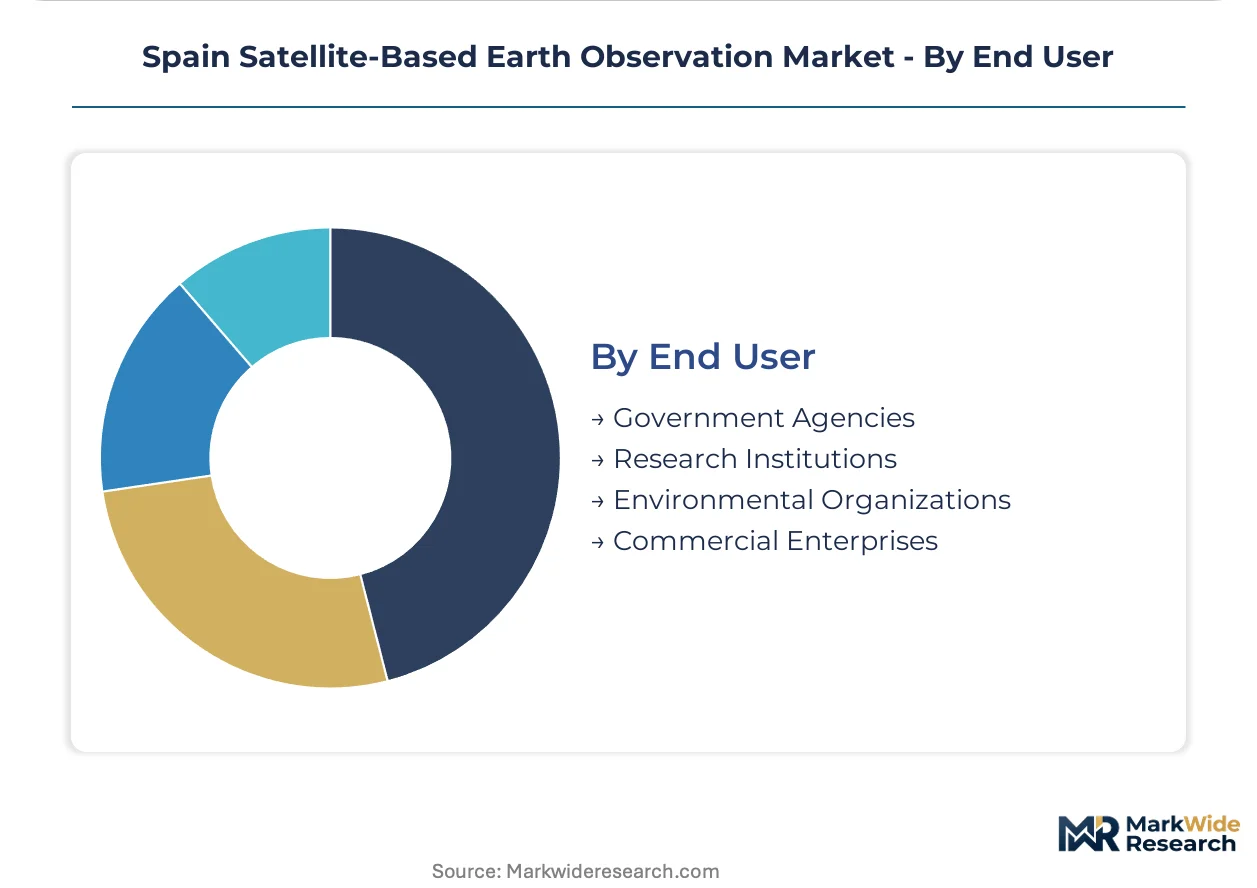
- Government Agencies:The Spanish Ministry of Science and Innovation and CDTI coordinate national payload standards and prioritize domestic industry participation in Copernicus downstream services. These institutions dominate capital-intensive radar constellation procurement and climate verification service contracts.
- Commercial Enterprises:Agricultural cooperatives and analytics platforms are capturing margin pools through vertically integrated offerings that bypass traditional institutional procurement cycles. Madrid-Barcelona corridor intermediaries dominate this channel, though Andalusian associations are building competing collective bargaining structures.
- Research Institutions:Universities and technical centers validate sensor performance and develop retrieval algorithms for agricultural and environmental applications.
- Environmental Organizations:Non-governmental monitoring programs leverage subsidized Copernicus data streams for conservation and advocacy purposes.
Government agencies deploy the largest procurement budgets. Commercial enterprises are gaining share fastest through cooperative purchasing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany channels more public procurement into radar constellation development than Spain directs toward optical platforms, while France maintains tighter vertical integration between satellite manufacturing and downstream analytics services.
Andalusia
Water-stressed agricultural belts in Córdoba and Seville drive concentrated demand for evapotranspiration monitoring and irrigation leakage detection. The EU Green Deal's drought surveillance mandates channel CDTI recovery funds toward precision farming infrastructure. The Guadalquivir Valley hosts cooperative purchasing platforms that aggregate multispectral service contracts across olive and citrus operations.
Madrid
National payload standards and Copernicus downstream coordination concentrate government procurement authority in the capital region. The Spanish Ministry of Science and Innovation directs climate verification service contracts toward domestic aerospace suppliers. The Madrid-Barcelona aerospace corridor anchors mission control software development and legacy ground station integration challenges.
Catalonia
Barcelona's technology cluster supports analytics platform development that decouples raw imagery from value-added intelligence. REACH compliance requirements for thermal management materials extend qualification timelines for payload components manufactured in the region. The Barcelona metropolitan area hosts procurement intermediaries serving agricultural cooperatives across the Ebro basin.
Basque Country
Maritime surveillance mandates from the EU Integrated Maritime Policy drive radar service procurement for fisheries enforcement in the Bay of Biscay. Hisdesat's government-backed contracts demonstrate replicable models for border monitoring applications. Bilbao and San Sebastián anchor specialized sensor development for all-weather ocean observation.
Spain Satellite-Based Earth Observation Market Competitive Landscape
Top-tier vendors anchor national program mission control software, while mid-tier specialists concentrate on compact optical payloads and regional analytics platforms. The vendor base stratifies across defense primes with flight dynamics heritage, commercial smallsat operators, and vertically integrated agricultural service providers. Two strategic archetypes dominate: established aerospace contractors leveraging institutional relationships, and NewSpace ventures capturing cooperative purchasing channels. Competitive moves center on strategic partnerships for ground segment access and portfolio diversification into AI-ML analytics layers.
Within the national program tier, GMV Aerospace and Defence and Hisdesat occupy positions reflecting long-standing institutional relationships with CDTI and defense ministries. SATLANTIS represents the commercial smallsat archetype, while Deimos Space exemplifies vertically integrated analytics capabilities. These three entities anchor distinct competitive vectors without overlapping core specializations.
| Leading Market Players |
|---|
| Indra Sistemas S.A. |
| GMV Aerospace and Defence |
| Deimos Space |
| Hisdesat |
| SATLANTIS |
| Alén Space |
| Open Cosmos Ltd |
| Thales Alenia Space España |
| Airbus Defence and Space |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon verification mandates are forcing Spanish agricultural cooperatives toward hyperspectral subscription tiers with documented calibration chains, compelling payload suppliers to absorb REACH compliance costs and sensor qualification delays into premium service pricing.
Pricing Analysis
Capacity additions in Andalusia's cooperative purchasing platforms are reshaping price floors for multispectral crop monitoring services. Three-tier pricing structure across premium hyperspectral, standard multispectral, and economy optical tiers dominates procurement, with certification grade and volume scale driving differentiation. Pricing pressure stems from CDTI's extended payload validation timelines that inflate development amortization. Small agricultural cooperatives exhibit highest price sensitivity, while government climate verification contracts tolerate premium positioning.
Supply Chain Analysis
Freight costs for thermal management materials and silicon detector arrays from Germany, France, and the Netherlands compound REACH compliance burdens for Spanish payload manufacturers. Supply draws from concentrated European specialty chemical suppliers and Asian semiconductor foundries. Single-source vulnerability in radiation-hardened component qualification creates program delay risks. Distribution runs through Madrid-Barcelona aerospace corridor intermediaries serving both institutional and cooperative procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's satellite-based earth observation market reads as a late-cycle quality story, with EU Green Deal carbon sequestration verification mandates shifting procurement toward hyperspectral platforms with traceable sensor calibration documentation.
For Market Incumbents: Hedge against NewSpace analytics platforms by deepening backward integration into AI-ML yield forecasting modules that bypass CDTI technical review cycles. Acquire flight dynamics talent from Spanish universities before specialist scarcity worsens mission control software development bottlenecks. For New Entrants and Emerging Players: Agricultural cooperative purchasing intermediaries represent the most penetrable channel for compact optical payload services in Andalusia's water-stressed irrigation districts. Target evapotranspiration monitoring white space through subscription-based leakage detection offerings that aggregate demand across olive and citrus operations. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated analytics platforms combining satellite tasking with automated agricultural decision workflows. Five-to-ten-year viability favors firms capturing cooperative purchasing channel relationships ahead of Madrid-Barcelona corridor consolidation. Watch CDTI budget allocation shifts between established defense primes and emerging ventures as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-ML Analytics Platform Integration | Machine learning convergence with multispectral streams enables automated yield forecasting for Andalusian cooperatives. |
| Hyperspectral Payload Certification Investment | EU Green Deal climate verification contracts demand documented sensor drift correction methodologies from Spanish operators. |
| Cooperative Purchasing Channel Partnership | Shared service platforms in Guadalquivir Valley aggregate demand and displace individual farm subscriptions. |
| Backward Integration into Edge Computing | Onboard preprocessing architectures reduce bandwidth requirements for real-time agricultural anomaly detection. |
| Maritime Surveillance Radar Expansion | Hisdesat's government-backed fisheries enforcement contracts demonstrate replicable models for Basque Country operators. |
Research Methodology
Multiple input streams — primary interviews with satellite mission directors, agricultural cooperative procurement managers, and CDTI program officers; secondary validation through ESA funding disclosures, Copernicus service procurement records, and Spanish Ministry of Science budget allocations — were reconciled through bottom-up payload deployment tallies and top-down public investment tracking.
Data-stream reconciliation across sensor technology segments, application domains from precision viticulture to maritime surveillance, and end-user procurement channels generated volume and value outputs throughout the forecast period. CAGRs were derived from public recovery fund allocation trajectories and cooperative subscription growth patterns, with segmentation modeling incorporating optical-radar-hyperspectral platform splits and government-commercial end-user dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU space program budget revisions, launch cost volatility in rideshare markets, and CDTI certification timeline fluctuations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
LEO and GEO Satellite Market
Satellite
Satellite Operation Service Market
Satellite
North America Satellite Bus Market
Satellite
North America Military Satellite Market
Satellite
Satellite Internet Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
UAE Satellite Imagery Services Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Medium and Large Satellite Market
Satellite
China Satellite Imagery Services Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Russia Satellite Imagery Services Market
Satellite
North America Remote Sensing Services Market