
 Intelligence Surveillance and Reconnaissance (ISR) Market | 2026-2036
Intelligence Surveillance and Reconnaissance (ISR) Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligence Surveillance and Reconnaissance (ISR) Market Insights
ITAR reform is broadening the cost-of-entry calculus for foreign subsystem suppliers seeking access to US defense supply chains. Lockheed Martin leverages captive production of advanced electro-optical turrets to sustain margin pools in manned-unmanned teaming programs. Northrop Grumman dominates space-based radar constellations, while Elbit Systems specializes in tactical unmanned systems for contested electromagnetic environments.
Intelligence Surveillance and Reconnaissance denotes the integrated process of collecting, processing, and disseminating timely, accurate, and relevant information through airborne, space-based, and ground sensor platforms operating across infrared, radar, and signals intelligence spectra to support decision superiority in contested operational environments. Military Operations applications anchor current procurement volumes, though Maritime Surveillance is accelerating fastest as Indo-Pacific navies prioritize undersea domain awareness. Data Fusion technology occupies the highest-margin tier within the technology stack, where real-time correlation of multi-source intelligence creates vendor stickiness through proprietary algorithmic architectures.
The US Department of Defense, NATO Standardization Office, and EU AI Act compliance frameworks collectively shape platform interoperability mandates, export licensing thresholds, and autonomous engagement protocols for unmanned ISR systems. FAA integration standards for beyond-visual-line-of-sight unmanned aircraft operations further constrain domestic airspace deployment timelines for commercial-adjacent ISR services. Stakeholders must monitor evolving classification boundaries between defensive ISR and offensive strike-enabling capabilities, as this distinction increasingly determines which regulatory gate governs foreign sales eligibility and technology transfer permissions.
Market Dynamics
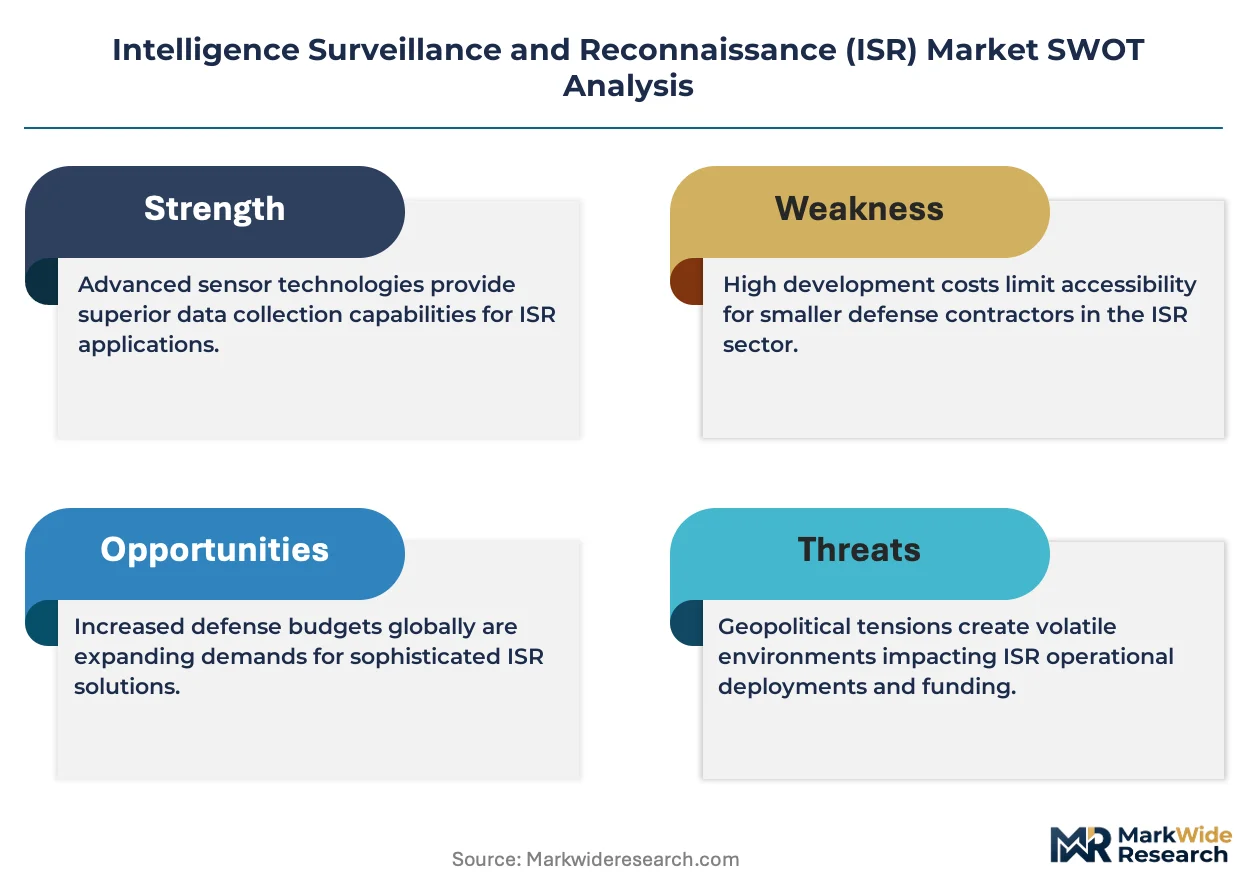
The transition from platform-centric to distributed sensing architectures is compressing procurement timelines and fragmenting vendor hierarchies across NATO defense establishments. Pentagon budget reallocations toward autonomous systems are forcing traditional prime contractors to absorb AI-enabled subsystem suppliers or cede tier-one positioning.
Growth Catalysts
- EU AI Act compliance mandates:Certification requirements for autonomous ISR platforms are accelerating procurement of pre-integrated sensor-fusion systems that embed explainable AI by design.
- Indo-Pacific maritime patrol expansion:Undersea domain awareness programs across Australia, Japan, and South Korea are generating demand for multi-static sonar networks and persistent airborne surface surveillance.
- Synthetic aperture radar miniaturization:Reduced size-weight-power constraints are enabling tactical unmanned platforms to carry previously satellite-reserved imaging capabilities.
Market Restraints
- Gallium nitride foundry concentration:Advanced radar transmitter supply chains cluster in US and Japanese semiconductor facilities, creating single-source vulnerability for European platform integrators.
- ITAR classification creep:US State Department reclassification of electro-optical stabilization algorithms as munition-list items is blocking technology transfer to allied co-development programs.
- Lithium-sulfur battery immaturity:Energy density limitations in next-generation unmanned platforms are extending development timelines for endurance-critical missions.
Strategic Opportunities
- Poland and Baltic states:NATO eastern flank nations are building indigenous ISR industrial bases through offset agreements that mandate local subsystem production.
- Commercial space radar convergence:Synthetic aperture radar operators are repurposing maritime surveillance constellations for defense tipping-and-cueing contracts.
- FAA beyond-visual-line-of-sight rulemaking:Proposed domestic airspace integration standards will unlock commercial-adjacent ISR services for infrastructure and environmental monitoring.
Industry Challenges
- AI/ML systems engineering talent:Defense contractors face acute shortages of cleared personnel capable of training edge-deployed target recognition models.
- Multi-level security architecture integration:Fielding systems that simultaneously handle unclassified commercial imagery and compartmented signals intelligence requires complex cross-domain solution development.
- Legacy platform software certification:Updating 1980s-era airborne mission computers to host modern sensor management applications demands expensive airworthiness requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligence Surveillance and Reconnaissance (ISR) Market |
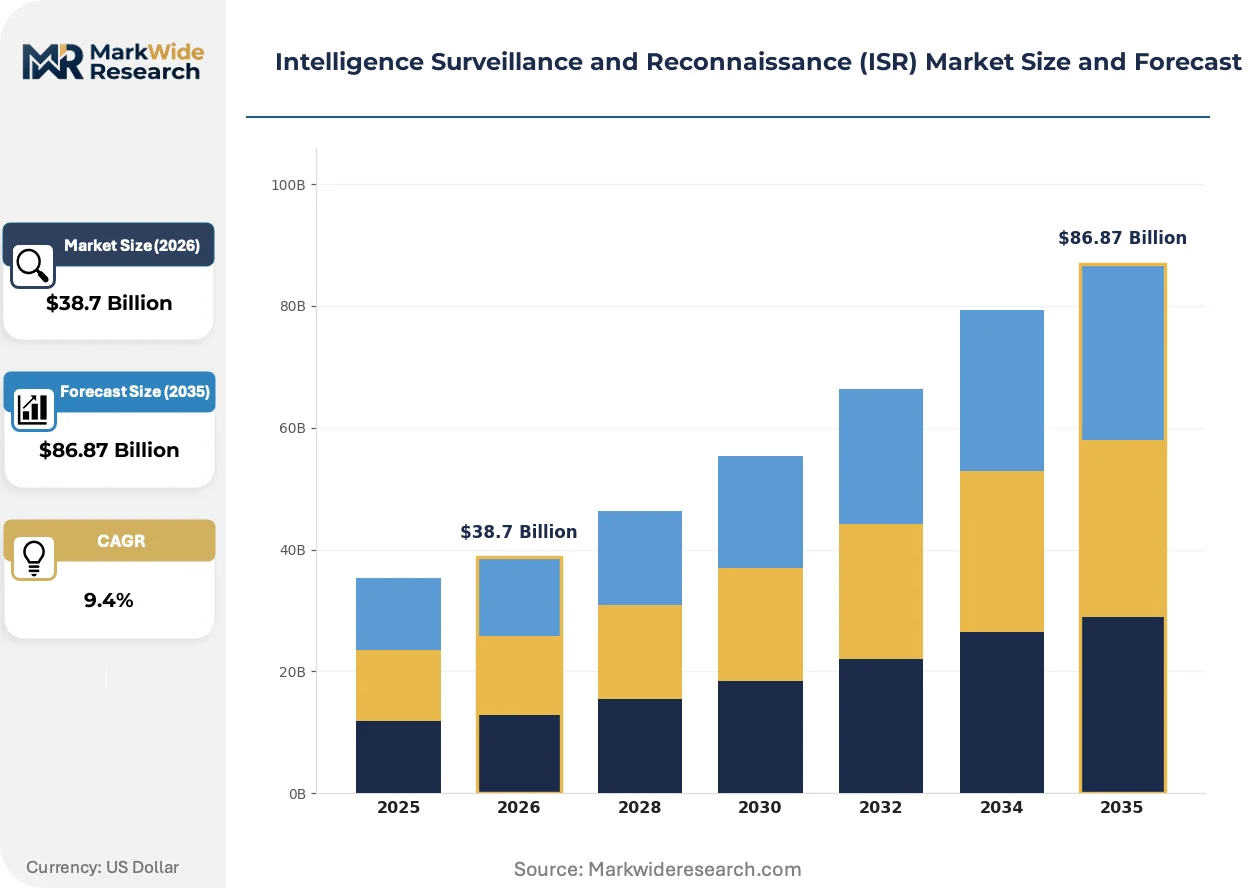
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Military Operations, Border Security, Maritime Surveillance, Disaster Management Technology: Electro-Optical Systems, Radar Systems, Acoustic Sensors, Data Fusion End User: Defense Agencies, Intelligence Services, Security Firms, Government Institutions Deployment: On-Premise, Cloud-Based, Hybrid Models, Edge Computing |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, RTX Corporation, L3Harris Technologies, Inc., BAE Systems PLC, General Dynamics Corporation, Elbit Systems Ltd., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligence Surveillance and Reconnaissance (ISR) Market Trends and Innovations
Active electronically scanned array technology is migrating from manned platforms to tactical unmanned systems, compressing the performance gap between crewed and autonomous assets. Regulatory frameworks for autonomous engagement are simultaneously enabling and constraining deployment velocity.
Conformal antenna arrays are electrifying airframe design paradigms by embedding radar apertures into wing structures rather than external pods. Defense primes in the United States and Israel are retrofitting existing unmanned platforms with these low-drag configurations to recover payload capacity for extended missions. This integration is electrifying competition between structural composite suppliers and traditional radar houses for airframe-level contracting authority.
The EU AI Act's risk-based classification system is imposing conformity assessment requirements on unmanned ISR platforms operating in populated areas. European platform developers must now document algorithmic decision pathways for autonomous navigation systems prior to member state deployment authorization. Maritime surveillance programs in the Mediterranean and Baltic regions are most affected, with several national procurement offices delaying contract awards pending harmonized certification guidance from the European Defence Agency.
Allied defense ministries are consolidating sensor procurement through framework agreements that specify open architecture standards and data format interoperability. Traditional prime contractors face disintermediation as subsystem suppliers gain direct contracting relationships with national acquisition offices. This pattern is most visible in the United Kingdom and Netherlands, where defense material organizations now issue separate tenders for airframes, payloads, and ground control segments.
Intelligence Surveillance and Reconnaissance (ISR) Market Segmentation
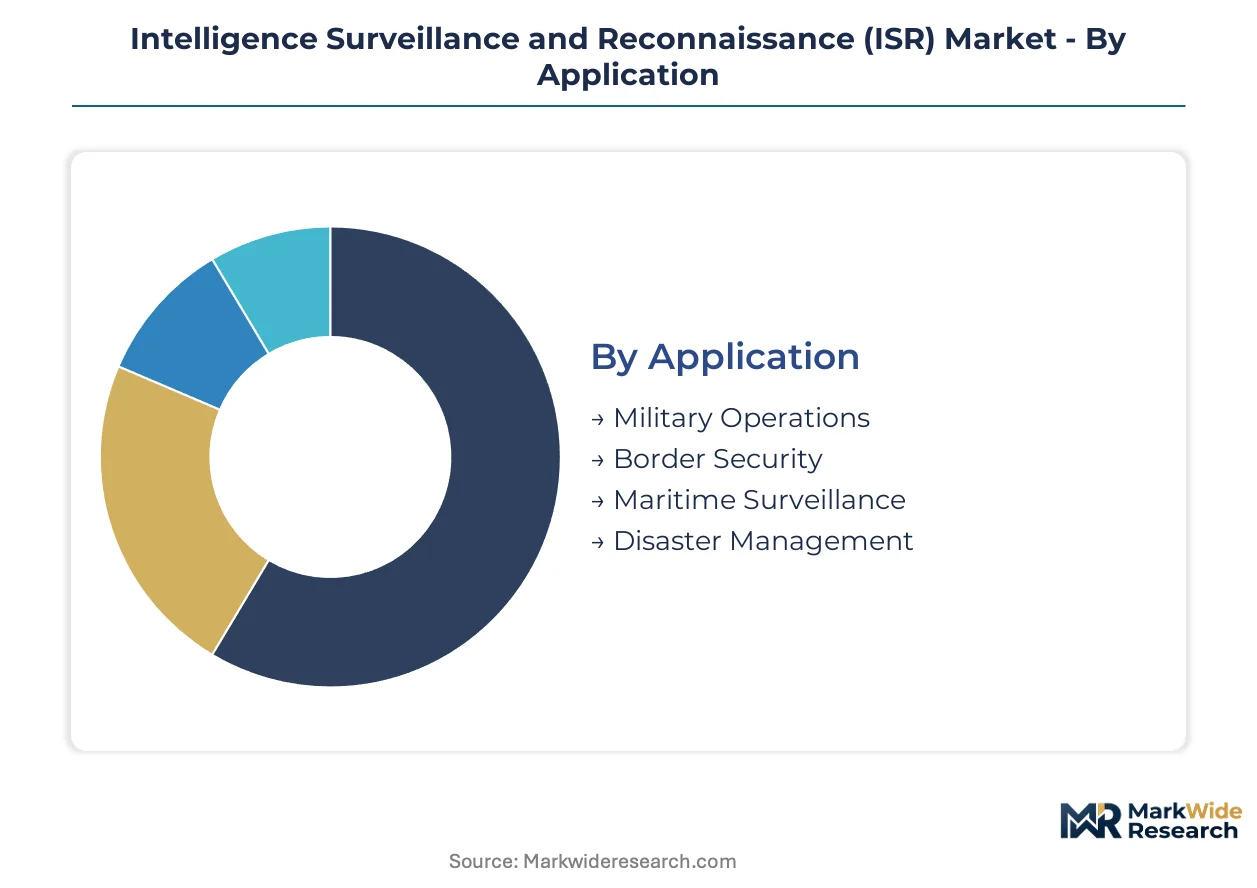
ISR procurement patterns diverge sharply across operational contexts, with platform specifications and data handling architectures varying by mission criticality and electromagnetic threat environment. Segmentation reveals where vendor specialization creates defensible margin pools versus commodity competition.
Application:
Legacy platform replacement cycles and emerging threat geometries are redistributing procurement volumes across operational domains, with some segments demanding entirely new sensor modalities.
- Military Operations:Crewed and uncrewed platforms integrate multi-spectral turrets for real-time targeting and battle damage assessment. Pentagon spending on distributed sensing architectures and NATO eastern flank modernization programs anchor procurement volumes here.
- Maritime Surveillance:Persistent airborne surface surveillance and undersea domain awareness programs across Australia, Japan, and South Korea drive demand for multi-static sonar networks and synthetic aperture radar miniaturization. Indo-Pacific navies prioritize this segment fastest.
- Border Security:Ground-based radar and electro-optical towers monitor territorial boundaries with automated anomaly detection.
- Disaster Management:Rapidly deployable unmanned platforms assess infrastructure damage and coordinate emergency response.
Volume placements concentrate in Military Operations; the faster expansion belongs to Maritime Surveillance.
Technology:
Cost tiers separate proprietary algorithmic architectures from commodity sensor hardware, with integration complexity determining vendor stickiness.
- Data Fusion:Real-time correlation of multi-source intelligence through proprietary algorithmic architectures creates the highest-margin tier. Defense primes defend positioning through classified processing pipelines and cross-domain security certifications.
- Electro-Optical Systems:Stabilized turrets combining infrared, visible, and laser designator channels dominate tactical unmanned platforms. ITAR reclassification of stabilization algorithms as munition-list items constrains allied technology transfer.
- Radar Systems:Active electronically scanned arrays migrate from manned platforms to tactical unmanned systems, compressing performance gaps.
- Acoustic Sensors:Passive and active sonar arrays enable undersea domain awareness for submarine detection and seabed infrastructure monitoring.
Margin capture concentrates in Data Fusion; steepest expansion trajectory belongs to Electro-Optical Systems as unmanned platform proliferation accelerates.
End User:
Customer type dictates security clearance requirements, funding stability, and procurement timeline predictability.
- Defense Agencies:National military establishments issue multi-year platform contracts with stringent interoperability mandates. Pentagon budget allocations and NATO framework agreements sustain the largest procurement volumes.
- Intelligence Services:Signals intelligence and imagery analysis agencies demand compartmented processing architectures with specialized cross-domain solutions. Multi-level security integration requirements limit vendor pools.
- Security Firms:Private contractors supply perimeter monitoring and facility protection with commercial-grade sensor packages.
- Government Institutions:Civilian agencies deploy environmental monitoring and infrastructure inspection capabilities under FAA beyond-visual-line-of-sight constraints.
Contract value concentrates with Defense Agencies; Intelligence Services show the most rapid capability expansion.
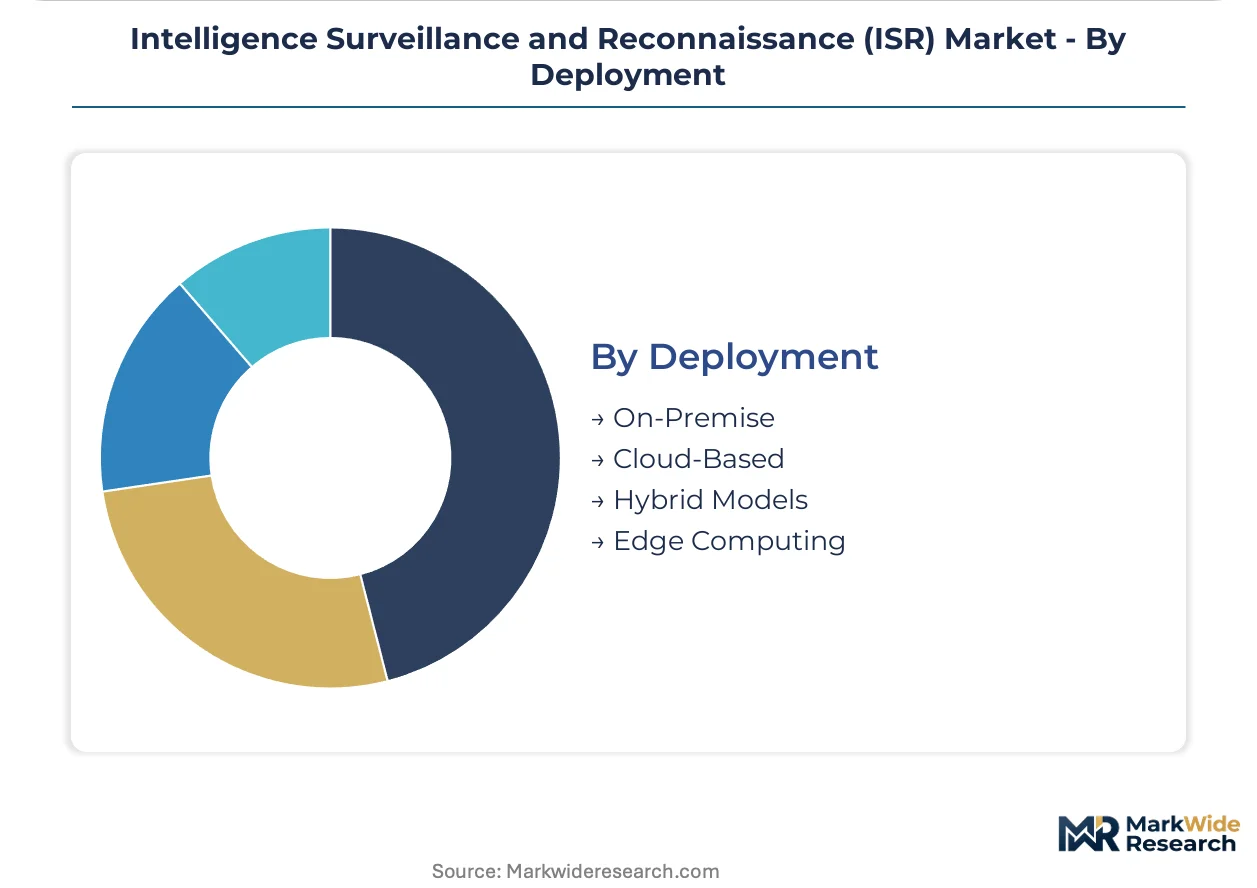
Deployment:
Maturity gradients separate field-proven on-premise architectures from emerging edge-computing configurations with unproven security postures.
- On-Premise:Classified processing within hardened facilities remains mandatory for compartmented signals intelligence. Legacy mission computer architectures and airworthiness requalification burdens slow modernization.
- Edge Computing:Real-time target recognition on platform-embedded processors reduces bandwidth requirements and decision latency. EU AI Act conformity assessments for autonomous navigation algorithms constrain European deployment velocity.
- Cloud-Based:Unclassified imagery archives and training data pipelines migrate to commercial infrastructure with FedRAMP or equivalent certifications.
- Hybrid Models:Tiered processing splits raw collection at the edge, feature extraction in theater, and exploitation in continental processing centers.
Operational reliance concentrates in On-Premise; Edge Computing gains share fastest as autonomous engagement protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense innovation zones in the United States concentrate prime contractor headquarters and classified R&D facilities. Israel's military-industrial complex leverages combat-proven technology transfer. European sovereignty initiatives fragment procurement across national industrial bases.
United States
Pentagon distributed sensing architectures and NATO eastern flank modernization programs drive procurement volumes. FAA beyond-visual-line-of-sight rulemaking shapes domestic airspace integration timelines. The Virginia-classified facility corridor hosts electro-optical turret production for manned-unmanned teaming programs.
Israel
Contested electromagnetic environment expertise and tactical unmanned system specialization anchor export competitiveness. Israeli Ministry of Defense procurement mandates prioritize indigenous sensor-fusion development. Haifa's defense technology cluster concentrates electro-optical stabilization algorithm research.
United Kingdom
Defense Material Organization framework agreements disaggregate prime contractor roles across airframe, payload, and ground control segments. UK Strategic Command open architecture mandates accelerate subsystem supplier direct contracting. Farnborough's aerospace corridor hosts multi-level security architecture integration facilities.
Germany
Bundeswehr maritime patrol modernization and Baltic Sea undersea domain awareness programs expand acoustic sensor demand. German Aerospace Center certification requirements constrain autonomous navigation system deployment. Bavaria's sensor house cluster specializes in conformal antenna array integration for unmanned platforms.
Australia
AUKUS submarine technology sharing and Indo-Pacific maritime surveillance expansion drive multi-static sonar network procurement. Australian Defence Force sovereign industrial capability priorities mandate local subsystem production. Adelaide's defense technology precinct hosts persistent airborne surface surveillance platform integration.
Intelligence Surveillance and Reconnaissance (ISR) Market Competitive Landscape
United States producers anchor the prime contractor tier; Israeli specialists hold tactical unmanned system positioning. Market structure concentrates around five dominant defense primes with captive subsystem production. Three archetypes prevail: vertically integrated platform houses, sensor-fusion software specialists, and sovereign-industrial-base champions. Competitive moves center on AI-enabled subsystem acquisition and classified processing pipeline certification.
Within the prime contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform-integration dominance through captive electro-optical and space-based radar capabilities. Elbit Systems Ltd. represents the specialist archetype with tactical unmanned positioning in contested electromagnetic environments. Thales Group anchors European sovereign-industrial-base competition through multi-domestic production footprints and EU AI Act compliance integration.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| RTX Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems PLC |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Pentagon distributed sensing architecture mandates compressing procurement timelines are forcing subsystem suppliers to absorb inventory risk and accelerate qualification cycles, which concentrates pricing power with prime contractors holding captive electro-optical and radar production.
Pricing Analysis
Short-lead-time premiums dominate contract negotiations as NATO eastern flank modernization programs demand rapid fielding timelines. Three-tier pricing structure across ITAR-restricted, NATO-releasable, and commercial-grade certification levels separates vendor pools. Cost compression in electro-optical turret supply chains stems from gallium nitride foundry concentration. Intelligence Services exhibit lowest price sensitivity due to compartmented processing requirements; Security Firms face acute margin pressure from commercial-grade commoditization.
Supply Chain Analysis
ITAR and EU AI Act qualification gating restricts electro-optical stabilization algorithm sourcing to US and Israeli semiconductor facilities. Raw material dependencies center on gallium nitride substrates, lithium-sulfur battery cells, and synthetic aperture radar components. Single-source vulnerability in advanced radar transmitter supply chains creates procurement risk. Distribution runs through defense material organizations issuing framework agreements for airframe, payload, and ground control segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ISR market has become a vertical-integration race as prime contractors absorb AI-enabled subsystem suppliers to defend tier-one positioning against disintermediation by national acquisition offices.
For Market Incumbents: Anticipate disintermediation pressure from UK and Netherlands defense material organizations fragmenting prime contractor roles across airframe, payload, and ground control segments. Absorb sensor-fusion software specialists to preserve margin capture in data fusion architectures. Invest in cross-domain security certifications to maintain vendor stickiness with Intelligence Services procurement. For New Entrants and Emerging Players: Begin with Poland and Baltic states offset agreements mandating local subsystem production as the most penetrable entry vector. Target maritime surveillance applications where Indo-Pacific navies prioritize undersea domain awareness and multi-static sonar networks. Pursue direct contracting relationships with national acquisition offices through open architecture standard compliance. For Investors and Strategic Acquirers: The window for entry favors sensor-fusion software specialists with classified processing pipeline certifications and proprietary algorithmic architectures. Long-term viability hinges on positioning within autonomous engagement protocol development as regulatory frameworks mature. Watch for FAA beyond-visual-line-of-sight rulemaking finalization as inflection indicator for commercial-adjacent ISR service expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI-Enabled Subsystem Supplier | Captures explainable AI certification pathways required under EU AI Act compliance mandates. |
| Cross-Domain Security Certification Investment | Unlocks Intelligence Services procurement with compartmented signals intelligence handling requirements. |
| Conformal Antenna Array Integration Partnership | Recovers payload capacity for extended missions through low-drag radar aperture embedding. |
| Offset Agreement Localization in NATO Eastern Flank | Secures framework contract access through Poland and Baltic states indigenous production mandates. |
| Synthetic Aperture Radar Miniaturization Scale-Up | Enables tactical unmanned platforms to carry previously satellite-reserved imaging capabilities. |
Research Methodology
Independent corroboration across defense procurement officers, sensor-fusion software engineers, and cross-domain security architects underwrites the qualitative findings. Primary interviews with program managers at national acquisition offices, subsystem supplier technical directors, and Intelligence Services capability development leads combined with secondary validation from Pentagon budget documentation, NATO standardization office publications, and EU AI Act implementation guidance. Bottom-up platform deployment modeling and top-down defense expenditure allocation triangulation anchored volume estimates.
Rate-of-change decomposition across the analysis window separates platform replacement cycles from autonomous system procurement acceleration. Segmentation dimensions modeled include application domain, technology tier, end-user security clearance level, and deployment architecture maturity. CAGRs derived from correlated defense budget trajectory analysis and vendor revenue attribution across multi-year framework agreements. Industry-specific forecast inputs incorporate ITAR classification threshold adjustments and FAA beyond-visual-line-of-sight rulemaking progression.
ITAR reclassification events, EU AI Act certification timeline delays, and lithium-sulfur battery technology maturation setbacks are the dominant revision risks. Forecasts reflect documented assumptions regarding defense budget continuity and allied interoperability mandate adherence. A model refresh is warranted upon material change in Pentagon distributed sensing architecture procurement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Japan C4ISR Market
ISR
North America C5ISR Market
ISR
Naval ISR Market
ISR
C6ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Brazil C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Land Based C4ISR Market
ISR
Europe C5ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Airborne ISR Market
ISR
Infrared Suppression Systems Market
ISR
Low Altitude Radar Market
ISR
United States C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Australia C4ISR Market