
 Australia C4ISR Market | 2026-2036
Australia C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Australia C4ISR Market Outlook
Network-centric warfare capability standards are bifurcating the competitive landscape between legacy platform integrators and next-generation software-defined providers. BAE Systems PLC leverages its Adelaide-based maritime systems hub to anchor sovereign build requirements under AUKUS. Lockheed Martin Corporation sustains long-term positioning through the Joint Air Battle Management System program. Thales Group differentiates via its Bushmaster and Hawkei protected mobility vehicle electronics suites.
C4ISR denotes the integrated architecture of Command, Control, Communications, Computers, Intelligence, Surveillance and Reconnaissance systems enabling real-time battlespace decision-making across joint force operations. These systems fuse sensor data through standardized data links, processing protocols, and human-machine interfaces to compress the observe-orient-decide-act loop from hours to minutes. Satellite Communications within the Technology dimension dominates current procurement outlays given Australia's vast maritime approaches and Indo-Pacific operational requirements. Intelligence Gathering applications represent the fastest-expanding segment as autonomous platforms and signals intelligence modernization multiply collection nodes. Military Organizations anchor the End User base, though Defense Contractors are absorbing expanded sustainment and integration responsibilities under Australia's enhanced sovereign industry agenda.
Defence Australia and the Capability Acquisition and Sustainment Group shape market access through sovereign industrial capability priorities and AUKUS technology transfer frameworks. The Defence Trade Controls Act and associated export permit requirements constrain foreign supplier participation without domestic partnership structures. Stakeholders must monitor how classified technology release protocols evolve under trilateral security arrangements and whether local content thresholds tighten beyond current guided weapons and explosive ordnance enterprise plans.
Market Dynamics
AUKUS technology transfer protocols and sovereign industrial capability mandates are restructuring supplier relationships, forcing foreign primes into domestic partnership architectures that reshape competitive access across naval, aerospace, and land systems domains.
Growth Catalysts
- Defence Strategic Review implementation:The review's force posture realignment redirects investment toward integrated joint capabilities, expanding C4ISR procurement envelopes across all three services with unified funding streams.
- South Australia technology clustering:The Osborne naval shipyard complex and adjacent electronics manufacturing precincts concentrate specialized labor pools and test infrastructure that accelerate system integration timelines.
- Autonomous platform proliferation:Uncrewed aerial, surface, and underwater vehicles multiply sensor deployment nodes, generating demand for distributed command architectures and edge processing capabilities.
Market Restraints
- Semiconductor supply concentration:Advanced processor and FPGA sourcing remains concentrated among Taiwanese and South Korean foundries, exposing programs to geopolitical supply disruption risks without domestic alternatives.
- Defence Trade Controls Act friction:Export permit requirements for classified technology transfer create procurement delays averaging 8-14 months for foreign component integration.
- Legacy platform interoperability burdens:Existing ANZAC-class frigate and Collins-class submarine combat systems require expensive middleware development to interface with AUKUS-standard architectures.
Strategic Opportunities
- Queensland aerospace corridor expansion:RAAF Base Amberley and surrounding defense precincts offer underutilized capacity for airborne early warning and electronic warfare system development.
- AI-enabled decision support convergence:Machine learning inference at the tactical edge combined with predictive maintenance analytics creates new product categories between traditional C4 and ISR boundaries.
- Sovereign guided weapons enterprise:Commonwealth manufacturing incentives for domestic missile production include embedded C4ISR subsystems that open supplier entry points previously controlled by primes.
Industry Challenges
- Cleared workforce scarcity:Security vetting backlogs and specialized cyber-physical systems engineering shortages constrain program execution velocity across major acquisition streams.
- Trilateral technology release protocols:Evolving UK-US-Australia classification harmonization creates uncertainty in intellectual property boundaries and software export licensing for integrated systems.
- Multi-domain integration complexity:Joint all-domain command requirements demand real-time data fusion across space, cyber, air, maritime, and land networks with incompatible legacy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia C4ISR Market |
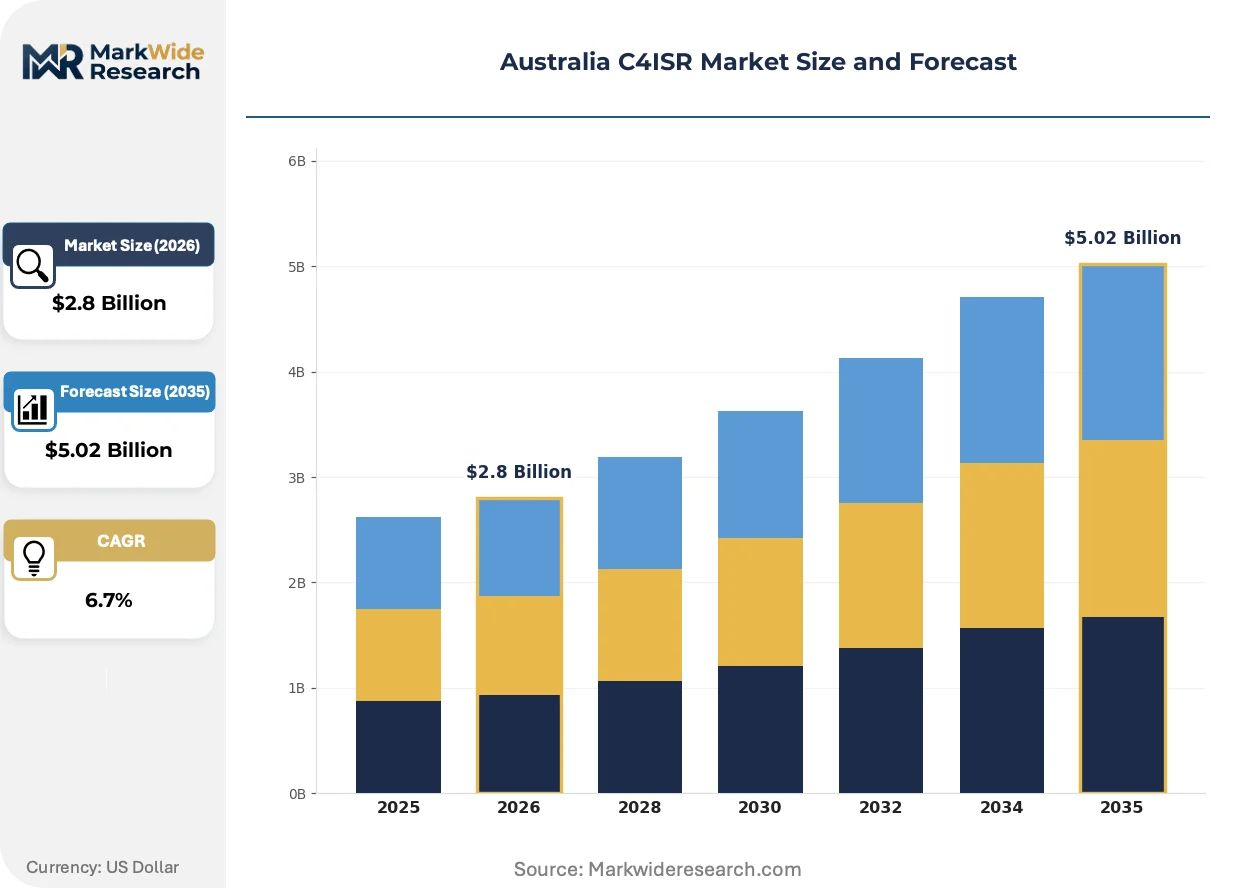
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Satellite Communications, Mobile Communication, Cybersecurity, Data Analytics Application: Defense Operations, Intelligence Gathering, Surveillance, Reconnaissance End User: Government Agencies, Military Organizations, Defense Contractors, Private Security Firms Solution: Integrated Systems, Software Solutions, Training Programs, Support Services |
| Companies Covered | Lockheed Martin Corporation, L3Harris Technologies Inc, BAE Systems PLC, General Dynamics Corporation, Elbit Systems Ltd, Thales Group, Northrop Grumman, The Boeing Company, Saab AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia C4ISR Market Strategic Shifts
Software-defined radio and open systems architectures are dissolving traditional hardware-locked competitive moats, enabling modular capability upgrades that compress procurement cycles and shift value toward firmware and algorithm providers.
Software-defined wideband networking waveforms are displacing proprietary legacy datalink protocols across RAAF and RAN platforms. Platform integrators at Amberley and Nowra are fielding these systems on accelerated timelines. This displacement collapses the vendor lock-in that previously protected incumbent radio suppliers.
The Defence Trade Controls Act amendment process is tightening technology transfer oversight while paradoxically creating streamlined pathways for AUKUS-partnered entities. Australian subsidiaries of US and UK primes now access expedited licensing for trilaterally developed components. Naval combat system providers face the steepest compliance adaptation requirements.
Capability-as-a-service contracting is replacing traditional capital acquisition for satellite communications and cyber defense functions. Defense contractors absorb operational risk through availability-based payment structures. Western Australia and Northern Territory garrison rotations demonstrate this model most extensively.
Australia C4ISR Market Segmentation
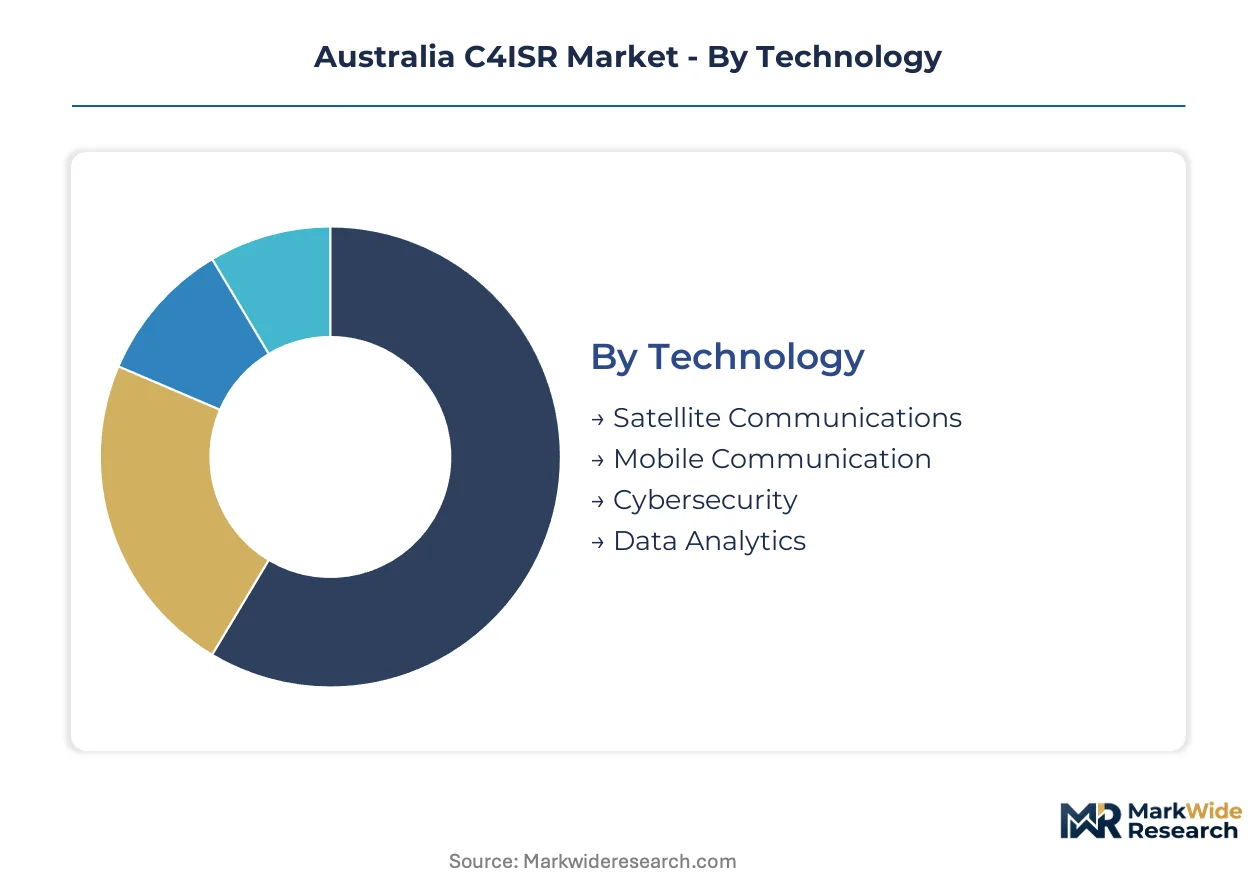
C4ISR procurement in Australia fragments across technology maturity curves and sovereign capability mandates. Defence Strategic Review funding envelopes create divergent investment profiles across operational applications and delivery models.
Technology:
TGA certification pathways and Defence Trade Controls Act compliance requirements differentiate technology segments by export licensing burden and foreign component dependency.
- Satellite Communications:Geostationary and low-earth orbit constellations deliver beyond-line-of-sight connectivity across Australia's maritime approaches and Northern Territory garrison networks. Demand concentrates in South Australia around Osborne shipyard integration timelines, constrained by semiconductor supply concentration in Taiwanese foundries.
- Mobile Communication:Software-defined wideband networking waveforms displace proprietary datalink protocols across RAAF Amberley and RAN Nowra platforms. Fielding accelerates as open systems architectures collapse vendor lock-in that previously protected incumbent radio suppliers.
- Cybersecurity:Zero-trust architectures and tactical edge encryption for AUKUS-classified networks.
- Data Analytics:Machine learning inference pipelines for predictive maintenance and threat detection.
Satellite Communications handles the majority of throughput; Mobile Communication is gaining share fastest as software-defined architectures proliferate.
Application:
Capability-as-a-service contracting shifts procurement economics across operational use cases, with availability-based payment structures favoring sustained engagement over capital acquisition.
- Intelligence Gathering:Autonomous platform sensor networks and signals intelligence modernization multiply collection nodes across space, cyber, and electromagnetic domains. Investment clusters in Queensland aerospace corridor development for airborne early warning systems, driven by AI-enabled decision support convergence at the tactical edge.
- Defense Operations:Joint all-domain command systems integrating space, air, maritime, land, and cyber networks through standardized data links. Sovereign guided weapons enterprise manufacturing incentives absorb expanded C4ISR subsystem integration responsibilities.
- Surveillance:Persistent wide-area motion imagery and acoustic monitoring for northern maritime approaches.
- Reconnaissance:Uncrewed platform tasking for time-sensitive target prosecution.
Defense Operations commands the largest funding envelope; Intelligence Gathering shows the steepest expansion trajectory from autonomous platform proliferation.
End User:
Security vetting backlogs and cleared workforce scarcity constrain program execution velocity differently across customer categories with varying classification access tiers.
- Military Organizations:Royal Australian Navy fleet modernization programs and AUKUS submarine construction drive integrated combat system procurement through CASG acquisition frameworks. RAAF Base Amberley and Osborne naval shipyard complexes anchor demand concentration with specialized labor pool dependencies.
- Defense Contractors:BAE Systems Adelaide maritime systems hub and Thales protected mobility vehicle electronics suites demonstrate sovereign build requirement absorption. Enhanced sovereign industry agenda transfers sustainment and integration responsibilities from uniformed services.
- Government Agencies:Defence Intelligence Organisation and Australian Signals Directorate collection platform requirements.
- Private Security Firms:Critical infrastructure protection and government-contracted facility security.
Military Organizations anchor procurement volume; Defense Contractors are climbing fastest on share through sovereign capability mandates.
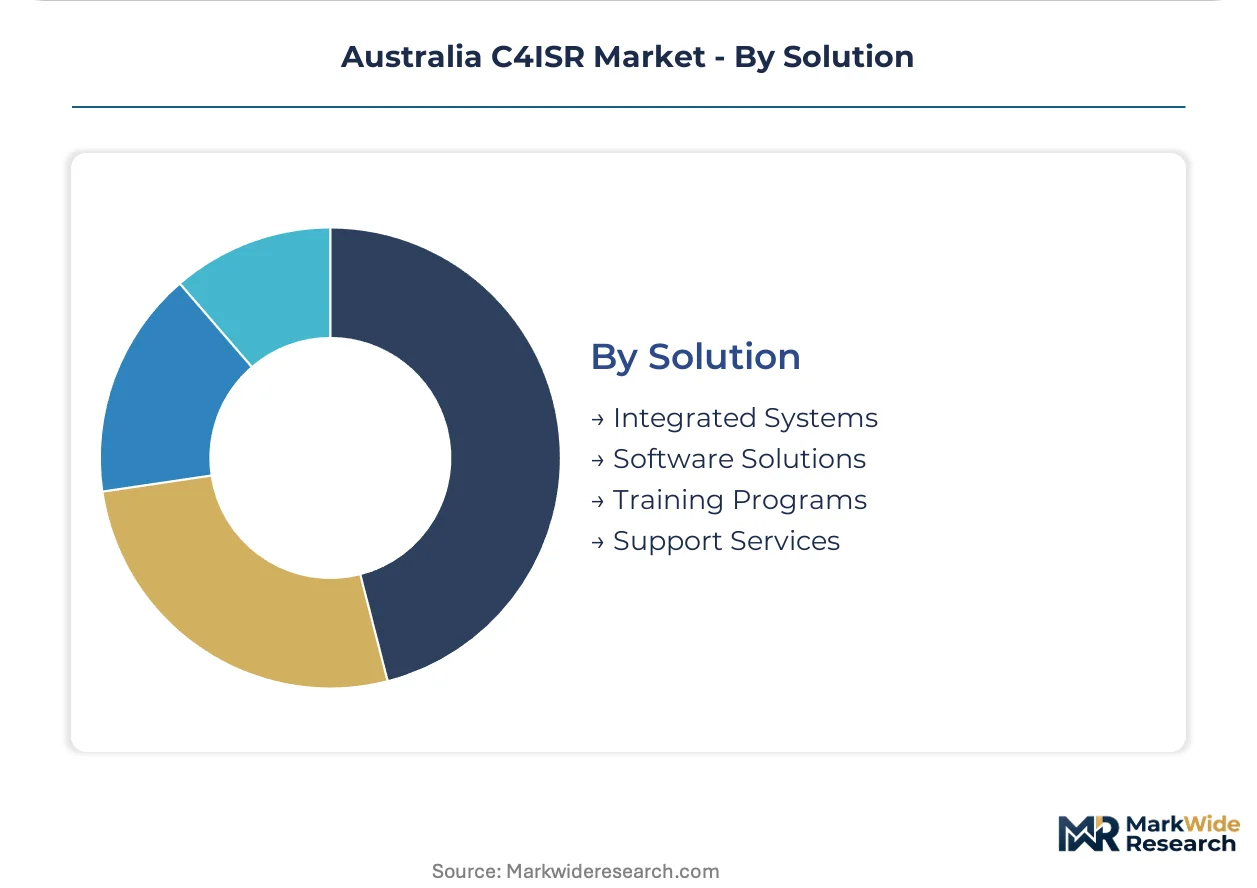
Solution:
Lifecycle cost structures and intellectual property retention terms differentiate delivery models under trilateral technology release protocol uncertainty.
- Integrated Systems:Naval combat system architectures and Joint Air Battle Management System platforms fuse sensor data through standardized processing protocols. ANZAC-class frigate and Collins-class submarine middleware development burdens concentrate in South Australia technology clusters.
- Software Solutions:Open systems architectures enable modular capability upgrades compressing procurement cycles, shifting value toward firmware and algorithm providers. Software-defined radio dissolves hardware-locked competitive moats across RAAF and RAN platforms.
- Support Services:Availability-based sustainment contracting for satellite communications and cyber defense functions.
- Training Programs:Simulator-based crew qualification and maintenance certification for AUKUS-standard systems.
Integrated Systems dominates capital allocation; Software Solutions is expanding most quickly as capability-as-a-service models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's C4ISR market operates as a net importer of advanced electronic warfare and combat system components, with domestic production concentrated in sovereign build requirements under AUKUS and the Defence Strategic Review. Technology transfer protocols from the United States and United Kingdom reshape regional supply chains.
South Australia
The Osborne naval shipyard complex anchors submarine and surface combatant construction, driving integrated command system demand. Defence Trade Controls Act compliance requirements concentrate foreign prime partnerships in Adelaide's maritime systems hub. Technology clusters around the shipyard absorb AUKUS-standard combat system integration responsibilities.
Queensland
RAAF Base Amberley and the surrounding aerospace corridor host airborne early warning and electronic warfare development programs. The state's northern positioning supports Indo-Pacific operational requirements for beyond-line-of-sight connectivity. Autonomous platform testing facilities at Woomera Range Complex extend Queensland's surveillance reach.
New South Wales
Defence Intelligence Organisation and Australian Signals Directorate headquarters in Canberra drive intelligence gathering procurement across electromagnetic and cyber domains. The state hosts Joint Air Battle Management System program offices and satellite communications ground stations. Western Sydney defense precincts concentrate cybersecurity workforce development.
Victoria
Land system electronics integration for protected mobility vehicles clusters around Melbourne's manufacturing corridor. Thales Group's Bushmaster and Hawkei programs sustain sovereign industrial capability mandates. The state's defense research institutions support human-machine interface development for armored platforms.
Western Australia
Capability-as-a-service contracting for satellite communications and northern maritime surveillance concentrates in Perth-based defense contractor operations. HMAS Stirling naval base and Northwest Shelf oil and gas infrastructure drive critical infrastructure protection requirements. Remote garrison rotations demonstrate availability-based payment structures for persistent surveillance.
Australia C4ISR Market Competitive Environment
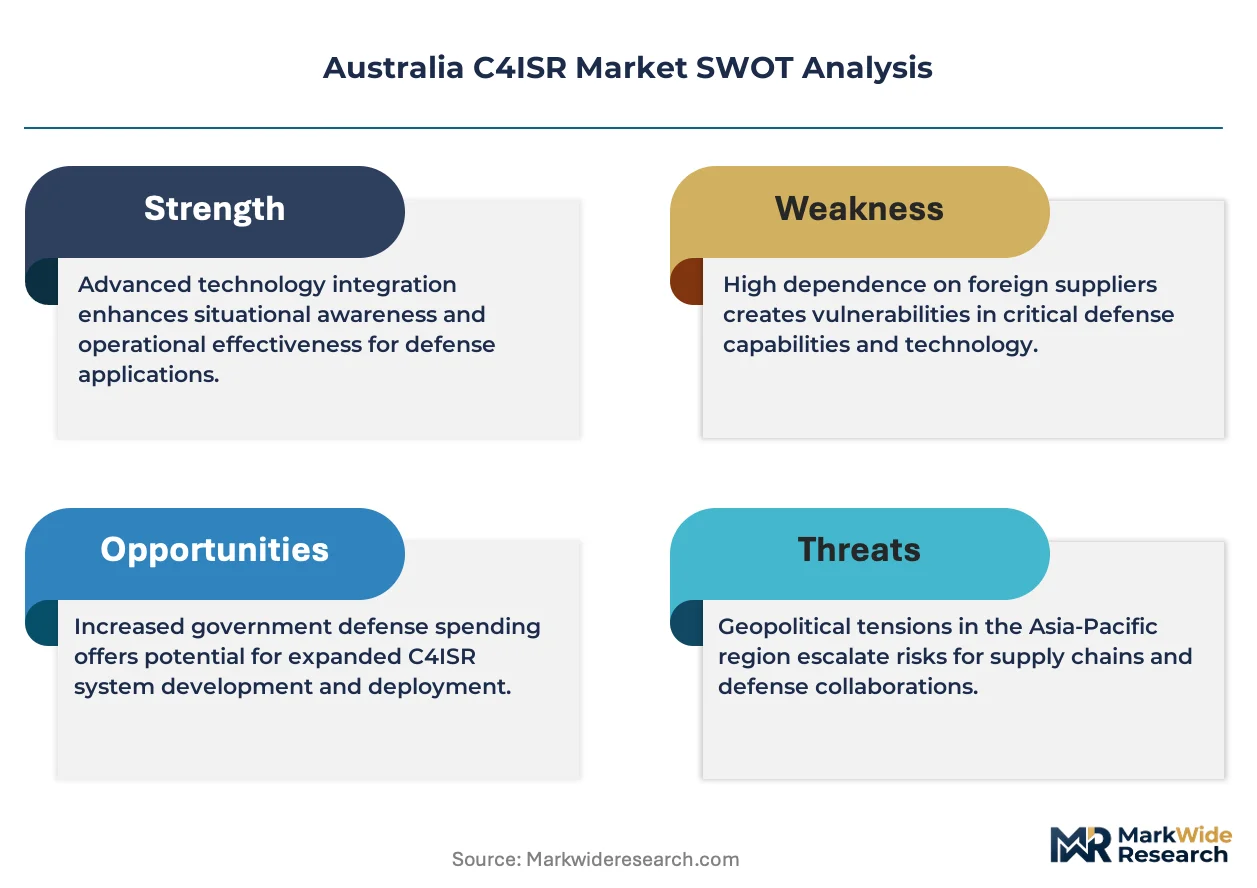
Listed defense primes compete with private specialists across sovereign build mandates and technology transfer licensing. The market structures around tiered access to AUKUS-classified architectures, with foreign ownership restrictions forcing partnership models. Three archetypes dominate: US-based system integrators leveraging trilateral security arrangements, UK-headquartered naval combat specialists, and Australian-registered subsidiaries absorbing local content requirements. Competitive moves center on Adelaide hub establishment and Canberra policy access cultivation.
Within the naval systems tier, BAE Systems PLC and Lockheed Martin Corporation exemplify foreign prime positioning through Australian subsidiary structures. Thales Group occupies a distinct land systems specialization. These three anchors represent the dominant competitive pattern: foreign-headquartered entities with cleared domestic workforces bidding under sovereign industrial capability frameworks.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| L3Harris Technologies Inc |
| BAE Systems PLC |
| General Dynamics Corporation |
| Elbit Systems Ltd |
| Thales Group |
| Northrop Grumman |
| The Boeing Company |
| Saab AB |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month lead times for radiation-hardened FPGAs concentrate pricing power among Taiwanese foundry-dependent integrators while compressing margins for Australian-based system assemblers competing on fixed-price Defence contracts.
Pricing Analysis
Defence prime contractors anchor pricing structures around capability-as-a-service availability contracts with embedded hardware refresh cycles. Three-tier pricing separates AUKUS-trusted from allied-standard from commercial-off-the-shelf certification tiers, with differentiation driven by security clearance depth and sovereign content thresholds. Cost compression in software-defined radio modules is intensifying because open architecture standards collapse proprietary protocol premiums. Tier 2 subsystem integrators exhibit highest price sensitivity due to fixed-margin pass-through arrangements with primes.
Supply Chain Analysis
Taiwan Strait transit risk underwrites semiconductor supply vulnerability for advanced processors and RF components essential to naval combat systems. Australian C4ISR production draws from Taiwanese foundries, South Korean memory fabricators, and US defense-qualified component suppliers. Single-source vulnerability concentrates in gallium nitride substrates and space-grade FPGAs. Distribution runs through cleared domestic warehousing at Adelaide and Amberley with Defence Trade Controls Act documentation gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Defence Australia and CASG as sole-source procurement envelopes consolidate under sovereign capability mandates, fragmenting supplier leverage across tiered subcontractor networks.
For Market Incumbents: Secure cleared workforce pipelines through Adelaide and Amberley technology cluster partnerships to counter security vetting backlogs that constrain program velocity. Anchor vertical integration into software-defined radio firmware development to defend against open-architecture margin erosion from algorithm specialists. Prioritize Defence Trade Controls Act compliance infrastructure as regulatory friction intensifies for foreign component integration. For New Entrants and Emerging Players: Post-mission analytics and predictive maintenance algorithm layers represent under-served service gaps where primes lack specialized machine learning depth. Target Queensland aerospace corridor expansion for airborne early warning subsystem entry, exploiting RAAF Base Amberley capacity buildout timelines. Pursue sovereign guided weapons enterprise subcontractor qualification as the fastest channel to AUKUS technology access without prime-tier capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign capability arbitrage play because trilateral technology release protocols progressively favor Australian-registered subsidiaries with cleared domestic workforces. Acquisition targets should display software-defined systems expertise combined with Defence security clearance infrastructure. Monitor AUKUS classification harmonization progress as the signal for intellectual property licensing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Adelaide Maritime Systems Hub Establishment | BAE Systems anchors sovereign build requirements under AUKUS submarine construction timelines at Osborne. |
| Software-Defined Radio Platform Integration | Open architecture waveforms displace proprietary Lockheed Martin and Northrop Grumman datalink protocols across RAAF platforms. |
| Queensland Aerospace Corridor Partnership | RAAF Base Amberley expansion hosts airborne early warning development outside incumbent South Australia concentration. |
| Sovereign Guided Weapons Enterprise Qualification | Domestic missile manufacturing incentives open C4ISR subsystem entry points previously controlled by prime contractors. |
| Cleared Workforce Pipeline Investment | Security vetting backlogs constrain program execution velocity across CASG acquisition streams. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Royal Australian Navy program executives, CASG acquisition leads, BAE Systems Adelaide integration engineers, and Thales Australia electronics specialists. Secondary validation drew from Defence Strategic Review documentation, AUKUS implementation pathway releases, Defence Trade Controls Act regulatory filings, and parliamentary committee testimony records. Bottom-up segment sizing triangulated against top-down defence budget envelope analysis.
Across the analysis window, projections incorporate technology adoption curves for software-defined architectures, sovereign industrial capability mandate implementation phases, and AUKUS submarine construction milestones. Segmentation modeling spans technology maturity tiers, application use cases from intelligence gathering through defense operations, end-user classification access levels, and solution delivery modes from integrated systems through capability-as-a-service. CAGRs derive from deployment timeline phasing and funding envelope allocation patterns across the three services.
Forecasts assume regulatory continuity in Defence Trade Controls Act administration and AUKUS technology transfer protocols; material policy shifts in trilateral classification harmonization or sovereign content threshold tightening would require re-modeling. Semiconductor supply concentration risk and cleared workforce availability constraints represent specific revision triggers. Practitioners should keep alternative scenarios live as AUKUS implementation pace and Indo-Pacific force posture adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Brazil C4ISR Market
ISR
Air Based C4ISR Market
ISR
United States C4ISR Market
ISR
Airborne ISR Market
ISR
Europe C5ISR Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
North America Airborne ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Japan C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
NATO C4ISR Market
ISR
Low Altitude Radar Market
ISR
Asia-Pacific C4ISR Market
ISR
IFF System Market