
 Space Radar Market | 2026-2036
Space Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Space Radar Market Analysis
Defense procurement is recalibrating toward persistent satellite-based surveillance as terrestrial and airborne assets face contested airspace risks. Lockheed Martin Corporation leverages decades of classified program experience to anchor high-orbit radar constellations for the US military. Capella Space competes through commercial synthetic aperture radar specialization, offering rapid revisit times that differentiate its offering from legacy defense primes. ICEYE sustains a lean satellite manufacturing model that controls unit costs while extending coverage to disaster response agencies globally.
Space radar encompasses active remote sensing systems that transmit microwave energy toward Earth and process backscattered signals to generate two-dimensional imagery, typically operating at X-band, C-band, or L-band frequencies with spatial resolution ranging from sub-meter to tens of meters depending on antenna configuration and orbital altitude. Synthetic aperture radar dominates commercial procurement due to its all-weather, day-night imaging capability, while phased array radar occupies the premium military tier where electronic beam steering enables multi-target tracking. Earth observation represents the fastest-growing application segment as climate monitoring agencies and agricultural insurers adopt subscription-based radar imagery, whereas military surveillance remains the margin pool leader given classified budget flows and long-term platform development cycles.
The Federal Communications Commission and the National Oceanic and Atmospheric Administration jointly shape US space radar deployment through spectrum allocation and remote sensing licensing requirements, while the European Space Agency coordinates member-state radar satellite programs under Copernicus continuity frameworks. These regulatory layers determine orbital slot access, data export controls, and foreign participation eligibility, directly constraining market entry for non-domestic operators. Stakeholders must monitor evolving debris mitigation mandates and dual-use technology transfer restrictions that will determine which constellation architectures achieve operational scale.
Market Dynamics
Defense procurement is recalibrating toward persistent satellite-based surveillance as terrestrial and airborne assets face contested airspace risks. Lockheed Martin Corporation leverages decades of classified program experience to anchor high-orbit radar constellations for the US military. Capella Space competes through commercial synthetic aperture radar specialization, offering rapid revisit times that differentiate its offering from legacy defense primes. ICEYE sustains a lean satellite manufacturing model that controls unit costs while extending coverage to disaster response agencies globally.
Growth Catalysts
- US FCC Spectrum Allocation:The Federal Communications Commission is releasing additional X-band and S-band spectrum for commercial Earth observation, enabling higher-resolution imaging constellations to achieve regulatory clearance faster.
- European Union Debris Mitigation Mandates:Stricter end-of-life disposal requirements under EU Space Surveillance and Tracking frameworks are accelerating demand for radar systems that can track small debris objects in low Earth orbit.
- Synthetic Aperture Radar Miniaturization:Advances in phased array antenna design and onboard processing are reducing satellite bus mass requirements, allowing smaller launch vehicles to deploy operational radar payloads.
Market Restraints
- Launch Cost Concentration:Dependence on a limited set of US and European launch providers creates capacity bottlenecks for constellation deployment schedules.
- Dual-Use Export Controls:US International Traffic in Arms Regulations and EU dual-use technology restrictions fragment supply chains and delay foreign operator market entry.
- Radio Frequency Interference:Crowded spectral environments in X-band and C-band are degrading signal quality and forcing costly interference mitigation hardware upgrades.
Strategic Opportunities
- Australian Defense Modernization:The Australian Defence Force is soliciting sovereign satellite radar capabilities under Project REDSPICE, creating procurement windows for non-US operators.
- Agricultural Insurance Subscriptions:Parametric crop insurers in India and Brazil are adopting daily revisit radar data to validate claims without field inspections.
- AI-Assisted Change Detection:Machine learning inference at the edge is enabling automated anomaly detection for infrastructure monitoring, opening municipal and utility procurement channels.
Industry Challenges
- RF Engineer Scarcity:The specialized workforce for microwave circuit design and antenna calibration is concentrated at legacy defense primes, constraining startup hiring pipelines.
- ITAR Compliance Timelines:US foreign disclosure review processes for international data sharing agreements routinely extend 18-24 months, delaying revenue recognition for dual-use contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Radar Market |
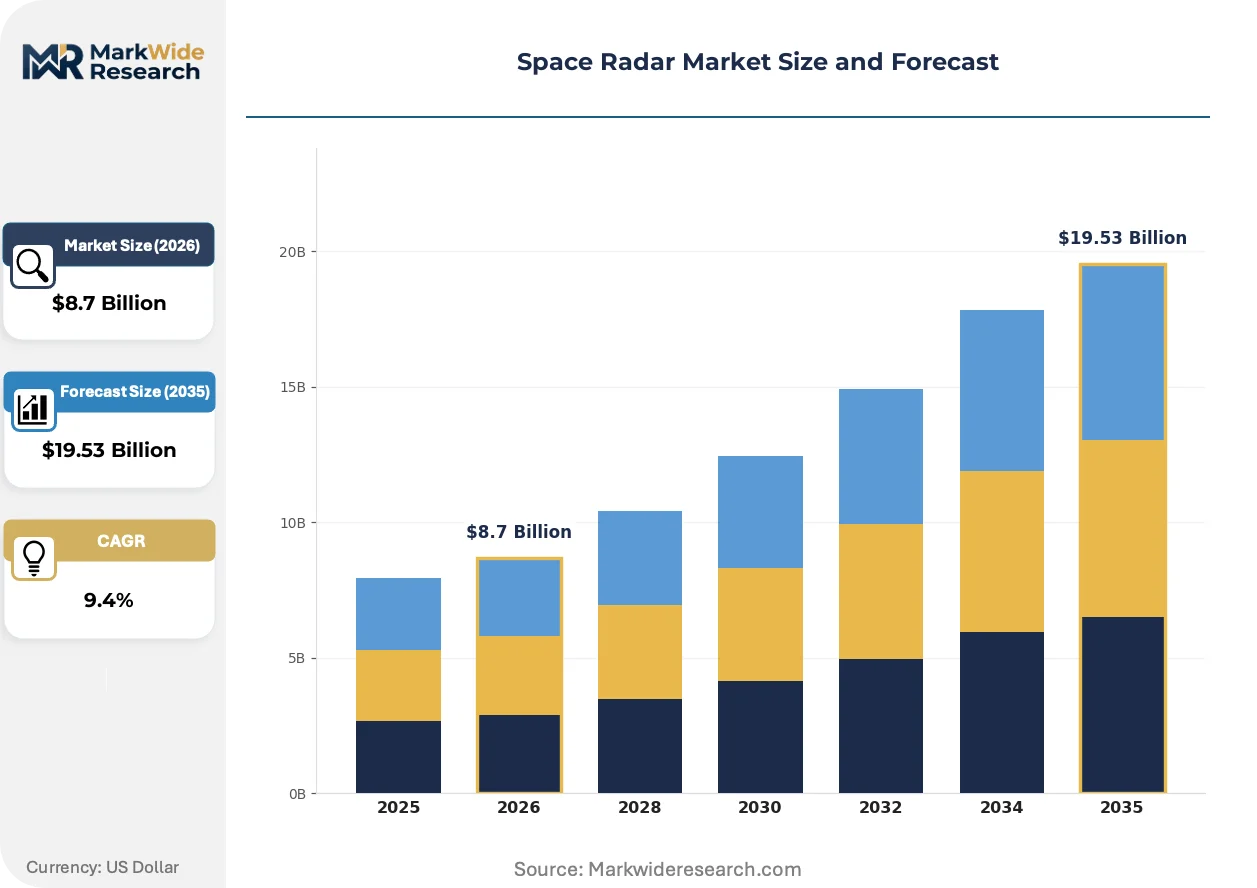
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Synthetic Aperture Radar, Phased Array Radar, Pulsed Radar, Continuous Wave Radar Application: Earth Observation, Military Surveillance, Weather Monitoring, Disaster Management End User: Aerospace Agencies, Defense Organizations, Research Institutions, Commercial Enterprises Deployment: Ground-Based, Airborne, Spaceborne, Maritime |
| Companies Covered | ICEYE, Capella Space, Lockheed Martin Corporation, Northrop Grumman, Leonardo S.p.A., BAE Systems, Airbus, Saab AB, RTX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Radar Market Emerging Trajectories
Active beam steering and onboard edge processing are compressing the latency between data acquisition and actionable intelligence delivery. These capabilities are rewriting competitive benchmarks for revisit frequency and real-time responsiveness.
Digital beamforming is rewriting how synthetic aperture radar satellites manage power allocation across multiple imaging targets. Military operators are demanding simultaneous multi-mode operation—combining stripmap, spotlight, and scanSAR modes from a single pass. This compression of capability into single platforms is raising the technical barrier for new entrants while extending the serviceable life of deployed constellations.
The European Space Agency's Copernicus Contributing Missions framework is mandating open data policies for radar imagery acquired under public funding. This regulatory shift is commoditizing archival imagery and forcing commercial operators to differentiate through analytics layers rather than raw data sales. European agricultural ministries are responding by consolidating procurement around value-added service contracts rather than pixel-delivery agreements.
Subscription-based imagery-as-a-service contracts are displacing traditional per-square-kilometer pricing in commercial Earth observation. Insurance and commodity trading desks are consolidating vendor relationships around platforms offering API-delivered change detection rather than manual image ordering portals. This behavioral shift is most visible in North American agricultural technology markets, where farm management software platforms are bundling radar-derived soil moisture analytics into annual SaaS licenses.
Space Radar Market Segmentation
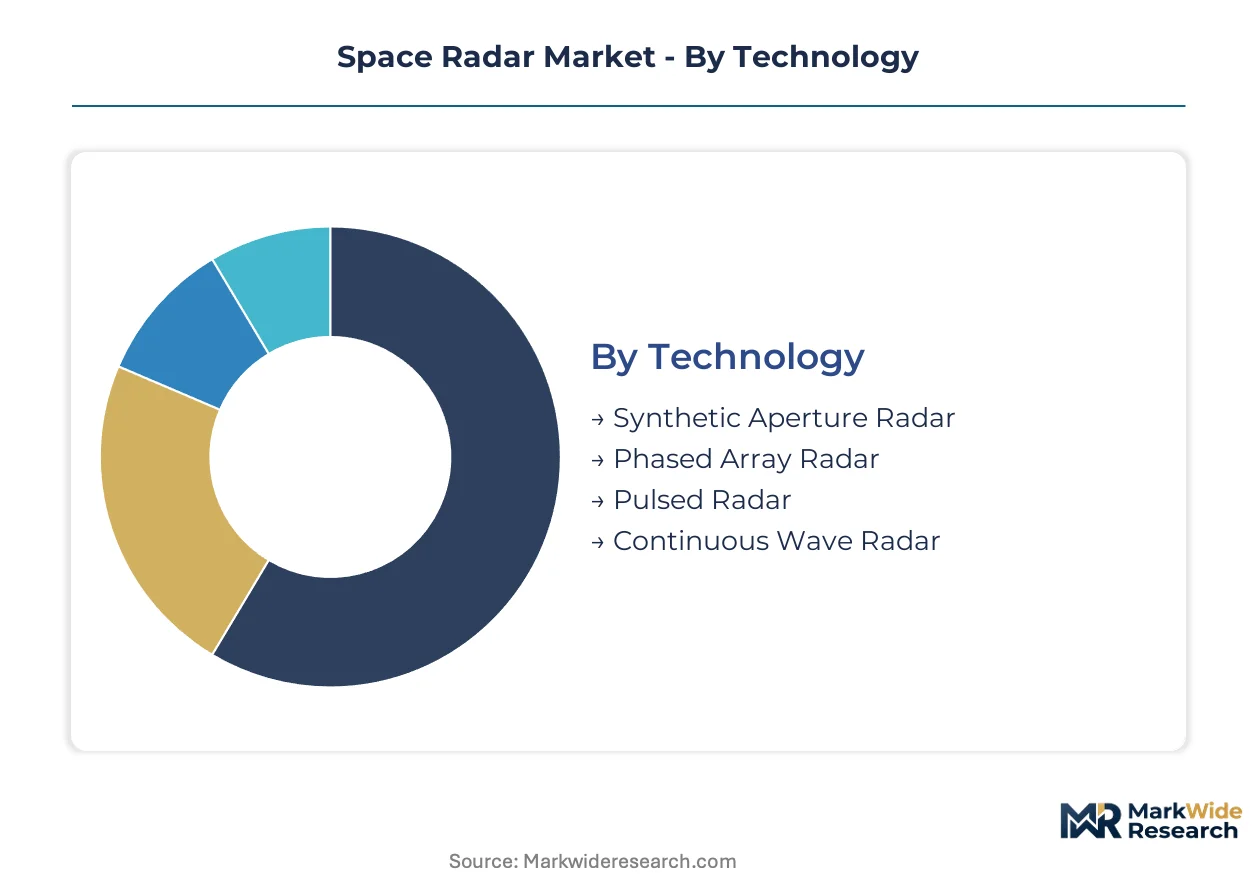
Space radar procurement splits across technical architectures, mission profiles, and operational domains. Each segmentation axis carries distinct margin structures, regulatory exposure, and customer concentration patterns that reshape vendor strategy.
Technology:
Synthetic aperture radar occupies the standardization pole with mature manufacturing templates, while phased array systems demand extensive customization for military beam-steering requirements.
- Synthetic Aperture Radar:Active microwave systems synthesize large antenna apertures through platform motion, generating high-resolution imagery independent of solar illumination. Demand clusters with agricultural insurers and commodity traders in North America seeking daily soil moisture monitoring.
- Phased Array Radar:Electronic beam steering enables simultaneous multi-target tracking and rapid revisit without mechanical antenna movement. US Space Force and classified intelligence programs anchor procurement, with ITAR compliance extending development cycles.
- Pulsed Radar:Short-duration energy bursts support precise ranging applications with lower power budgets than continuous operation.
- Continuous Wave Radar:Uninterrupted signal transmission suits Doppler-based velocity measurement for orbital debris tracking missions.
Most installed capacity flows through Synthetic Aperture Radar. Expansion is steepest in Phased Array Radar.
Application:
Mission-critical defense surveillance commands premium pricing tiers, while commercial Earth observation scales through subscription volume.
- Earth Observation:All-weather terrain mapping and change detection serve climate monitoring agencies, agricultural ministries, and infrastructure operators. The European Space Agency's Copernicus program and India's ISRO anchor public procurement, with commercial resale markets expanding in Brazil and Australia.
- Military Surveillance:Classified reconnaissance constellations require encrypted downlinks, nuclear-hardened electronics, and assured access to polar orbits. US National Reconnaissance Office budgets dominate segment revenue, with Australian Defence Force Project REDSPICE emerging as a secondary demand node.
- Weather Monitoring:Precipitation radar and atmospheric profiling support national meteorological services and aviation routing.
- Disaster Management:Rapid damage assessment and flood extent mapping mobilize civil protection agencies and humanitarian organizations.
Defense procurement anchors revenue concentration in Military Surveillance. Commercial momentum is building fastest in Earth Observation.
End User:
Public-sector anchor customers provide contract visibility, while commercial enterprise adoption scales through API-integrated analytics platforms.
- Aerospace Agencies:NASA, ESA, and national space programs fund technology demonstration missions and operational constellation deployment. Procurement emphasizes technology transfer requirements and domestic supplier mandates.
- Defense Organizations:Classified program offices and unified combatant commands drive specifications for survivability, encryption, and anti-jam resilience. US Space Force Space Systems Command and UK Strategic Command coordinate allied interoperability standards.
- Research Institutions:University consortia and national laboratories access radar data through scientific use agreements and shared mission partnerships.
- Commercial Enterprises:Insurance underwriters, commodity traders, and precision agriculture platforms purchase subscription imagery through SaaS-integrated delivery models.
Defense Organizations channel the majority of committed procurement spend. Commercial Enterprises are climbing the fastest as parametric insurance and agricultural technology platforms mature.
Deployment:
Orbital deployment carries the steepest technical barriers and longest development timelines, while terrestrial and airborne alternatives serve calibration and tactical mobility needs.
- Spaceborne:Low Earth orbit constellations at 400-600 kilometer altitudes deliver global revisit with sub-meter resolution. FCC licensing and NOAA remote sensing permits constrain US market entry, while EU debris mitigation mandates reshape satellite design.
- Ground-Based:Fixed and transportable radar installations support satellite tracking, space situational awareness, and calibration campaigns for orbital sensors.
- Airborne:Manned and unmanned platforms carry SAR payloads for tactical reconnaissance and disaster response where orbital revisit is insufficient.
- Maritime:Ship-mounted systems extend surveillance coverage in contested littoral environments and support ice navigation in polar routes.
Spaceborne deployment concentrates operational investment. Airborne systems are expanding most quickly as contested airspace drives demand for tactical persistence below satellite detection thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver-Aurora anchors the space radar industrial base through concentrated defense contractor facilities and classified program offices. National procurement flows through three additional demand centers spanning allied defense modernization programs and commercial Earth observation hubs.
United States
US Space Force Space Systems Command and the National Reconnaissance Office channel classified procurement toward high-orbit radar constellations with nuclear-hardened electronics requirements. The FCC and NOAA jointly license commercial remote sensing operations through spectrum allocation and orbital debris mitigation protocols. Denver-Aurora and the Greater Los Angeles area concentrate prime contractor engineering facilities and satellite integration cleanrooms.
United Kingdom
UK Strategic Command coordinates allied interoperability standards for synthetic aperture radar satellite networks serving unified combatant commands. The UK Space Agency mandates domestic supplier participation in radar payload development under national security frameworks. Harwell Space Cluster in Oxfordshire hosts SAR component testing facilities and mission analysis centers for European defense programs.
Australia
The Australian Defence Force solicits sovereign satellite radar capabilities under Project REDSPICE with explicit non-US operator procurement windows. The Australian Space Agency enforces technology transfer requirements and local workforce development mandates for foreign contractors. South Australia's Lot Fourteen innovation district anchors mission control facilities and ground segment operations for regional coverage constellations.
Finland
Finnish meteorological institutes and ice navigation authorities procure compact SAR satellites for Baltic Sea monitoring and Arctic route surveillance. The country's national space regulator coordinates with ESA Copernicus frameworks for open data policy compliance. The Otaniemi technology campus in Espoo concentrates university-affiliated radar algorithm development and NewSpace manufacturing startups.
United Arab Emirates
UAE Space Agency funding supports synthetic aperture radar demonstration missions for desert agriculture monitoring and infrastructure change detection. The national remote sensing center enforces data sovereignty requirements and domestic processing mandates for foreign imagery providers. Dubai's Mohammed bin Rashid Space Centre hosts ground station networks and AI-assisted analytics development for regional disaster response agencies.
Space Radar Market Vendor Landscape
Strategic partnerships dominate the current landscape as defense primes and commercial operators forge hybrid procurement arrangements. The vendor base splits between classified program incumbents with decades of government relationships and venture-backed constellation operators pursuing subscription revenue models. Three archetypes define positioning: legacy defense contractors with ITAR-cleared manufacturing, pure-play SAR satellite operators with rapid revisit capabilities, and diversified aerospace conglomerates with multi-domain radar portfolios. Capacity expansion and technology licensing constitute the primary competitive vectors, with orbital slot acquisition and spectrum clearance determining deployment velocity.
Within the classified program tier, Lockheed Martin Corporation and Northrop Grumman anchor high-orbit military constellations through established relationships with US Space Force and intelligence community procurement offices. Capella Space and ICEYE exemplify the commercial SAR specialization archetype, with the former emphasizing rapid revisit times and the latter maintaining lean satellite manufacturing economics for disaster response agencies. Leonardo S.p.A. represents the European defense-aerospace hybrid model, bridging national security requirements with Copernicus program participation.
| Leading Market Players |
|---|
| ICEYE |
| Capella Space |
| Lockheed Martin Corporation |
| Northrop Grumman |
| Leonardo S.p.A. |
| BAE Systems |
| Airbus |
| Saab AB |
| RTX |
| Others |
Supply Flow & Price Mechanics
Australian Defence Force procurement under Project REDSPICE is mandating sovereign satellite radar capabilities with explicit non-US operator windows, forcing supply chains to establish regional manufacturing footprints and compressing margins for foreign primes unable to meet domestic content thresholds.
Pricing Analysis
Launch vehicle cost pass-through dominates pricing architecture for spaceborne radar constellations, with subscription-based imagery-as-a-service models displacing per-square-kilometer transactional pricing across commercial Earth observation. Price differentiation rests on revisit frequency guarantees and onboard edge-processing capabilities, with agricultural insurers in North America exhibiting highest price sensitivity while classified military programs remain least elastic due to mission-critical requirements. Cost compression in commercial SAR tiers is intensifying as Capella Space and ICEYE scale rapid-revisit constellations.
Supply Chain Analysis
End-of-life satellite refurbishment and orbital debris retrieval logistics are emerging as critical supply chain nodes under EU Space Surveillance and Tracking frameworks, with deorbit service providers creating reverse-flow revenue streams. Manufacturing concentration spans the United States, Finland, and Australia, with phased array antenna components drawing from specialized microwave foundries in the UK and Germany. Single-source vulnerability in radiation-hardened electronics creates procurement bottlenecks for nuclear-qualified military payloads. Distribution runs through defense procurement offices for classified programs and API-integrated SaaS platforms for commercial Earth observation subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between ITAR-constrained US procurement and EU open-data Copernicus frameworks creates margin expansion opportunities for operators able to serve both compliance regimes without dual supply chains.
For Market Incumbents: Cement classified program relationships through accelerated ITAR clearance timelines for international data sharing agreements, while backward integration into radiation-hardened electronics manufacturing reduces exposure to single-source foundry bottlenecks. Lockheed Martin and Northrop Grumman must defend against commercial SAR operators encroaching on tactical reconnaissance margins through rapid-revisit value propositions. For New Entrants and Emerging Players: Enter via Australian Project REDSPICE procurement windows as the most penetrable defense market segment, targeting sovereign capability requirements with explicit non-US operator eligibility. ICEYE's lean manufacturing model offers a template for disaster response agency penetration, while municipal infrastructure monitoring through AI-assisted change detection APIs represents an underserved commercial channel. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play SAR constellation operators possessing rapid-revisit capabilities and established NOAA licensing clearance, as defense primes face margin compression from commercial encroachment. Acquisition targets should demonstrate proven FCC spectrum allocation and ESA Copernicus Contributing Mission participation. Monitor Australian Defence Force sovereign satellite procurement awards as inflection signals for non-US operator market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Manufacturing Footprint Establishment | Australian Space Agency mandates domestic supplier participation under Project REDSPICE procurement frameworks. |
| ITAR Compliance Acceleration Program | US International Traffic in Arms Regulations review timelines routinely extend 18-24 months for international contracts. |
| API-Integrated Analytics Platform Launch | Farm management software platforms in North America bundle radar-derived soil moisture into annual SaaS licenses. |
| Orbital Debris Mitigation Service Development | EU Space Surveillance and Tracking frameworks mandate end-of-life disposal and debris tracking capabilities. |
| Dual-Use Technology Licensing Agreement | Commercial SAR operators leverage defense-derived phased array advances for agricultural insurance subscriptions. |
Methodological Framework
Bottom-up defense procurement and commercial Earth observation subscription modeling reconciled against top-down satellite manufacturing capacity tracking forms the analytical core. Primary interviews with US Space Force program officers, ESA mission directors, Australian Defence Force procurement leads, and agricultural technology platform executives combined with secondary validation from FCC spectrum allocation databases, NOAA remote sensing licensing records, ESA Copernicus Contributing Mission documentation, and defense budget appropriation disclosures. Triangulation across stakeholder inputs and regulatory filings ensures segmentation accuracy.
Input-output matrices mapping launch vehicle capacity, phased array antenna production, and ground segment deployment against constellation refresh cycles and subscription renewal rates drive projection modeling across the analysis window. Segmentation dimensions include technology architecture, application mission profile, end-user procurement channel, and orbital deployment altitude. CAGRs derive from installed base growth trajectories and pricing elasticity assumptions for classified versus commercial procurement tiers. Forecast inputs incorporate debris mitigation mandate compliance costs and spectrum allocation timeline probabilities.
Inputs from defense procurement databases and commercial satellite operator disclosures were available through the study window; gaps in classified National Reconnaissance Office budget line-item granularity introduce uncertainty bands around military surveillance segment projections. Forecasts reflect assumptions regarding ITAR clearance timeline stability and EU debris mitigation mandate enforcement consistency. Practitioners should monitor Australian sovereign satellite procurement award announcements and FCC X-band spectrum release schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Designing Market
Space
US Space Launch Services Market
Space
Asia-Pacific Space Logistics Market
Space
US Space Electronics Market
Space
Space Tourism Market
Space
Space-Based Solar Power Market
Space
France Space Electronics Market
Space
Space Oscillator Market
Space
Deep Space Exploration Market
Space
Deep Space Robotics Market
Space
Africa Space Propulsion System Market
Space
Space Colonization Market
Space
Space Ground Station Equipment Market
Space
South Korea Space Electronics Market
Space
UK Space Propulsion System Market
Space
Space Mobile Service Market