
 NATO C4ISR Market | 2026-2036
NATO C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
NATO C4ISR Market Analysis
Defense procurement channels across NATO member states is fragmenting as national sovereignty requirements clash with alliance interoperability mandates. Lockheed Martin Corporation leverages its integrated battle management portfolio to anchor large-scale command contracts in North America. Thales Group competes through specialized tactical communications systems that dominate European defense ministries. Rheinmetall AG extends its land systems expertise into sensor-network integration for armored formations.
NATO C4ISR denotes the unified architecture of command, control, communications, computers, intelligence, surveillance, and reconnaissance systems enabling real-time battlespace awareness and decision superiority across allied forces. These systems integrate satellite uplinks, encrypted tactical radios, and multi-source data fusion engines operating at sub-second latency thresholds for kinetic and non-kinetic operations. Communication Systems and Surveillance Systems command the largest installed bases, while AI & Machine Learning within the Technology dimension represents the fastest-expanding capability layer as operators automate threat detection pipelines. Data Processing Systems sit at the core of margin concentration, since proprietary algorithms and secure cloud integration carry higher switching costs than hardware refresh cycles.
STANAG interoperability standards issued by NATO's Standardization Office shape hardware and software procurement requirements across all member militaries, while national regulators such as the US DoD's DISA and the UK's Defence Science and Technology Laboratory enforce supplemental cybersecurity certifications that fragment vendor qualification pathways. The EU AI Act and GDPR frameworks increasingly constrain cross-border data flows for intelligence-sharing architectures, forcing architecture redesigns for coalition operations. Stakeholders must monitor how emerging quantum-resistant encryption mandates and evolving classification reciprocity agreements between member states reshape competitive access to classified program tiers.
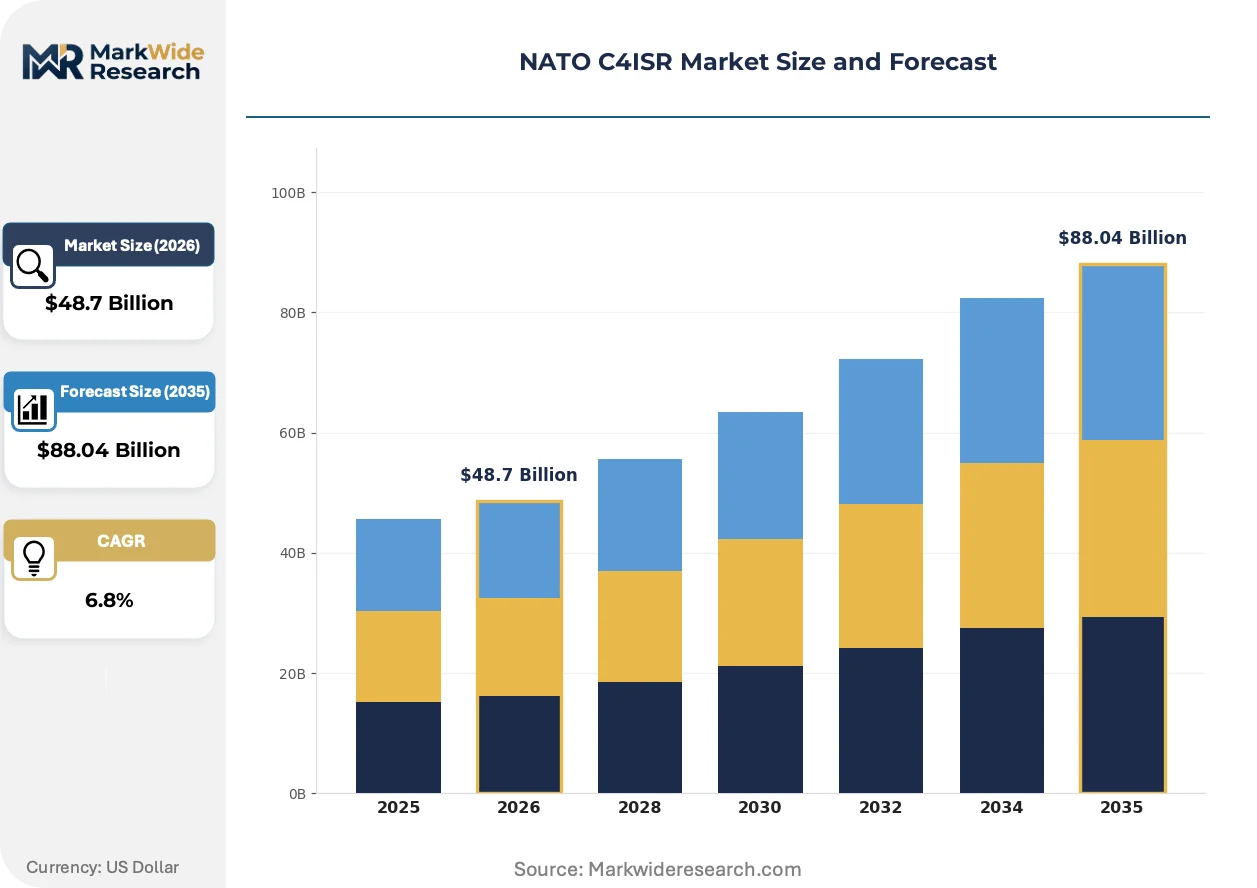
Market Dynamics
NATO's Digital Transformation Strategy is compressing procurement timelines for interoperable command architectures, forcing member militaries to reconcile sovereign data sovereignty requirements with alliance-wide cloud integration mandates.
Growth Catalysts
- STANAG Interoperability Mandates:NATO Standardization Office protocols compel hardware and software refresh cycles across member forces, creating synchronized procurement windows for integrated battle management systems.
- AI-Enabled Threat Detection:Machine learning pipelines for automated intelligence fusion are accelerating operator decision cycles in kinetic and non-kinetic operations across allied commands.
- Quantum-Resistant Encryption:Emerging cryptographic mandates from national defense agencies are driving replacement of legacy tactical radio networks with post-quantum secure architectures.
Market Restraints
- GDPR Cross-Border Friction:EU data protection frameworks constrain intelligence-sharing architectures, forcing costly redesigns of coalition cloud systems for classified information exchange.
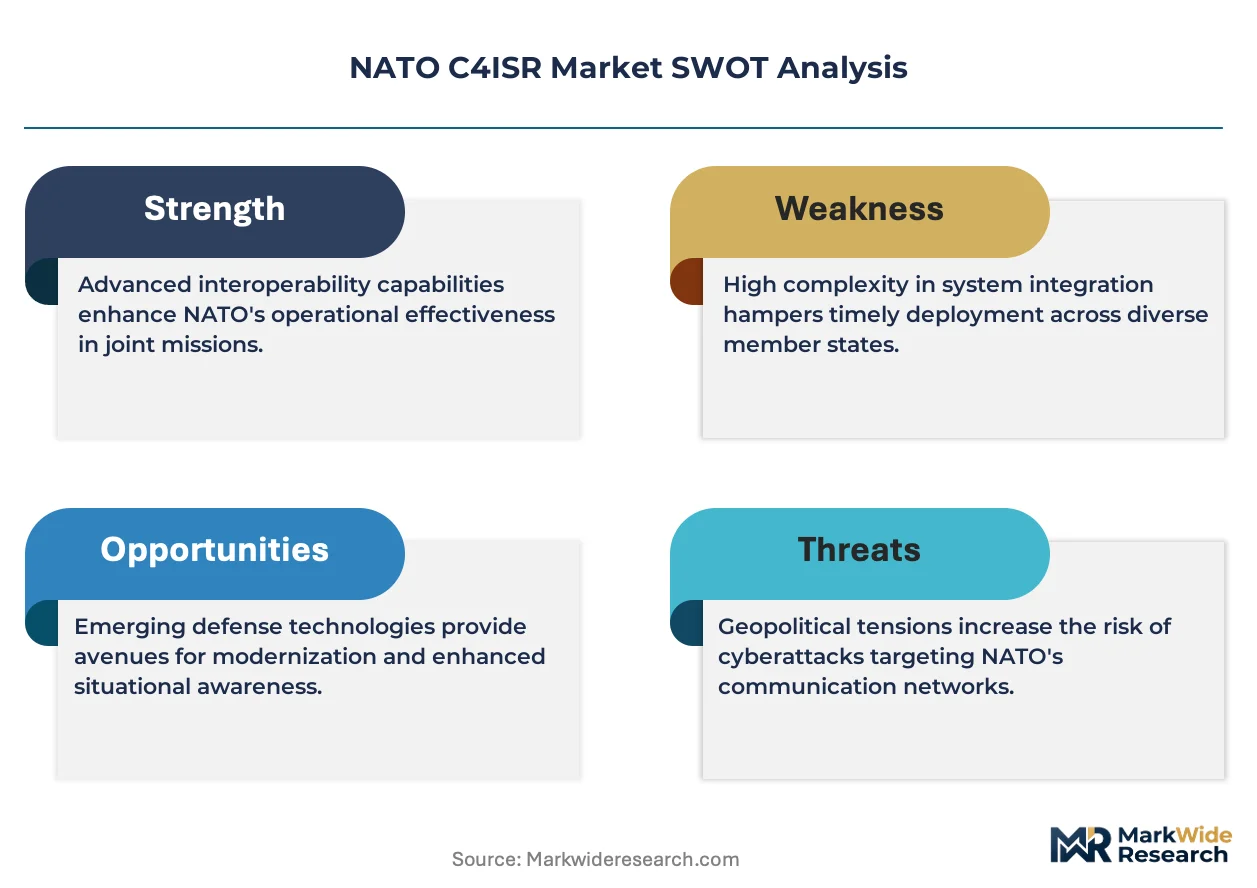
- Classification Reciprocity Gaps:Inconsistent security clearance reciprocity between member states fragments vendor access to classified program tiers and extends qualification timelines.
- Specialized Engineering Talent Scarcity:Shortage of cleared personnel with dual expertise in military operations and secure cloud engineering limits deployment velocity for integrated command systems.
Strategic Opportunities
- Poland's Eastern Flank Expansion:New NATO command structures in Poland create demand for localized C4ISR integration hubs serving enhanced forward presence battlegroups.
- Multi-Domain Operations Convergence:Integration of space, cyber, and electromagnetic spectrum capabilities into unified command architectures opens new system-of-systems contract categories.
- EU Defence Fund Incentives:Collaborative procurement financing mechanisms reduce national budget barriers for joint capability development among smaller member states.
Industry Challenges
- Legacy System Integration Complexity:Decades-old national command infrastructures resist seamless interoperability with modern cloud-native architectures, requiring expensive middleware development.
- Certification Timeline Compression:DISA and national cybersecurity laboratories face backlogs in evaluating quantum-resistant and AI-enabled systems against evolving threat models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NATO C4ISR Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Systems, Surveillance Systems, Reconnaissance Systems, Data Processing Systems Technology: AI & Machine Learning, Cloud Computing, Big Data Analytics, Cybersecurity Technologies End User: Military Forces, Defense Agencies, Government Contractors, Security Organizations Deployment: On-Premises, Hybrid, Cloud-Based, Remote Operations |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales Group, Northrop Grumman Corporation, Rheinmetall AG, Leonardo S.p.A., General Dynamics Corporation, Leidos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NATO C4ISR Market Emerging Trajectories
Real-time battlespace data fusion is displacing stovepiped national intelligence systems, compressing the latency between sensor collection and command authorization across allied formations.
Edge computing nodes for tactical units is hybridizing satellite-dependent command architectures with localized processing capabilities. Armored formations in Germany and forward-deployed units in the Baltic states are fielding vehicle-mounted data fusion engines that reduce reliance on contested satellite uplinks. This distributed architecture is compressing kill-chain timelines while creating new vulnerabilities in node-to-node synchronization protocols.
EU AI Act risk classification frameworks are reshaping procurement specifications for autonomous threat detection systems. Military applications of machine learning now face mandatory human-in-the-loop requirements and algorithmic transparency audits that extend development cycles. French and Dutch defense ministries are revising technical requirements documents to embed these compliance checkpoints into milestone payment structures.
Consolidated platform-as-a-service contracting is displacing discrete hardware procurement for command infrastructure. British and Norwegian armed forces are bundling satellite communications, secure cloud tenancy, and software licenses into single-vendor relationships with decade-long terms. This shift concentrates vendor selection authority within defense ministry central procurement offices rather than distributed service branches.
NATO C4ISR Market Segmentation
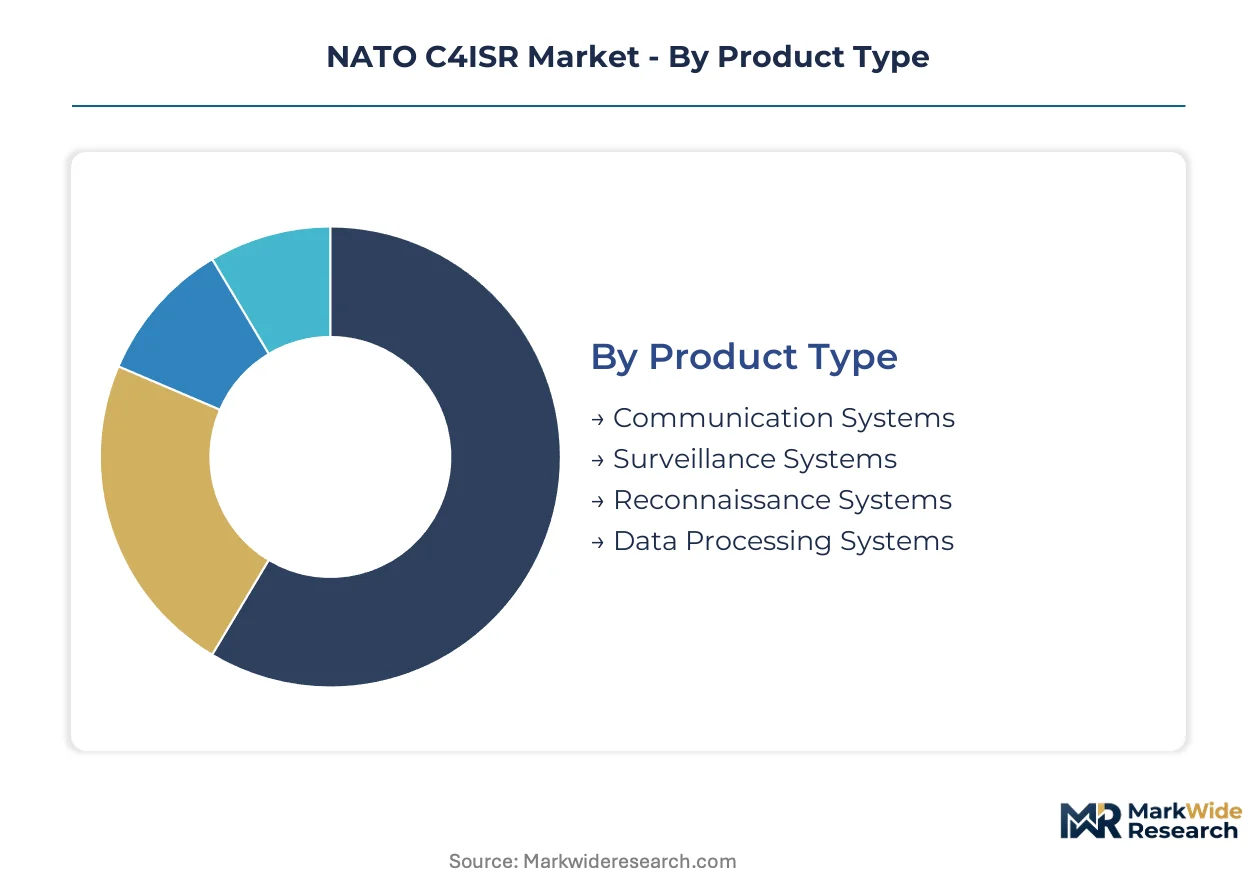
Segmentation in NATO C4ISR procurement reveals how capability investments cluster around interoperability mandates and sovereign data requirements. Understanding these divisions exposes where vendor qualification pathways diverge and where alliance-wide standardization creates concentrated demand windows.
Product Type:
After-sales-service intensity varies sharply across product categories, with software-intensive systems demanding continuous firmware updates and hardware platforms requiring field maintenance networks.
- Communication Systems:Encrypted tactical radios, satellite uplink terminals, and mesh networking hardware form the backbone of allied voice and data exchange. Demand concentrates in Germany and Poland as host nations for forward-deployed command structures, driven by STANAG interoperability refresh cycles and quantum-resistant encryption mandates.
- Surveillance Systems:Ground-based radar arrays, signals intelligence platforms, and electro-optical sensor networks deliver persistent battlespace monitoring. The United Kingdom and Norway prioritize these capabilities for maritime domain awareness in the North Atlantic, constrained by classification reciprocity gaps that fragment vendor access to classified tiers.
- Reconnaissance Systems:Unmanned aerial platforms and signals collection assets operating at extended ranges.
- Data Processing Systems:Secure cloud nodes and edge computing engines for tactical command centers.
By volume, Communication Systems leads. By growth pace, Data Processing Systems is ahead.
Technology:
Cost tier stratification separates mature capabilities with predictable procurement cycles from emerging technologies requiring extended certification timelines.
- AI & Machine Learning:Automated threat detection pipelines and predictive maintenance algorithms reduce operator cognitive load. French and Dutch defense ministries embed EU AI Act compliance checkpoints into milestone payments, extending development cycles but securing algorithmic transparency for coalition operations.
- Cybersecurity Technologies:Post-quantum cryptographic modules, zero-trust network architectures, and intrusion detection systems protect classified data flows. The United States DISA and UK Defence Science and Technology Laboratory enforce supplemental certification requirements that create vendor qualification bottlenecks.
- Cloud Computing:Distributed secure tenancy models for alliance-wide data sharing.
- Big Data Analytics:Multi-source intelligence fusion engines correlating satellite, signals, and human intelligence feeds.
By installed base, Cybersecurity Technologies dominates. By expansion trajectory, AI & Machine Learning is climbing the fastest.
End User:
Customer type determines contracting authority concentration, with centralized defense ministries bundling capabilities that service branches once procured separately.
- Military Forces:Operational commands requiring integrated battle management for kinetic and non-kinetic operations.
- Defense Agencies:Technical directorates managing capability development and interoperability certification.
- Government Contractors:System integrators and prime vendors executing large-scale command infrastructure deployments.
- Security Organizations:Intelligence services and law enforcement units with specialized data sovereignty requirements.
By contract value, Military Forces accounts for the largest share. By procurement velocity, Government Contractors is expanding most quickly.
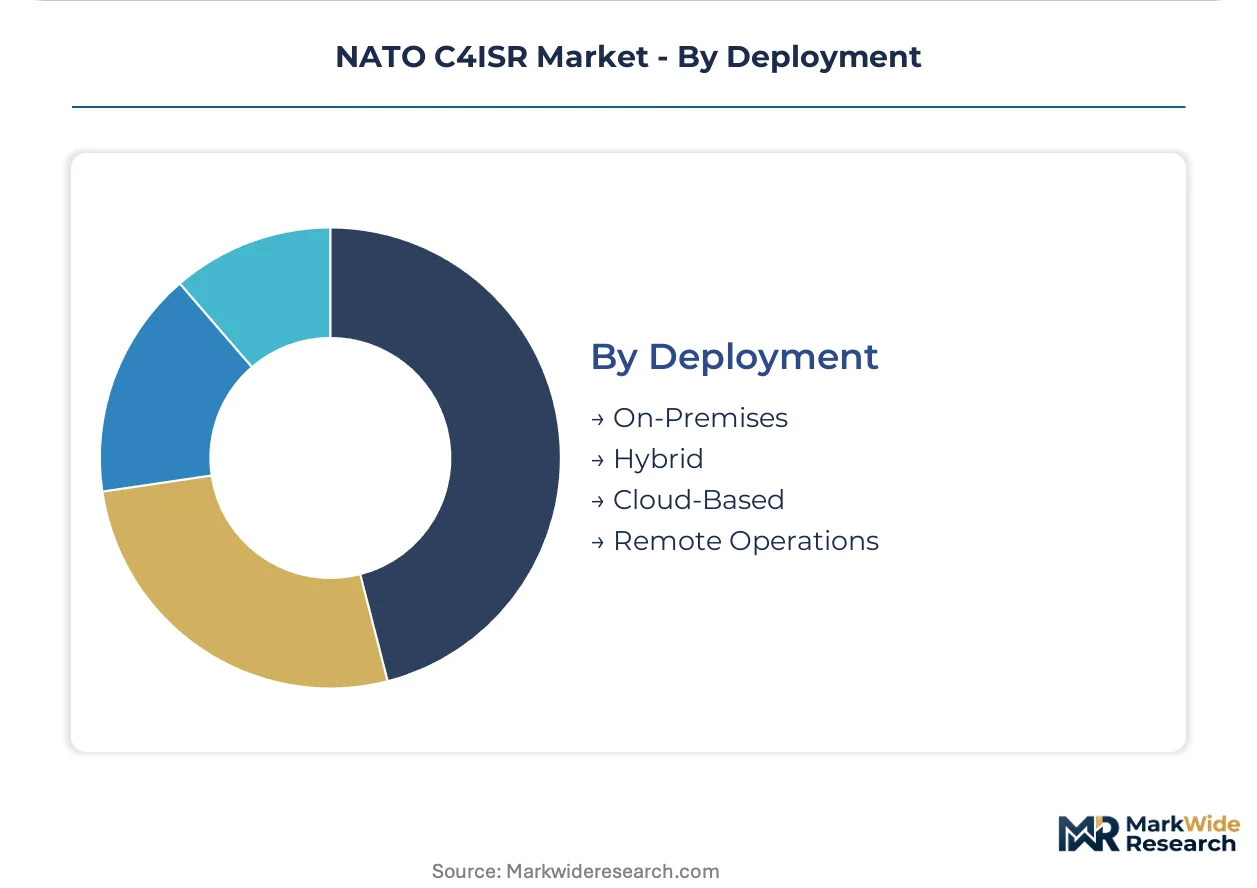
Deployment:
Supply concentration in secure cloud infrastructure favors vendors with existing national security clearances and data center presence in NATO member states.
- On-Premises:Air-gapped command centers for highest-classification operations with zero external connectivity.
- Hybrid:Architectures combining localized processing with burst capacity to sovereign cloud nodes.
- Cloud-Based:Multi-tenant secure environments enabling real-time intelligence sharing across allied commands.
- Remote Operations:Disconnected or intermittently connected tactical units operating in contested electromagnetic environments.
By current deployment share, Hybrid architectures lead. By transition momentum, Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DISA cybersecurity certification requirements anchor procurement pathways in the United States, while STANAG interoperability mandates synchronize refresh cycles across European host nations for allied command structures.
United States
Pentagon budget allocations for integrated battle management systems and quantum-resistant encryption upgrades drive procurement velocity. DISA evaluates vendor systems against evolving threat models for coalition cloud architectures. Virginia-based command centers host the primary integration hubs for NATO Allied Command Operations.
United Kingdom
Maritime domain awareness investments in the North Atlantic and nuclear deterrent modernization programs concentrate C4ISR demand. The Defence Science and Technology Laboratory enforces supplemental cybersecurity certifications that fragment vendor qualification pathways. Scotland hosts specialized signals intelligence processing facilities for allied operations.
Germany
Armored formation modernization and forward-deployed command structures in Eastern Europe accelerate sensor-network integration contracts. The country's national defense regulator coordinates STANAG compliance with sovereign data sovereignty requirements. Bavaria concentrates land systems engineering clusters for tactical communications hardware.
Poland
New NATO command structures for enhanced forward presence battlegroups create localized integration hub demand. EU AI Act risk classification frameworks reshape procurement specifications for autonomous systems deployed on the eastern flank. Warsaw anchors the regional coordination center for allied rapid response forces.
France
Multi-domain operations convergence and space-based surveillance capabilities drive system-of-systems contract categories. French defense ministries embed EU AI Act compliance checkpoints into milestone payment structures for algorithmic transparency. Toulouse hosts specialized aerospace clusters for satellite communications integration.
NATO C4ISR Market Vendor Landscape
Integrated systems primes and specialized tactical communications providers split the market along capability depth versus geographic proximity lines. The vendor base concentrates around defense ministry relationships rather than pure technology differentiation. Three archetypes dominate: North American battle management integrators, European communications specialists, and land systems engineering houses extending into sensor networks. Competitive moves center on multi-year platform-as-a-service bundling and quantum-resistant encryption certification racing.
Within the integrated systems tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent North American anchoring positions for large-scale command contracts. Thales Group and Rheinmetall AG exemplify European-based specialization patterns, with the former occupying tactical communications dominance and the latter extending land systems expertise into networked sensor architectures. These four entities sit within distinct qualification pathways shaped by national security clearance reciprocity and host-nation procurement preferences.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Thales Group |
| Northrop Grumman Corporation |
| Rheinmetall AG |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Leidos Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in quantum-resistant encryption module fabrication is compressing supplier margins while amplifying pricing power for certified vendors serving DISA and UK Defence Science and Technology Laboratory procurement channels. This utilization squeeze forces defense primes to pre-position component inventory, embedding carrying costs into long-term platform-as-a-service contracts.
Pricing Analysis
Price spreads between US and European procurement corridors widen where DISA cybersecurity certification adds qualification premiums unavailable to uncertified competitors. Three-tier pricing structure across STANAG-compliant, national-sovereignty, and commercial-off-the-shelf levels separates allied-interoperable systems from restricted national variants. Cost compression in tactical radio hardware intensifies as Polish and Baltic demand absorbs surplus legacy inventory. Defense agencies exhibit lowest price sensitivity due to mandate-driven refresh cycles, while smaller NATO contributors face budget constraints that delay procurement windows.
Supply Chain Analysis
Contract manufacturing for secure tactical radios concentrates in Germany, the United Kingdom, and selected US defense corridors where facility security clearances anchor production. Supply chains draw from gallium nitride semiconductors, rare-earth magnet assemblies, and radiation-hardened processors. Single-source vulnerability in classified cryptographic chip fabrication exposes programs to national export control disruptions. Distribution runs through defense ministry central procurement offices rather than service branch channels, consolidating vendor selection authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NATO C4ISR procurement operates as a defensive-moat market where regulatory entrenchment through DISA and national cybersecurity laboratory certification creates switching costs that lock out unqualified competitors. This structural barrier protects incumbents while constraining new entrant pathways.
For Market Incumbents: Harden certification portfolios against emerging quantum-resistant encryption mandates by accelerating pre-qualification submissions to DISA and UK Defence Science and Technology Laboratory backlogs. Deepen backward integration into secure cloud infrastructure to capture margin concentration in data processing systems, insulating against middleware development cost overruns in legacy system integration. For New Entrants and Emerging Players: Poland's eastern flank command structure expansion represents the most penetrable geographic entry point, with localized C4ISR integration hub demand outpacing established vendor capacity. Target EU Defence Fund collaborative procurement mechanisms to bypass national budget barriers among smaller member states, positioning for subcontractor roles in platform-as-a-service bundles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-as-a-service providers with decade-long defense ministry tenancy contracts. Long-term viability across the projection horizon favors vendors with dual expertise in military operations and secure cloud engineering. Monitor classification reciprocity agreement negotiations between member states as the signal for expanded vendor access to classified program tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Encryption Certification | DISA pre-qualification submission secures access to coalition cloud architecture contracts. |
| Platform-as-a-Service Bundling | British and Norwegian armed forces consolidate satellite communications and secure cloud tenancy under single-vendor decade terms. |
| EU Defence Fund Partnership | Collaborative procurement financing reduces national budget barriers for joint capability development. |
| Edge Computing Node Deployment | German armored formations field vehicle-mounted data fusion engines reducing contested satellite uplink dependence. |
| STANAG Compliance Investment | NATO Standardization Office protocol alignment synchronizes refresh cycles across member force procurement windows. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense ministry procurement disclosures, NATO Standardization Office protocol documentation, and national regulatory filing repositories. Primary interviews engaged program managers at allied command structures, defense ministry procurement directors, and systems integration engineers at prime contractors. Secondary validation incorporated DISA certification bulletins, EU Defence Fund award announcements, and customs trade data for tactical communications hardware. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Forecast inputs span product type refresh cycles, technology adoption velocity for AI-enabled threat detection, and deployment architecture transitions from on-premises to hybrid and cloud-based models. Segmentation dimensions include communication versus surveillance versus data processing systems, AI and machine learning versus cybersecurity versus cloud computing technologies, and military forces versus defense agencies versus government contractors as end users. CAGRs derive from fitted growth curves adjusted for procurement timeline compression under NATO's Digital Transformation Strategy.
Practitioners should monitor classification reciprocity agreement negotiations, quantum-resistant encryption mandate implementation schedules, and EU AI Act compliance checkpoint integration into milestone payment structures for early signals of competitive access shifts. Quarterly review of defense ministry central procurement office bundling decisions and DISA certification backlog clearance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Saudi Arabia C4ISR Market
ISR
Europe C5ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Airborne ISR Market
ISR
Australia C4ISR Market
ISR
C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Air Based C4ISR Market
ISR
North America C5ISR Market
ISR
Eastern Europe C4ISR Market
ISR
C6ISR Market
ISR
Low Altitude Radar Market
ISR
Asia-Pacific C4ISR Market
ISR
C5ISR Market