
 Brazil C4ISR Market | 2026-2036
Brazil C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil C4ISR Market Outlook
ABNT NBR ISO 9001 defense-sector certification is bifurcating the supplier landscape into qualified system integrators and peripheral component vendors. Lockheed Martin leverages its F-35 supply chain protocols to anchor high-complexity surveillance contracts with Brazilian defense agencies. Elbit Systems specializes in border monitoring architectures, sustaining R&D intensity through its Campinas engineering facility.
C4ISR denotes command, control, communications, computers, intelligence, surveillance, and reconnaissance systems integrating sensor fusion algorithms with secure datalinks operating across HF to Ka-band spectra for real-time battlespace awareness. The Surveillance application segment leads procurement volume as the Amazon monitoring program expands airborne radar coverage. Software solutions within the Solution dimension capture expanding margin pools as defense ministries shift from hardware ownership to subscription-based situational awareness platforms.
ANVISA cybersecurity frameworks and ABNT NBR IEC 61508 functional-safety standards constrain foreign system access while mandating local data residency for classified networks. The Brazilian Army's DGLOG logistics directorate enforces offset requirements that redirect procurement toward Embraer-domesticated supply chains. Stakeholders must monitor pending updates to the Lei de Contratações Públicas that could reshape bidding eligibility for integrated C4ISR packages.
Market Dynamics
ABNT NBR ISO 9001 defense-sector certification is bifurcating the supplier landscape into qualified system integrators and peripheral component vendors, concentrating procurement authority around certified primes while marginalizing uncertified subcontractors.
Growth Catalysts
- Submarine Modernization Program:The Brazilian Navy's PROSUB initiative drives integrated command system adoption across underwater platforms, requiring sensor fusion architectures that link sonar arrays with surface datalinks.
- ANVISA Cybersecurity Directives:Mandatory data residency requirements for classified networks reshape procurement standards, compelling foreign vendors to establish local server infrastructure and domestic engineering presence.
- Amazon Airborne Radar Expansion:Surveillance missions over the Legal Amazon region accelerate Ka-band radar deployment, creating sustained demand for synthetic aperture processing and real-time ground station integration.
Market Restraints
- Offset Requirements:The Brazilian Army's DGLOG logistics directorate enforces local content thresholds that redirect procurement toward Embraer-domesticated supply chains, limiting direct foreign vendor participation.
- Functional-Safety Certification Costs:ABNT NBR IEC 61508 compliance mandates SIL-rated component sourcing, inflating subsystem costs by requiring redundant architectures and extended validation cycles.
- HF Spectrum Congestion:Legacy military frequency allocations overlap with commercial maritime traffic, constraining secure datalink bandwidth for over-the-horizon communications in coastal defense applications.
Strategic Opportunities
- Subscription-Based Situational Awareness:Defense ministries are migrating from hardware ownership to software-as-a-service platforms, opening recurring revenue streams for cloud-hosted C2 architectures.
- Border Monitoring Architectures:Unattended ground sensor networks along the Paraguay and Bolivia frontiers present white space for integrated electro-optical and seismic detection systems with mesh networking protocols.
- Campinas Engineering Cluster:The São Paulo state technology corridor offers established aerospace talent pools for R&D-intensive surveillance subsystem development, reducing reliance on imported technical labor.
Industry Challenges
- Embedded Systems Security Clearance Pipeline:ANVISA-mandated personnel vetting for classified network access creates 18-month onboarding bottlenecks, constraining delivery velocity for integrated programs.
- Legacy Platform Integration Complexity:Existing SICLODA army command systems require custom protocol bridges to interface with modern IP-based architectures, extending deployment timelines and testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil C4ISR Market |
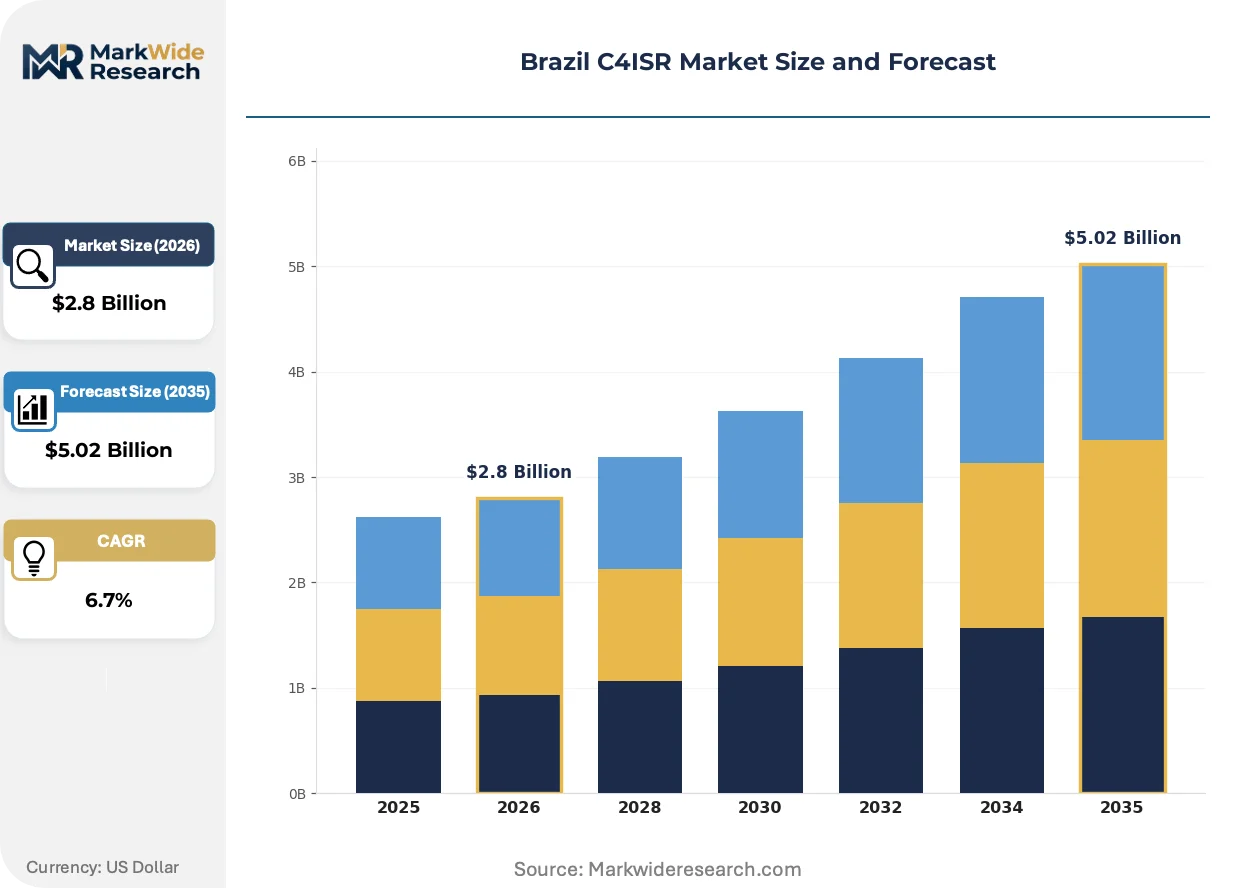
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radio, Satellite, Radar, Communications End User: Military, Government, Defense Contractors, Security Agencies Application: Surveillance, Reconnaissance, Command Control, Intelligence Gathering Solution: Software, Hardware, Integrated Systems, Cloud Solutions |
| Companies Covered | Lockheed Martin Corporation, Embraer SA, Elbit Systems Ltd, Northrop Grumman Corporation, Saab AB, Raytheon Technologies, Thales Group, BAE Systems, Leonardo S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil C4ISR Market Strategic Shifts
Sensor fusion algorithms operating across HF to Ka-band spectra are compressing decision cycles for real-time battlespace awareness, while procurement frameworks pivot toward capability-based contracting that decouples hardware from software refresh timelines.
Edge-deployed AI inference engines for target classification are bifurcating processing architectures between centralized cloud analytics and distributed onboard computation. Naval aviation units are adopting these systems for submarine-hunting missions, prioritizing low-latency track identification over bandwidth-heavy raw data transmission. This compression of the compute layer is displacing legacy ground-station dependency for time-critical targeting workflows.
ANVISA cybersecurity frameworks now mandate local data residency for classified networks, compelling foreign system vendors to establish domestic server infrastructure and engineering presence. This regulatory friction is segmenting the supplier base into compliant integrators with certified facilities and non-compliant vendors restricted to unclassified subsystems. The surveillance application segment bears the heaviest compliance burden, as airborne radar platforms generate the highest classification volumes requiring domestic storage.
Capability-based service contracts are displacing traditional hardware acquisition for C2 software platforms, unbundling perpetual licenses from maintenance and upgrade cycles. The Brazilian Navy's integrated command programs are leading this transition, subscribing to situational awareness dashboards rather than owning on-premise server infrastructure. Rio de Janeiro's naval-industrial cluster around Itaguaí shipyard exhibits the most advanced adoption, with shipboard systems increasingly provisioned through annual service agreements rather than capital expenditure procurement.
Brazil C4ISR Market Segmentation
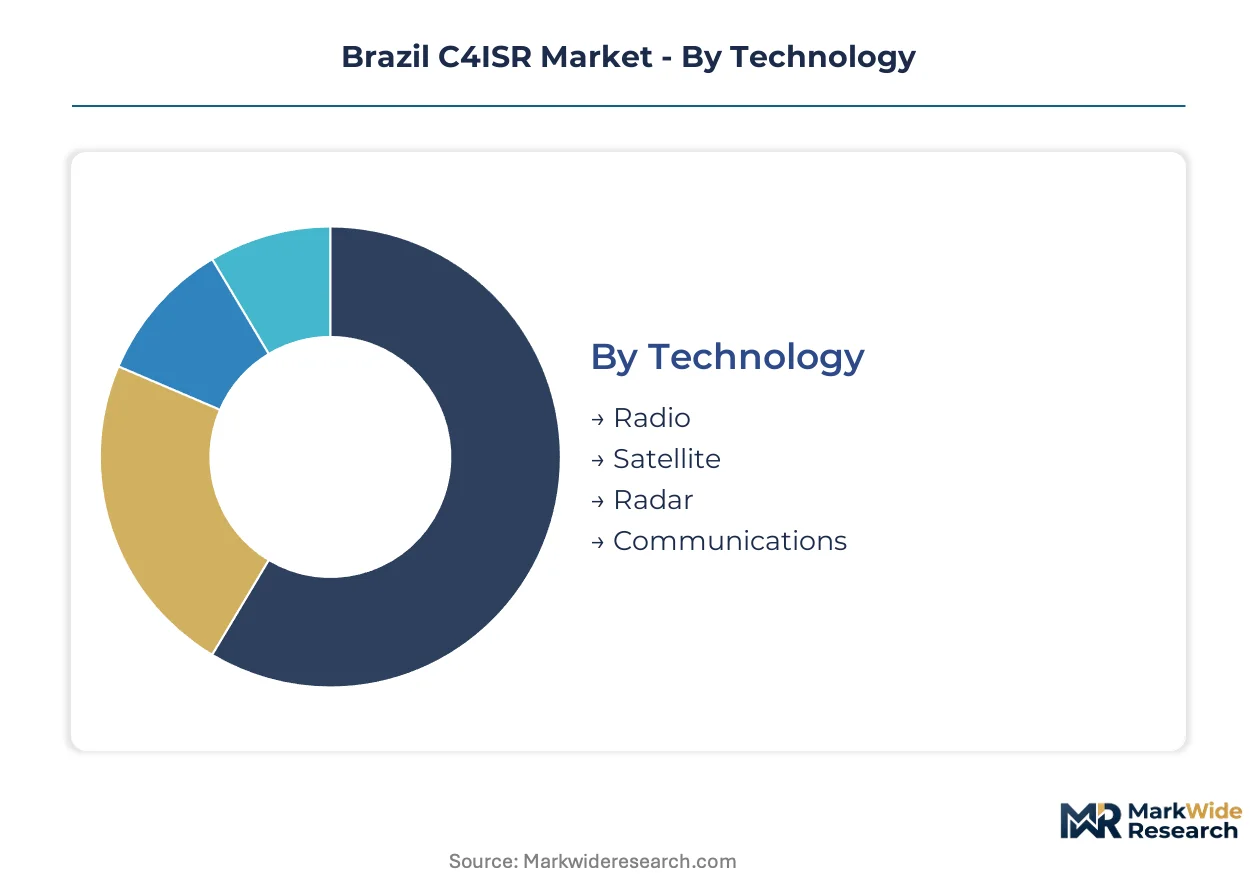
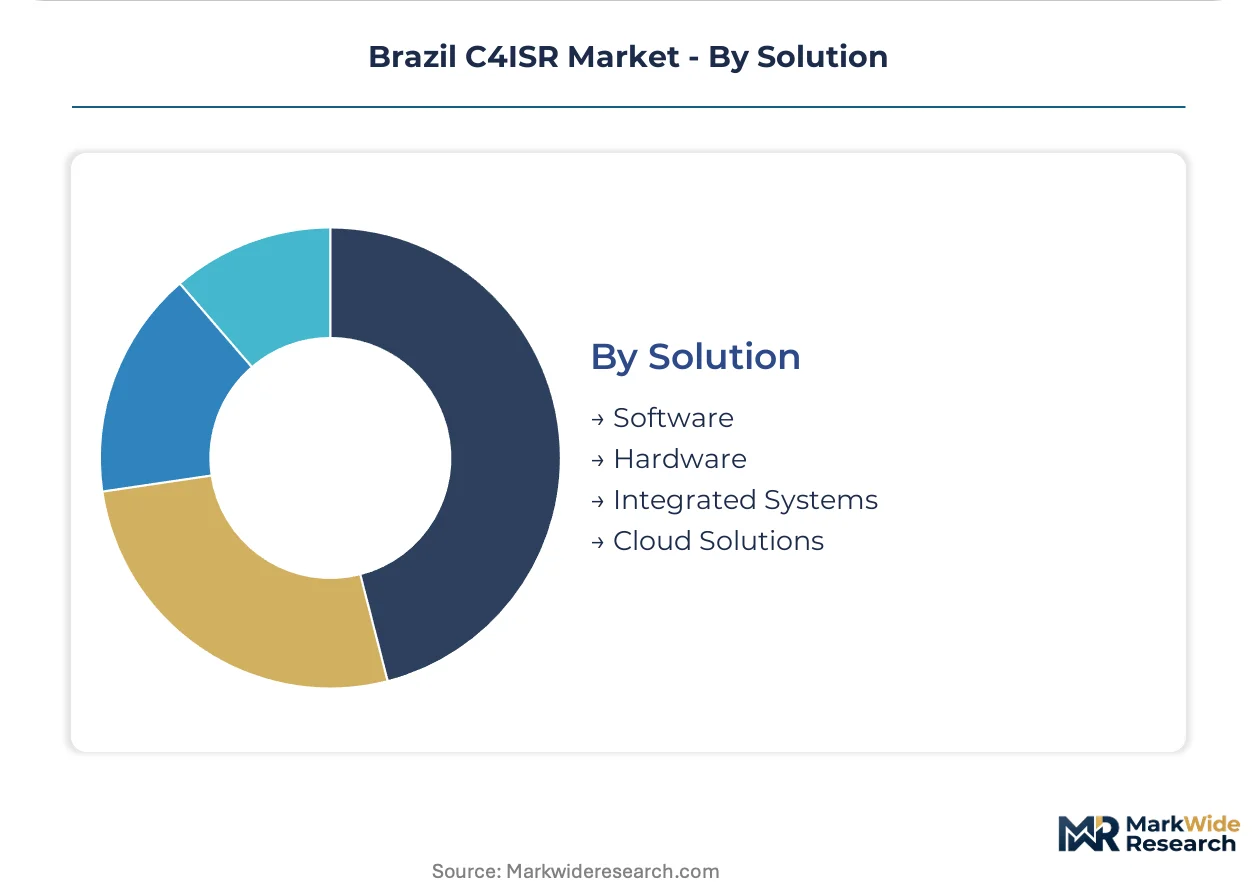
Segmentation reveals how procurement authority concentrates around certified system integrators while margin pools shift from hardware ownership toward recurring software platforms. Understanding these structural divisions clarifies where ANVISA compliance costs and ABNT certification barriers reshape competitive positioning across the Brazilian defense electronics landscape.
Technology:
Margin concentration follows the complexity gradient from commoditized radio equipment toward sensor fusion architectures requiring specialized waveform engineering.
- Radar:Synthetic aperture and phased-array systems dominate surveillance procurement for Amazon airborne coverage. Demand clusters around Rio de Janeiro's naval-industrial complex, where PROSUB submarine programs require integrated sonar-radar fusion for surface-subsurface threat correlation.
- Satellite:Ka-band secure datalinks and military communications constellations command premium pricing through proprietary waveform protocols. Procurement concentrates with the Brazilian Navy's integrated command initiatives, driven by ANVISA-mandated local ground station infrastructure.
- Radio:HF to UHF tactical communications equipment faces spectrum congestion constraints along coastal defense corridors.
- Communications:Mesh networking protocols for unattended ground sensors gain traction along Paraguay and Bolivia border monitoring architectures.
The dominant share belongs to Radar, while Satellite is closing the gap fastest.
End User:
Volume procurement authority cascades from military branches through logistics directorates with offset enforcement power toward security agencies with narrower technical mandates.
- Military:The Brazilian Navy's PROSUB program and Army's SICLODA modernization drive integrated C4ISR adoption across underwater and ground platforms. Rio de Janeiro's Itaguaí shipyard complex anchors naval demand, constrained by DGLOG offset requirements redirecting procurement toward Embraer-domesticated supply chains.
- Government:Federal coordination bodies manage cross-branch situational awareness platforms with ANVISA cybersecurity compliance overhead. Demand centers on classified network infrastructure requiring local data residency and 18-month personnel vetting pipelines.
- Defense Contractors:System integrators with ABNT NBR ISO 9001 certification capture prime contractor status, marginalizing peripheral component vendors.
- Security Agencies:Border monitoring units deploy unattended ground sensor networks with lower classification thresholds and faster procurement cycles.
Military branches command the largest procurement volume, though Government coordination bodies are expanding their platform integration role most rapidly.
Application:
Revenue expansion correlates with classification intensity, where surveillance missions generate recurring data processing demand versus discrete hardware acquisition.
- Surveillance:Amazon airborne radar expansion and maritime domain awareness missions sustain Ka-band deployment with synthetic aperture processing requirements. The Legal Amazon program drives sustained demand for real-time ground station integration across Roraima and Pará operational areas.
- Intelligence Gathering:Multi-source fusion platforms integrating signals intelligence with imagery analysis command premium margins through subscription-based delivery models. Brazilian Navy integrated command programs lead adoption of cloud-hosted situational awareness dashboards.
- Reconnaissance:Tactical unmanned systems and special operations platforms require portable sensor packages with edge-deployed AI inference.
- Command Control:Legacy SICLODA army systems demand custom protocol bridges for IP-based modernization, extending deployment timelines.
Surveillance maintains the largest installed base, while Intelligence Gathering is climbing the fastest as ministries migrate toward software-as-a-service architectures.
Solution:
Commercial models are bifurcating between capital-intensive hardware ownership and recurring-revenue platforms that decouple capability refresh from asset replacement cycles.
- Software:Situational awareness dashboards and sensor fusion algorithms capture expanding margin pools through annual subscription contracts. The Brazilian Navy's integrated command programs provision shipboard systems via service agreements rather than capital expenditure, concentrated in Rio de Janeiro's Itaguaí cluster.
- Cloud Solutions:Domestic server infrastructure mandated by ANVISA cybersecurity frameworks creates compliance moats for certified integrators with local engineering presence.
- Hardware:Radio terminals, radar arrays, and satellite ground stations face procurement compression as ministries prioritize capability-based service contracts.
- Integrated Systems:Full-stack C4ISR packages requiring ABNT NBR IEC 61508 functional-safety certification concentrate with qualified primes absorbing SIL-rated component costs.
Software solutions are gaining share fastest from hardware-centric procurement, while Integrated Systems retain the largest contract value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA cybersecurity mandates and ABNT certification requirements are reshaping procurement geography across Brazilian defense electronics. Regional demand clusters around naval-industrial complexes and aerospace engineering corridors with established compliance infrastructure.
Rio de Janeiro
The Itaguaí shipyard complex anchors Brazil's submarine modernization program, driving integrated command system procurement for PROSUB underwater platforms. ANVISA data residency requirements compel foreign vendors to establish local server infrastructure here. The naval-industrial cluster concentrates sensor fusion development for surface-subsurface threat correlation.
São Paulo
Campinas hosts Elbit Systems' engineering facility sustaining R&D intensity for border monitoring architectures. The state's technology corridor supplies aerospace talent pools for surveillance subsystem development. ABNT NBR ISO 9001 certification pipelines concentrate here, bifurcating qualified integrators from peripheral vendors.
Brasília
The federal district coordinates cross-branch situational awareness platforms through government coordination bodies. ANVISA cybersecurity frameworks mandate local data residency for classified networks originating here. DGLOG logistics directorate offset requirements redirect procurement decisions toward Embraer-domesticated supply chains.
Amazon Region
Roraima and Pará operational areas sustain airborne radar deployment for Legal Amazon surveillance missions. Ka-band synthetic aperture processing demand concentrates in forward operating locations with real-time ground station integration. Lower classification thresholds here enable faster procurement cycles for unattended ground sensor networks.
Rio Grande do Sul
Southern border monitoring architectures with Paraguay deploy electro-optical and seismic detection systems. Mesh networking protocols for unattended ground sensors gain traction in frontier security applications. Regional procurement operates under reduced ANVISA compliance burdens compared to classified naval programs.
Brazil C4ISR Market Competitive Environment
Listed defense conglomerates compete with private specialists across certification tiers, concentrating procurement authority around ABNT-qualified system integrators. The supplier landscape bifurcates between certified primes absorbing SIL-rated component costs and uncertified subcontractors restricted to peripheral hardware. Three archetypes dominate: multinational platform integrators leveraging F-35 supply chain protocols, domestic aerospace champions capturing offset-mandated procurement, and Israeli surveillance specialists with established local engineering presence. Competitive moves center on strategic partnerships with Embraer-domesticated supply chains and technology licensing arrangements satisfying DGLOG local content thresholds.
Within the multinational integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform-scale vendors navigating ANVISA compliance through domestic infrastructure investments. Elbit Systems Ltd. anchors the surveillance specialization vector, occupying a position shaped by its Campinas engineering footprint. These three represent contrasting geographic origins—American conglomerates versus Israeli specialists—while each sits within distinct competitive archetypes shaped by certification access and local partnership depth.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Embraer SA |
| Elbit Systems Ltd |
| Northrop Grumman Corporation |
| Saab AB |
| Raytheon Technologies |
| Thales Group |
| BAE Systems |
| Leonardo S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month personnel vetting pipelines for ANVISA-mandated security clearances compress supplier margins by extending project timelines while concentrating pricing power among certified integrators with established clearance infrastructure. This lead-time bottleneck reinforces a bifurcated supply structure where ABNT NBR ISO 9001-qualified primes capture premium contract values and uncertified vendors compete on commoditized component supply.
Pricing Analysis
Certification level creates the primary spread across the supplier landscape, with ABNT NBR IEC 61508 SIL-rated system integrators commanding three-tier pricing structure across premium, standard, and economy levels tied to functional-safety compliance depth. Subscription-based situational awareness platforms are displacing perpetual hardware licenses, compressing upfront capital recovery while expanding recurring revenue attachment. Cost compression in standard-tier radio equipment intensifies because HF spectrum congestion reduces differentiation leverage. Government coordination bodies exhibit lowest price sensitivity given ANVISA compliance mandates, while security agencies operating in Amazon border regions prioritize procurement velocity over certification premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate for SIL-rated components and Ka-band radar subsystems given ABNT validation cycles and single-source vulnerabilities in synthetic aperture processing chipsets. Manufacturing concentration rests on the United States for secure waveform protocols, Israel for electro-optical sensor packages, and domestic Brazilian facilities for ANVISA-compliant server infrastructure. Raw material dependencies include gallium nitride semiconductors for phased-array radar, rare earth magnets for precision gimbal systems, and specialized aluminum-lithium alloys for airborne platforms. Tariff exposure runs through ITAR-controlled US technology transfers. Distribution runs through Embraer-domesticated supply chains mandated by DGLOG offset requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazilian C4ISR market structures around service-attach opportunity, where software-as-a-service situational awareness platforms expand recurring revenue pools faster than hardware ownership models. Annual subscription contracts for cloud-hosted command architectures now outpace capital expenditure procurement velocity across Navy integrated command programs.
For Market Incumbents: Shield installed base relationships by deepening ABNT NBR ISO 9001 certification barriers and embedding proprietary sensor fusion protocols into PROSUB submarine modernization workflows. Counter emerging SaaS-native entrants through long-term service agreements that bundle hardware refresh cycles with software maintenance. Prioritize vertical integration into Campinas engineering talent pools to reduce imported technical labor dependency.
For New Entrants and Emerging Players: Differentiate on rapid ANVISA compliance completion, targeting 12-month security clearance pipelines versus incumbent 18-month benchmarks. Penetrate Amazon border monitoring architectures where lower classification thresholds enable faster procurement cycles and unattended ground sensor networks present white-space demand. Pursue technology licensing arrangements with Embraer that satisfy DGLOG local content thresholds without full system integration burden.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational defense conglomerates divesting non-core C4ISR units lacking Brazilian certification infrastructure. Five-to-ten-year viability favors integrators with domestic server facilities and established ANVISA relationships over hardware-centric vendors. Monitor PROSUB program milestone acceleration as inflection indicator for integrated command system procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Compliance Infrastructure Buildout | Domestic server facilities create procurement moats for classified network contracts. |
| Subscription-Based C2 Platform Migration | Brazilian Navy programs shift from capex to annual service agreements. |
| Campinas Engineering Cluster Expansion | R&D talent pools reduce reliance on imported technical labor. |
| Embraer Supply Chain Partnership | DGLOG offset requirements redirect procurement toward domesticated channels. |
| Border Monitoring Architecture Deployment | Paraguay and Bolivia frontiers drive unattended ground sensor network demand. |
Study Parameters
A spread of perspectives from submarine program directors, ANVISA compliance officers, DGLOG procurement leads, and Campinas engineering facility managers converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation through Brazilian Navy budget disclosures, ANVISA regulatory filings, ABNT certification registries, and Embraer supply chain documentation. Bottom-up segment sizing across technology, end user, application, and solution dimensions triangulated against top-down defense expenditure allocation models.
Segmentation dimensions modeled include command system complexity tiers, platform integration depth, classification level requirements, and regional procurement authority distribution across the analysis window. CAGRs derive from weighted scenario analysis incorporating PROSUB program milestone schedules, Amazon surveillance mission expansion rates, and ANVISA framework update probabilities. Forecast inputs incorporate sensor fusion algorithm deployment velocity and cloud-hosted platform adoption curves specific to naval integrated command architectures.
The analysis sits within stated boundaries; outcomes outside sustained PROSUB funding commitment or accelerated ANVISA personnel vetting reform would require recalibration. Forecasts reflect documented assumptions regarding DGLOG offset enforcement continuity and Ka-band spectrum allocation stability. Revision becomes warranted when ABNT certification timeline compression crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Synthetic Aperture Radar (SAR) Market
ISR
C4ISR Market
ISR
United States C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Low Altitude Radar Market
ISR
Europe C5ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Japan C4ISR Market
ISR
Airborne ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Land Based C4ISR Market
ISR
North America C5ISR Market
ISR
IFF System Market
ISR
Naval ISR Market
ISR
C6ISR Market
ISR
Australia C4ISR Market