
 Asia-Pacific C4ISR Market | 2026-2036
Asia-Pacific C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific C4ISR Market Outlook
Artificial intelligence integration into sensor fusion architectures is reshaping how C4ISR platforms process multi-domain intelligence in real time. Lockheed Martin leverages its satellite communications heritage to anchor Australia's AUKUS-linked undersea surveillance networks. Northrop Grumman sustains technology leadership in autonomous systems through its specialized unmanned platforms for maritime patrol. THALES competes aggressively in Southeast Asian naval modernization by offering localized electronic warfare suites tailored to archipelagic operating environments.
C4ISR denotes the integrated military framework combining command, control, communications, computers, intelligence, surveillance, and reconnaissance into unified operational networks, typically operating across frequencies from HF through Ka-band with hardened encryption protocols and sub-millisecond latency requirements for time-critical targeting. The primary purpose is collapsing the sensor-to-shooter timeline while maintaining decision superiority across air, land, sea, space, and cyber domains. Radar and satellite communication technologies dominate current procurement budgets due to their foundational role in area denial strategies, while cybersecurity represents the fastest-expanding segment as militaries confront escalating electronic and cyber threats against networked battle management systems. Deployment architecture is shifting decisively toward hybrid and edge computing configurations that enable continued operations in contested electromagnetic environments where cloud connectivity cannot be assured.
Japan's METI coordinates defense technology export frameworks that shape how foreign C4ISR vendors access domestic procurement channels, while Australia's Defense Trade Controls Act governs technology transfer limitations affecting AUKUS partner collaboration. India's Ministry of Defence implements offset requirements and indigenous content mandates through the Defence Acquisition Procedure that condition market access for foreign system integrators. Stakeholders must monitor how evolving technology transfer agreements between Australia, the United Kingdom, and the United States reshape supplier qualification pathways across the broader Asia-Pacific defense industrial base.
Market Dynamics
Hybrid edge computing architectures are compressing decision timelines across Asia-Pacific defense networks, forcing system integrators to redesign hardware-software stacks for contested electromagnetic environments where satellite uplinks face persistent jamming threats.
Growth Catalysts
- Japan's Defense Build-Up Program:Tokyo's accelerated standoff defense investments are generating procurement pipelines for integrated battle management systems spanning air and maritime domains.
- Electronic warfare modernization:Southeast Asian navies are prioritizing localized EW suites for archipelagic operations, creating demand for modular, frequency-agile countermeasure platforms.
- AUKUS technology transfer frameworks:The trilateral Australia-UK-US agreement is unlocking submarine and undersea surveillance capability upgrades across Australian defense infrastructure.
Market Restraints
- GaN and GaAs component supply concentration:Foundry capacity for high-frequency semiconductors remains concentrated in East Asian manufacturing hubs, exposing procurement timelines to single-source vulnerabilities.
- India's indigenous content mandates:The Defence Acquisition Procedure imposes strict offset requirements that complicate foreign system integrator participation in domestic platform development.
- Legacy analog integration burdens:Existing HF and VHF communication networks across regional militaries resist seamless digital overlay without complete infrastructure replacement.
Strategic Opportunities
- India's Make in India framework:Indigenous C4ISR platform development programs offer partnership pathways for foreign vendors willing to establish domestic production and technology sharing arrangements.
- AI-sensor fusion convergence:Machine learning integration with multi-spectral surveillance arrays creates white space for real-time threat classification in maritime patrol applications.
- Sub-regional maritime surveillance gaps:Indonesia and Vietnam maintain underinvested coastal monitoring networks vulnerable to gray-zone maritime coercion, opening procurement windows for integrated coastal radar and UAV systems.
Industry Challenges
- Cleared workforce scarcity:Security clearance processing timelines for software engineers and systems architects lag program schedules across Australian and Japanese defense projects.
- Interoperability certification complexity:Multi-national exercises expose protocol mismatches between US, Australian, Japanese, and Indian tactical data links, requiring expensive middleware development.
- Cyber-physical system hardening:Networked battle management architectures face escalating supply chain penetration risks that demand continuous firmware attestation and zero-trust architecture retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific C4ISR Market |
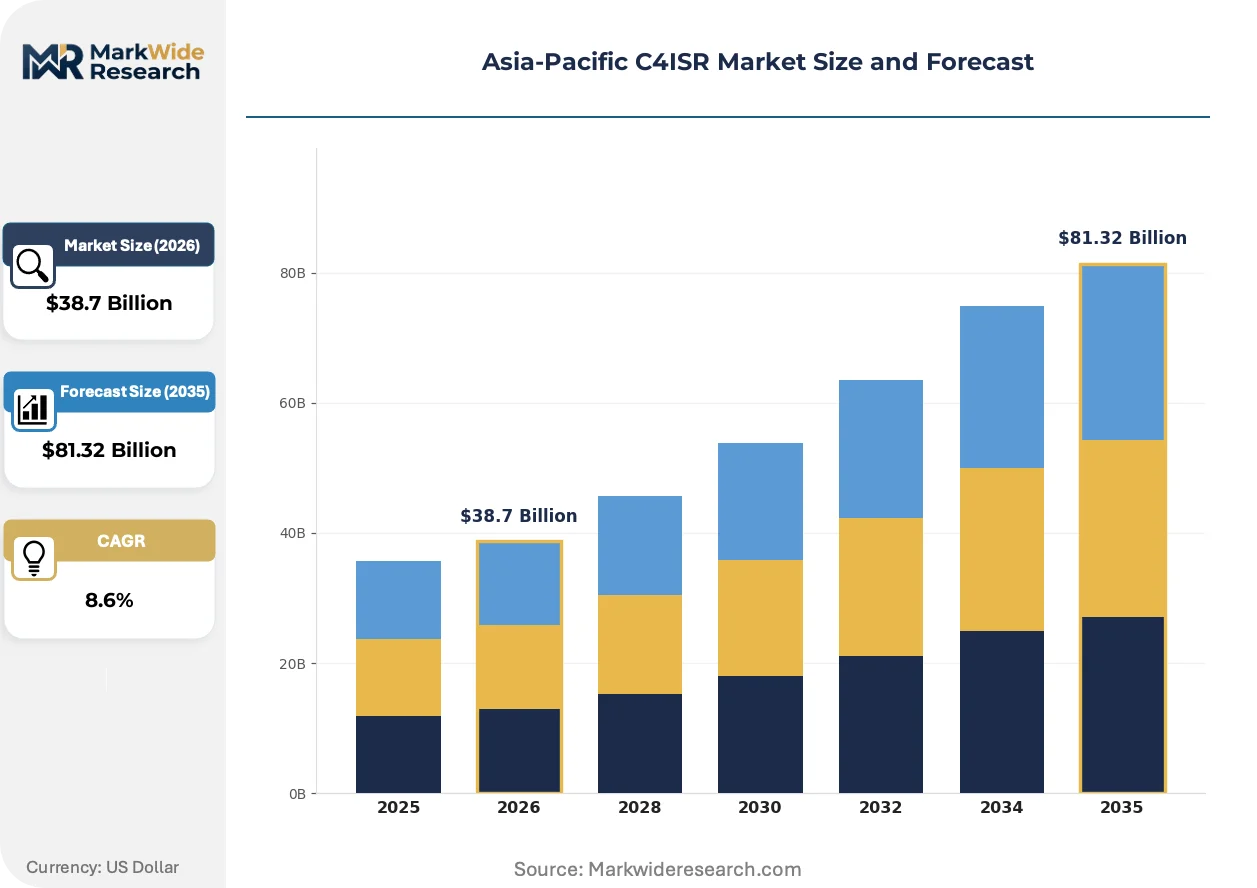
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Satellite Communication, Cybersecurity, Sensors End User: Government, Military, Defense Contractors, Intelligence Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Surveillance, Reconnaissance, Command Control, Communication |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies Corporation, BAE Systems plc, THALES, General Dynamics Corporation, Elbit Systems Ltd., L3Harris Technologies, Inc., Saab AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific C4ISR Market Strategic Shifts
Software-defined radio and cognitive electronic warfare systems are displacing hardware-fixed architectures across Asia-Pacific tactical networks, enabling frequency agility that outpaces adversary jamming capabilities without platform replacement cycles.
Virtualized ground station infrastructure is virtualizing satellite control and data processing functions previously locked to fixed earth terminals. Japanese and Australian operators are deploying containerized mission applications on tactical edge servers. This compression of ground segment hardware is virtualizing supplier ecosystems, allowing defense agencies to source software capabilities from non-traditional vendors without antenna farm construction.
Australia's Defense Trade Controls Act is tightening technology transfer oversight for AUKUS-linked collaboration, creating compliance friction for subsystem suppliers seeking trilateral market access. The legislation's extraterritorial reach is forcing UK and US vendors to restructure Australian subsidiary governance. Maritime surveillance and undersea warfare segments bear the heaviest administrative burden as these categories trigger mandatory control assessments.
Consolidated program management offices are supplanting discrete system procurement across regional defense ministries. Australia's AUKUS integration demands and Japan's standoff defense consolidation are compressing vendor relationship structures from transactional equipment sales to multi-decade platform sustainment partnerships. This behavioral shift concentrates contract value with integrators capable of delivering through-life capability management rather than point solutions.
Asia-Pacific C4ISR Market Segmentation
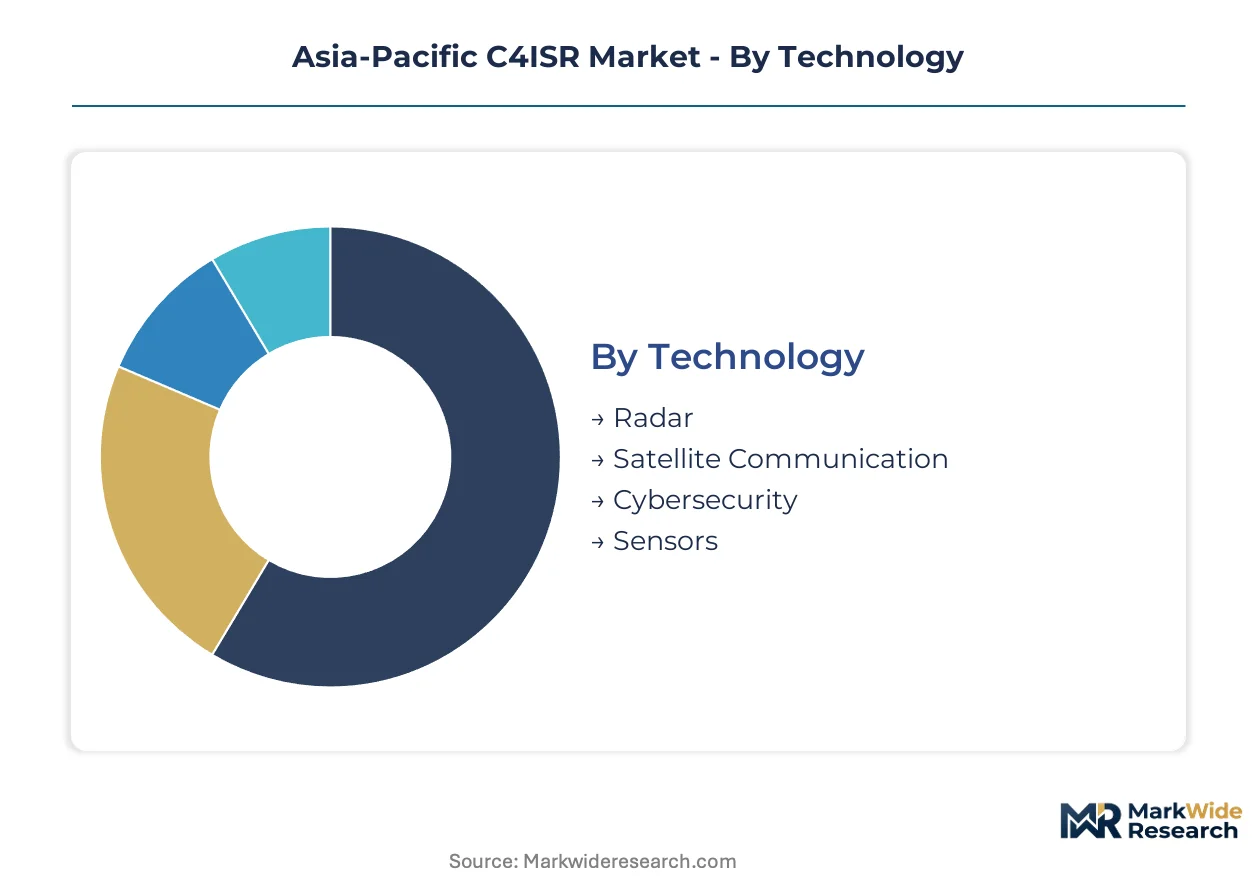
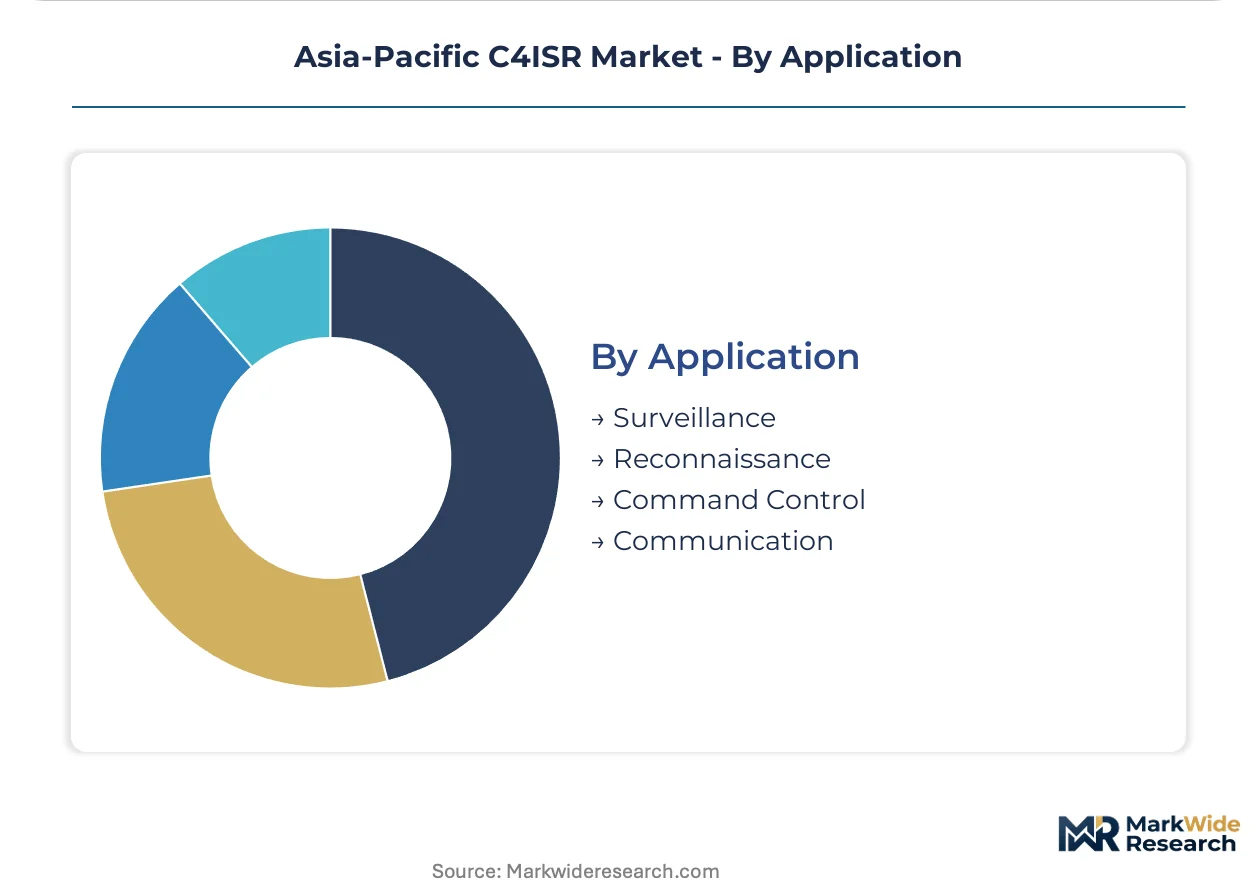
C4ISR procurement across Asia-Pacific fragments along technology maturity curves and operational deployment models. Understanding these segment boundaries clarifies where defense budgets concentrate versus where emerging capabilities disrupt established supplier relationships.
Technology:
Mature electronic warfare platforms coexist with emerging AI-driven sensor architectures across regional procurement pipelines.
- Radar:Active electronically scanned arrays dominate airborne and maritime surveillance programs. Australia's AUKUS-linked surface fleet modernization and Japan's standoff defense investments anchor regional demand for multi-band phased array systems.
- Satellite Communication:Military Ka-band and X-band terminals form the backbone of beyond-line-of-sight connectivity. Australian undersea surveillance networks and Japanese remote island defense posts drive procurement of hardened, low-probability-of-intercept terminals.
- Cybersecurity:Zero-trust architectures for battle management networks represent the fastest-expanding budget line as militaries confront supply chain penetration risks.
- Sensors:Multi-spectral electro-optical and infrared packages integrate with unmanned platforms for maritime patrol applications.
Radar retains volume leadership; cybersecurity holds the steepest expansion curve.
End User:
Procurement authority concentrates in sovereign defense ministries, though contractor-led system integration is gaining ground.
- Military:Service-specific commands across Australia's ADF, Japan's JSDF, and India's armed services drive platform-centric C4ISR acquisition. Maritime surveillance and integrated air defense networks absorb the dominant share of capital allocation.
- Government:National security agencies and defense ministries manage cross-domain architecture standards. Australia's Defence Trade Controls Act and India's Defence Acquisition Procedure shape how foreign vendors access these channels.
- Defense Contractors:System integrators increasingly operate as prime contractors under through-life capability management contracts rather than transactional equipment sales.
- Intelligence Agencies:Signals intelligence and cyber operations units procure specialized intercept and analysis platforms outside standard defense procurement frameworks.
Military end users command the largest absolute spend; defense contractors are capturing share fastest through consolidated program management structures.
Deployment:
Architecture decisions increasingly prioritize continued operations in contested electromagnetic environments over cost optimization.
- Hybrid:Split processing between secure cloud infrastructure and tactical edge nodes dominates new program specifications. Australian and Japanese operators deploy containerized mission applications that maintain functionality when satellite uplinks face jamming.
- Edge Computing:Hardened servers aboard ships, aircraft, and forward ground stations compress sensor-to-shooter timelines. Real-time target classification algorithms run locally without cloud dependency.
- On-Premises:Legacy command centers and fixed headquarters retain conventional server infrastructure for administrative and planning functions.
- Cloud-Based:Non-tactical applications including logistics, training, and peacetime intelligence analysis migrate to sovereign cloud environments.
Hybrid deployment anchors new procurement; edge computing climbs the fastest as contested environment requirements harden.
Application:
Functional priorities reflect geographic imperatives—maritime domain awareness dominates archipelagic nations while integrated air defense preoccupies continental powers.
- Surveillance:Coastal radar networks and unmanned maritime patrol systems address gray-zone coercion risks across Indonesia's and Vietnam's undermonitored archipelagos. Integrated wide-area coverage demands fuse data from shore stations, patrol aircraft, and satellite constellations.
- Command Control:Battle management systems integrating air, maritime, and ground domain awareness represent the highest-value procurement category. Japan's standoff defense consolidation and Australia's AUKUS integration drive demand for unified operational pictures.
- Reconnaissance:Deep-targeting capabilities for long-range precision strike missions absorb growing investment under Japan's Defense Build-Up Program.
- Communication:Resilient tactical data links connecting dispersed forces resist electronic attack through frequency agility and mesh networking protocols.
Command control absorbs the largest program value; surveillance expands most quickly as Southeast Asian coastal monitoring gaps drive urgent procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement authorities across the Asia-Pacific concentrate spending in maritime surveillance and integrated battle management systems, with national security frameworks conditioning foreign vendor access to domestic programs.
Japan
Standoff defense investments under the Defense Build-Up Program are accelerating procurement of unified air and maritime domain awareness systems. METI coordinates defense technology export frameworks that shape how foreign C4ISR vendors access domestic procurement channels. Tokyo and the surrounding Kanto region host the concentration of systems integration activity for next-generation command architectures.
Australia
AUKUS-linked submarine and undersea surveillance capability upgrades are reshaping capability requirements across the Australian Defence Force. The Defense Trade Controls Act governs technology transfer limitations affecting trilateral partner collaboration. Adelaide and Perth anchor the industrial concentration for maritime platform integration and sustainment partnerships.
India
Indigenous C4ISR platform development under the Make in India framework is conditioning market access for foreign system integrators. The Ministry of Defence implements offset requirements and indigenous content mandates through the Defence Acquisition Procedure. Bengaluru and Hyderabad host the emerging clusters for domestic defense electronics manufacturing and software development.
South Korea
KF-21 fighter and next-generation destroyer programs are driving integrated sensor and battle management procurement. The country's national defense procurement agency manages technology transfer requirements for foreign subsystem suppliers. Seoul and the surrounding Gyeonggi Province concentrate defense electronics manufacturing and systems engineering capacity.
Singapore
Smart Nation defense digitalization initiatives are prioritizing AI-enabled command decision support and cyber-resilient communications networks. The national technology agency coordinates sovereign capability development in sensor fusion and autonomous systems. The island city-state functions as a regional hub for Southeast Asian naval modernization program coordination and technology demonstration.
Asia-Pacific C4ISR Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered market structure where multi-decade platform sustainment contracts concentrate value with integrators capable of through-life capability management. System integrators with satellite communications heritage anchor undersea surveillance networks, while specialists in autonomous systems sustain technology leadership in unmanned maritime patrol platforms. Competitive moves center on strategic partnerships for localized production and technology licensing arrangements that satisfy indigenous content mandates.
Within the integrated systems tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the channel-controlling archetype, occupying positions that leverage heritage capabilities in satellite communications and autonomous platforms respectively. THALES represents the European specialist model, competing through localized electronic warfare suites tailored to archipelagic operating environments. These three anchors illustrate how vendor positioning stratifies between scale-driven integrators and geography-focused specialists.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| BAE Systems plc |
| THALES |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| L3Harris Technologies, Inc. |
| Saab AB |
| Others |
Value Chain & Pricing Dynamics
GaN and GaAs foundry concentration in East Asian manufacturing hubs exposes procurement timelines to single-source vulnerabilities that compress pricing tier spreads between premium hardened systems and standard configurations while forcing buyers toward multi-year offtake commitments.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate Australian AUKUS-linked programs and Japanese Defense Build-Up procurements, insulating integrators from semiconductor commodity swings while transferring risk to sovereign buyers. Price differentiation rests on ITAR/EAR compliance tiers and sovereign content mandates rather than performance specifications alone. Cost compression in mid-tier electronic warfare suites is intensifying because Southeast Asian navies prioritize localized production over full NATO interoperability. Government procurement offices exhibit highest price sensitivity due to budget cycle constraints; intelligence agencies demonstrate lowest sensitivity given mission-critical timelines.
Supply Chain Analysis
Export-control regime enforcement under Australia's Defense Trade Controls Act, Japan's METI frameworks, and India's Defence Acquisition Procedure fragments component flows across trilateral and bilateral technology transfer agreements. Geographic supply concentration centers on Taiwan and South Korea for high-frequency semiconductors, Japan for precision microwave components, and the United States for classified encryption modules. Raw material dependencies include gallium nitride substrates, sapphire wafers, and rare-earth magnet alloys. Single-source vulnerability in GaN foundry capacity represents the dominant structural risk. Distribution runs through defense ministry program management offices rather than open commercial channels, with prime contractors managing tier-2 and tier-3 supplier qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
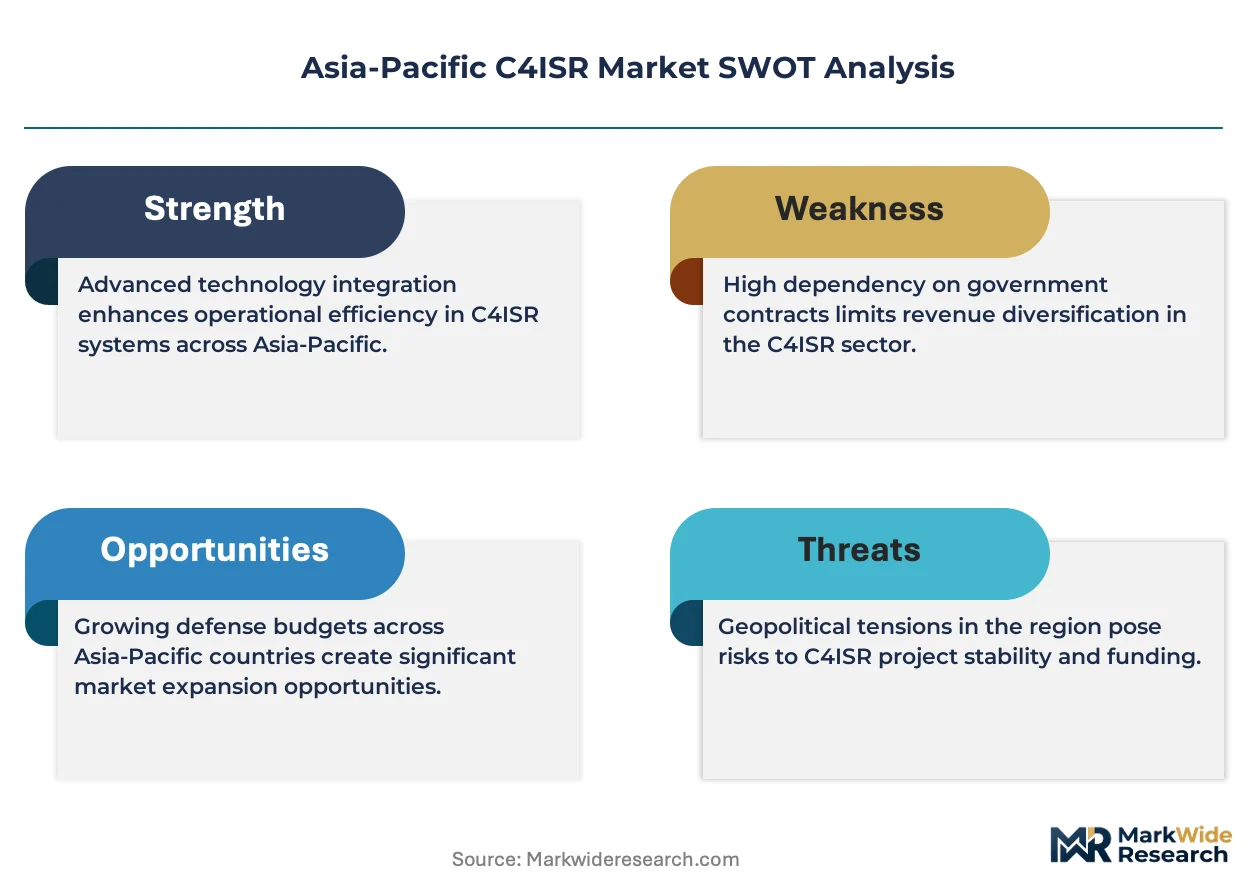
Asia-Pacific C4ISR procurement fragmentation creates specialized entry points as sovereign indigenous content mandates splinter previously consolidated program structures into component-level competitions.
For Market Incumbents: Harden supply chain resilience through backward integration into GaN semiconductor sourcing or captive production partnerships in India and South Korea. Lockheed Martin and Northrop Grumman channel positions face erosion from THALES localized electronic warfare suites and emerging Israeli autonomous platform specialists; defend through multi-decade sustainment contracts embedding cybersecurity upgrade pathways. For New Entrants and Emerging Players: Vietnam and Indonesia coastal surveillance gaps offer white-space entry through integrated UAV-radar packages priced below NATO-tier systems. Target maritime domain awareness applications in archipelagic environments where legacy HF networks resist replacement; partner with domestic system integrators to satisfy indigenous content thresholds without full technology transfer. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized electronic warfare and edge-AI sensor fusion targets over broad platform integrators. Long-term viability hinges on through-life capability management contract capture rather than transactional equipment sales. Monitor AUKUS technology transfer agreement evolution as inflection indicator for Australian market access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Production Partnership | India's Defence Acquisition Procedure offsets and Make in India mandates condition foreign prime contractor participation. |
| Edge-AI Sensor Fusion Development | Machine learning integration with multi-spectral arrays compresses maritime patrol classification timelines for gray-zone operations. |
| Multi-Decade Sustainment Contract | Australia's AUKUS integration demands shift procurement from equipment sales to through-life capability management structures. |
| Cyber-Physical System Hardening | Zero-trust architecture retrofits address escalating supply chain penetration risks against networked battle management systems. |
| Trilateral Technology Transfer Compliance | Australian Defense Trade Controls Act extraterritorial reach forces UK and US vendors to restructure subsidiary governance for AUKUS access. |
Study Parameters
Cross-validation between primary interviews with defense procurement officers, systems integration program managers, and semiconductor supply chain directors and secondary validation through defense ministry budget submissions, parliamentary committee testimony, and ITAR/EAR regulatory filings anchors the qualitative findings. Bottom-up triangulation against platform-specific procurement announcements and top-down reconciliation with sovereign defense expenditure databases ensures segment-level consistency.
Calibration against historical program execution timelines and technology insertion cycles informs the analytical framework across the projection horizon. Segmentation dimensions modeled include technology maturity curves, deployment architecture preferences, and sovereign content mandate intensity. CAGRs derive from weighted program pipeline analysis and capability requirement evolution. Industry-specific forecast inputs include AUKUS submarine delivery schedules and Japan's Defense Build-Up Program procurement waves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed system integrators or accelerated Indian indigenous platform development would shift outcomes. Material shifts in trilateral technology transfer agreement scope or GaN foundry capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Air Based C4ISR Market
ISR
Japan C4ISR Market
ISR
Brazil C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Low Altitude Radar Market
ISR
North America C5ISR Market
ISR
North America Airborne ISR Market
ISR
C6ISR Market
ISR
Australia C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
Naval ISR Market
ISR
Land Based C4ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
C4ISR Market
ISR
C5ISR Market