
 Europe C5ISR Market | 2026-2036
Europe C5ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Europe C5ISR Market Insights
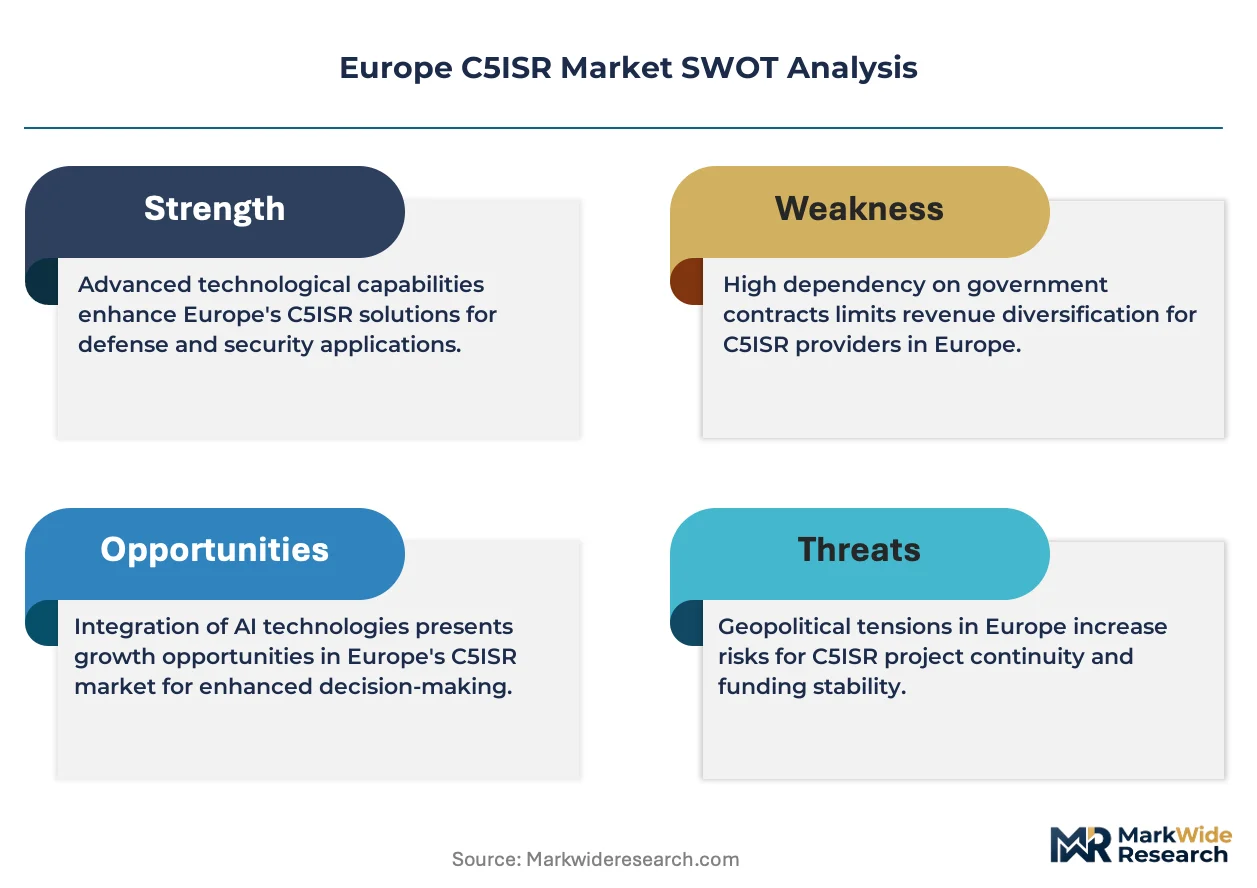
Software-defined radio maintenance and upgrade subscriptions is hardening into the dominant revenue model across European defense electronics. Thales leverages its pan-European service footprint to lock in long-term support contracts for naval and airborne platforms. BAE Systems anchors UK sovereign capability through deep integration with the Ministry of Defence's digital transformation programs. Leonardo S.p.A competes on specialized electronic warfare suites tailored to Italian and NATO operational requirements.
C5ISR denotes the integrated architecture of command, control, communications, computers, cyber, intelligence, surveillance, and reconnaissance systems that fuse multi-domain data streams into actionable decision support for military operators. These systems typically operate across classified frequency bands with embedded encryption protocols and real-time cross-platform interoperability standards. Electronic Warfare commands the largest installed base but faces margin compression as legacy platforms age. Cybersecurity within the technology dimension absorbs disproportionate R&D investment as NATO members harden networks against sophisticated intrusion campaigns. Cloud-Based deployment models are gaining traction among intelligence agencies seeking elastic compute for signals processing, though On-Premise systems retain primacy in frontline tactical applications where connectivity remains contested.
EU Green Deal procurement criteria and the EU AI Act are beginning to shape vendor qualification requirements for energy-efficient and algorithmically transparent systems. EDA capability development programs and national regulators such as France's DGA enforce stringent electromagnetic compatibility and spectrum management standards that filter market access. Stakeholders must monitor how PESCO project consolidation affects national industrial base protections and cross-border technology transfer rules.
Market Dynamics
PESCO project consolidation is compressing national procurement timelines while the EU AI Act imposes algorithmic transparency mandates on defense electronics vendors. This regulatory-structural intersection is forcing suppliers to requalify platforms for cross-border interoperability.
Growth Catalysts
- Permanent Structured Cooperation (PESCO):The EU framework channels pooled procurement toward interoperable C5ISR architectures, accelerating joint capability development across member states.
- France:The DGA's sovereign cloud initiatives for defense data processing are generating dedicated demand for secure edge computing infrastructure in tactical environments.
- Software-defined radio:Modular waveform reprogramming enables rapid spectrum adaptation against electronic warfare threats without hardware replacement cycles.
Market Restraints
- Gallium nitride supply concentration:Foundry capacity for high-power RF components clusters in East Asian semiconductor manufacturing zones, exposing European prime contractors to single-source vulnerabilities.
- REACH compliance costs:The EU chemicals regime restricts legacy solder materials and flame-retardant substrates, forcing expensive redesigns of proven avionics assemblies.
- Technical debt in legacy platforms:Cold War-era command systems lack open architecture interfaces, blocking seamless integration with modern ISR networks.
Strategic Opportunities
- Poland:Accelerated military modernization under the Homeland Defence Act creates unmet demand for integrated battlefield management systems.
- AI-enabled predictive maintenance:Convergence of machine learning with sensor telemetry allows shift from scheduled to condition-based platform support contracts.
- EU Green Deal procurement criteria:Energy-efficient system mandates favor suppliers with low-power signal processing architectures in upcoming tender evaluations.
Industry Challenges
- Security-cleared engineering talent:National vetting bottlenecks constrain workforce scaling for classified program execution across Germany, France, and the United Kingdom.
- NATO STANAG certification timelines:Interoperability testing for new waveforms and data links extends product launch windows by 18-24 months.
- Cross-domain integration complexity:Fusing space-based SAR, airborne ELINT, and ground radar into unified tracks demands data format reconciliation across historically stovepiped communities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe C5ISR Market |
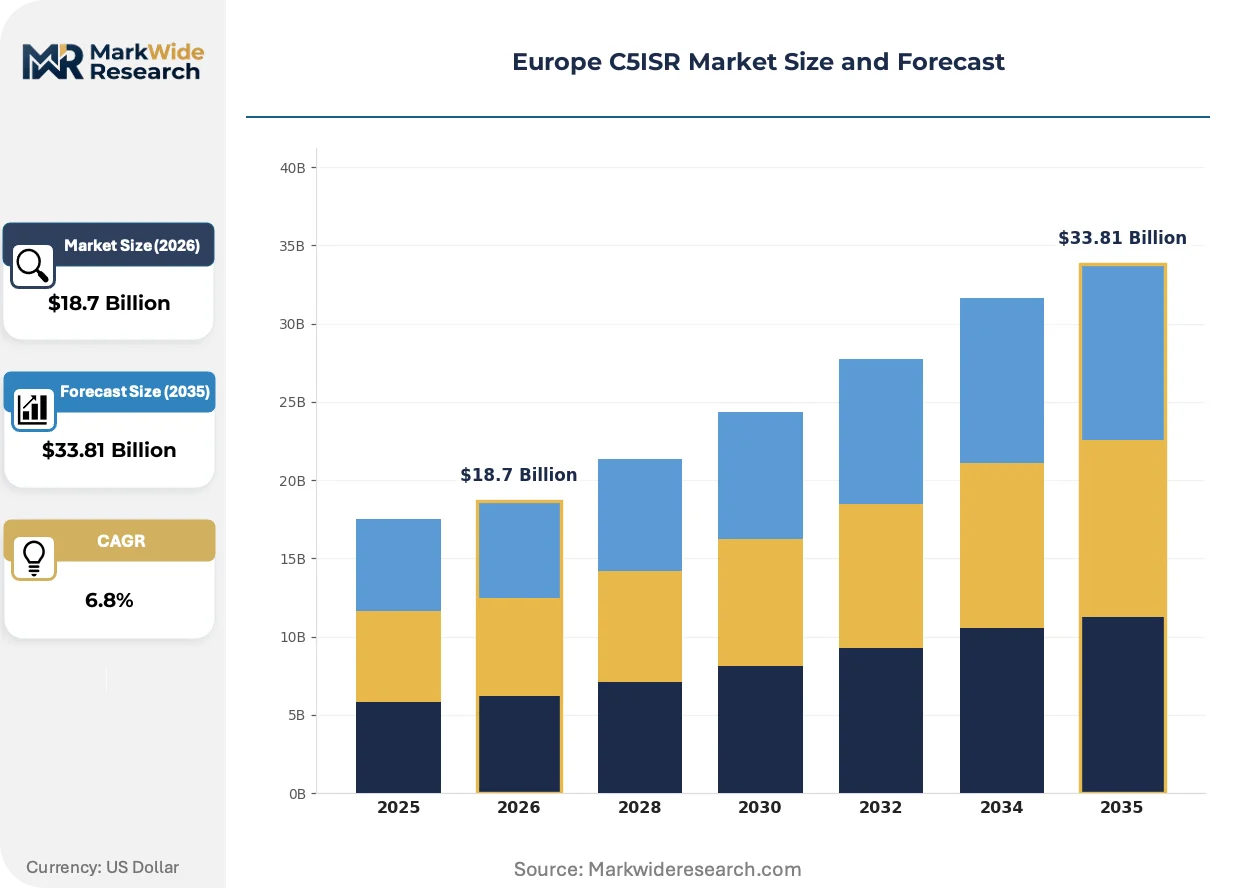
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Warfare, Command and Control, Communications, Intelligence End User: Military, Government, Defense Contractors, Intelligence Agencies Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile Technology: Satellite, Radar, Cybersecurity, IoT |
| Companies Covered | BAE Systems, Thales, Airbus, Leonardo S.p.A, Saab AB, Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, General Dynamics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe C5ISR Market Trends and Innovations
European defense electronics is pivoting toward software-centric architectures that decouple capability delivery from hardware refresh cycles. This structural shift compresses supplier margins on physical platforms while expanding recurring revenue in firmware and analytics layers.
Multi-function RF systems are consolidating radar, communications, and electronic warfare into shared apertures and processing chains. Naval surface combatants and fighter aircraft programs are adopting these architectures to reduce topside antenna count and signature. The technology is consolidating three historically separate supplier ecosystems into unified RF domain competitions.
The EU AI Act's risk classification framework for autonomous decision support systems is mandating explainability logging and human oversight interfaces in targeting and signals analysis software. Defense ministries are embedding these requirements into technical specifications before formal implementation deadlines. French and German procurement offices are now requiring algorithmic audit trails in intelligence fusion platforms.
Buyer organizations are unbundling long-term support from initial platform acquisition, treating software maintenance and threat library updates as separately contracted subscriptions. This disintermediates traditional prime contractor capture of through-life revenue. The United Kingdom's Defence Digital organization is pioneering this model in its C4ISR estate rationalization program.
Europe C5ISR Market Segmentation
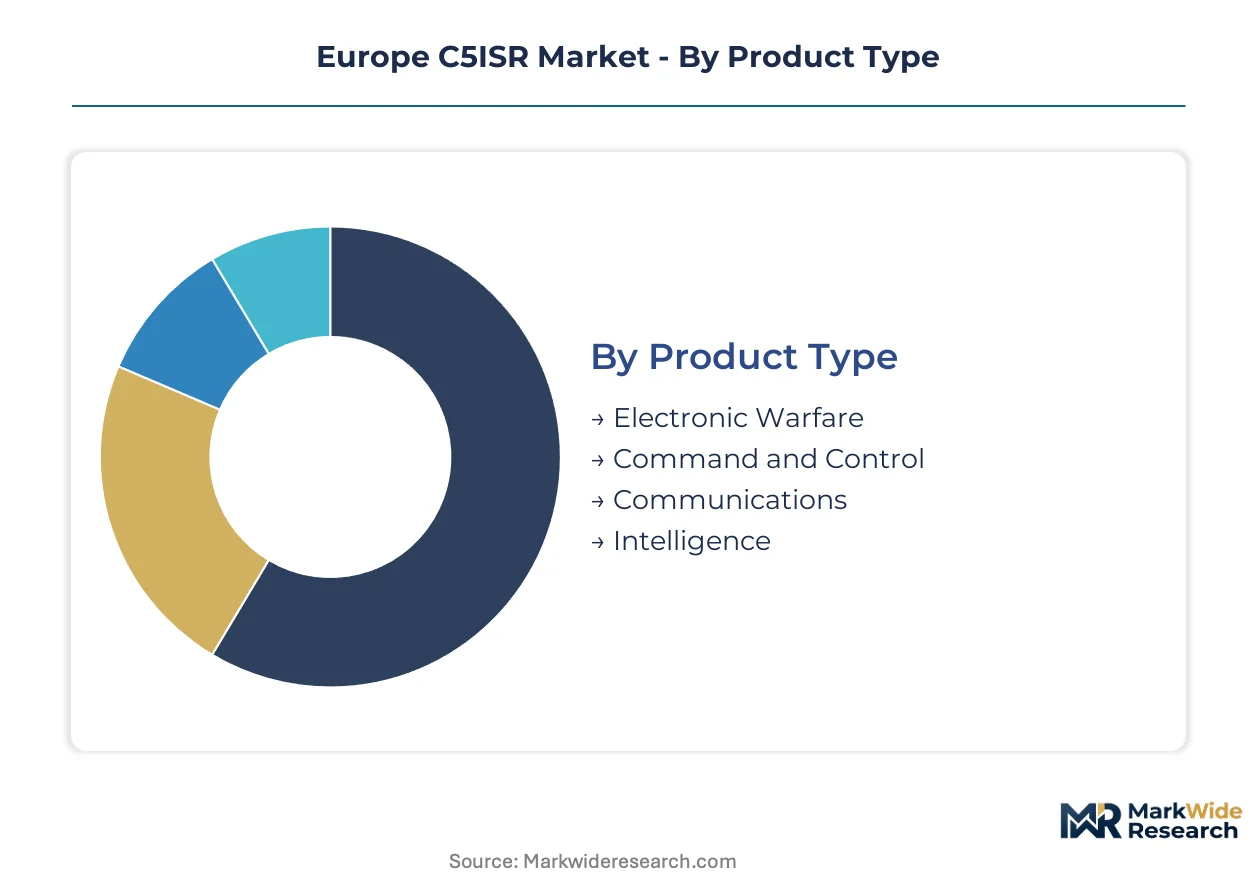
C5ISR procurement decisions in Europe hinge on interoperability mandates from PESCO and national sovereignty requirements. Segmentation reveals where defense ministries concentrate spending versus where capability gaps persist.
Product Type:
European ministries prioritize segments that reduce platform obsolescence risk through software upgradeability.
- Electronic Warfare:Systems integrate radar warning, jamming, and electronic attack into unified RF suites. France and Germany anchor demand through fighter and naval modernization programs facing electromagnetic spectrum congestion in contested environments.
- Command and Control:Multi-domain battle management platforms fuse air, land, sea, space, and cyber data into single operational pictures. The United Kingdom's Defence Digital transformation and Poland's battlefield management modernization drive concentrated procurement.
- Communications:Software-defined radios with modular waveforms enable rapid reprogramming against emerging threats without hardware replacement.
- Intelligence:SIGINT and GEOINT fusion platforms process multi-source data for targeting and situational awareness.
Electronic Warfare leads on scale; Command and Control leads on momentum.
End User:
Contracting authority determines technical specification authority and security classification thresholds.
- Military:Armed forces operate the largest installed base of tactical C5ISR across NATO's eastern flank and expeditionary formations. Frontline units in Poland, Romania, and the Baltic states drive demand for hardened, low-latency systems.
- Defense Contractors:Prime integrators embed C5ISR subsystems into major platforms—combat aircraft, surface vessels, armored vehicles—under national procurement frameworks.
- Government:Civil ministries and border security agencies adopt adapted military technologies for critical infrastructure protection.
- Intelligence Agencies:Signals intelligence services require specialized high-capacity processing for cryptanalysis and foreign communications interception.
Military end users dominate volume; Defense Contractors capture the steepest expansion trajectory through platform integration mandates.
Deployment Model:
Connectivity assumptions in contested environments versus secure rear areas shape architecture selection.
- On-Premise:Tactical command posts and forward operating bases rely on localized processing when satellite or terrestrial links face jamming or physical destruction. Germany's land forces and France's expeditionary units specify air-gapped systems for command continuity.
- Cloud-Based:Intelligence agencies and strategic headquarters leverage elastic compute for bulk signals processing and AI-enabled analytics. The DGA's sovereign cloud initiatives and UK Defence Digital programs establish classified cloud infrastructure.
- Hybrid:Architectures split processing between tactical edge and strategic core based on data classification and latency requirements.
- Mobile:Vehicle-mounted and dismounted systems provide command capability for maneuver formations and special operations.
On-Premise retains the largest footprint; Cloud-Based deployment is climbing the fastest as sovereign infrastructure matures.
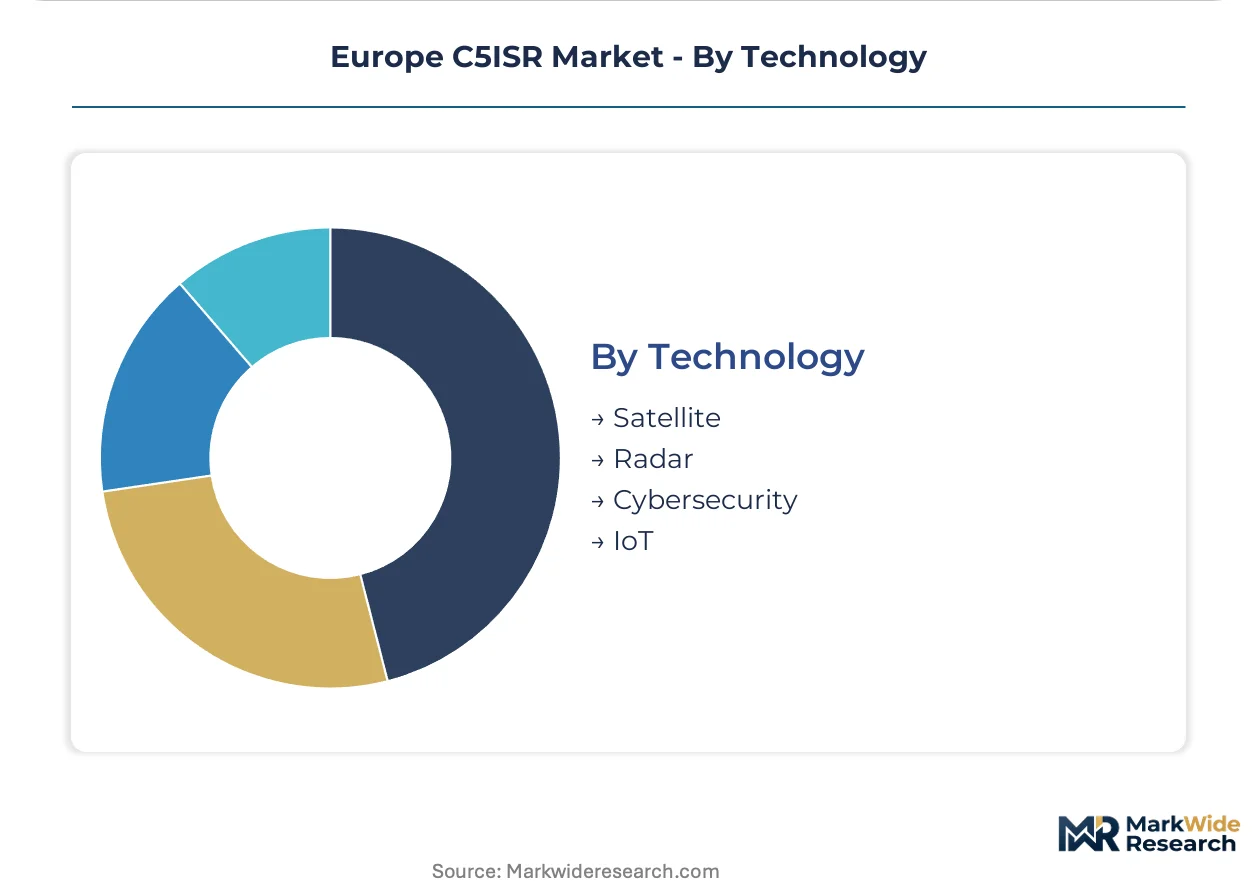
Technology:
Underlying technology layers determine vulnerability surface and integration complexity with legacy NATO systems.
- Cybersecurity:Embedded encryption, zero-trust architectures, and intrusion detection absorb disproportionate R&D investment as NATO members harden networks against sophisticated campaigns. The EU AI Act and national security vetting impose stringent supply chain verification.
- Satellite:Space-based communications and PNT services enable beyond-line-of-sight coordination, though anti-satellite threats drive demand for resilient constellations and tactical alternatives.
- Radar:Active electronically scanned arrays and multi-function RF systems consolidate surveillance, fire control, and electronic warfare in naval and airborne platforms.
- IoT:Sensor networks for perimeter security, equipment monitoring, and logistics tracking extend C5ISR into physical infrastructure management.
Cybersecurity leads on investment intensity; Satellite technology is gaining share fastest through NATO space domain initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier positioning as REACH compliance costs and EU AI Act mandates create divergent cost-of-compliance environments across European defense electronics manufacturing.
France
The DGA's sovereign cloud initiatives and Rafale fighter modernization programs drive concentrated demand for secure edge computing and multi-function RF systems. France's electromagnetic compatibility standards filter market access for non-EU suppliers. The Île-de-France defense electronics cluster around Paris-Saclay anchors Thales and Safran's integrated C5ISR development.
Germany
Bundeswehr digitalization and FCAS fighter program investments prioritize interoperable command systems with NATO STANAG certification. The KBA and BAAINBw enforce stringent spectrum management protocols for tactical communications. Bavaria's Munich-Augsburg corridor concentrates Rohde & Schwarz and Hensoldt's radar and electronic warfare engineering capabilities.
United Kingdom
Defence Digital transformation and AUKUS integration commitments accelerate procurement of software-defined architectures and AI-enabled intelligence fusion. UK National Cyber Security Centre mandates shape vendor qualification for classified network infrastructure. The South West England cluster around Bristol and Portsmouth hosts BAE Systems' naval and airborne C5ISR integration facilities.
Poland
Homeland Defence Act procurement timelines compress supplier selection for integrated battlefield management and coastal defense radar networks. Poland's national security vetting requirements constrain workforce scaling for classified program execution. The Warsaw-Łódź corridor is emerging as a regional hub for NATO-compatible communications system integration.
Italy
Naval fleet modernization and NATO southern flank surveillance requirements drive demand for electronic warfare and maritime patrol C5ISR suites. Leonardo's supply chain integration with the Italian Ministry of Defence shapes domestic procurement specifications. The Rome-Latium and Lombardy aerospace clusters concentrate electronic warfare and radar system engineering talent.
Europe C5ISR Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with prime contractors capturing platform integration value while subsystem vendors compete on modular technology insertion. The structure consolidates around national champions with deep ministry relationships, supplemented by transatlantic suppliers leveraging NATO interoperability mandates. Three archetypes dominate: pan-European integrated primes, national sovereign capability anchors, and specialized RF subsystem vendors. Competitive moves center on PESCO project consortium positioning and long-term through-life support contract capture.
Among European-based defense primes, BAE Systems, Thales, and Leonardo S.p.A occupy positions reflecting distinct national industrial strategies. BAE Systems exemplifies the sovereign capability anchor archetype through its UK Ministry of Defence integration. Thales represents the pan-European service footprint model with cross-border maintenance networks. Leonardo S.p.A sits within the specialized electronic warfare tier, leveraging Italian and NATO operational requirements. These three entities collectively illustrate how national procurement frameworks shape competitive positioning in European defense electronics.
| Leading Market Players |
|---|
| BAE Systems |
| Thales |
| Airbus |
| Leonardo S.p.A |
| Saab AB |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| General Dynamics Corporation |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed defense primes anchor European C5ISR procurement, concentrating supply relationships around national ministry frameworks and compressing price competition into long-term service contract structures. This ownership pattern tightens pricing discipline across hardware platforms while expanding recurring revenue capture in firmware subscriptions and threat library updates.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for NATO-compatible battlefield management systems as Homeland Defence Act procurement accelerates. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-certified platforms from commercial-off-the-shelf alternatives and legacy upgrade paths. Cost compression in mid-tier electronic warfare suites is intensifying because REACH compliance redesigns inflate non-recurring engineering. Defense contractors show highest price sensitivity on initial platform acquisition, while intelligence agencies prioritize performance over unit cost in signals processing infrastructure.
Supply Chain Analysis
Gallium nitride foundry capacity rests on Taiwanese and South Korean semiconductor manufacturing zones, exposing European primes to single-source vulnerabilities in high-power RF components. Raw material dependencies span rare earth substrates for magnetics, specialized ceramic packages for thermal management, and flame-retardant laminates constrained by EU chemicals regulation. Tariff exposure runs through East Asian component sourcing as geopolitical friction disrupts just-in-time delivery schedules. Distribution runs through national procurement frameworks with BAAINBw, DGA, and UK Defence Digital acting as gatekeepers for qualified vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European C5ISR represents a late-cycle quality story as defense ministries shift procurement weight toward AI-enabled predictive maintenance and sovereign cloud infrastructure. Premium specifications now dominate tender evaluations under EU Green Deal and EU AI Act mandates.
For Market Incumbents: Deploy PESCO consortium positioning to lock in cross-border interoperability requirements before competitor requalification completes. BAE Systems, Thales, and Leonardo S.p.A should deepen backward integration into secure semiconductor packaging to offset gallium nitride supply concentration. Channel control through security-cleared engineering networks filters emerging RF subsystem vendors from classified program access. For New Entrants and Emerging Players: Polish systems integrators present the most penetrable entry vector for NATO STANAG-certified communications modules under compressed Homeland Defence Act timelines. Target software-defined radio waveform libraries as a white-space opportunity where hardware-agnostic delivery sidesteps prime contractor platform capture. AUKUS-aligned UK suppliers offer partnership pathways for AI-enabled intelligence fusion components. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier electronic warfare specialists with dormant NATO certification pipelines. Long-term viability hinges on through-life support contract duration rather than initial platform margins. Watch PESCO project consolidation announcements as inflection indicators for national industrial base protection relaxation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Deployment | DGA and UK Defence Digital programs establish classified edge computing standards for tactical data processing. |
| Multi-Function RF System Integration | Thales and Safran consolidate radar, communications, and electronic warfare into shared naval and airborne apertures. |
| AI-Enabled Predictive Maintenance Platform | Machine learning convergence with sensor telemetry shifts defense contractors toward condition-based support contracts. |
| REACH Compliance Redesign Program | ECHA restrictions on legacy solder materials force expensive avionics assembly requalification across European primes. |
| Software-Defined Radio Waveform Library Expansion | Modular reprogramming capabilities enable rapid spectrum adaptation against emerging electronic warfare threats. |
Research Methodology
Coverage spans France, Germany, the United Kingdom, Poland, and Italy, with primary inputs from each national defense procurement ecosystem. The analysis combines structured interviews with program managers at BAAINBw, DGA, and UK Defence Digital, platform engineers at Thales and Leonardo S.p.A, and procurement officers at Polish Ministry of National Defence with secondary validation against NATO STANAG documentation, EU Defence Fund disbursement records, and national military modernization white papers. Bottom-up segment sizing triangulates against top-down defense budget allocation data.
Granularity-level modeling spans product type, end user, deployment model, and technology dimensions with country-specific procurement timeline overlays. CAGRs derive from defense budget trajectory analysis and platform replacement cycle assessment across the projection horizon. Forecast inputs include PESCO project pipeline velocity, REACH compliance cost pass-through estimates, and security-cleared workforce expansion constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption of gallium nitride supply and PESCO consolidation pace. The analysis reflects assumptions around NATO interoperability mandate continuity and EU AI Act implementation timelines. Material deviation in East Asian semiconductor access or transatlantic defense industrial cooperation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Air Based C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Naval ISR Market
ISR
North America Airborne ISR Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
C4ISR Market
ISR
North America C5ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
United States C4ISR Market
ISR
C5ISR Market
ISR
NATO C4ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
C6ISR Market
ISR
Infrared Suppression Systems Market