
 C5ISR Market | 2026-2036
C5ISR Market Size, Share, and Industry Trends Forecast 2026-2036
C5ISR Market Analysis
Modular platform bundling is realigning procurement decisions across defense ministries, with buyers favoring configurable mission packages over fixed-architecture systems. Lockheed Martin leverages its satellite communications integration to anchor large-scale program awards. BAE Systems sustains competitive positioning through specialized electronic warfare subsystems. Thales dominates European naval C5ISR retrofit programs with country-specific industrial participation requirements.
C5ISR denotes the integrated military architecture spanning command, control, communications, computers, cyber, intelligence, surveillance, and reconnaissance, typically operating across encrypted waveforms with sub-millisecond latency thresholds for time-critical targeting. Its primary purpose is to collapse sensor-to-shooter timelines across joint force operations. Communication Systems and Cybersecurity Solutions command the largest share of current program spending, while Artificial Intelligence and Big Data Analytics represent the fastest-expanding technology layer as militaries automate threat correlation. Cloud Computing deployment models are gaining traction where data sovereignty rules permit federated architectures.
The U.S. Department of Defense's JADC2 framework and NATO's Federated Mission Networking standards shape product interoperability mandates, while the U.S. FCC regulates spectrum allocation for military communications and the EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems. Contractors must navigate divergent certification regimes when supplying integrated platforms across allied nations. Stakeholders should monitor how export control harmonization between the U.S. International Traffic in Arms Regulations and EU dual-use frameworks affects cross-border subsystem integration.
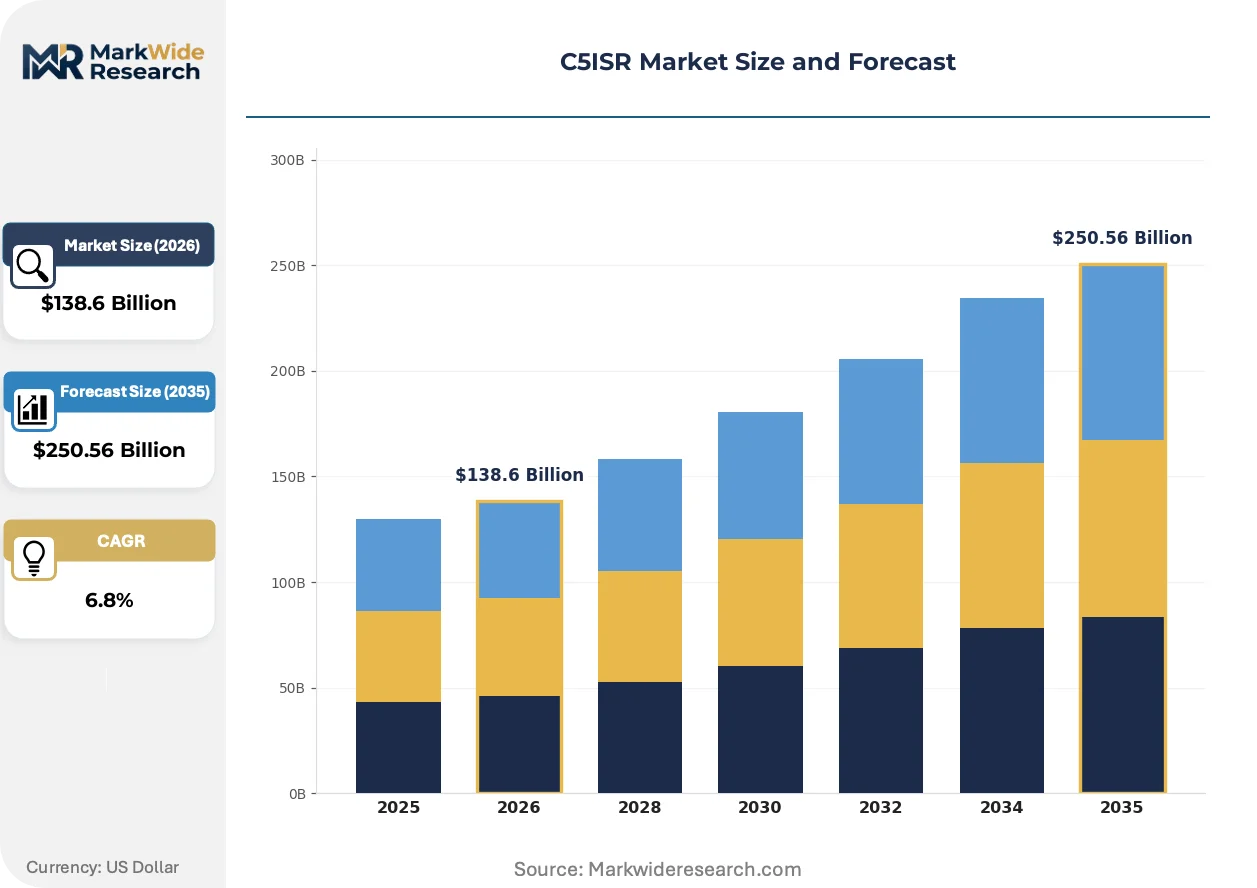
Market Dynamics
The U.S. Department of Defense's Joint All-Domain Command and Control initiative is compressing sensor-to-shooter timelines and mandating interoperable architectures across all service branches, forcing contractors to redesign platforms for multi-domain connectivity rather than single-service deployment.
Growth Catalysts
- NATO Federated Mission Networking standards:Allied defense ministries are procuring interoperable C5ISR suites to enable coalition operations, driving cross-border subsystem integration requirements.
- Electronic warfare subsystem modernization:Naval forces across NATO member states are accelerating integrated command platform procurement to counter peer adversary jamming capabilities.
- Pacific theater posture adjustments:The United States is investing in networked battle management systems to sustain distributed maritime operations across contested environments.
Market Restraints
- ITAR-EU dual-use regulatory divergence:Contractors face divergent certification regimes when supplying integrated platforms across allied nations, extending compliance timelines.
- Semiconductor supply concentration:Advanced signal processing chips for encrypted waveforms depend on limited foundry capacity in East Asia, creating input vulnerability.
- Legacy platform integration complexity:Existing command systems in allied fleets use proprietary protocols that resist rapid modernization without full replacement.
Strategic Opportunities
- Cloud Computing deployment models:Federated architectures are gaining traction where data sovereignty rules permit, enabling shared intelligence processing across allied networks.
- Artificial Intelligence and Big Data Analytics convergence:Militaries are automating threat correlation, creating demand for algorithmic decision-support layers.
- EU AI Act algorithmic transparency requirements:European defense procurement is mandating explainable autonomous targeting systems, opening specialized compliance markets.
Industry Challenges
- Cleared workforce scarcity:Sub-millisecond latency system engineering requires security-cleared personnel with specialized waveform protocol expertise.
- Multi-domain integration complexity:JADC2-compliant platforms must synchronize air, maritime, ground, space, and cyber domains simultaneously.
- Export control harmonization delays:Cross-border subsystem integration awaits alignment between U.S. International Traffic in Arms Regulations and European frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C5ISR Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Systems, Surveillance Systems, Reconnaissance Systems, Cybersecurity Solutions End User: Military, Defense Contractors, Government Agencies, Intelligence Organizations Technology: Artificial Intelligence, Big Data Analytics, Cloud Computing, Cyber Operations Installation: On-premise, Cloud-based, Hybrid, Mobile Deployment |
| Companies Covered | General Dynamics Corporation, BAE Systems plc, Lockheed Martin Corporation, Leidos, Inc., Thales Group, Northrop Grumman Corporation, L3Harris Technologies, Inc., Leonardo S.p.A., RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C5ISR Market Emerging Trajectories
Encrypted waveform architectures are evolving toward software-defined flexibility, enabling rapid reconfiguration against adversary electronic attack without hardware replacement cycles.
Artificial Intelligence and Big Data Analytics is expanding into automated threat correlation workflows. Naval and air force command centers are deploying machine-learning pipelines to fuse multi-source intelligence feeds. This compression of analyst workload is expanding into predictive maintenance for satellite communications terminals and unmanned aerial vehicle fleets.
The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems. European defense procurement offices now mandate explainability documentation for machine-learning models used in fire-control loops. Naval C5ISR retrofit programs across France, Germany, and Italy are prioritizing vendors with certified ethical AI governance frameworks.
Defense ministries are consolidating vendor relationships around configurable mission packages. Fixed-architecture system procurement is yielding to modular platform bundling with country-specific industrial participation requirements. This preference shift is most visible in European naval modernization programs, where Thales and BAE Systems compete on subsystem interoperability rather than end-to-end platform dominance.
C5ISR Market Segmentation
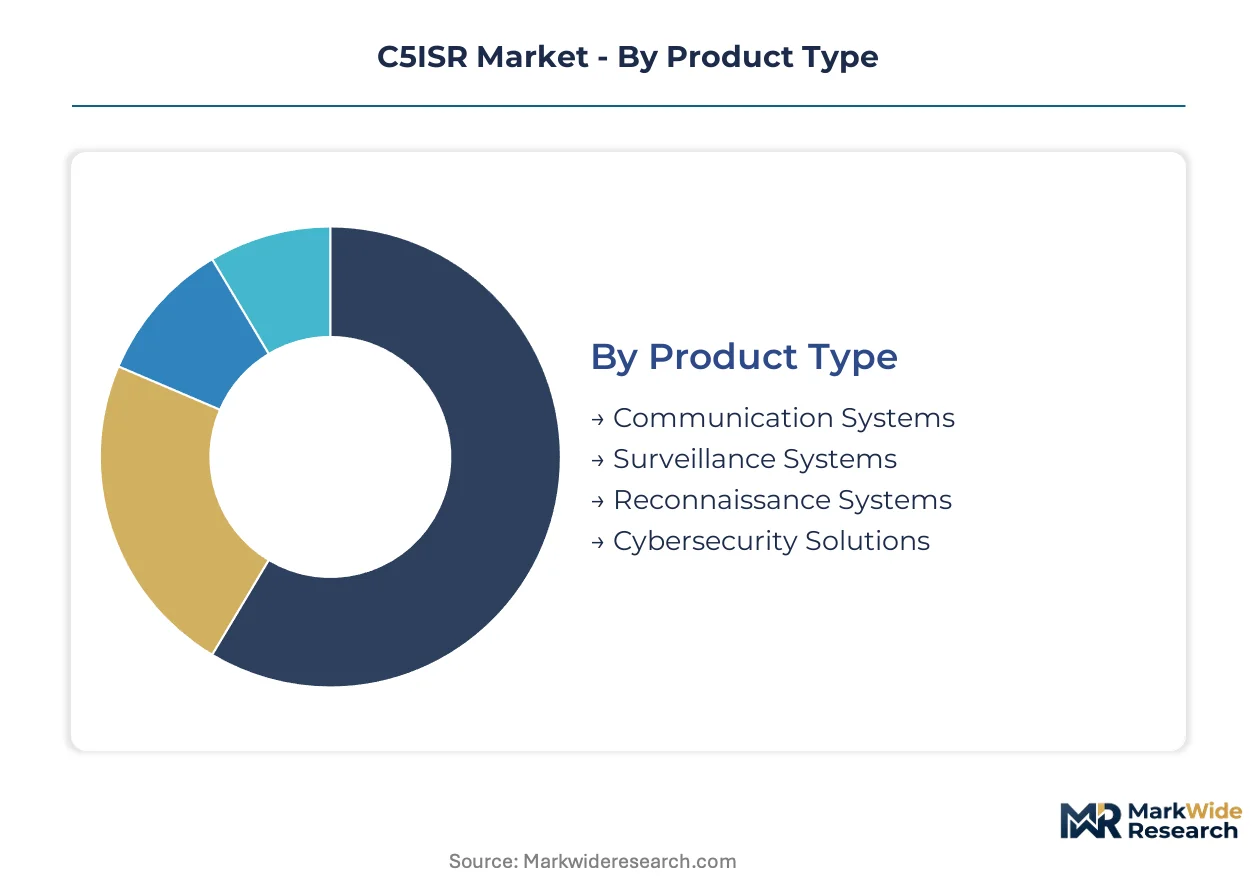
C5ISR procurement patterns diverge sharply across buyer types and deployment contexts. Product specifications, technology layers, and installation models each impose distinct vendor qualification barriers and lifecycle cost structures.
Product Type:
Defense ministries prioritize mission-critical performance thresholds over unit economics when selecting platform categories.
- Communication Systems:These encompass encrypted waveform terminals, satellite uplink modules, and software-defined radio networks operating at sub-millisecond latency. The U.S. Pacific theater posture drives concentrated investment in resilient beyond-line-of-sight links for distributed maritime operations. NATO Federated Mission Networking standards mandate interoperable protocols across allied procurement.
- Cybersecurity Solutions:Defensive cyber operations platforms, zero-trust network architectures, and threat-hunting tools protect command infrastructure from adversary intrusion. Intelligence Organizations in Five Eyes nations represent the most demanding customer segment, requiring cleared development teams and sovereign data handling.
- Surveillance Systems:Multi-spectral sensor arrays and persistent monitoring platforms integrate radar, electro-optical, and signals intelligence collection.
- Reconnaissance Systems:Unmanned platforms and penetrating sensor packages deliver tactical imagery and electronic intelligence from contested airspace.
Volume sits with Communication Systems; growth tilts toward Cybersecurity Solutions.
End User:
Contractor security clearance requirements and procurement authority thresholds segment the customer base into distinct engagement models.
- Military:Service branches demand JADC2-compliant architectures with multi-domain connectivity across air, maritime, ground, space, and cyber environments. The U.S. Department of Defense's Joint All-Domain Command and Control initiative compresses sensor-to-shooter timelines and mandates interoperable platforms.
- Intelligence Organizations:Signals intelligence agencies and national reconnaissance offices require specialized compartmented programs with enhanced counterint protections. These buyers concentrate procurement in the United States and United Kingdom, where satellite communications integration and electronic warfare subsystems anchor vendor selection.
- Government Agencies:Homeland security and federal emergency management organizations procure C5ISR for domestic crisis response and critical infrastructure protection.
- Defense Contractors:Prime integrators and subsystem suppliers purchase components for platform integration under foreign military sales and direct commercial contracts.
Procurement volume clusters with Military end users; Intelligence Organizations expand most quickly.
Technology:
Automation depth and data processing architecture determine competitive differentiation in platform bids.
- Artificial Intelligence:Machine learning pipelines automate threat correlation and predictive maintenance across satellite communications terminals and unmanned vehicle fleets. The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems, mandating explainability documentation for fire-control loops in European defense procurement.
- Big Data Analytics:Multi-source intelligence fusion platforms process petabyte-scale sensor feeds for pattern recognition and anomaly detection. Naval command centers across NATO member states deploy these systems to compress analyst workload and accelerate decision cycles.
- Cloud Computing:Federated architectures enable shared intelligence processing where data sovereignty rules permit allied network integration.
- Cyber Operations:Offensive and defensive cyber capabilities integrate into unified electronic warfare suites.
Big Data Analytics commands current program spending; Artificial Intelligence shows the steepest expansion trajectory.
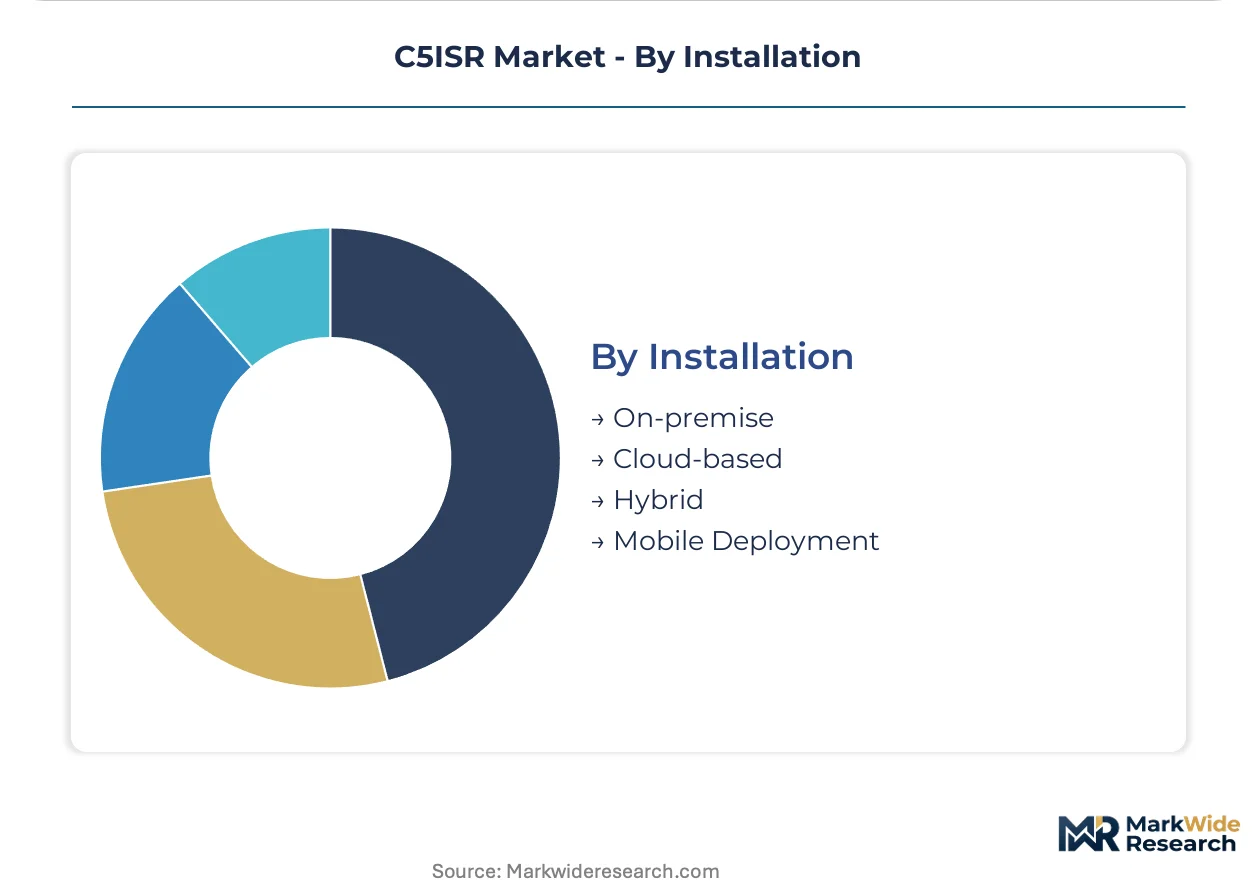
Installation:
Deployment model selection hinges on data sovereignty constraints, connectivity reliability, and platform mobility requirements.
- On-premise:Air-gapped command centers and hardened facilities house classified processing infrastructure with physical security controls. Intelligence Organizations and strategic command nodes mandate this architecture for top-secret compartmented information.
- Cloud-based:Federated cloud deployments support coalition operations and shared situational awareness across allied networks. European naval C5ISR retrofit programs prioritize these models where industrial participation requirements align with sovereign cloud frameworks.
- Hybrid:Tiered security architectures route unclassified processing to cloud infrastructure while retaining sensitive workloads on-premise.
- Mobile Deployment:Vehicle-mounted, airborne, and dismounted platforms deliver C5ISR capability to expeditionary and contested environments.
On-premise installations retain the largest installed base; Cloud-based deployment gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in established defense industrial bases while procurement demand spreads across allied nations responding to theater-specific threats. The United States absorbs the largest share of program spending, though European NATO members and Pacific partners accelerate parallel investments.
United States
The U.S. Department of Defense's Joint All-Domain Command and Control initiative compresses sensor-to-shooter timelines across all service branches. FCC spectrum allocation rules shape encrypted waveform development for military communications. Virginia's defense corridor around the Pentagon and Maryland's intelligence community cluster host prime integrators developing multi-domain connectivity platforms.
United Kingdom
Five Eyes intelligence-sharing obligations drive procurement of satellite communications integration and electronic warfare subsystems. The UK Ministry of Defence's procurement frameworks emphasize sovereign industrial participation in C5ISR retrofit programs. London and the South East concentration of defense contractors competes for NATO Federated Mission Networking standard-compliant awards.
Germany
Berlin's naval modernization programs prioritize integrated command platforms with country-specific industrial participation requirements. EU AI Act algorithmic transparency mandates shape autonomous targeting system procurement specifications. The Bavarian and Baden-Württemberg defense manufacturing clusters supply specialized electronic warfare subsystems to NATO allied fleets.
France
Thales anchors European naval C5ISR retrofit programs through domestically mandated industrial partnerships. The EU AI Act imposes explainability documentation requirements on machine-learning models in fire-control loops. The Île-de-France aerospace and defense cluster around Paris hosts systems integrators competing for coalition interoperability contracts.
Japan
Pacific theater posture adjustments drive investment in networked battle management systems for distributed maritime operations. METI industrial policy coordinates domestic semiconductor supply for advanced signal processing chips. The Kanto region around Tokyo concentrates prime contractors developing resilient beyond-line-of-sight communications for contested environments.
C5ISR Market Vendor Landscape
The competitive structure tilts toward systems integrators with cleared development teams and multi-domain platform expertise. Prime contractors compete on JADC2-compliant architecture delivery, while specialized subsystem vendors capture retrofit opportunities in allied fleets. Two strategic archetypes dominate: end-to-end platform integrators and component specialists with waveform protocol depth. Consolidation pressure runs through strategic partnerships bridging ITAR and EU dual-use regulatory domains, alongside portfolio diversification into AI-enabled decision-support layers.
Among U.S.-based defense conglomerates, Lockheed Martin and Northrop Grumman occupy positions as archetypal platform integrators anchoring large-scale program awards. BAE Systems exemplifies the European specialist tier competing on electronic warfare subsystem interoperability. Thales represents the continental European integrator archetype leveraging country-specific industrial participation requirements. These three entities illustrate how geographic regulatory alignment shapes competitive positioning across NATO procurement frameworks.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Leidos, Inc. |
| Thales Group |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| Leonardo S.p.A. |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate qualified supply for autonomous targeting systems and reserve premium-tier pricing access to vendors with certified ethical AI governance frameworks. Defense ministries now bundle compliance documentation costs into procurement evaluations, compressing margins for non-certified suppliers while elevating pricing power for pre-qualified integrators.
Pricing Analysis
Cost-down pressure on JADC2-compliant platforms accelerates because prime contractors must absorb multi-domain integration engineering without proportional contract value expansion. Three-tier pricing structure across mission-certified, interoperable-standard, and legacy-economy levels reflects differentiation by security clearance depth and waveform protocol sophistication. Price differentiation hinges on ITAR certification status and sovereign data handling capabilities. Intelligence Organizations show least price sensitivity due to compartmented program budgets, while Government Agencies face strict fiscal constraints.
Supply Chain Analysis
Refurbishment flows for satellite communications terminals and electronic warfare subsystems extend platform lifecycles in European naval retrofit programs, creating secondary supply channels alongside original manufacturing. Advanced signal processing chips draw from foundry capacity concentrated in Taiwan, South Korea, and Japan. Gallium nitride substrates and rare earth magnets for radar arrays rest on limited extraction sources. Single-source vulnerability in semiconductor fabrication threatens encrypted waveform production. Distribution runs through prime integrator-direct contracts with defense ministries and foreign military sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The C5ISR market operates as a cost-of-compliance story where ITAR-EU dual-use regulatory divergence erects barrier-to-entry moats favoring contractors with pre-cleared development teams and multi-certification portfolios.
For Market Incumbents: Anchor JADC2-compliant architecture dominance through captive supply of software-defined radio modules and satellite communications integration. Deepen backward integration into waveform protocol engineering to offset cleared workforce scarcity. Consolidate around federated cloud deployment capabilities where data sovereignty rules permit coalition network access. For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in European defense procurement open a window for specialized compliance vendors with explainable machine-learning documentation capabilities. Target naval C5ISR retrofit programs across France, Germany, and Italy as the most penetrable geography. Pursue subsystem interoperability certification rather than end-to-end platform competition. For Investors and Strategic Acquirers: Export control harmonization alignment between U.S. International Traffic in Arms Regulations and EU dual-use frameworks is the leading indicator that cross-border integration value will unlock. Position for 5-10 year consolidation plays around mid-tier electronic warfare specialists with waveform protocol depth. Monitor NATO Federated Mission Networking standard adoption rates as the inflection signal for coalition interoperability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Subsystem Interoperability Certification | Enables vendor participation in NATO Federated Mission Networking standard-compliant procurement frameworks. |
| Cleared Workforce Pipeline Investment | Addresses scarcity of security-cleared personnel with sub-millisecond latency system engineering expertise. |
| AI Governance Framework Certification | Satisfies EU AI Act explainability documentation mandates for autonomous targeting system bids. |
| Multi-Domain Architecture Integration | Aligns platform development with U.S. Department of Defense JADC2 sensor-to-shooter timeline compression requirements. |
| Sovereign Cloud Partnership Structure | Unlocks federated deployment models where European data sovereignty rules restrict foreign infrastructure access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with platform engineering directors, defense procurement officers, and electronic warfare subsystem specialists. SEC 10-K disclosures, NATO standardization agreements, and EU defense procurement databases provided cross-reference validation. Bottom-up program award tracking and top-down defense budget allocation analysis enabled triangulation.
Granularity-level modeling addressed product type, end user, technology layer, installation model, and geographic regulatory cluster across the analysis window. Communication Systems and Cybersecurity Solutions volumes were built from disclosed contract values, while Artificial Intelligence and Big Data Analytics expansion was projected from R&D pipeline indicators. CAGRs derived from weighted scenario analysis of JADC2 implementation pacing and coalition interoperability adoption curves.
Caveats apply where ITAR-EU regulatory harmonization delays or semiconductor supply concentration disruptions could materially shift the outlook. Forecasts reflect assumptions regarding Pacific theater posture sustainment and NATO member state naval modernization continuity. Practitioners should monitor export control alignment negotiations and foundry capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Europe C5ISR Market
ISR
Brazil C4ISR Market
ISR
IFF System Market
ISR
Air Based C4ISR Market
ISR
Airborne ISR Market
ISR
C6ISR Market
ISR
Japan C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
NATO C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
North America C5ISR Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Low Altitude Radar Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Australia C4ISR Market