
 Micro Switch Market | 2026-2036
Micro Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Switch Market Outlook
Buyer concentration in automotive electrification is rebalancing procurement power toward tier-one suppliers and EV platform architects. Omron Corporation leverages its electromechanical heritage to sustain dominance in precision automotive applications. Honeywell International Inc. anchors aerospace and industrial segments through MIL-spec certification depth. TE Connectivity competes on connector-switch integration, reducing assembly complexity for OEM customers.
A micro switch is a compact electromechanical device actuated by minimal physical force, typically rated for operational lives exceeding one million cycles and contact gaps measured in fractions of a millimeter. It functions as a binary position sensor in safety-critical circuits, translating mechanical displacement into clean electrical state changes. Miniature switches lead volume shipments in consumer electronics assembly, while Hall Effect technology captures the fastest expansion as contactless architectures displace mechanical wear in sealed environments. Electromechanical variants retain the largest installed base but face margin compression from optical alternatives in medical and laboratory instrumentation.
FCC equipment authorization rules govern electromagnetic compatibility for micro switches deployed in US telecommunications infrastructure, while REACH and RoHS frameworks in Europe restrict cadmium and lead content in contact alloys and housing plastics. China's GB standards and MIIT certification requirements shape product entry protocols for domestic appliance and automotive supply chains. Stakeholders must monitor how dual carbon goals across Chinese manufacturing zones alter material sourcing mandates and energy-intensity benchmarks for precision stamping and plating operations.
Market Dynamics
Automotive electrification is compressing switch procurement cycles as EV platform architects consolidate supplier tiers and mandate sealed-component qualification at vehicle-program inception rather than subsystem integration.
Growth Catalysts
- EV Thermal Management Mandates:High-temperature micro switch variants gain specification lock-in across German and Chinese battery pack architectures, driven by NHTSA and MIIT safety thresholds for thermal runaway detection circuits.
- REACH Contact Alloy Restrictions:European RoHS and REACH frameworks phase out cadmium-bearing contacts, accelerating palladium-silver and gold-nickel plating investments that extend operational life in automotive safety loops.
- Shenzhen Electronics Cluster Density:Miniature switch consumption concentrates in Guangdong Province surface-mount assembly corridors, where consumer electronics OEMs specify sub-5mm actuation travel for wearable and handheld device integration.
Market Restraints
- Platinum Group Metal Cost Volatility:Ruthenium and palladium price swings in South African and Russian concentrate markets compress contact plating margins, forcing pass-through clauses that OEM procurement teams resist.
- East Asian Stamping Concentration:Precision metal forming for switch housings and contact springs clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability when regional power rationing disrupts dual carbon compliance timelines.
- Hall Effect Displacement in Sealed Environments:Contactless magnetic sensing eliminates mechanical wear in automotive transmission and brake-by-wire modules, eroding electromechanical switch share in fluid-immersed applications above IP67 rating.
Strategic Opportunities
- Indian Appliance Electrification:BIS certification pathways for micro switches in induction cooktop and washing machine safety interlocks remain underpenetrated relative to Southeast Asian supply chain maturity, offering first-mover positioning as domestic manufacturing scales under PLI scheme incentives.
- Medical Robotics Integration:ISO 13485-certified miniature switches for surgical instrument haptic feedback converge with force-sensor fusion architectures, opening precision-positioning applications in laparoscopic tool articulation joints.
- US IRA Clean Energy Manufacturing:Domestic content bonuses for renewable energy equipment assembly pull switch sourcing toward North American stamping and plating operations, rewarding FCC-authorized suppliers with tariff-advantaged positioning in solar inverter and energy storage safety circuits.
Industry Challenges
- MIL-SPEC Certification Talent Scarcity:Aerospace and defense switch qualification requires AS9100D auditors and DLA-approved test engineers, with workforce gaps concentrated in Midwestern US manufacturing zones where demographic outmigration outpaces technical training pipeline expansion.
- Automotive SPICE Alignment Complexity:Tier-one suppliers demand AEC-Q100 and ISO 26262 functional safety documentation at PPAP submission, compressing development timelines for mid-cap switch manufacturers lacking captive semiconductor failure analysis laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Switch Market |
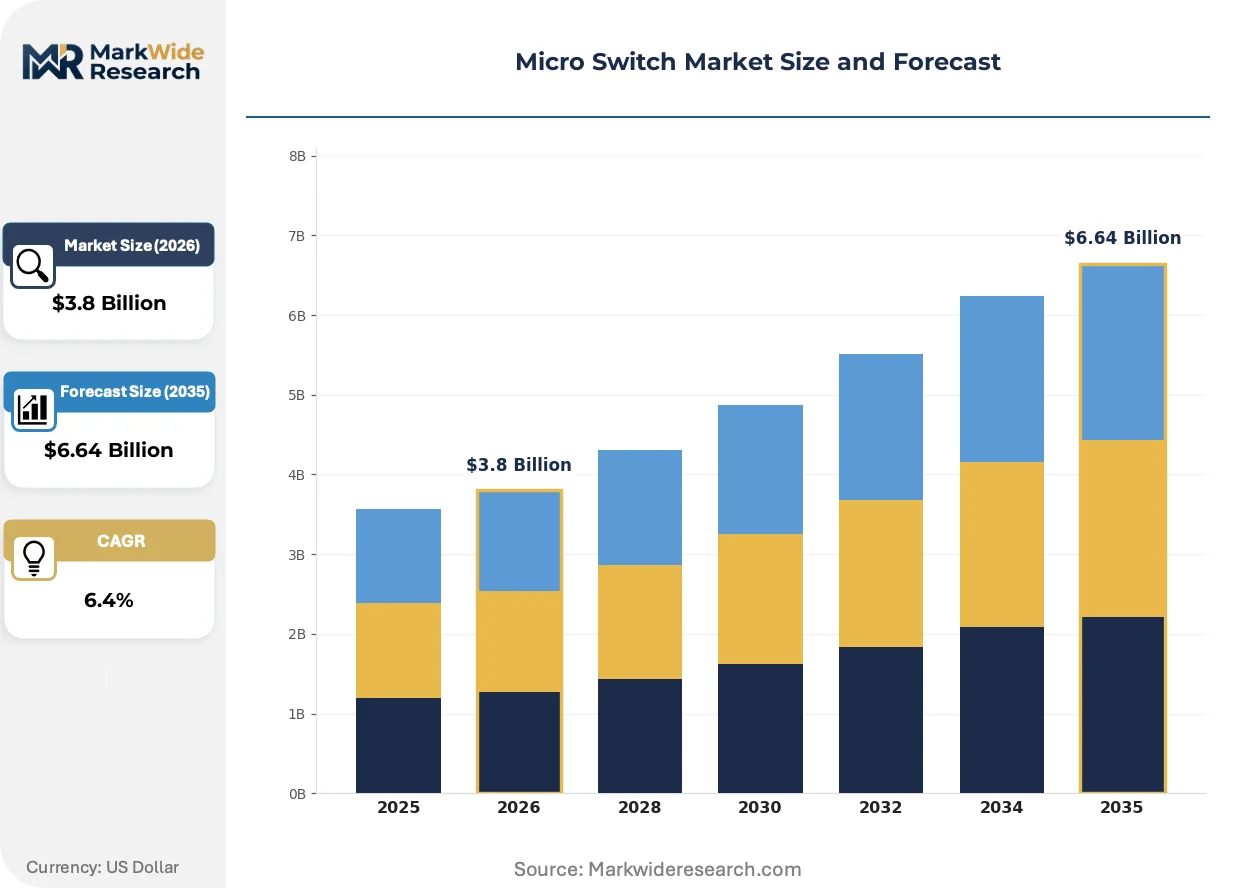
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Switches, Subminiature Switches, Standard Switches, Tactile Switches Application: Consumer Electronics, Automotive, Industrial Automation, Appliances Technology: Electromechanical, Optical, Reed, Hall Effect End User: Manufacturers, OEMs, Distributors, Retailers |
| Companies Covered | Omron Corporation, ALPS Alpine, Honeywell International Inc., TE Connectivity, ZF (CHERRY), Panasonic, Littelfuse, Johnson Electric Holdings Limited, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Switch Market Strategic Shifts
Contactless sensing architectures and modular safety-system integration are restructuring how position-detection components get specified, tested, and replaced across vehicle and industrial equipment lifecycles.
MEMS-based force sensing is unifying mechanical switch and strain-gauge functions into single-package solutions for brake pedal and steering column applications. German Tier-1 chassis suppliers are piloting these fused architectures at platform-program scale. The consolidation is unifying two previously separate supplier qualification paths into one component category, compressing vendor count and simplifying BOM management for EV skateboard platforms.
China's GB/T standards and MIIT certification protocols now mandate cybersecurity documentation for switches deployed in connected vehicle telematics gateways. Domestic OEMs in Beijing and Shanghai accelerate supplier audits to verify firmware-update capabilities in smart-switch modules. The regulatory expansion most affects legacy electromechanical manufacturers lacking embedded systems engineering depth, forcing partnership or acquisition strategies to maintain automotive qualification status.
Consolidated procurement desks at Korean and Japanese electronics conglomerates now specify switch lifecycle data through cloud-based supplier portals rather than discrete datasheet exchange. Distributors in Seoul and Osaka restructure inventory commitments around consumption-forecast sharing, replacing volume-commitment contracts. The behavioral shift concentrates most visibly in East Asian consumer electronics supply chains, where real-time production-line visibility determines supplier scorecard rankings and allocation priority during component shortages.
Micro Switch Market Segmentation
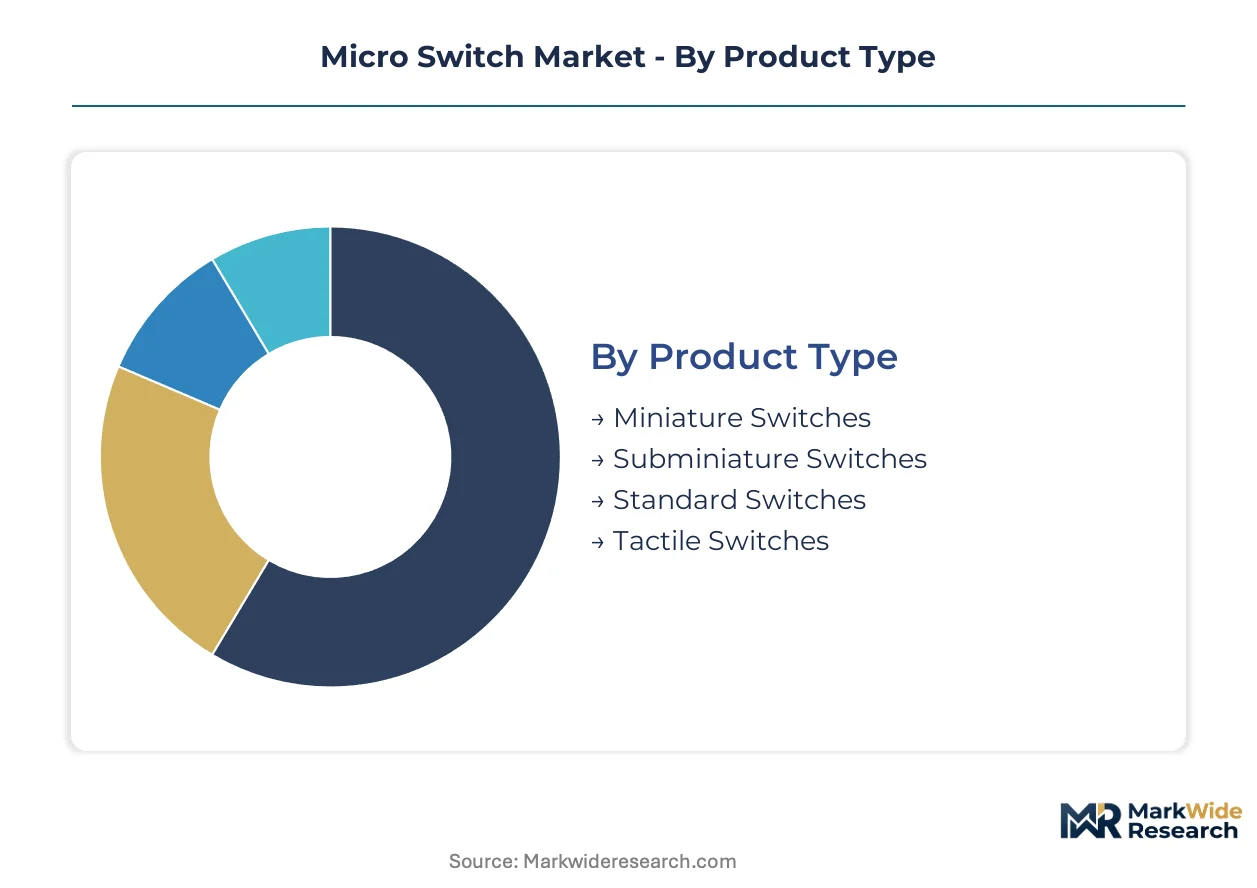
Micro switch procurement patterns diverge sharply across product dimensions, with automotive safety mandates and consumer electronics miniaturization pulling specifications in opposite directions. Certification requirements, actuation force tolerances, and lifecycle ratings determine supplier qualification tiers and pricing bandwidths.
Product Type:
REACH and RoHS compliance burdens concentrate on contact alloy selection for miniature variants, while standard switches face less restrictive material constraints but longer automotive SPICE documentation cycles.
- Miniature Switches:Sub-5mm form factors with gold-nickel or palladium-silver plating dominate Shenzhen and Seoul surface-mount corridors. Wearable OEMs in Guangdong Province specify sub-100gf actuation force for handheld integration, forcing suppliers to maintain ISO 13485-adjacent cleanliness protocols.
- Subminiature Switches:Contact gaps below 0.5mm require precision stamping tolerances achievable only in Zhejiang and Jiangsu province clusters. Medical robotics integrators in Germany specify these for laparoscopic instrument haptic feedback where space constraints override cost considerations.
- Standard Switches:One-million-cycle ratings satisfy industrial automation safety interlocks with less stringent size constraints.
- Tactile Switches:Audible feedback mechanisms concentrate in Korean consumer electronics assembly for appliance control panels.
Miniature switches sit at the top of the volume ranking, with subminiature variants climbing the fastest.
Application:
Cost tier stratification separates MIL-spec aerospace programs from high-volume appliance contracts, with automotive electrification occupying the premium middle band.
- Automotive:Sealed IP67-plus variants with high-temperature ratings capture specification lock-in across German battery pack architectures. NHTSA thermal runaway detection mandates and MIIT safety thresholds force AEC-Q100 qualification at vehicle-program inception, compressing supplier development timelines.
- Consumer Electronics:Sub-3mm actuation travel specifications from Seoul and Osaka procurement desks drive real-time consumption forecasting through cloud-based supplier portals. Distributors restructure inventory commitments around production-line visibility rather than volume-commitment contracts.
- Industrial Automation:IEC 60947-5-1 certification requirements govern position sensing in safety-critical machinery circuits.
- Appliances:BIS certification pathways for induction cooktop safety interlocks remain underpenetrated in India relative to Southeast Asian supply chain maturity.
Consumer electronics commands the highest shipment volumes, with automotive applications expanding most quickly.
Technology:
Customer type determines whether contactless architectures displace mechanical wear or electromechanical heritage sustains procurement relationships.
- Electromechanical:Physical contact mechanisms with fractional-millimeter gaps retain the largest installed base across industrial safety circuits. Margin compression from optical alternatives in medical instrumentation forces palladium-silver plating investments to extend operational life.
- Hall Effect:Contactless magnetic sensing eliminates mechanical wear in automotive transmission and brake-by-wire modules. Fluid-immersed applications above IP67 rating favor this architecture despite higher semiconductor content costs.
- Optical:Beam-interruption mechanisms capture laboratory instrumentation where contamination sensitivity excludes metal contacts.
- Reed:Hermetically sealed glass envelopes serve aerospace applications requiring vacuum-compatible position sensing.
Electromechanical variants lead installed base metrics, with Hall Effect technology gaining share fastest.
End User:
Supply concentration in East Asian stamping corridors shapes distributor margin structures and OEM direct-sourcing incentives.
- OEMs:Tier-one automotive suppliers consolidate procurement tiers and mandate sealed-component qualification at platform inception. PPAP submission requirements compress development timelines for mid-cap manufacturers lacking captive failure analysis laboratories.
- Manufacturers:Captive production for consumer electronics brands concentrates in Guangdong Province surface-mount corridors. Dual carbon compliance timelines in Chinese manufacturing zones alter energy-intensity benchmarks for precision stamping operations.
- Distributors:Seoul and Osaka inventory commitments restructure around consumption-forecast sharing rather than volume contracts.
- Retailers:Aftermarket replacement demand concentrates in North American HVAC and appliance repair channels.
Manufacturers handle the highest transaction volumes, with OEM direct procurement expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electrification programs pull demand toward sealed high-temperature variants, while China's electronics manufacturing clusters dominate miniature switch consumption through Shenzhen and Seoul production corridors.
United States
EV platform architects consolidate supplier tiers and mandate sealed-component qualification at vehicle-program inception. NHTSA thermal runaway detection thresholds force AEC-Q100 documentation for battery pack safety circuits. Midwestern manufacturing zones face MIL-SPEC certification talent scarcity as demographic outmigration outpaces technical training pipeline expansion.
Germany
Tier-one chassis suppliers pilot MEMS-based force sensing architectures that unify mechanical switch and strain-gauge functions. REACH and RoHS frameworks phase out cadmium-bearing contacts, accelerating palladium-silver plating investments. Bavarian automotive corridors anchor specification lock-in for high-temperature variants across battery pack architectures.
China
GB standards and MIIT certification requirements shape product entry protocols for domestic appliance and automotive supply chains. Dual carbon goals across Zhejiang and Jiangsu manufacturing zones alter energy-intensity benchmarks for precision stamping and plating operations. Shenzhen surface-mount assembly corridors concentrate wearable OEM procurement for sub-5mm actuation travel specifications.
South Korea
Consumer electronics conglomerates specify switch lifecycle data through cloud-based supplier portals rather than discrete datasheet exchange. Seoul distributors restructure inventory commitments around consumption-forecast sharing, replacing volume-commitment contracts. Busan-Ulsan production corridors drive real-time production-line visibility requirements that determine supplier scorecard rankings.
India
BIS certification pathways for induction cooktop and washing machine safety interlocks remain underpenetrated relative to Southeast Asian supply chain maturity. PLI scheme incentives pull domestic manufacturing scale for appliance electrification programs. Maharashtra and Gujarat industrial corridors offer first-mover positioning as procurement desks consolidate supplier tiers.
Micro Switch Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across segmented qualification tiers. The vendor base stratifies between electromechanical heritage players, semiconductor-integrated contactless architects, and precision-stamping mid-caps. Three archetypes dominate: aerospace-certified conglomerates with MIL-spec depth, automotive-integrated connector-switch hybridists, and East Asian miniature-switch volume specialists. Competitive moves concentrate on backward integration into contact plating operations and strategic partnerships for embedded systems engineering depth.
Within the diversified conglomerate tier, Omron Corporation and Honeywell International Inc. occupy positions anchored by electromechanical heritage and precision certification depth respectively. TE Connectivity exemplifies the connector-switch integration archetype, while ALPS Alpine represents East Asian volume concentration in surface-mount corridors. These three named entities sit within distinct competitive vectors rather than direct overlap, with each archetype commanding separate procurement relationships based on end-use qualification requirements.
| Leading Market Players |
|---|
| Omron Corporation |
| ALPS Alpine |
| Honeywell International Inc. |
| TE Connectivity |
| ZF (CHERRY) |
| Panasonic |
| Littelfuse |
| Johnson Electric Holdings Limited |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive procurement consolidation toward sealed IP67-plus variants at vehicle-program inception is compressing supplier qualification timelines and forcing plating capacity investments that reshape cost structures across East Asian stamping corridors.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for precision-formed contact springs and switch housings. Three-tier pricing structure across AEC-Q100 automotive, IEC-certified industrial, and standard appliance tiers separates qualification-burdened premiums from commodity spot transactions. Cost compression in miniature switch segments stems from real-time consumption forecasting through Seoul and Osaka cloud portals that eliminate volume-commitment buffers. Appliance OEMs in India exhibit highest price sensitivity due to PLI scheme margin constraints, while German battery pack architects prioritize thermal rating over unit cost.
Supply Chain Analysis
AEC-Q100 and MIL-SPEC certification gating concentrates qualified supply among electromechanical heritage players with captive failure analysis laboratories. Precision stamping draws from China, South Korea, and Japan, with palladium-silver plating feedstock anchored in South African and Russian concentrate markets. Single-source vulnerability runs through Zhejiang province dual carbon compliance timelines where power rationing disrupts stamping operations. Distribution runs through Seoul and Osaka distributor networks restructuring around consumption-forecast sharing rather than volume-commitment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Indian PLI scheme incentives for domestic appliance manufacturing contrast with REACH compliance costs burdening European plating operations, creating margin capture opportunities for suppliers with dual-continent qualification pathways.
For Market Incumbents: Acquire embedded systems engineering capabilities to satisfy GB/T cybersecurity documentation mandates for connected vehicle telematics gateways. Backward integration into palladium-silver plating operations defends margin position against South African concentrate price volatility. Hall Effect displacement in sealed brake-by-wire modules threatens electromechanical heritage; partnership with semiconductor architects preserves automotive qualification status. For New Entrants and Emerging Players: Contactless magnetic sensing architectures offer technology-first wedge into fluid-immersed automotive transmission applications above IP67 rating. BIS certification pathways for induction cooktop safety interlocks in Maharashtra and Gujarat corridors represent the most penetrable geography. ISO 13485-adjacent cleanliness protocols for medical robotics haptic feedback command premium positioning absent in commoditized consumer electronics supply. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-stamping mid-caps possessing Zhejiang province operational footprints and pending AEC-Q100 qualification submissions. Long-term viability hinges on dual-use capability spanning automotive thermal management and medical instrumentation contamination sensitivity. Watch for MIIT cybersecurity documentation mandates triggering acquisition premiums for legacy electromechanical players with embedded systems partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Plating | Captive palladium-silver capacity insulates margins from South African concentrate volatility. |
| Embedded Systems Partnership | GB/T cybersecurity compliance preserves automotive qualification for legacy electromechanical suppliers. |
| AEC-Q100 Certification Investment | Sealed high-temperature variant lock-in across German battery pack architectures commands premium positioning. |
| Cloud-Based Supplier Portal Integration | Real-time consumption forecasting with Seoul procurement desks secures allocation priority during shortages. |
| Dual-Continent Qualification Pathway | Indian PLI scheme positioning plus REACH compliance capability captures geographic arbitrage margins. |
Study Parameters
Bottom-up automotive and consumer electronics modeling reconciled against top-down precision stamping capacity tracking forms the analytical core. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and plating operation technical directors combined with secondary validation from SEC filings, MIIT certification registries, customs trade data, and AEC-Q100 qualification databases. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map contact alloy specifications, actuation force tolerances, and lifecycle ratings to end-use demand across the projection horizon. Segmentation dimensions span product type, application, technology, and end-user archetype with regional production cluster overlay. CAGRs derive from shipment volume reconciliation against plating capacity expansion and qualification pipeline velocity. Forecast inputs include EV platform program timelines and dual carbon compliance trajectory in Chinese manufacturing zones.
The model holds under stable palladium concentrate supply and continued automotive electrification investment; deviation in platinum group metal price volatility or NHTSA thermal runaway detection threshold revisions would shift supplier margin structures. A model refresh is warranted upon material change in MIIT cybersecurity documentation mandates or Indian PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Disconnect Switch Market
Switches
High-Voltage Disconnect Switch Market
Switches
Global Light Control Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Fusible Switches Market
Switches
Safety Limit Switches Market
Switches
Optical Switches Market
Switches
Reed Switches Sensors Market
Switches
Digital Crosspoint Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Smart Home Switches Market
Switches
Global Electrical Switches Market
Switches
Intelligent Power Switches Market
Switches
Campus Switches Market
Switches
Rocker Switch Market
Switches
Carrier Router Switch Market