
 Low Voltage Cable Accessories Market | 2026-2036
Low Voltage Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage Cable Accessories Market Outlook
Capital-intensity divergence between integrated polymer compounders and assembly-focused distributors is bifurcating competitive returns. Prysmian Group leverages captive resin formulation and extrusion capacity to capture margin upstream. TE Connectivity anchors its position through precision-molded connector platforms certified to IEC 60529 ingress-protection tiers. Nexans competes via dedicated low-voltage accessory factories serving European utility procurement frameworks.
Low voltage cable accessories comprise termination kits, splice housings, joint enclosures, and sealing systems engineered for conductors rated below 1 kV AC or 1.5 kV DC, typically molded from cross-linked polyethylene, EPDM rubber, or thermoplastic elastomers with IP-rated sealing geometry. These components ensure electrical continuity, mechanical strain relief, and environmental protection across distribution networks, building infrastructure, and industrial machinery. Connectors and terminations lead product-type revenue due to replacement-cycle density in aging urban grids, while junction boxes represent the fastest-growing category as photovoltaic rooftop installations multiply. Data centers and industrial automation applications command premium positioning because uptime-critical environments demand arc-resistant, halogen-free accessory specifications that carry higher certification burdens.
CE marking under the EU Low Voltage Directive governs market access across Europe, while the US National Electrical Code and OSHA electrical safety standards dictate installation practice and product qualification stateside. China's GB/T standards and CCC certification enforce domestic manufacturing conformity for accessories deployed in state-grid infrastructure. Stakeholders must monitor evolving fire-safety regulations in residential construction and accelerating renewable-interconnection mandates to calibrate product-development roadmaps and regional capacity allocation.
Market Dynamics
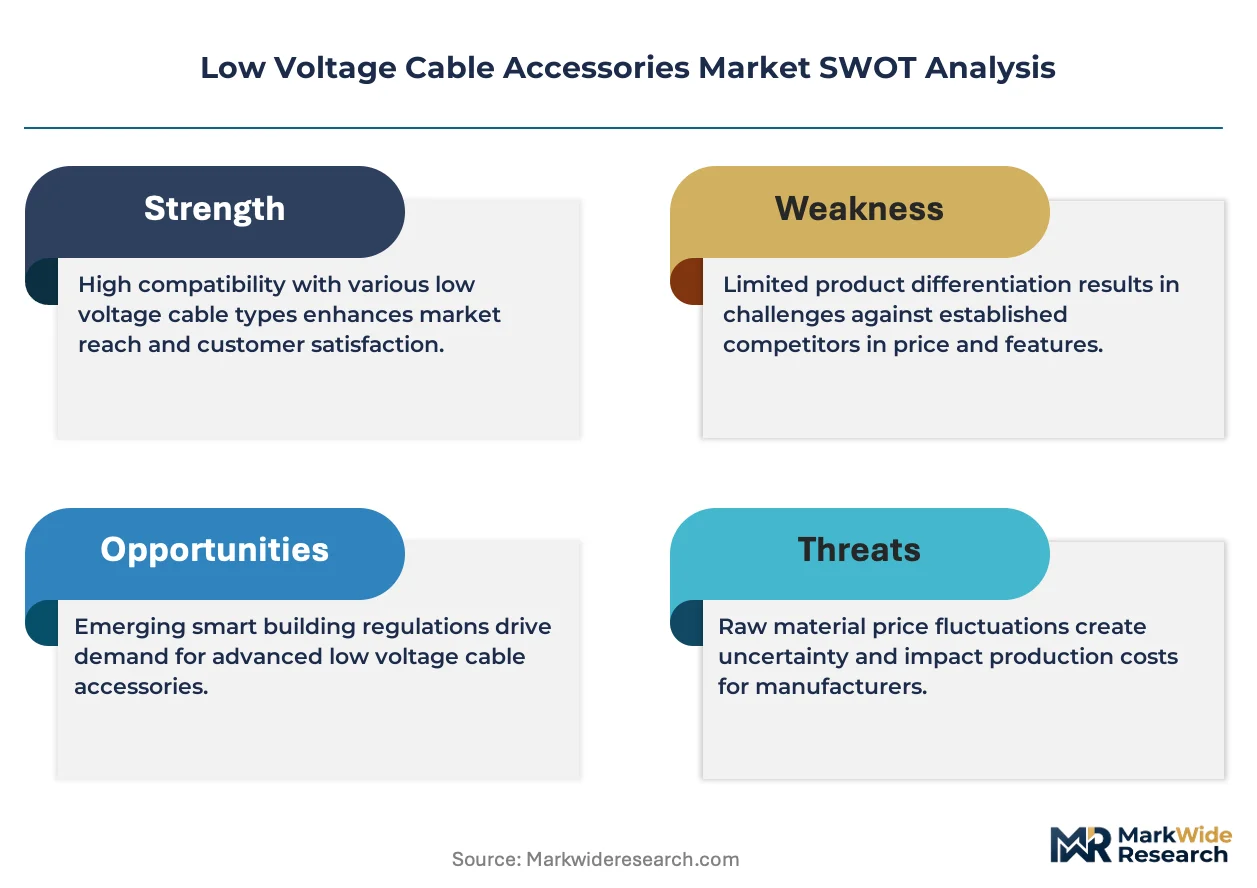
Electrification mandates across building codes and utility procurement frameworks are compressing product lifecycles and forcing compound reformulation decisions before amortization completes.
Growth Catalysts
- EU Green Deal building renovation targets:Member states must double renovation rates by 2030, accelerating junction box and termination kit replacement in existing housing stock.
- Photovoltaic rooftop interconnection standards:Germany's VDE-AR-N 4105 and comparable technical connection rules in California and Australia mandate arc-fault protection accessories that command premium positioning.
- EPDM-to-silicone rubber transition:High-temperature conductor ratings in data center busway applications are pulling material specifications upward.
Market Restraints
- Copper price volatility:LME copper fluctuations above 9,000 USD per metric ton compress termination kit margins for distributors without forward hedging.
- Cross-linked polyethylene resin concentration:Three Korean and Saudi petrochemical groups supply 60 percent of global XLPE compound, creating single-source vulnerability.
- F-Gas Regulation phase-down:Blowing agents for cable sealing foam face supply constraints as EU hydrofluorocarbon quotas tighten through 2030.
Strategic Opportunities
- India smart city distribution automation:State electricity boards in Maharashtra and Gujarat are tendering pre-fabricated splice enclosures for underground residential distribution.
- Halogen-free compound certification:IEC 60754-2 compliance opens building infrastructure segments where fire toxicity regulations exclude conventional PVC accessories.
- E-commerce contractor procurement:Electrical wholesalers in the United States are launching same-day delivery platforms for termination kits, displacing traditional branch counter relationships.
Industry Challenges
- Polymer compounding talent scarcity:Formulation chemists with cross-linking expertise command premium compensation and limited geographic mobility.
- Multi-standard certification timelines:Simultaneous UL, CE, and CCC qualification for a single connector platform extends time-to-revenue by 14-18 months.
- Legacy crimp tooling incompatibility:New insulation-piercing connector designs require contractor field training and inventory turnover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage Cable Accessories Market |
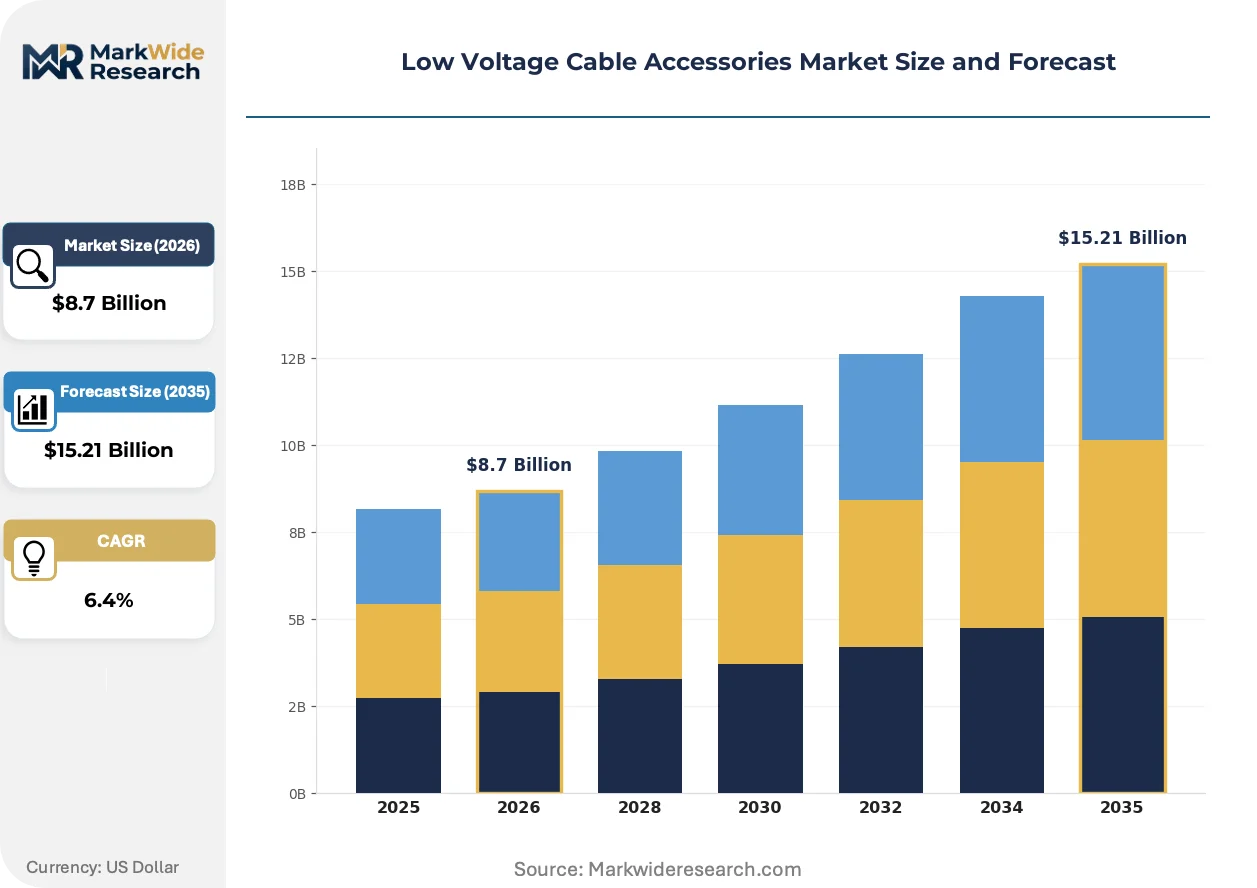
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Terminations, Junction Boxes, Splice Kits Application: Telecommunications, Power Distribution, Data Centers, Industrial Automation End User: Telecom Operators, Utilities, Electrical Contractors, OEMs Installation Type: Indoor, Outdoor, Underground, Aerial |
| Companies Covered | Sumitomo Electric Industries, LS Cable & System, Prysmian Group, TE Connectivity, Southwire Company, Nexans, ABB Ltd., General Cable, NKT A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage Cable Accessories Market Strategic Shifts
Material science advances and procurement digitization are compressing traditional specification hierarchies while opening premium tiers for performance-certified accessories.
Thermoplastic elastomer injection molding is fragmenting the dominance of heat-shrink terminations in secondary distribution networks. European utilities in Denmark and the Netherlands are specifying cold-applied TPE joints for 0.6/1 kV underground residential connections, eliminating field heating equipment and reducing installation time by half. This shift is fragmenting supplier tiers by separating compound formulation capability from simple kit assembly.
EU F-Gas Regulation phase-down schedules are forcing reformulation of sealing compounds and foam-in-place gasket systems used in splice enclosures. Compounders must validate hydrofluoroolefin and hydrocarbon alternatives without sacrificing IP67 ingress protection ratings. German cable accessory factories report 18-month qualification cycles for revised sealing systems, compressing product refresh timelines.
Electrical contractor buying collectives in France and Spain are consolidating purchase volumes and demanding direct manufacturer relationships, bypassing traditional wholesale distribution. These groups negotiate specification compliance guarantees and consolidated logistics rather than spot-price competition. The behavior is most visible in commercial building electrification projects above 500 kVA capacity.
Low Voltage Cable Accessories Market Segmentation
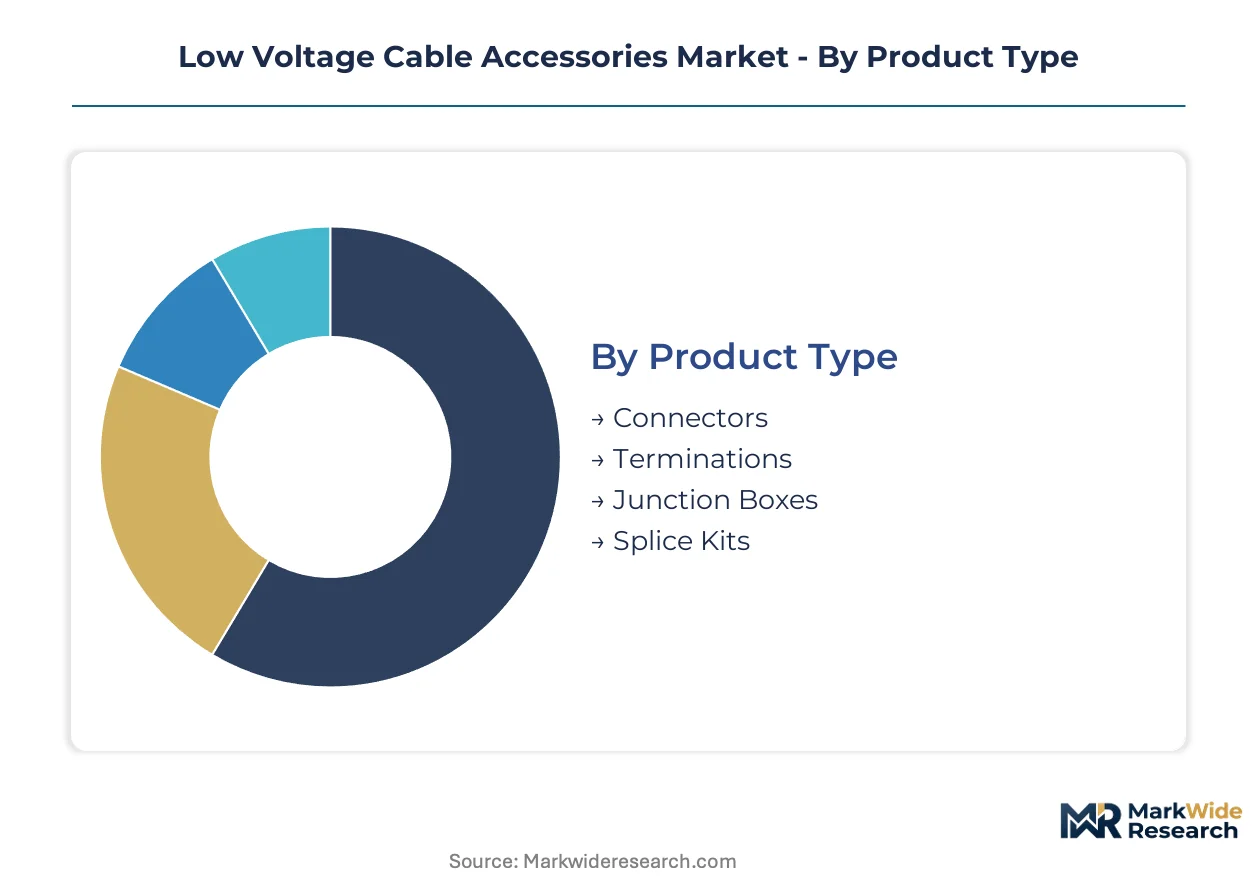
Low voltage cable accessories serve heterogeneous demand profiles across utility procurement frameworks, contractor supply chains, and OEM specification programs. Segmentation reveals how product architectures, installation environments, and buyer types concentrate margin capture differently across channel tiers.
Product Type:
Electrical wholesalers stock termination kits and connectors as high-velocity SKUs, while junction boxes and splice kits flow through project-specific procurement channels with longer sales cycles.
- Connectors:Precision-molded conductor interfaces built from tin-plated copper bodies with thermoplastic housings. Demand clusters in German utility underground residential distribution programs where pre-fabricated connection systems reduce field labor hours. IEC 61215-1 certification requirements for photovoltaic string connections are pulling specification grades upward.
- Terminations:Cold-shrink and heat-shrink assemblies engineered for 0.6/1 kV conductor sealing. Replacement-cycle density in aging urban grids across the United States and China sustains volume, though cold-applied thermoplastic elastomer alternatives are fragmenting technology tiers in European markets.
- Junction Boxes:IP-rated enclosures for conductor branching and protection. German VDE-AR-N 4105 rooftop solar interconnection mandates and comparable California electrical code provisions are expanding specification scope for arc-fault rated variants.
- Splice Kits:Pre-engineered assemblies for conductor repair and extension. Underground residential distribution automation tenders in Maharashtra and Gujarat state electricity boards are opening volume procurement for pre-fabricated splice enclosures.
By volume, connectors lead. By growth pace, junction boxes are climbing the fastest.
Application:
Cost tiers separate commodity-grade accessories for building wiring from performance-certified systems for uptime-critical infrastructure.
- Power Distribution:Grid-tied infrastructure spanning utility substations, transformer secondaries, and building service entrances. EU Green Deal building renovation targets are accelerating termination kit replacement in existing European housing stock.
- Data Centers:Busway and rack-power distribution systems demanding halogen-free, arc-resistant accessory specifications. EPDM-to-silicone rubber transitions are emerging in high-temperature conductor ratings for hyperscale facilities.
- Industrial Automation:Machine-power and control-circuit connectivity with IP67+ ingress protection requirements. IEC 60529 certification tiers command premium positioning against standard commercial-grade alternatives.
- Telecommunications:Copper and fiber-optic cable termination for network infrastructure. 5G small-cell densification programs are expanding outdoor-rated enclosure demand in urban corridors.
Power distribution captures the highest absolute volume. Data center applications show the steepest expansion trajectory.
End User:
Procurement authority patterns separate specification-driven OEM relationships from price-sensitive contractor spot purchasing.
- Utilities:State electricity boards and municipal distribution companies with framework procurement for standardized accessory platforms. India's smart city distribution automation programs are tendering pre-fabricated splice enclosures at scale.
- Electrical Contractors:Project-based buyers consolidating through French and Spanish buying collectives for direct manufacturer relationships. Same-day delivery platforms from US electrical wholesalers are displacing traditional branch counter channels.
- Telecom Operators:Network infrastructure owners specifying outdoor-rated termination systems for 5G and fiber deployments. VDE and UL certification requirements govern vendor qualification.
- OEMs:Original equipment manufacturers integrating accessories into switchgear, panelboards, and industrial machinery. CCC certification in China and CE marking in Europe dictate supply base compliance.
Utilities dominate procurement volume. Contractor collectives are gaining share fastest through channel consolidation.
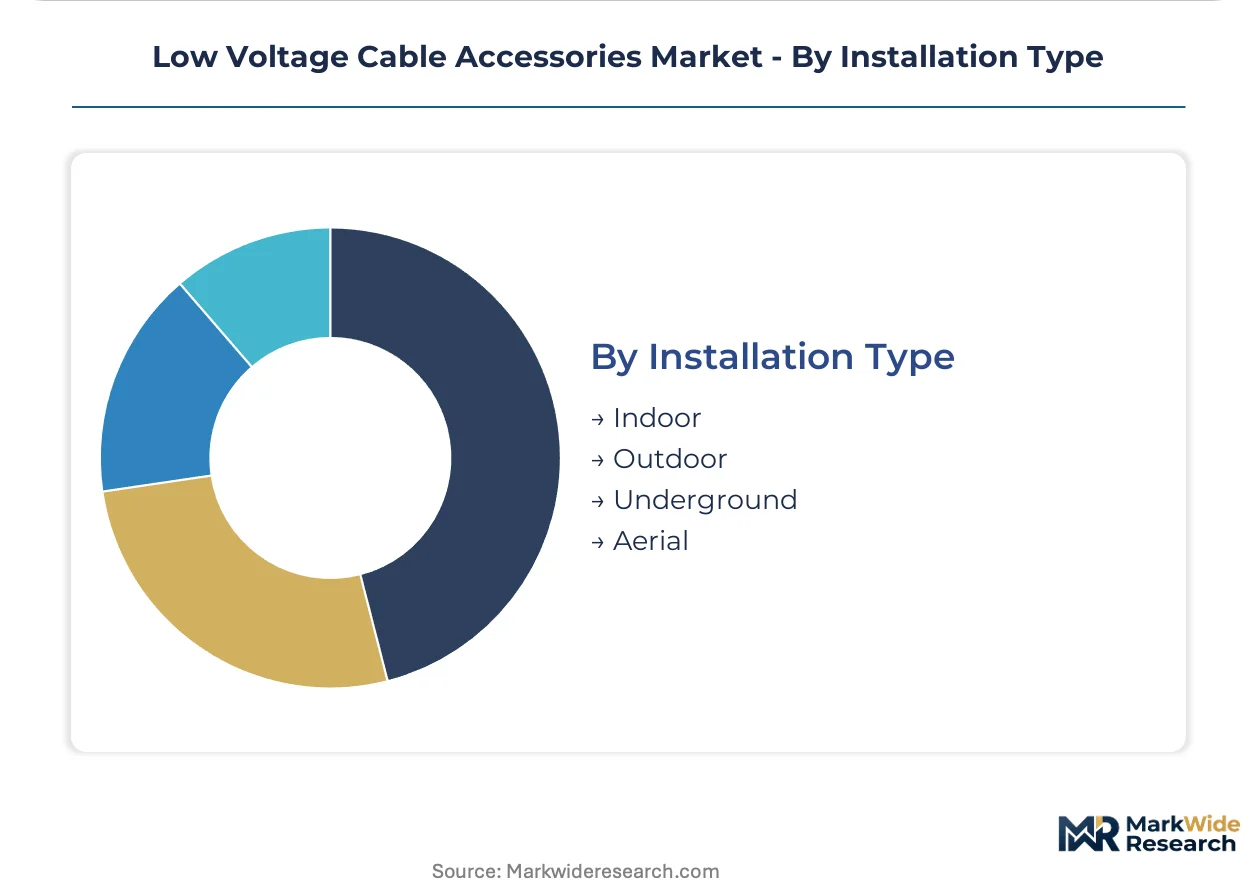
Installation Type:
Environmental exposure severity determines material specification tiers and sealing geometry complexity.
- Underground:Direct-buried and duct-bank installations requiring moisture-blocking and mechanical protection. Danish and Dutch utilities are specifying cold-applied TPE joints for 0.6/1 kV residential connections.
- Outdoor:Above-grade exposure to UV, thermal cycling, and precipitation. IP67 ingress protection ratings and UV-stabilized polymer formulations separate premium from standard tiers.
- Indoor:Controlled-environment building infrastructure with lower sealing burden. Halogen-free compound certification under IEC 60754-2 is opening segments where fire toxicity regulations exclude conventional PVC.
- Aerial:Messenger-supported and self-supporting cable systems for overhead distribution. Mechanical strain relief and wind-loading resistance govern connector and termination design.
Underground installations lead by unit volume. Outdoor applications are expanding most quickly with distributed energy resource interconnection growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical contractors in Germany and the Netherlands accept 15-20% price premiums for cold-applied thermoplastic elastomer systems, while Indian state electricity boards prioritize lowest-compliant-bid procurement for pre-fabricated splice enclosures.
Germany
VDE-AR-N 4105 rooftop solar interconnection mandates are accelerating arc-fault rated junction box procurement across residential construction. The EU Green Deal building renovation targets are compressing replacement cycles for termination kits in existing housing stock. Industrial clusters in North Rhine-Westphalia and Bavaria host dedicated low-voltage accessory factories serving European utility procurement frameworks.
United States
OSHA electrical safety standards and National Electrical Code provisions dictate installation practice and product qualification for termination systems. Data center busway applications in Northern Virginia and Phoenix hyperscale corridors are pulling EPDM-to-silicone rubber material specifications upward. Same-day delivery platforms from electrical wholesalers are displacing traditional branch counter relationships for contractor procurement.
China
GB/T standards and CCC certification enforce domestic manufacturing conformity for accessories deployed in state-grid infrastructure. Dual carbon goals are tightening fire-safety regulations in residential construction and accelerating renewable-interconnection mandates. Yangtze River Delta manufacturing bases concentrate cross-linked polyethylene compounding capacity for regional distribution networks.
India
Maharashtra and Gujarat state electricity boards are tendering pre-fabricated splice enclosures for underground residential distribution automation. The country's national electrical regulator enforces technical standards for grid-connected infrastructure. Smart city programs in Mumbai and Ahmedabad are opening volume procurement channels for utility-standardized accessory platforms.
Denmark
Danish utilities are specifying cold-applied TPE joints for 0.6/1 kV underground residential connections, eliminating field heating equipment and reducing installation time. REACH compliance requirements are reshaping material specifications for insulation and sealing compounds. Copenhagen-area distribution automation projects are consolidating procurement through framework agreements with compound-integrated suppliers.
Low Voltage Cable Accessories Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the low voltage cable accessories market. Captive resin formulation and extrusion capacity separate margin-capturing compounders from assembly-focused distributors. Three archetypes dominate: vertically integrated polymer compounders, precision-molded connector specialists, and project-logistics distributors. Competitive moves concentrate on M&A for regional certification portfolios and capacity expansion in high-temperature silicone rubber compounding.
Among Japan-based industrial conglomerates, Sumitomo Electric Industries exemplifies the integrated materials-to-systems archetype. TE Connectivity anchors the precision-molded connector tier with IEC 60529 ingress-protection certification platforms. Prysmian Group occupies a position representing captive upstream compounding integrated with European utility channel access.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| LS Cable & System |
| Prysmian Group |
| TE Connectivity |
| Southwire Company |
| Nexans |
| ABB Ltd. |
| General Cable |
| NKT A/S |
| Others |
Value Chain & Pricing Dynamics
Thermoplastic elastomer substitution for heat-shrink terminations is simultaneously shifting supply geography toward German and Dutch compounders and compressing pricing premiums for field-installation equipment bundles. This material transition rewards integrated polymer formulators with captive extrusion capacity while squeezing margin for kit assemblers dependent on third-party resin supply.
Pricing Analysis
After-sales service contracts and extended warranty bundles drive lifetime value for precision-molded connector platforms. Three-tier pricing structure across arc-fault certified premium, standard IEC 60529, and economy PVC tiers separates utility framework procurement from contractor spot purchasing. Pricing pressure stems from copper price volatility above historical baselines, compressing termination kit margins for distributors lacking forward hedging programs. Electrical contractors in French and Spanish buying collectives exhibit highest price sensitivity through consolidated volume negotiations, while data center operators show lowest sensitivity due to uptime-critical specification requirements.
Supply Chain Analysis
South Korea and Saudi Arabia anchor cross-linked polyethylene resin supply for global cable accessory manufacturing. Raw material flows draw from petrochemical feedstocks, EPDM rubber compounds, and thermoplastic elastomer pellets. Single-source vulnerability concentrates in XLPE compound where three petrochemical groups control majority supply. Distribution runs through electrical wholesalers for high-velocity SKUs and project-specific channels for junction boxes and splice enclosures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down constitutes a regulatory inflection forcing 18-month reformulation cycles for sealing compounds, accelerating competitive turnover beyond typical product amortization timelines.
For Market Incumbents: Compound formulation expertise in hydrofluoroolefin alternatives to defend IP67 certification tiers against new entrants lacking qualification infrastructure. Expand captive silicone rubber compounding capacity for data center busway applications before EPDM displacement accelerates. Prioritize direct relationships with French and Spanish contractor collectives bypassing wholesale intermediaries. For New Entrants and Emerging Players: Anchor in Maharashtra and Gujarat state electricity board tenders for pre-fabricated splice enclosures, the most penetrable procurement channel given lowest-compliant-bid protocols and limited incumbent localization. Pursue halogen-free IEC 60754-2 certification as go-to-market wedge against PVC-legacy suppliers excluded from European building infrastructure segments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical distribution platforms lacking upstream polymer compounding integration. Five-to-ten year viability hinges on material science capabilities and regional certification portfolios rather than pure assembly scale. Monitor EU hydrofluorocarbon quota tightening as signal for consolidation timing among sealing compound specialists.| Strategic Initiative | Industry Significance |
|---|---|
| High-Temperature Silicone Compounding Expansion | Captures EPDM displacement in hyperscale data center busway specifications across Northern Virginia and Phoenix corridors. |
| Direct Contractor Collective Partnership | Bypasses wholesale intermediaries in French and Spanish markets consolidating procurement above 500 kVA project thresholds. |
| Halogen-Free Certification Investment | Unlocks building infrastructure segments where IEC 60754-2 compliance excludes conventional PVC accessory suppliers. |
| Pre-Fabricated Splice Enclosure Localization | Positions for Maharashtra and Gujarat state electricity board automation tenders in underground residential distribution. |
| Cold-Applied TPE Joint Platform Launch | Addresses Danish and Dutch utility specifications eliminating field heating equipment and reducing installation labor by half. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, utility procurement frameworks, and petrochemical supply disclosures. Interviews with polymer formulation chemists, electrical contractor procurement leads, and state electricity board tender officers informed demand-side validation. Regulatory filings with ECHA on REACH compliance and EU F-Gas Regulation phase-down schedules anchored supply-side constraints. Bottom-up product-type volume builds triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product architecture, installation environment exposure, end-user procurement authority, and regional regulatory framework clusters. CAGRs derive from trend-line extrapolation moderated by substitution elasticity parameters for material transitions and adoption curve analysis for cold-applied installation technologies. Forecast inputs incorporate EU Green Deal renovation target trajectories and photovoltaic interconnection standard proliferation.
Material uncertainties — copper price volatility, XLPE resin supply disruption, and multi-standard certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement consistency and contractor training adoption rates for insulation-piercing connector designs. Recalibration cycles align with material shifts in polymer specifications and utility procurement framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Middle East Cable Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Cable Carrier Market
Cables
FFC/FPC Jumper Cables Market
Cables
North America Wire and Cable Market
Cables
Ethernet Converters Market
Cables
Instrumentation Cables Market
Cables
LASER Light Cables Market
Cables
Asia-Pacific Premise Cable Market
Cables
Patch Cable Market
Cables
US Cables Market
Cables
Copper Cable Market
Cables
Cable Flange Market
Cables
Low-Temperature Cable Market
Cables
Europe Cable Joints Market
Cables
Power Cable Accessories Market