
 Power Connector Market | 2026-2036
Power Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Power Connector Market Analytics
Asian contract manufacturers is decoupling from legacy European supply chains as regional capacity for high-current connector assemblies expands. TE Connectivity leverages backward integration into precision stamping operations to secure copper alloy feedstock. Amphenol Corporation sustains technology leadership in ruggedized military-aerospace interconnects. Molex dominates automotive high-voltage connector architectures for electric powertrains.
A power connector is an electromechanical device engineered to join electrical terminations and create a circuit, typically rated from milliamps to thousands of amps with specified contact resistance below 5 milliohms. These components employ copper or copper-alloy contacts plated with tin, silver, or gold to manage conductivity and corrosion resistance across temperature ranges spanning minus 55 to 175 degrees Celsius. Automotive applications command the largest value pool as electrified powertrains replace mechanical systems. Wire-to-board installations represent the fastest-expanding installation category, driven by miniaturized consumer electronics and dense industrial control panels. Composite material connectors are capturing margin from aluminum alternatives in weight-sensitive aerospace and mobility segments.
UL standards in the United States, CE marking under the EU's Low Voltage Directive, and China's GB/T national standards collectively govern safety clearance, flammability ratings, and interoperability testing for power connector certification. REACH and RoHS frameworks in Europe restrict hazardous substances in contact platings and housing polymers, compelling reformulation of legacy product lines. Stakeholders must monitor evolving EV charging standards and regional content requirements as electrification policies fragment certification pathways across jurisdictions.
Market Dynamics
Electrification mandates across automotive supply chains are forcing connector manufacturers to reengineer contact geometries and thermal management systems for sustained high-current transmission. This structural pressure is compressing development cycles and redrawing competitive boundaries between legacy industrial specialists and emerging EV-native suppliers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating demand for hermetic sealing solutions in refrigeration and HVAC interconnects, pulling specialty connector architectures into climate-control equipment supply chains.
- Factory electrification:Germany's industrial automation corridor is deploying high-reliability connector systems for motor drives and power distribution, creating sustained pull for ruggedized contact technologies.
- Copper-alternative materials:Aluminum-copper hybrid conductors and silver-plated aluminum contacts are penetrating weight-sensitive mobility applications, expanding addressable markets beyond traditional copper-dependent architectures.
Market Restraints
- Copper price volatility:Contact material costs swing with LME copper futures, squeezing gross margins for manufacturers locked into fixed-price OEM contracts without raw material pass-through clauses.
- Asian supply concentration:Precision stamping and plating capacity clusters in China's Pearl River Delta, creating single-source vulnerability for European and North American connector assemblers.
- REACH substance restrictions:Cadmium and lead limitations in contact platings force expensive reformulation of legacy product lines, extending qualification timelines with safety-critical end-users.
Strategic Opportunities
- India manufacturing:Production-linked incentive schemes for electronics and automotive components are attracting connector assembly investments to serve domestic OEMs and re-export markets.
- Wireless power integration:Inductive charging coil modules are converging with traditional connector footprints in consumer electronics, opening hybrid power interface categories.
- Second-life EV battery interconnects:Stationary energy storage deployments require reworked high-voltage connector architectures, creating aftermarket demand streams parallel to new vehicle production.
Industry Challenges
- High-voltage safety certification:UL 4128 and IEC 61984 test protocols for 800V+ automotive systems demand specialized arc-quenching contact designs, extending engineering validation cycles.
- Legacy system integration:Industrial retrofit projects require backward-compatible connector geometries that bridge decades-old pin configurations with modern power densities, complicating product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Connector Market |
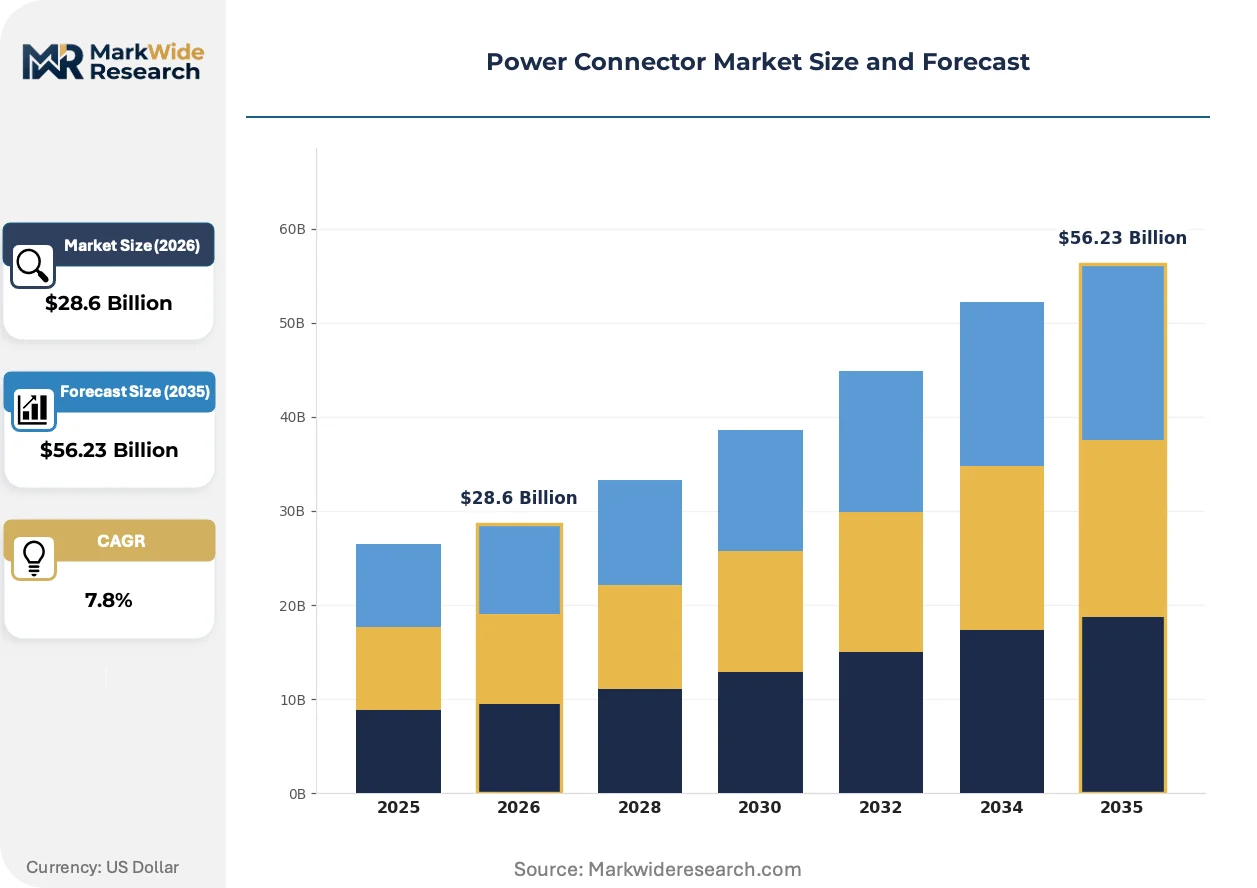
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Plug, Socket, Adapter, Receptacle Application: Automotive, Industrial Equipment, Consumer Electronics, Telecommunications Material: Copper, Aluminum, Plastic, Composite Installation: Panel Mount, Through Hole, Wire-to-Wire, Wire-to-Board |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Phoenix Contact, Hirose Electric, HARTING Technology Group, ITT Inc., Yazaki Corporation, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Connector Market Evolving Landscape
Contact metallurgy and housing thermoplastics are undergoing simultaneous transformation as thermal loads rise and sustainability frameworks tighten. These material shifts are reshaping supplier qualification criteria and compressing technology refresh cycles across end-use verticals.
Silver-graphene composite plating is converging with traditional tin-over-nickel finishes in high-frequency power applications. Aerospace harness manufacturers are piloting these deposits for satellite busbar interconnects, attracted by reduced contact resistance at cryogenic temperatures. The convergence is enabling denser power distribution without increasing connector mass or footprint.
REACH authorization procedures are tightening scrutiny on chromium trioxide in decorative and functional plating. Connector manufacturers serving European medical and industrial markets are accelerating transitions to trivalent chromium and thin-film ceramic alternatives. German automotive Tier-1s are now mandating full material disclosure through SCIP database entries, pushing supply chain transparency upstream to raw material smelters.
Specification consolidation among industrial buyers is compressing approved vendor lists for critical power distribution systems. Large-scale datacenter operators in Virginia and Frankfurt are standardizing on single-source connector families across facilities, trading supply redundancy for volume pricing and simplified sparing. This concentration is visible most acutely in hyperscale cloud infrastructure deployments where interchangeability outweighs multi-source risk mitigation.
Power Connector Market Segmentation
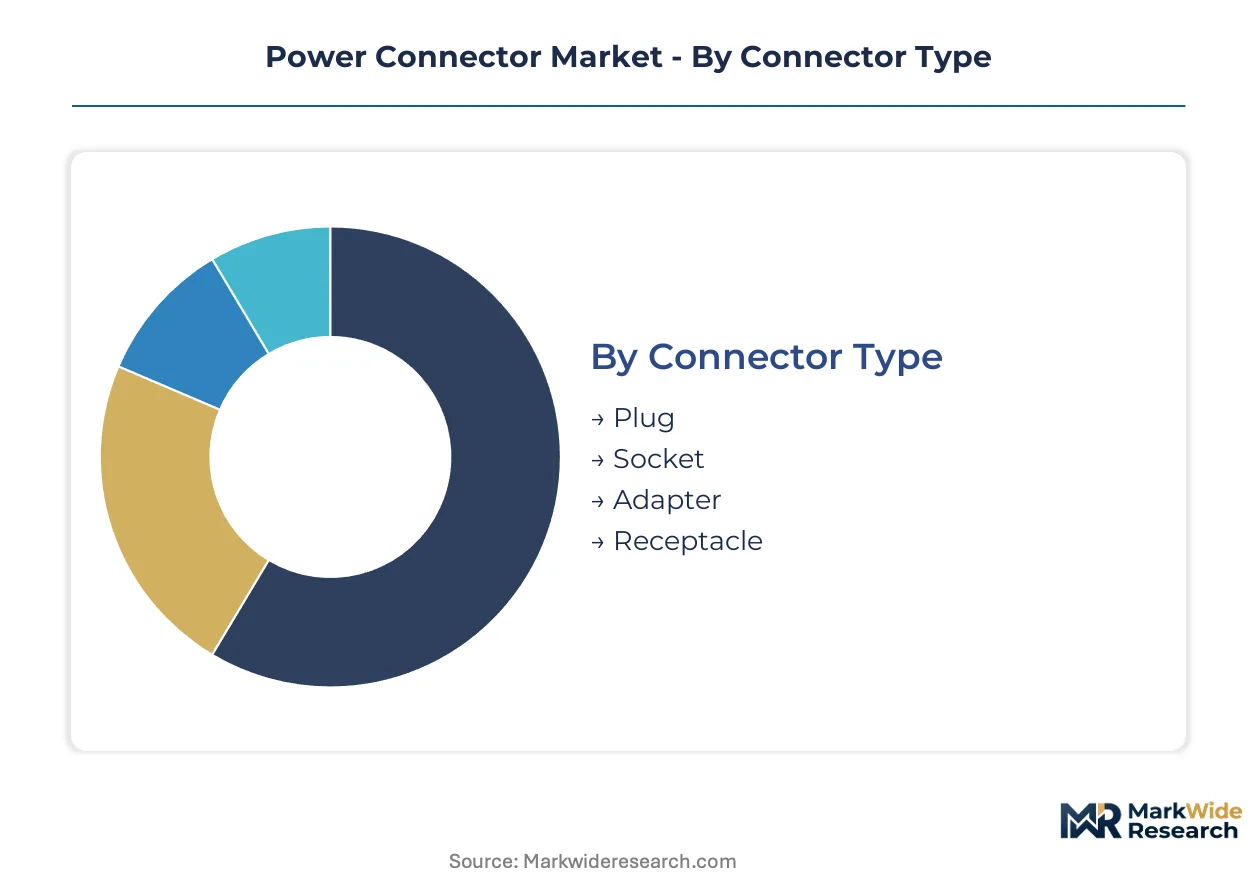
Power connector architectures fragment across integration depth, material composition, and installation environment. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Connector Type:
Standalone plug-and-socket assemblies serve field-replaceable applications, while embedded receptacles integrate permanently into end-equipment chassis. This integration-depth split determines warranty exposure and aftermarket revenue capture for manufacturers.
- Plug:Male-contact housings engineered for repeated mating cycles, typically rated for 500-10,000 insertion cycles depending on contact plating thickness. Automotive charging infrastructure in Germany and China's Pearl River Delta is pulling high-cycle variants for DC fast-charging stations. The EU F-Gas Regulation is accelerating hermetic plug demand for refrigeration compressors.
- Socket:Female-contact receptacles designed for panel or chassis mounting with retention mechanisms for vibration resistance. Industrial motor drives across India's manufacturing corridors require IP67-sealed socket variants for dusty environments. REACH substance restrictions are forcing nickel-plating reformulations in European medical equipment sockets.
- Adapter:Intermediary devices bridging incompatible connector families, often incorporating voltage transformation or protocol conversion.
- Receptacle:Fixed-position connectors integrated permanently into equipment housings, common in aerospace and medical devices where field replacement is restricted.
Volume placements concentrate in Socket configurations for industrial retrofits; the faster expansion belongs to Plug architectures for EV charging infrastructure.
Application:
End-use verticals impose divergent thermal, vibration, and safety certification requirements that filter supplier eligibility. Cost tiers stratify sharply between safety-critical automotive and price-sensitive consumer electronics.
- Automotive:High-voltage interconnects for electrified powertrains, spanning 48V mild-hybrid to 800V+ battery electric architectures. OEMs in Stuttgart and Shanghai are qualifying 800V connector systems for next-generation EV platforms. NHTSA and China's MIIT are tightening high-voltage safety protocols.
- Industrial Equipment:Ruggedized connectors for motor drives, power distribution, and factory automation with extended temperature ratings.
- Consumer Electronics:Miniaturized low-current connectors for smartphones, laptops, and wearables where footprint and cost dominate specifications.
- Telecommunications:High-density power connectors for datacenter racks and 5G base stations requiring hot-swappable capabilities.
Revenue concentrates in Automotive electrification programs; margin expansion is steepest in Telecommunications hyperscale deployments.
Material:
Conductive and structural material choices trade electrical performance against weight, cost, and regulatory compliance. Supply concentration in copper refining shapes procurement strategies across all tiers.
- Copper:Primary contact material offering conductivity of 100% IACS with tin, silver, or gold plating for oxidation resistance. Aerospace harness manufacturers in Toulouse and Seattle specify oxygen-free copper for satellite applications. LME copper price volatility is compressing margins for fixed-price OEM contracts.
- Aluminum:Lightweight conductor material penetrating weight-sensitive mobility applications through copper-clad and plated variants.
- Plastic:Housing thermoplastics including PBT, PA66, and LCP with UL94 flammability ratings for insulation and mechanical retention.
- Composite:Fiber-reinforced polymer housings and hybrid conductor systems for aerospace and advanced mobility segments.
Procurement weighting favors Copper for established platforms; Composite adoption is climbing fastest in next-generation aerospace programs.
Installation:
Mounting methodology determines manufacturing integration depth and field service accessibility. Panel and through-hole variants embed permanently; wire-terminated styles enable modular system architecture.
- Wire-to-Board:Connectors terminating discrete conductors directly to printed circuit boards, enabling dense power distribution in miniaturized electronics. Datacenter operators in Virginia and Frankfurt are standardizing wire-to-board families across facilities for sparing efficiency. Miniaturization trends in industrial control panels are pulling 2-6mm pitch variants.
- Panel Mount:Flanged connectors secured through equipment chassis walls for external cable attachment.
- Through Hole:Pins soldered through PCB vias for mechanical robustness in high-vibration environments.
- Wire-to-Wire:Inline connectors joining cable assemblies without board interface, common in automotive harnesses.
Standardization concentrates in Wire-to-Board for datacenter builds; Wire-to-Wire is expanding most quickly in modular automotive harness architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in Chile and Peru anchors raw-material supply for connector manufacturers serving electrification markets worldwide. Demand geography splits between established industrial automation corridors and emerging EV manufacturing clusters.
Germany
Factory electrification across Baden-Württemberg and Bavaria is pulling high-reliability connector systems for motor drives and power distribution. The EU F-Gas Regulation accelerates hermetic sealing demand for refrigeration and HVAC interconnects. Stuttgart-based automotive OEMs are qualifying 800V connector architectures for next-generation EV platforms.
China
MIIT tightening of high-voltage safety protocols is compressing engineering validation cycles for domestic EV-native suppliers. GB/T national standards govern interoperability testing for charging infrastructure interconnects. The Pearl River Delta hosts precision stamping and plating capacity clusters serving European and North American connector assemblers.
United States
NHTSA protocols for 800V+ automotive systems demand specialized arc-quenching contact designs from safety-critical suppliers. UL 4128 certification requirements extend qualification timelines with OEMs. Virginia datacenter operators are standardizing wire-to-board connector families across hyperscale facilities for sparing efficiency.
India
Production-linked incentive schemes for electronics and automotive components are attracting connector assembly investments to serve domestic OEMs. BIS standards increasingly govern safety clearance and flammability ratings for industrial applications. Manufacturing corridors in Maharashtra and Tamil Nadu are expanding capacity for high-current connector assemblies.
Japan
METI industrial policy supports next-generation mobility electrification requiring miniaturized high-density interconnects. JIS standards maintain rigorous qualification barriers for aerospace and medical device connectors. Nagoya-area automotive suppliers are integrating ruggedized socket variants for vibration-resistant motor drive applications.
Power Connector Market Competitive Landscape
Global majors compete with regional champions across certification breadth and vertical specialization. The vendor base stratifies into three tiers: diversified electromechanical conglomerates with captive materials science capabilities, mid-scale specialists dominating single end-use verticals, and contract manufacturers serving price-sensitive consumer electronics. Consolidation pressure concentrates among automotive-qualified suppliers as 800V+ electrification programs compress approved vendor lists. Dominant competitive moves include backward integration into precision stamping operations and geographic expansion through India manufacturing incentives.
Within the diversified conglomerate tier, TE Connectivity, Amphenol Corporation, and Molex exemplify archetypes spanning industrial automation, military-aerospace, and automotive electrification respectively. TE Connectivity anchors the materials-integrated segment through upstream control over copper alloy feedstock. Amphenol Corporation occupies a position in ruggedized interconnects for safety-critical applications. Molex sits within the high-voltage automotive specialization vector, representing the EV-native supplier archetype competing with legacy industrial incumbents.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Phoenix Contact |
| Hirose Electric |
| HARTING Technology Group |
| ITT Inc. |
| Yazaki Corporation |
| Aptiv |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany's industrial automation corridor anchor supply discipline through captive stamping operations, converting raw copper volatility into predictable contract pricing for automotive OEMs while insulating margins from spot-market swings.
Pricing Analysis
Warranty bundling separates automotive-qualified suppliers from unbundled industrial distributors, with Stuttgart-based OEMs demanding 10-year corrosion coverage that inflates upfront quotes. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL certification grade and volume scale. Cost compression in economy-tier consumer electronics runs through fixed-price Asian contract manufacturing. Datacenter operators in Virginia exhibit least price sensitivity, prioritizing interchangeability over multi-source savings.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore feed hub-and-spoke patterns into European and Southeast Asian manufacturing clusters. Copper refining in Chile and Peru, precision stamping in China's Pearl River Delta, and final assembly in Germany and Mexico concentrate upstream capacity. Single-source vulnerability in high-current plating capacity threatens continuity. Distribution runs through authorized distributor networks with consignment inventory at major OEM hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power connector market functions as a vertical-integration race where upstream control over copper alloy feedstock and downstream certification relationships determine survival. Players are pursuing backward integration into precision stamping to lock in material access.
For Market Incumbents: Deploy captive copper alloy smelting partnerships to neutralize LME price volatility squeezing fixed-price automotive contracts. Consolidate approved vendor lists by acquiring mid-scale specialists with existing UL 4128 qualifications, blocking EV-native entrants from certification pathways. Amphenol Corporation's military-aerospace anchor provides a defensive template.
For New Entrants and Emerging Players: Second-life EV battery interconnects represent an underserved buyer archetype with fragmented supplier coverage and lower certification barriers than new vehicle programs. India's production-linked incentive schemes offer the most penetrable geography for greenfield assembly investments. Pursue direct OEM relationships bypassing incumbent distributor networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor copper-dependent mid-caps in Germany's industrial corridor facing REACH reformulation costs. Long-term viability hinges on material science capabilities beyond commodity stamping. Monitor EU F-Gas Regulation implementation timelines as inflection indicators for hermetic sealing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Alloy Feedstock | TE Connectivity's captive smelting partnerships neutralize LME volatility for fixed-price OEM contracts. |
| REACH-Compliant Plating Reformulation | Trivalent chromium transitions unlock European medical equipment sockets previously blocked by cadmium restrictions. |
| India Manufacturing Footprint Expansion | PLI scheme benefits attract assembly investments serving domestic automotive OEMs and re-export markets. |
| 800V High-Voltage Certification Investment | UL 4128 qualification separates automotive suppliers from industrial incumbents in next-generation EV platforms. |
| Hermetic Sealing Technology Acquisition | EU F-Gas Regulation compliance pulls specialty architectures into refrigeration and HVAC supply chains. |
Research Methodology
SEC 10-K filings, customs trade databases, and copper futures exchange records formed the secondary backbone, cross-referenced with primary interviews across automotive Tier 1 procurement officers, industrial plant engineers, connector distributor category managers, and regulatory compliance specialists. Bottom-up bill-of-materials analysis triangulated against top-down OEM spending disclosures.
Historical trendline analysis of copper-intensive component markets established baseline growth patterns across the projection horizon. Segmentation modeling incorporated connector type, installation methodology, material composition, and regional regulatory cluster dimensions. CAGRs derived from supply-side capacity expansion schedules and demand-side electrification policy trajectories. EV charging infrastructure deployment curves and factory automation capital expenditure cycles served as industry-specific forecast inputs.
Revisions become necessary when REACH substance restrictions expand, copper price volatility exceeds historical bands, or 800V safety certification protocols shift. Forecasts reflect documented assumptions around OEM electrification timelines and regional content requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Japan Connector Market
Connectors
Canada Connector Market
Connectors
Magnetic Connector Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Automotive Data Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
Space Grade Connectors Market
Connectors
Filtered Connectors Market
Connectors
AS-Interface Market
Connectors
Global Automotive Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Connector Adapter Kits Market
Connectors
Circular Waterproof Connector Market
Connectors
Connector for PV System Market
Connectors
Australia Connector Market