
 Global Electronics Adhesives Market | 2026-2036
Global Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronics Adhesives Market Foresight
Buyer concentration among consumer electronics manufacturers is rebalancing as original design manufacturers diversify supply sources beyond traditional contract assemblers. Henkel AG & Co. KGaA leverages its European formulation heritage to sustain leadership in thermally conductive grades for power electronics. Dow Inc. anchors North American supply through integrated silicone resin production, while Shin-Etsu Chemical dominates Asia-Pacific feedstock channels with captive organosilicon manufacturing.
Electronics adhesives are specialty bonding agents engineered with dielectric constants below 4.0 and thermal conductivities exceeding 1.5 W/m·K, formulated for precision attachment of heat-sensitive components without mechanical fasteners. Epoxy formulations occupy the largest volume share due to established reliability in semiconductor underfill and PCB lamination, while UV-cure acrylics represent the fastest-expanding technology segment driven by throughput demands in display assembly lines. Conductive adhesive technology commands premium positioning as silver-filled epoxies displace solder in temperature-restricted sensor module applications.
EPA toxicity evaluations and REACH SVHC candidate list expansions are forcing reformulation timelines across imported and domestically produced adhesive lines. ECHA restriction proposals on bisphenol derivatives intersect with FDA indirect food-contact adhesive clearances to create dual-compliance burdens for wearable device manufacturers. Stakeholders must monitor regulatory divergence between EU substance restrictions and US state-level disclosure mandates to avoid supply chain fragmentation.
Market Dynamics
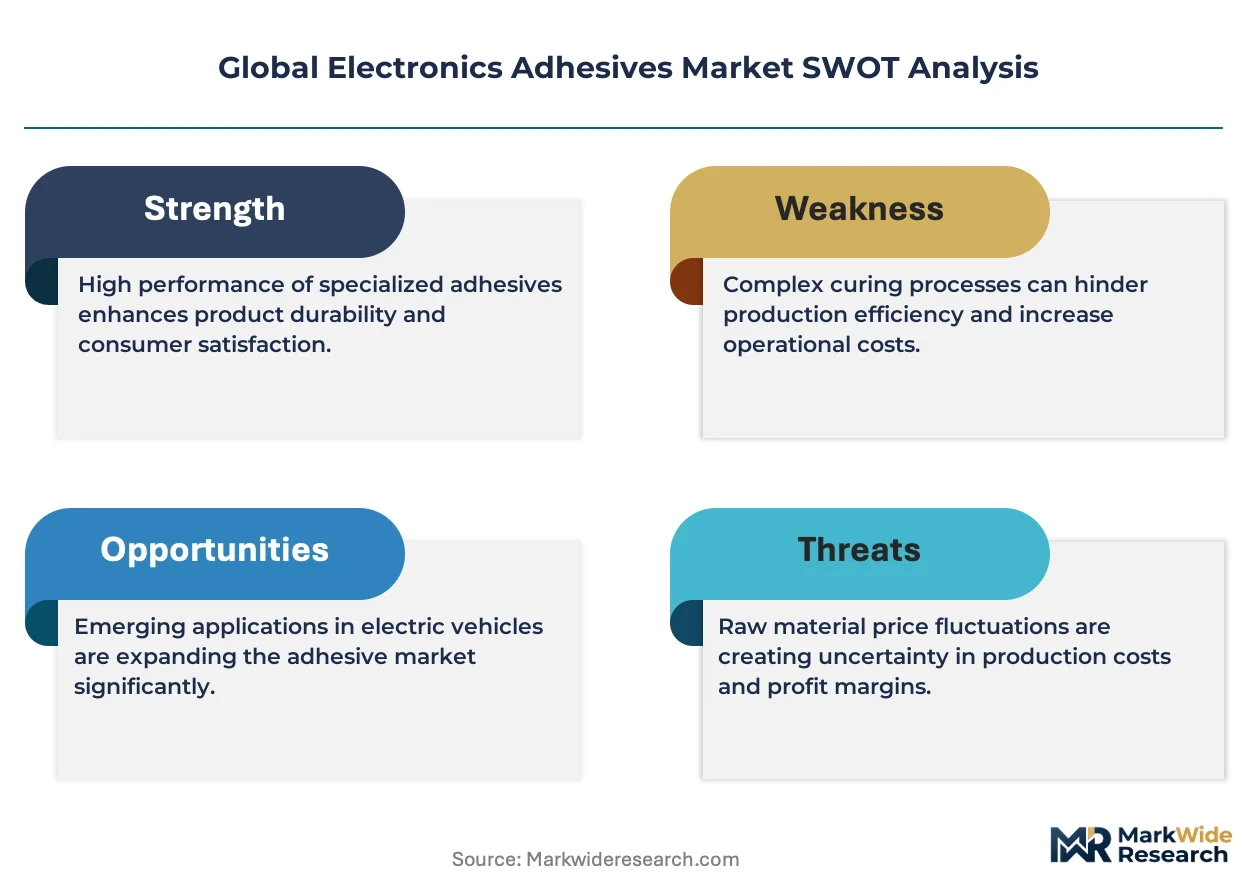
Device miniaturization in consumer electronics is compressing bond-line tolerances below 50 microns, forcing adhesive suppliers to reformulate for precision dispensing without sacrificing thermal management performance.
Growth Catalysts
- REACH SVHC restrictions:European substance regulations are accelerating halogen-free epoxy development for PCB lamination applications.
- Semiconductor packaging:Advanced packaging architectures are expanding underfill adhesive consumption for die-stacking operations.
- China PCB fabrication:Concentrated circuit board production in Guangdong and Jiangsu provinces sustains volume demand for solder mask and lamination adhesives.
Market Restraints
- Silver price volatility:Conductive adhesive formulations face input cost instability from precious metal feedstock fluctuations.
- Organosilicon supply concentration:Asia-Pacific captive production of silicone resins creates geographic dependency for thermal interface materials.
- UV-cure depth limitations:Acrylic formulations face technical constraints for shadowed component bonding in complex assemblies.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device production are opening adhesive procurement channels.
- Automotive sensor modules:Temperature-restricted LiDAR and camera assemblies are creating specification demand for low-stress conductive epoxies.
- EU Green Deal alignment:Bio-based feedstock mandates are creating premium positioning for renewable-content adhesive lines.
Industry Challenges
- Dual compliance timelines:Manufacturers must synchronize ECHA restriction proposals with FDA indirect food-contact clearances for wearable devices.
- Formulation-to-dispensing integration:Miniaturized device geometries require adhesive rheology optimization for jetting equipment compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronics Adhesives Market |
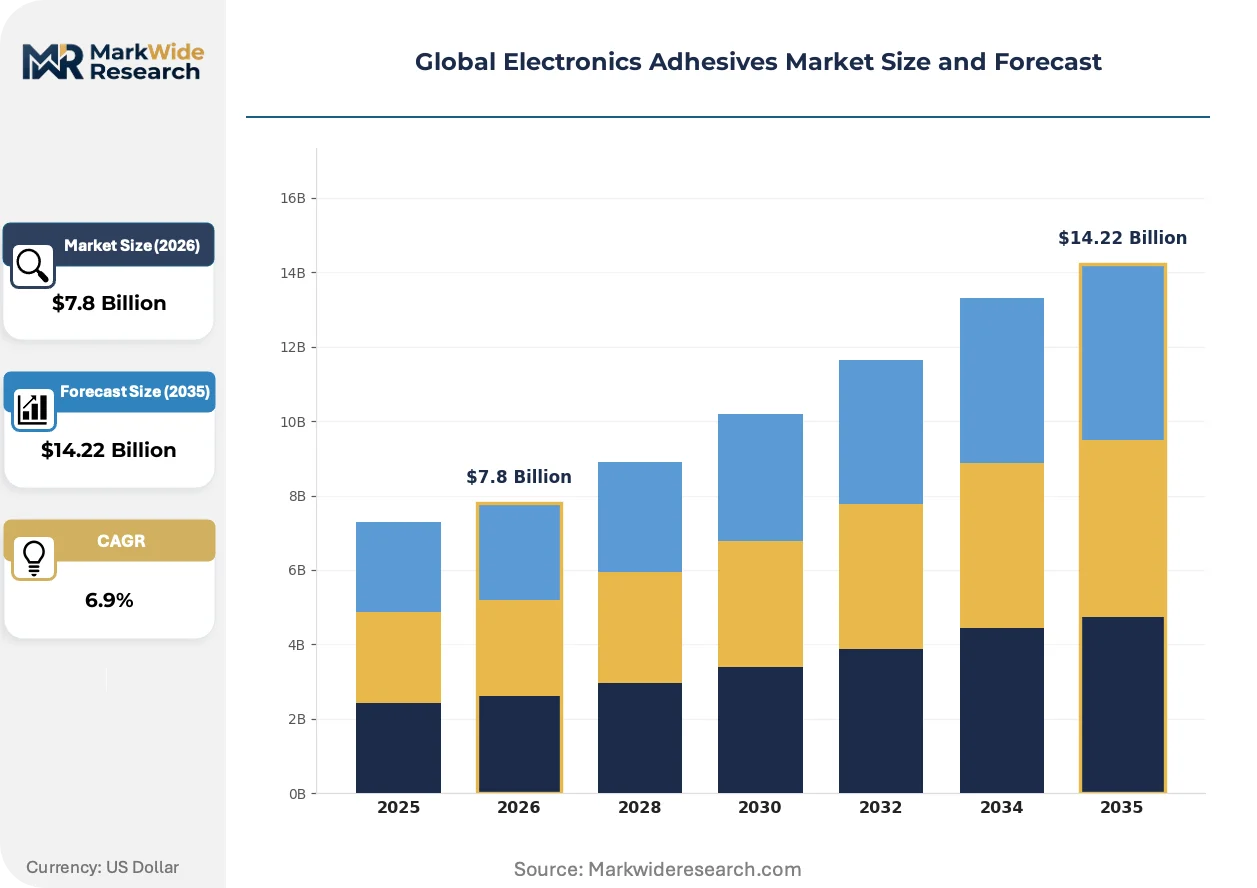
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $14.22 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Silicone, Polyurethane, UV Cure, Hot Melt Technology: Thermoplastic, Thermosetting, Anaerobic, Conductive, Non-Conductive Application: Printed Circuit Boards, Semiconductor Packaging, Display Assembly, LED Bonding, Sensor Modules End User: Consumer Electronics Manufacturers, Telecommunications Firms, Defense Contractors, Automotive Tier-1 Suppliers |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dow Inc., Sika AG, Arkema S.A., BASF SE, Shin-Etsu Chemical, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronics Adhesives Market Shifts & Advancements
Reformulation priorities are converging around thermal conductivity enhancement, regulatory substance elimination, and process speed acceleration across display and semiconductor assembly lines.
Silver-sintered pastes are absorbing functional roles previously served by solder interconnects in power module attachment. Automotive inverter manufacturers in Germany and Japan are adopting these materials for die-attach operations requiring operation above 175°C. The technology is absorbing market share from traditional conductive epoxies in high-reliability segments where thermal cycling resistance determines component lifetime.
ECHA restriction proposals targeting bisphenol derivatives are forcing systematic substance reviews across imported adhesive portfolios. Formulators serving European medical and wearable device markets must demonstrate compliance with both SVHC thresholds and indirect food-contact migration limits. Dual-regulatory burden is compressing reformulation timelines for suppliers without dedicated European regulatory affairs capacity.
Contract electronics manufacturers are consolidating adhesive procurement through qualified supplier lists tied to specific assembly platforms. Tier-one EMS providers in Taiwan and Mexico are reducing approved vendor counts from twelve to four for commodity epoxy grades. Consolidation is concentrating volume with formulation houses capable of multi-site technical support and regional inventory positioning.
Global Electronics Adhesives Market Segmentation
Electronics adhesives segment along four intersecting axes that determine specification requirements, regulatory exposure, and procurement economics. Product chemistry dictates thermal and electrical performance ceilings. Application geometry determines dispensing method and cure protocol. End-user industry sets reliability standards and compliance frameworks.
Product Type:
Thermal management specifications and cure chemistry separate commodity formulations from performance grades.
- Epoxy:Two-part and single-part formulations dominate semiconductor underfill and PCB lamination due to dielectric strength above 15 kV/mm and glass transition temperatures reaching 180°C. Guangdong province PCB fabricators consume the largest volumes, though REACH SVHC restrictions on bisphenol derivatives are compressing reformulation timelines for European-bound shipments.
- Silicone:Thermal interface materials and conformal coatings leverage organosilicon backbone flexibility across temperature swings from -55°C to 200°C. Shin-Etsu Chemical's captive feedstock production in Japan and Thailand creates geographic concentration for high-purity resin supply, exposing purchasers to Asia-Pacific logistics constraints.
- Acrylic:UV-cure grades enable display assembly throughput exceeding 500 units per hour.
- Polyurethane:Flexible encapsulants protect cable assemblies and connectors from moisture ingress.
- UV Cure:Rapid polymerization suits automated dispensing in high-volume consumer electronics lines.
- Hot Melt:Thermoplastic formulations serve temporary fixturing and rework applications.
Epoxy leads on scale; UV-cure acrylics lead on momentum.
Technology:
Cure mechanism and electrical function determine equipment compatibility and end-use eligibility.
- Thermosetting:Cross-linked polymer networks deliver permanent bonds for structural component attachment. Automotive Tier-1 suppliers in Germany specify these grades for power module die-attach where thermal cycling resistance exceeds 1,000 cycles.
- Conductive:Silver-filled epoxies displace solder in temperature-restricted sensor assemblies. Price volatility in precious metal feedstock creates margin pressure for LiDAR module manufacturers.
- Thermoplastic:Reversible softening enables rework and repair in high-value assemblies.
- Anaerobic:Cure-in-place formulations secure threaded fasteners and cylindrical joints.
- Non-Conductive:Dielectric grades isolate live traces in dense PCB layouts.
Thermosetting chemistry anchors volume demand; conductive technology commands the steepest expansion trajectory.
Application:
Assembly geometry and component density drive specification differentiation across device categories.
- Printed Circuit Boards:Solder mask, lamination, and component attach adhesives must survive multiple thermal excursions during assembly. Jiangsu province concentration of high-layer-count board production sustains specialized epoxy procurement.
- Semiconductor Packaging:Underfill and die-attach materials for 2.5D and 3D stacking architectures require filler loading above 70% by weight for coefficient of thermal expansion matching. Advanced packaging investments in Taiwan and South Korea are expanding specification demand for low-stress formulations.
- Display Assembly:UV-cure acrylics bond cover glass to LCD and OLED panels.
- LED Bonding:Thermally conductive grades attach chips to substrates in lighting modules.
- Sensor Modules:Miniaturized camera and environmental sensors require precision dispensing below 25-micron bond lines.
PCB applications lead on scale; semiconductor packaging leads on momentum.
End User:
Reliability requirements and regulatory exposure fragment procurement behavior across customer categories.
- Consumer Electronics Manufacturers:Smartphone and wearable device assemblers prioritize throughput and miniaturization compatibility. Original design manufacturers in Taiwan and Mexico are consolidating qualified supplier lists from twelve vendors to four for commodity epoxy grades.
- Automotive Tier-1 Suppliers:Inverter and sensor module manufacturers specify conductive adhesives for operation above 175°C. German and Japanese automotive electronics producers are adopting silver-sintered pastes for die-attach in power modules.
- Telecommunications Firms:Base station and network equipment builders demand long-term reliability under thermal cycling.
- Defense Contractors:MIL-SPEC qualification requirements extend procurement cycles and limit qualified vendor pools.
Consumer electronics manufacturers lead on scale; automotive Tier-1 suppliers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest adhesive procurement volumes for electronics assembly, while Germany sets the regulatory pace for halogen-free formulation standards across European supply chains.
China
Guangdong and Jiangsu provinces host the densest concentrations of PCB fabrication and semiconductor packaging operations worldwide. The country's dual carbon goals from MEE are accelerating solvent-free adhesive adoption in high-volume assembly lines. Shenzhen and Dongguan clusters drive specification demand for miniaturized component bonding in smartphone and wearable device production.
Germany
Automotive inverter manufacturers specify thermally conductive grades for power module die-attach exceeding 175°C operation. REACH SVHC restrictions from ECHA are compressing reformulation timelines for bisphenol-based epoxy imports. Bavaria-based Tier-1 suppliers are adopting silver-sintered pastes for thermal cycling resistance above 1,000 cycles in electric vehicle electronics.
United States
EPA toxicity evaluations are forcing systematic substance reviews across imported adhesive portfolios for consumer electronics assembly. FDA indirect food-contact clearances intersect with state-level disclosure mandates to create compliance burdens for wearable device manufacturers. Texas and California fabrication clusters are consolidating qualified supplier lists for commodity epoxy grades.
Japan
METI industrial standards shape reliability specifications for automotive and telecommunications equipment adhesives. Shin-Etsu's captive organosilicon production in Nagoya and Kyushu creates geographic concentration for high-purity silicone resin supply. Kanto region electronics assemblers are expanding procurement for advanced packaging underfill materials in 2.5D and 3D stacking architectures.
South Korea
Advanced packaging investments from Samsung and SK Hynix are expanding specification demand for low-stress conductive formulations. MFDS medical device regulations extend qualification timelines for adhesives in health-monitoring wearables. Seoul Capital Area and Busan-Ulsan clusters concentrate die-attach and underfill consumption for memory and logic semiconductor production.
Global Electronics Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated market structure where scale advantages clash with technical depth. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive resin production, adhesive specialists with regional formulation heritage, and materials science divisions of electronics manufacturing service providers. Consolidation pressures are concentrating volume with suppliers capable of multi-site technical support, while geographic expansion and portfolio diversification represent the dominant competitive moves for mid-scale players seeking procurement relationships with tier-one EMS providers.
Among European heritage formulation houses, Henkel AG & Co. KGaA exemplifies the integrated specialist archetype with sustained positioning in thermally conductive grades, while Sika AG represents the construction-to-electronics diversification path. Dow Inc. anchors North American supply capabilities through in-house silicone resin production. These three entities collectively illustrate how geographic feedstock control and regulatory affairs capacity determine competitive position in a market where dual compliance timelines for REACH and FDA requirements are compressing reformulation windows.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Dow Inc. |
| Sika AG |
| Arkema S.A. |
| BASF SE |
| Shin-Etsu Chemical |
| Evonik Industries |
| Others |
Supply & Pricing Matrix
Tier-one EMS providers in Taiwan and Mexico operate on contract-based long-term offtake agreements that anchor pricing discipline across commodity epoxy grades. Procurement consolidation from twelve approved vendors to four has compressed margin buffers for formulation houses without multi-site technical support capabilities.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for advanced packaging underfill materials. Three-tier pricing structure across premium thermally conductive grades, standard lamination epoxies, and economy temporary fixturing adhesives stratifies by thermal conductivity threshold and REACH compliance certification. Cost compression in silver-filled conductive formulations is intensifying because precious metal feedstock volatility transfers directly to bill-of-materials. Smartphone ODMs in Shenzhen exhibit highest price sensitivity for UV-cure acrylics, while German automotive Tier-1 suppliers accept premium positioning for silver-sintered die-attach pastes.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles coordinate hub-and-spoke patterns for just-in-time delivery to PCB fabrication clusters. Manufacturing concentrates in China, Japan, and Germany, with Guangdong and Jiangsu provinces hosting densest adhesive consumption for lamination and underfill operations. Feedstock supply draws from organosilicon captive production in Japan and Thailand, silver flake processing in South Korea, and bisphenol resin synthesis in Germany. Single-source vulnerability for high-purity silicone resins exposes purchasers to Asia-Pacific logistics constraints. Distribution runs through qualified supplier lists managed by contract electronics manufacturers with regional inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in electronics adhesives hinges on reformulation cost-down from bio-based feedstock substitution and premium-tier capture in automotive power module applications. Halogen-free chemistry transitions and silver-sintered paste adoption create dual pathways for pricing power.
For Market Incumbents: Lock in multi-year supply agreements with Guangdong and Jiangsu PCB fabricators before India PLI scheme incentives mature. Defend against silver-sintered paste displacement by accelerating thermally conductive epoxy development for 175°C operation. Vertical integration into organosilicon feedstock buffers Shin-Etsu-style geographic concentration risks. For New Entrants and Emerging Players: Launch via technical partnership with India-based semiconductor packaging startups qualifying for PLI scheme support. Automotive sensor module specifications for low-stress conductive epoxies present the most penetrable white-space. Target EU Green Deal alignment for bio-based adhesive lines with renewable-content certification. For Investors and Strategic Acquirers: Chemical conglomerates with captive resin production are the most active acquirer in this space, seeking formulation specialists with REACH regulatory affairs capacity. Five-to-ten-year viability favors targets with dual compliance infrastructure for ECHA restrictions and FDA indirect food-contact clearances. Watch for ECHA bisphenol derivative restriction finalization as inflection indicator for reformulation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Feedstock | Shin-Etsu's captive Nagoya production demonstrates margin protection against logistics disruption. |
| REACH Compliance Certification Investment | Henkel's European heritage formulation capacity secures premium positioning in German automotive supply chains. |
| Silver-Sintered Paste Capacity Expansion | German and Japanese inverter manufacturers absorb functional roles from solder interconnects above 175°C. |
| India PLI Scheme Geographic Expansion | Samsung and SK Hynix advanced packaging investments open specification demand for low-stress underfill. |
| Bio-Based Feedstock Joint Venture | EU Green Deal mandates create premium positioning for renewable-content adhesive lines in medical wearables. |
Research Methodology
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region's dominant electronics manufacturing clusters. The research combines interviews with adhesive formulation R&D directors, procurement leads at Taiwan-based EMS providers, plant managers at Guangdong PCB fabricators, and regulatory affairs specialists navigating ECHA SVHC restrictions. Secondary validation draws from SEC 10-K filings of integrated chemical conglomerates, ECHA restriction proposal documentation, customs trade data for organosilicon resin imports, and MFDS medical device adhesive qualification records. Bottom-up volume modeling triangulates against top-down value estimates derived from qualified supplier list consolidation trends.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. Segmentation dimensions include product chemistry, cure technology, application geometry, and end-user industry reliability tier, with additional modeling for regulatory compliance status. CAGRs derive from trend extrapolation of miniaturization-driven bond-line compression and advanced packaging architecture adoption. Industry-specific inputs capture silver price volatility impact on conductive adhesive margins and UV-cure equipment penetration in display assembly lines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA bisphenol restriction acceleration or organosilicon supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Europe Epoxy Adhesive Market