
 Europe Waterborne Adhesives Market | 2026-2036
Europe Waterborne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Waterborne Adhesives Market Foresight
Asset-light toll manufacturing partnerships is rewriting competitive entry dynamics for mid-size adhesive compounders. Henkel AG & Co. KGaA leverages its European formulation network to sustain technical service density without captive resin plants. BASF SE anchors polyurethane dispersion supply through backward integration into polyol production. Sika AG competes via construction-specialized application know-how rather than broad portfolio breadth.
Europe waterborne adhesives are aqueous polymer dispersions—primarily acrylic, polyurethane, polyvinyl acetate, and silicone latexes—where active polymer content ranges from 40% to 60% by weight and drying occurs through water evaporation at ambient or slightly elevated temperatures. These systems bond porous and non-porous substrates in packaging lines, automotive interior assembly, and furniture lamination while eliminating volatile organic solvent emissions. Acrylic formulations lead volume across flexible packaging sealing applications due to their clarity, aging stability, and food-contact compliance under EU framework regulation. Polyurethane dispersions represent the fastest-expanding product category as automotive OEMs specify them for dashboard and trim bonding to meet interior air quality protocols. Construction bonding applications remain margin-diluted given project-based procurement and price sensitivity among regional contractors.
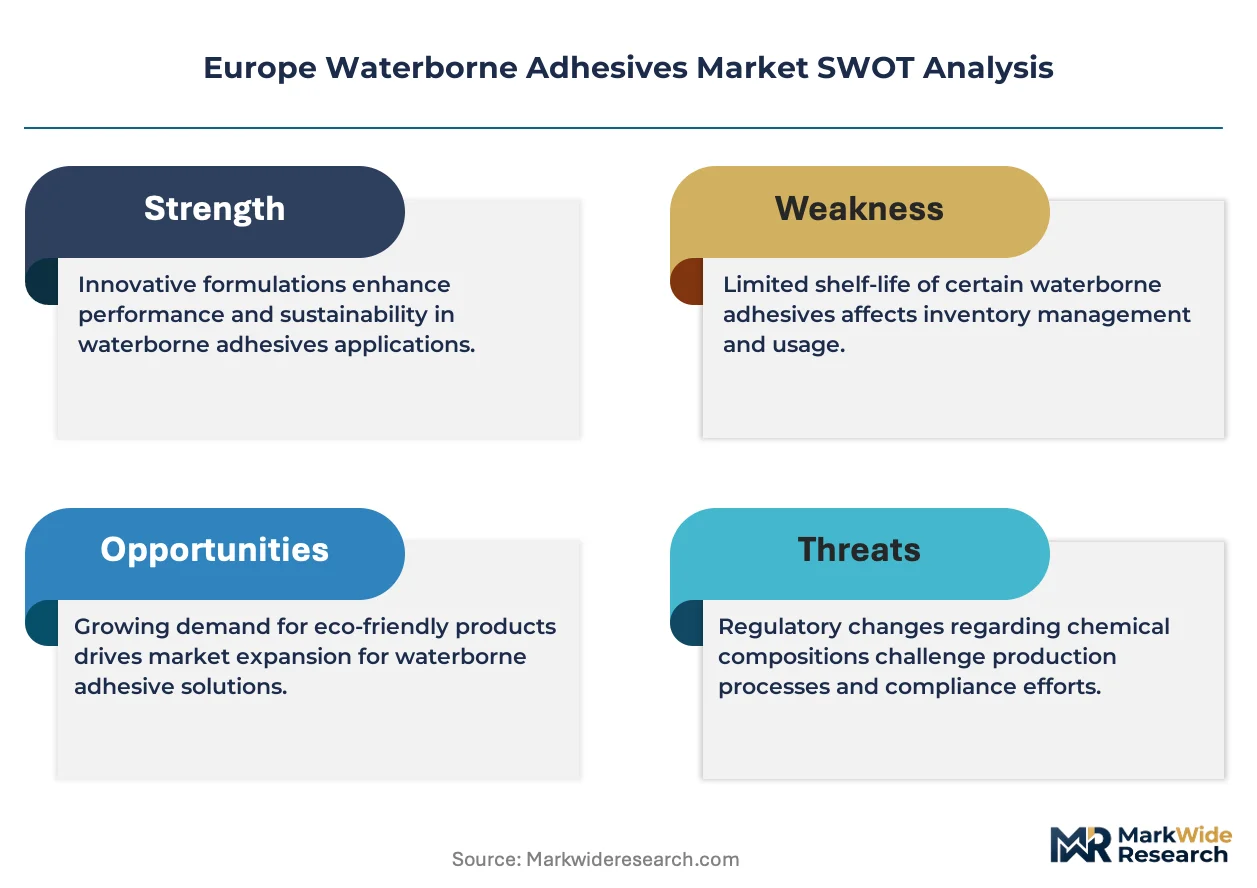
REACH and the EU Green Deal constrain residual monomer levels and mandate biodegradability disclosures for adhesive components placed on the European market. ECHA substance evaluation drives reformulation cycles as candidate list entries expand, while CE marking requirements for construction products tie adhesive performance to structural safety declarations. Germany's Federal Environment Agency enforces TA Luft emission controls that penalize solvent-based coating and bonding operations in industrial zones. Stakeholders must monitor upcoming PFAS restrictions under REACH that could eliminate certain fluorinated wetting agents from waterborne formulations.
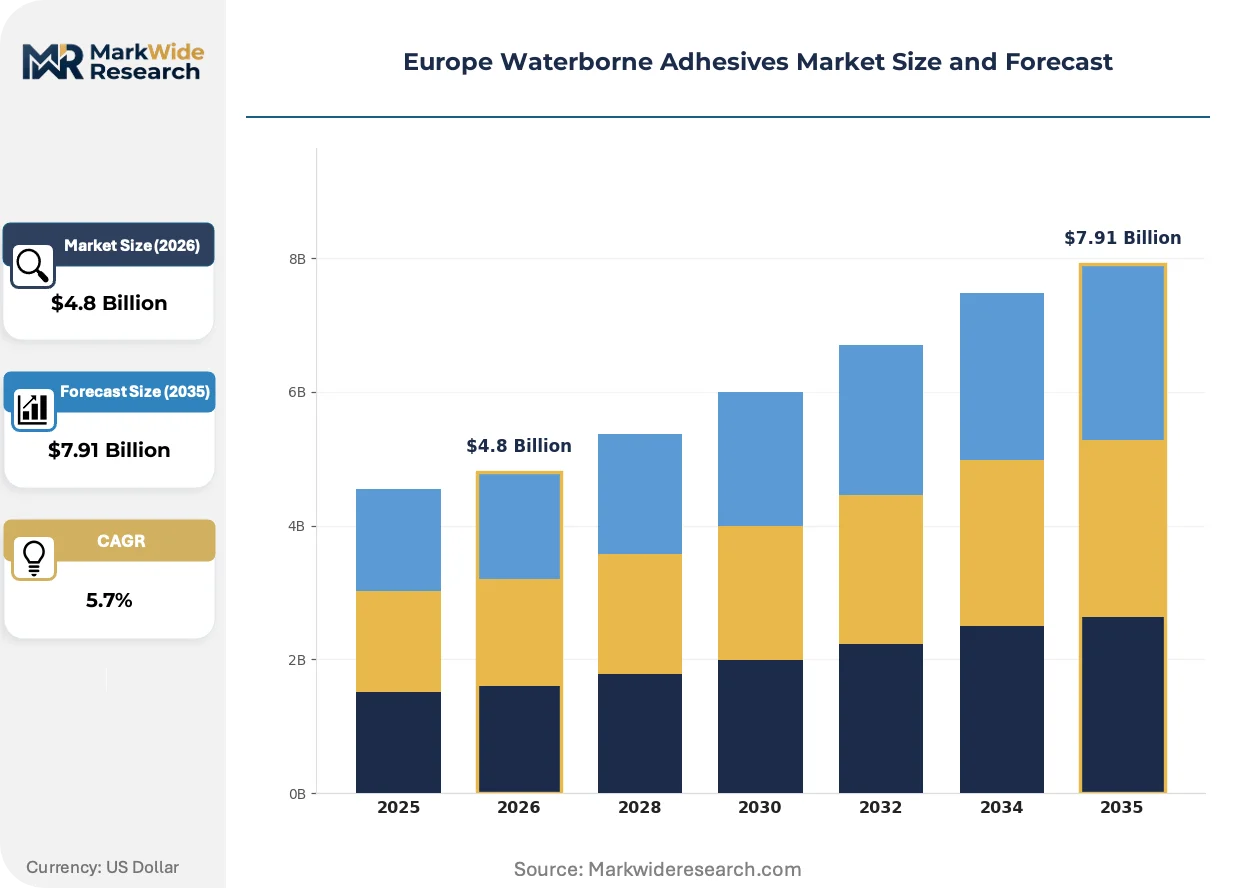
Market Dynamics
REACH compliance deadlines and the EU Green Deal's VOC emission thresholds are forcing solvent-to-waterborne conversion across European adhesive capacity, while packaging converters in Germany's industrial corridor accelerate procurement of aqueous polymer systems for flexible food sealing lines.
Growth Catalysts
- EU Green Deal emission mandates:Binding VOC reduction targets under the European Climate Law redirect solvent-based coating capacity toward waterborne polyurethane and acrylic dispersion systems in automotive and packaging plants.
- Flexible packaging sealing demand:Food-contact compliance under EU framework regulation 1935/2004 drives specification of waterborne acrylics for high-clarity laminate bonds in German and French converter facilities.
- Polyurethane dispersion chemistry advances:Improved hydrolytic stability and heat resistance in PUD formulations enable dashboard and interior trim bonding that meets OEM interior air quality protocols without solvent carriers.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and polyol prices fluctuate with naphtha and propylene markets, compressing formulation margins for dispersion producers without backward integration into resin supply.
- Cold-weather performance limitations:Waterborne systems require ambient temperatures above 15°C for proper film formation, restricting year-round construction adhesive applications in Nordic climates without heated application environments.
- Longer drying cycle requirements:Evaporative curing demands extended line times compared to reactive solvent or hot-melt systems, creating throughput penalties in high-speed packaging operations.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Automotive tier suppliers in Central European industrial zones present untapped demand for PUD-based interior bonding as OEMs regionalize supply chains away from Western European concentration.
- PFAS-free wetting agent development:Upcoming REACH restrictions on fluorinated compounds create first-mover advantage for compounders deploying silicone or bio-based surfactant alternatives in waterborne formulations.
- Construction product CE marking integration:Adhesive performance declarations tied to structural safety standards under EN 15416 enable premium positioning in engineered wood lamination and flooring installation systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and rheology modification for aqueous polymer systems concentrates among aging technical staff in established German and Swiss compounders.
- Multi-standard certification timelines:Simultaneous pursuit of food-contact approval under EFSA guidance, CE marking for construction applications, and automotive OEM specifications extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Waterborne Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, PVA, Silicone End User: Automotive, Packaging, Construction, Furniture Application: Coating, Sealing, Bonding, Assembly Packaging Type: Drum, Pail, Bottle, Bulk |
| Companies Covered | 3M, Arkema Group, Dow, Henkel AG & Co. KGaA, Sika AG, Ashland, BASF SE, Evonik Industries, H.B. Fuller, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Waterborne Adhesives Market Shifts & Advancements
Waterborne adhesive technology is pivoting toward high-performance polyurethane dispersions and bio-based acrylic systems, while regulatory pressure on residual monomers and fluorinated additives accelerates reformulation cycles across European supply chains.
Hybrid polyurethane-acrylic copolymer dispersions combine the toughness of urethane segments with acrylic cost structures, enabling single-component systems that bond engineered plastics and coated metals without primer layers. Automotive interior suppliers in Stuttgart and Munich are qualifying these materials for dashboard assembly. This convergence is rendering obsolete two-part solvent-borne polyurethane adhesives in premium vehicle trim applications.
REACH candidate list expansion for substances of very high concern is tightening residual monomer thresholds in acrylic dispersions, forcing compounders to invest in devolatilization equipment and alternative initiator chemistries. ECHA substance evaluation drives 12-18 month reformulation timelines for products containing styrene or formaldehyde-releasing crosslinkers. Construction adhesive portfolios face the steepest compliance burden as CE marking ties adhesive performance to structural safety declarations under EN 15416.
Specification authority is migrating from procurement departments to sustainability and EHS functions as large packaging converters embed carbon accounting into supplier scorecards. Unilever and Nestlé's European operations now require waterborne adhesive suppliers to submit cradle-to-gate LCA data and biodegradability disclosures under EU Single-Use Plastics Directive adjacent requirements. This shift is most visible in the Rhine-Ruhr packaging cluster, where converters have consolidated supplier panels to three qualified compounders per adhesive category.
Europe Waterborne Adhesives Market Segmentation
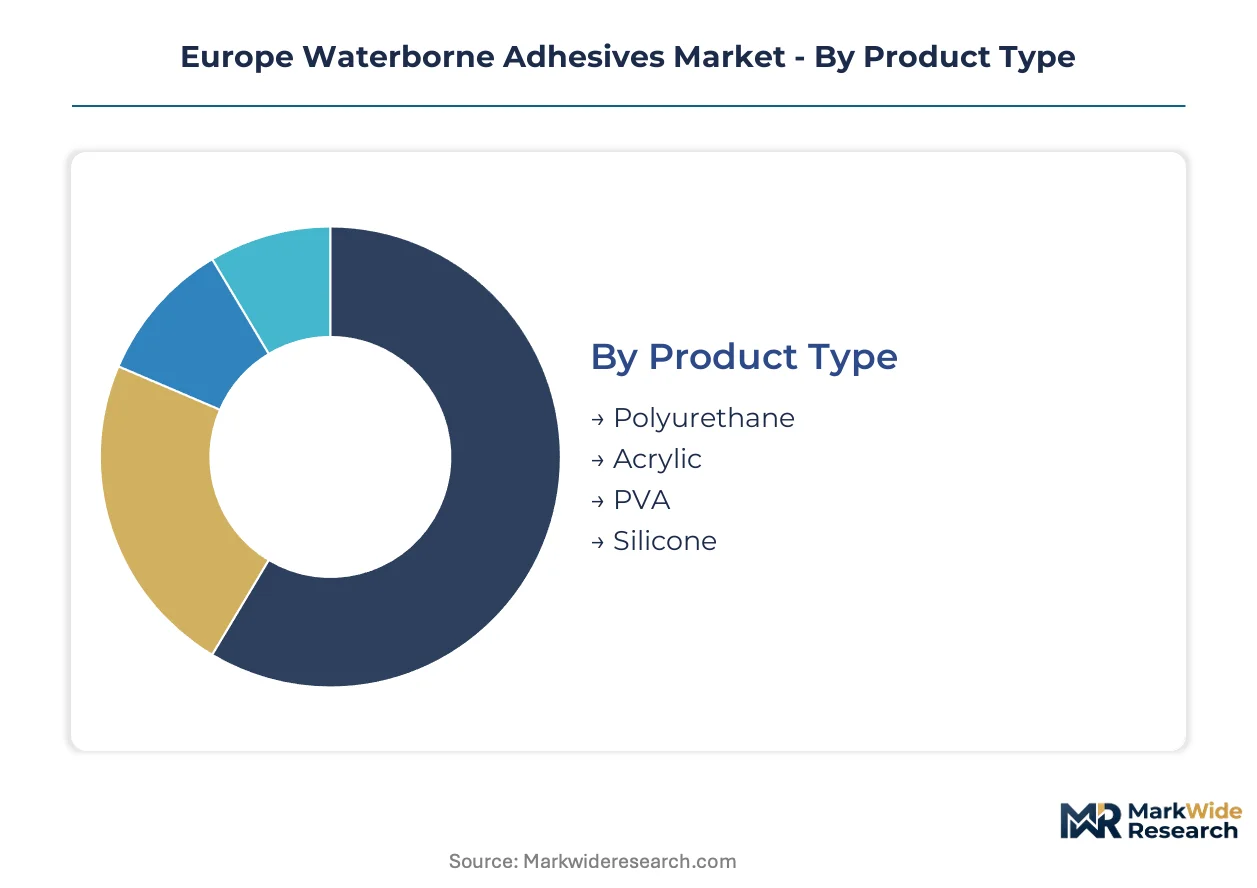
Waterborne adhesive procurement patterns diverge sharply across product chemistries and end-use specifications, with formulation complexity and regulatory compliance requirements driving distinct service intensity profiles. Technical support demands concentrate around polyurethane dispersions for automotive interior bonding and acrylic systems for food-contact packaging applications.
Product Type:
After-sales service intensity peaks with polyurethane dispersion customers requiring application engineering support for dashboard and trim bonding protocols.
- Polyurethane:These aqueous polymer dispersions deliver hydrolytic stability and heat resistance for automotive interior assembly. Dashboard bonding specifications from Stuttgart and Munich OEMs drive procurement concentration in Germany's automotive corridor, with technical service teams embedding at tier supplier facilities to qualify film formation parameters.
- Acrylic:Waterborne acrylic emulsions provide clarity and aging stability for flexible food packaging seals. Demand concentrates in the Rhine-Ruhr packaging cluster where converters specify high-clarity laminate bonds under EU framework regulation compliance protocols.
- PVA:Polyvinyl acetate homopolymers serve furniture lamination and woodworking applications with cost-efficient bonding of porous substrates.
- Silicone:Silicone latex systems address specialized construction sealing with moisture-cure characteristics for exterior glazing and facade applications.
By volume, Acrylic leads. By growth pace, Polyurethane is ahead.
End User:
Customer procurement sophistication varies by end-use maturity, with automotive OEMs imposing the most stringent qualification protocols.
- Automotive:Interior air quality mandates from German OEMs specify waterborne polyurethane dispersions for dashboard and trim assembly. Tier suppliers in Stuttgart, Munich, and emerging Central European zones require 18-24 month qualification cycles with embedded technical service support.
- Packaging:Flexible food sealing lines across Germany and France drive acrylic dispersion procurement for high-clarity laminate bonds. Unilever and Nestlé operations now require cradle-to-gate LCA submissions alongside adhesive performance data.
- Construction:Project-based procurement and price sensitivity among regional contractors compress margins for flooring installation and engineered wood lamination adhesives.
- Furniture:Woodworking assembly applications favor PVA systems for cost-efficient bonding of particleboard and veneer substrates in regional manufacturing clusters.
Packaging generates the highest volume pull. Automotive commands the steepest expansion trajectory.
Application:
Process integration requirements differentiate application segments, with coating operations demanding rheology modification expertise.
- Coating:Waterborne adhesive coatings for protective and functional layers require precise viscosity control and film weight uniformity. Technical service intensity concentrates at automotive tier suppliers qualifying dashboard coating lines.
- Sealing:Flexible packaging sealing applications prioritize food-contact compliance and clarity performance under EU framework regulation. Acrylic dispersions dominate high-speed laminate bonding in German converter facilities.
- Bonding:Structural adhesive bonding for construction and furniture applications ties to CE marking requirements under EN 15416 performance declarations.
- Assembly:Interior trim assembly in automotive plants specifies polyurethane dispersions for heat-resistant dashboard component attachment.
Sealing captures the largest volume share. Coating is climbing the fastest.
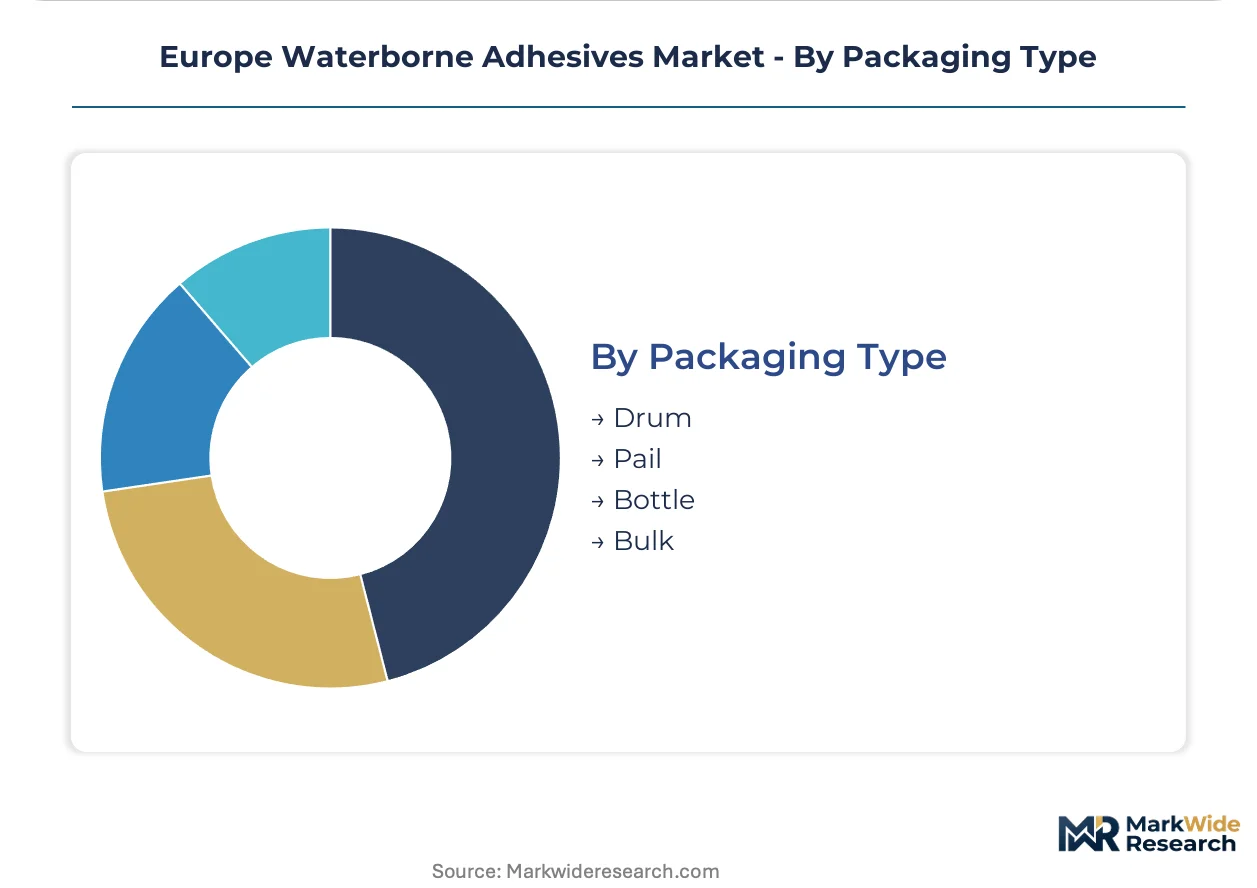
Packaging Type:
Logistics economics and consumption scale determine packaging configuration preferences across customer segments.
- Drum:Standard 200-liter steel drums serve mid-volume automotive tier suppliers and packaging converters with predictable consumption rates and established handling infrastructure.
- Pail:Smaller plastic pails address specialty formulation requirements and construction contractor job-site portability needs.
- Bottle:Laboratory and pilot-scale quantities in bottle packaging support qualification trials and R&D sampling for new adhesive specifications.
- Bulk:Tanker and tote deliveries for high-volume packaging converters in the Rhine-Ruhr cluster minimize packaging waste and enable direct line-feed integration.
Drum shipments dominate current volume. Bulk delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe maintains a modest net export position in waterborne adhesives, with German and French formulation capacity serving converter demand across Central and Eastern European markets while importing specialized polyurethane dispersions from Swiss and Belgian resin suppliers.
Germany
Automotive interior bonding specifications from Stuttgart and Munich OEMs drive polyurethane dispersion procurement, with TA Luft emission controls under the Federal Environment Agency penalizing solvent-based operations in the Cologne-Frankfurt industrial corridor. Packaging converters in the Rhine-Ruhr cluster consolidate supplier panels to three qualified compounders per adhesive category.
France
Flexible food packaging lines in the Île-de-France and Hauts-de-France regions accelerate waterborne acrylic procurement for high-clarity laminate bonds compliant with EU framework regulation 1935/2004. ANSM oversight of food-contact materials reinforces EFSA guidance on residual monomer thresholds. The Lyon packaging hub demands cradle-to-gate LCA submissions from adhesive suppliers.
Poland
Automotive tier suppliers in the Silesian and Greater Poland voivodeships present untapped demand for PUD-based interior bonding as OEMs regionalize supply chains away from Western European concentration. Polish national environmental regulations align with REACH compliance timelines. Warsaw-based converters are qualifying waterborne systems for flexible packaging export to German retail channels.
Italy
Furniture lamination clusters in Lombardy and Veneto favor PVA systems for cost-efficient bonding of particleboard and veneer substrates, though margin compression limits formulation investment. Italian Ministry of Environment decrees implement EU Green Deal VOC thresholds for woodworking operations. The Brianza furniture district maintains dual sourcing from domestic compounders and German suppliers.
Netherlands
Rotterdam chemical logistics infrastructure supports distribution of acrylic and polyurethane dispersions to Benelux packaging converters, with port-based toll manufacturing partnerships reducing working capital requirements for mid-size compounders. Dutch environmental permitting under the Activities Decree enforces REACH-aligned emission controls. The Eindhoven region's high-tech packaging equipment sector drives specification of low-VOC adhesive systems.
Europe Waterborne Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive resin production or formulation expertise. The European waterborne adhesives sector exhibits tiered concentration, with diversified chemical conglomerates anchoring polyurethane dispersion supply through backward integration into polyol production while mid-size compounders compete via asset-light toll manufacturing partnerships. Three archetypes dominate: integrated resin-to-formulation operators, construction-specialized application experts, and packaging-focused technical service providers. Competitive moves center on M&A consolidation of regional formulation assets and strategic partnerships with automotive tier suppliers for embedded technical support.
Within the integrated chemical tier, BASF SE anchors polyurethane dispersion supply through captive polyol production, while Henkel AG & Co. KGaA exemplifies the asset-light formulation model leveraging European technical service density without captive resin plants. Sika AG occupies a position as the construction-specialized archetype, competing via application know-how rather than broad portfolio breadth.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| Ashland |
| BASF SE |
| Evonik Industries |
| H.B. Fuller |
| Others |
Supply & Pricing Matrix
Overcapacity in Western European acrylic dispersion plants is compressing spot pricing for standard-grade formulations while forcing suppliers toward long-term offtake contracts with automotive OEMs to lock in utilization. This utilization-driven pricing posture redirects margin pressure toward mid-size compounders without backward integration into polyol or monomer supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for waterborne polyurethane dispersions used in dashboard assembly, with three-tier pricing structure across premium, standard, and economy levels differentiated by certification grade and volume scale. Pricing pressure stems from petrochemical feedstock volatility in naphtha and propylene markets, compressing margins for non-integrated formulators. Packaging converters exhibit highest price sensitivity due to project-based procurement cycles, while automotive tier suppliers accept premium positioning for REACH-compliant food-contact grades.
Supply Chain Analysis
Upstream acrylic monomer production concentrates in Germany, Belgium, and the Netherlands, with polyurethane dispersion feedstocks drawing from captive polyol operations at integrated chemical sites. Raw material dependencies center on propylene derivatives, ethylene oxide, and specialty isocyanates for high-performance grades. Single-source vulnerability persists for automotive-qualified PUD resins qualified through 18-24 month OEM protocols. Distribution runs through Rotterdam port logistics and Rhine-Ruhr chemical corridors to converter facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as automotive OEMs consolidate adhesive supplier panels and mandate interoperability with carbon accounting systems, embedding formulation providers into sustainability data infrastructure.
For Market Incumbents: Insulate margin position through captive polyol production or toll manufacturing partnerships that sustain technical service density without asset-heavy resin plants. Prioritize REACH pre-registration for PFAS-free wetting agent alternatives ahead of candidate list expansion. Defend against mid-size compounders by embedding application engineers at Stuttgart and Munich tier supplier facilities. For New Entrants and Emerging Players: Establish a beachhead in Poland's Silesian automotive corridor where PUD demand outpaces qualified supplier presence. Target construction adhesive segments in Nordic markets where cold-weather performance limitations have suppressed incumbent penetration. Lead with bio-based acrylic systems that satisfy Unilever and Nestlé cradle-to-gate LCA requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light toll manufacturing partnerships, favoring acquisition of formulation specialists with embedded technical service relationships over integrated resin producers. Target compounders with CE marking expertise and automotive qualification track records. Monitor ECHA substance evaluation timelines as inflection indicators for reformulation-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | BASF SE anchors PUD supply through captive resin production, locking in margin control. |
| PFAS-Free Wetting Agent Development | First-mover deployment of silicone surfactants ahead of REACH restrictions captures specification authority. |
| Automotive Technical Service Embedding | Henkel AG & Co. KGaA sustains OEM relationships through on-site application engineering at tier suppliers. |
| CE Marking Integration for Construction | EN 15416 performance declarations enable premium positioning in engineered wood lamination systems. |
| Central European Manufacturing Expansion | Polish and Czech automotive corridors present untapped demand as OEMs regionalize supply chains. |
Research Methodology
Desk research of ECHA substance evaluation databases, Cefic chemical industry reports, and EU customs trade data preceded structured interviews with adhesive formulation R&D directors, automotive tier supplier procurement leads, packaging converter technical managers, and toll manufacturing facility operators. Primary fieldwork combined with secondary validation across REACH compliance documentation and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Assumptions held REACH compliance timelines and EU Green Deal VOC thresholds fixed across the analysis window, while petrochemical feedstock pricing and automotive production volumes varied stochastically. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, packaging format configuration, and regional production hub concentration. CAGRs derived from logistic growth curve fitting to historical shipment data, with automotive interior air quality mandates and flexible packaging converter consolidation as industry-specific demand drivers.
Sensitivities concentrate around ECHA candidate list expansion for residual monomers, PFAS restriction implementation timing, and Nordic climate impacts on construction adhesive seasonality. Cross-checking against Cefic adhesive sector production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Solvent-Borne Adhesives Market