
 Elastomeric Adhesive Market | 2026-2036
Elastomeric Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Adhesive Market Intelligence
The shift towards asset-light manufacturing models, where specialized compounding is outsourced to third parties, is fragmenting the competitive landscape. Henkel AG leverages its extensive global distribution network to serve a wide array of end-users. Sika AG specializes in high-performance formulations for demanding construction and infrastructure projects. Dow differentiates through its deep expertise in upstream polymer science and raw material control.
Elastomeric adhesives are polymer-based bonding agents engineered for significant elongation and flexibility after curing. These materials, often based on silicone, polyurethane, or acrylic chemistry, maintain bond integrity under constant vibration, impact, and thermal cycling. Polyurethane and silicone-based products command a significant share due to their performance versatility. The automotive industry represents the fastest-growing end-user segment, driven by the need to bond dissimilar lightweight materials like composites and aluminum.
Regulations like the European Union's REACH framework and US EPA rules on volatile organic compounds (VOCs) directly steer development towards water-based and hot-melt technologies. China's mandatory GB standards also influence formulation requirements for market access, creating regional product variations. Formulators must therefore decide whether to invest heavily in compliant, solvent-free technology R&D or risk ceding share in key regulated markets.
Market Dynamics
The imperative to reduce volatile organic compounds (VOCs) is the central force shaping the elastomeric adhesive market. Regulatory frameworks like the European Union's REACH and US EPA rules are compelling a fundamental R&D pivot towards solvent-free technologies.
Growth Catalysts
- Automotive Lightweighting:Demand from automotive OEMs for bonding dissimilar materials, such as aluminum to carbon fiber composites, accelerates adoption. These adhesives are critical for reducing vehicle weight and improving fuel efficiency without compromising structural integrity or noise, vibration, and harshness (NVH) performance.
- Advanced Construction:The construction industry's use of elastomeric sealants and adhesives in high-performance building envelopes and infrastructure projects is a significant catalyst. These materials accommodate thermal expansion and contraction in curtain walls, windows, and expansion joints, ensuring long-term durability.
- Regulatory Mandates:Government regulations targeting VOC emissions in consumer and industrial products directly stimulate innovation in water-based, hot-melt, and reactive polyurethane formulations. Compliance is a prerequisite for market access in key regions like Europe and North America.
Market Restraints
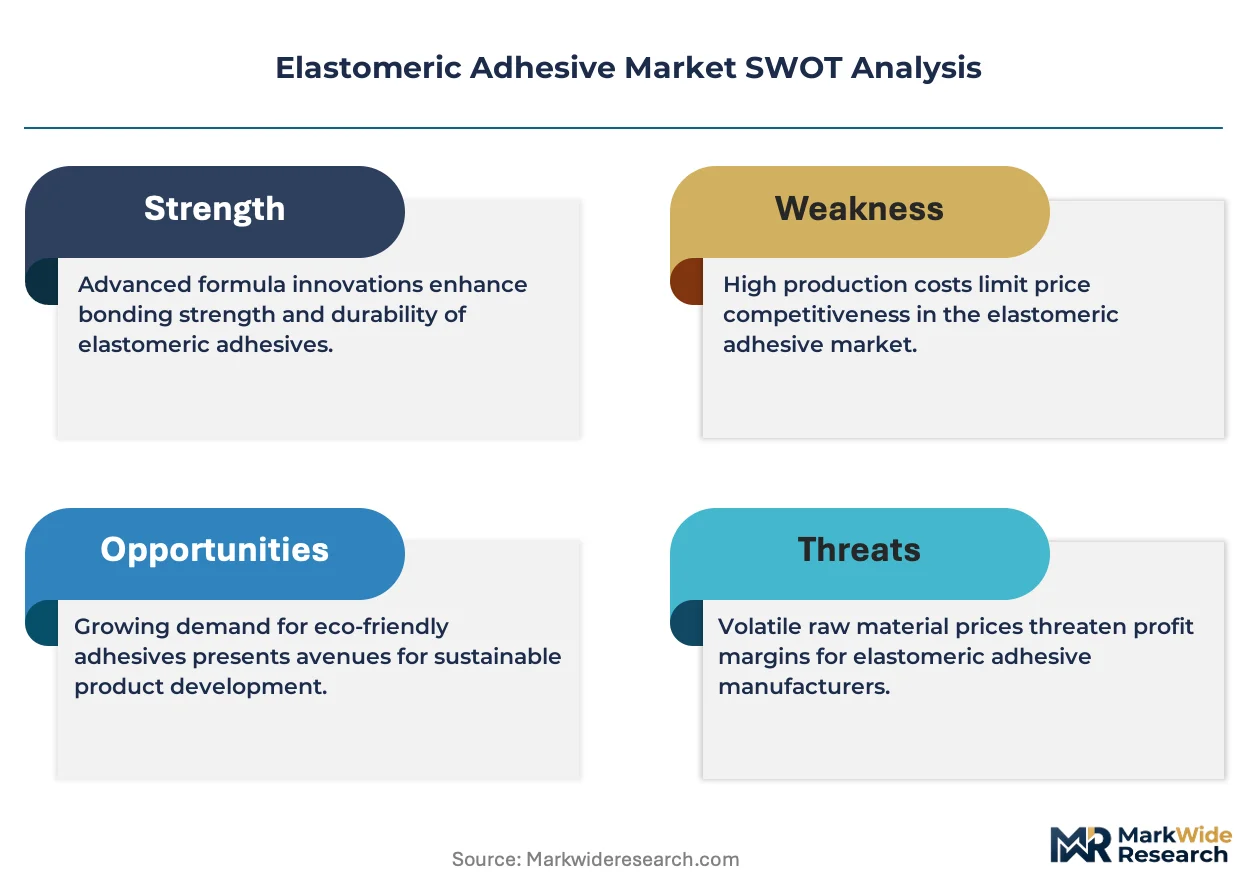
- Raw Material Volatility:The market is sensitive to price fluctuations and supply availability of key precursors like isocyanates, polyols, and siloxanes. These feedstocks are derived from petrochemicals, linking adhesive costs directly to global oil and gas market dynamics.
- Performance Trade-offs:Formulators face persistent technical challenges in balancing conflicting properties. For example, increasing elongation and flexibility can sometimes come at the expense of ultimate bond strength or chemical resistance, limiting use in certain demanding structural applications.
- Substitution by Mechanical Fasteners:In high-load-bearing structural applications, particularly in construction and heavy machinery, mechanical fasteners like bolts and rivets remain the preferred joining method. The perceived reliability and established engineering data for fasteners present a barrier to adhesive substitution.
Strategic Opportunities
- Flexible Electronics and Wearables:The emergence of flexible displays, wearable sensors, and smart textiles creates a new application frontier. Adhesives must provide durable, flexible bonds that can withstand repeated motion and protect sensitive electronic components, representing a high-value opportunity.
- Conductive Adhesive Formulations:Integrating conductive fillers like silver or carbon into elastomeric adhesive matrices opens opportunities in electronic assembly. These materials can provide both a structural bond and an electrical connection, simplifying designs for applications like RFID tags and printed circuit boards.
- Expansion in Southeast Asia:Rapid industrialization and infrastructure investment in countries across Southeast Asia present significant geographic expansion opportunities. Local manufacturing and construction sectors require advanced bonding solutions, creating demand in currently underpenetrated markets.
Industry Challenges
- Divergent Global Standards:Manufacturers must navigate a complex and fragmented regulatory landscape. Formulating a product that complies simultaneously with the EU's REACH, China's GB standards, and US EPA requirements is a significant technical and administrative burden, often requiring region-specific product lines.
- Application Engineering Skill Gaps:A shortage of polymer chemists and application engineers with expertise in advanced adhesive systems poses an operational challenge. This talent scarcity slows down new product development and limits the ability of suppliers to provide critical technical support to end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Adhesive Market |
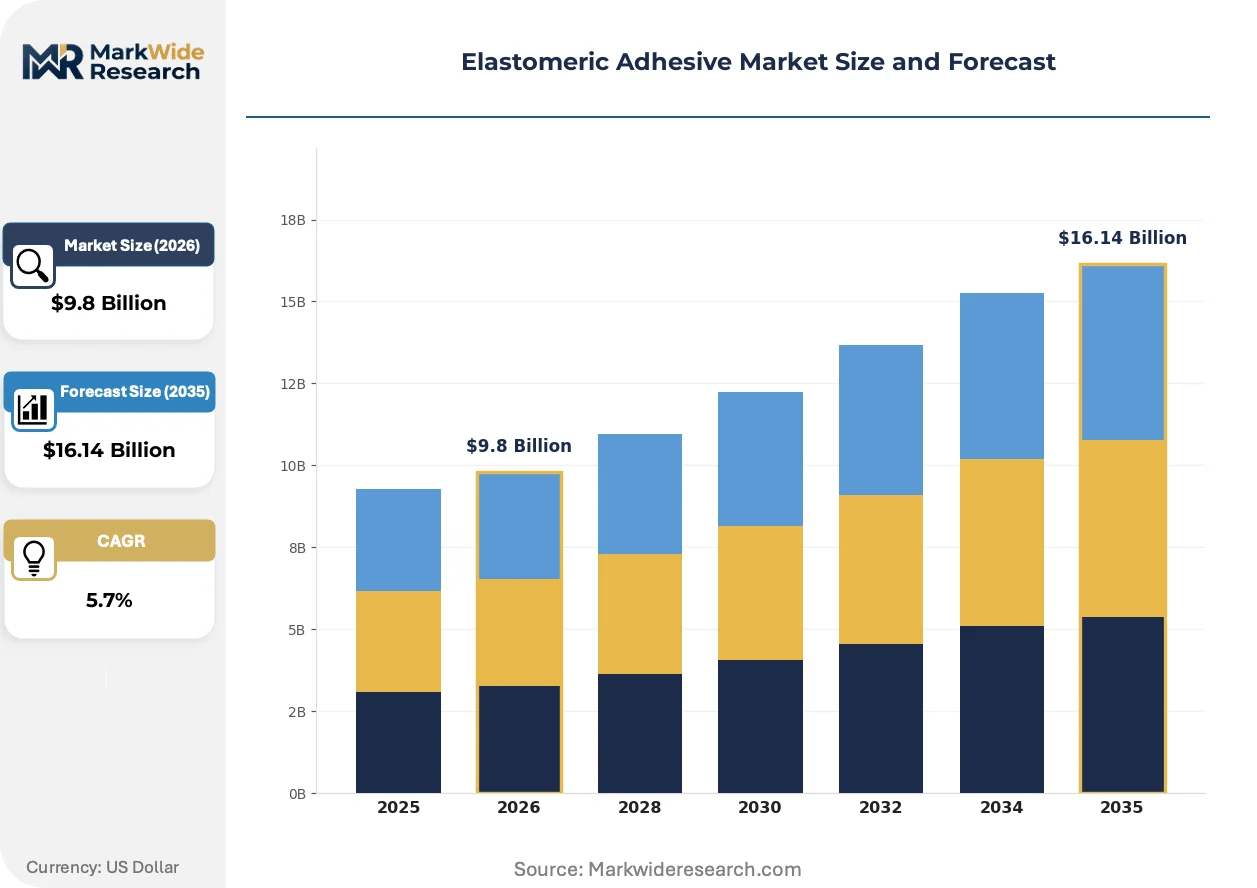
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Rubber End User: Automotive, Construction, Electronics, Packaging Application: Sealing, Bonding, Coating, Insulation Technology: Hot Melt, Solvent-Based, Water-Based, UV-Cured |
| Companies Covered | Dow, Henkel AG, 3M, Arkema, Sika AG, H.B. Fuller, Wacker Chemie AG, PPG Industries, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Adhesive Market Strategic Shifts & Innovations
Material science innovation is focused on creating multi-functional adhesives that satisfy both stringent environmental regulations and higher performance demands from advanced manufacturing sectors. This dual pressure is accelerating the development of hybrid chemistries and specialized formulations.
Hybrid polymer systems, such as silyl-modified polymers (SMPs), are gaining traction for their ability to combine the distinct advantages of silicones and polyurethanes. The construction and transportation industries are primary adopters, seeking a single product with superior weather resistance, paintability, and broad substrate adhesion. This development is rendering obsolete the reliance on separate products for sealing and bonding, simplifying inventory and application processes for end-users.
China's mandatory GB standards for adhesives are reshaping formulation strategies for market access. These regulations set strict limits on VOCs and other hazardous substances in products used for automotive interiors, furniture, and building materials. This forces global producers to develop and certify specific, compliant formulations for the Chinese market, effectively segmenting the global product portfolio. The automotive segment is particularly affected, driving localized R&D in water-based and hot-melt technologies.
A shift from transactional product sales toward integrated bonding solutions is altering supplier-customer relationships. End-users in high-stakes industries are demanding comprehensive packages that include the adhesive, automated dispensing equipment, and ongoing process optimization support. This model disrupts traditional distributors focused on volume sales, favoring suppliers with deep application engineering capabilities. This trend is most visible in the aerospace and medical device manufacturing sectors, where process validation and repeatability are critical.
Elastomeric Adhesive Market Segmentation
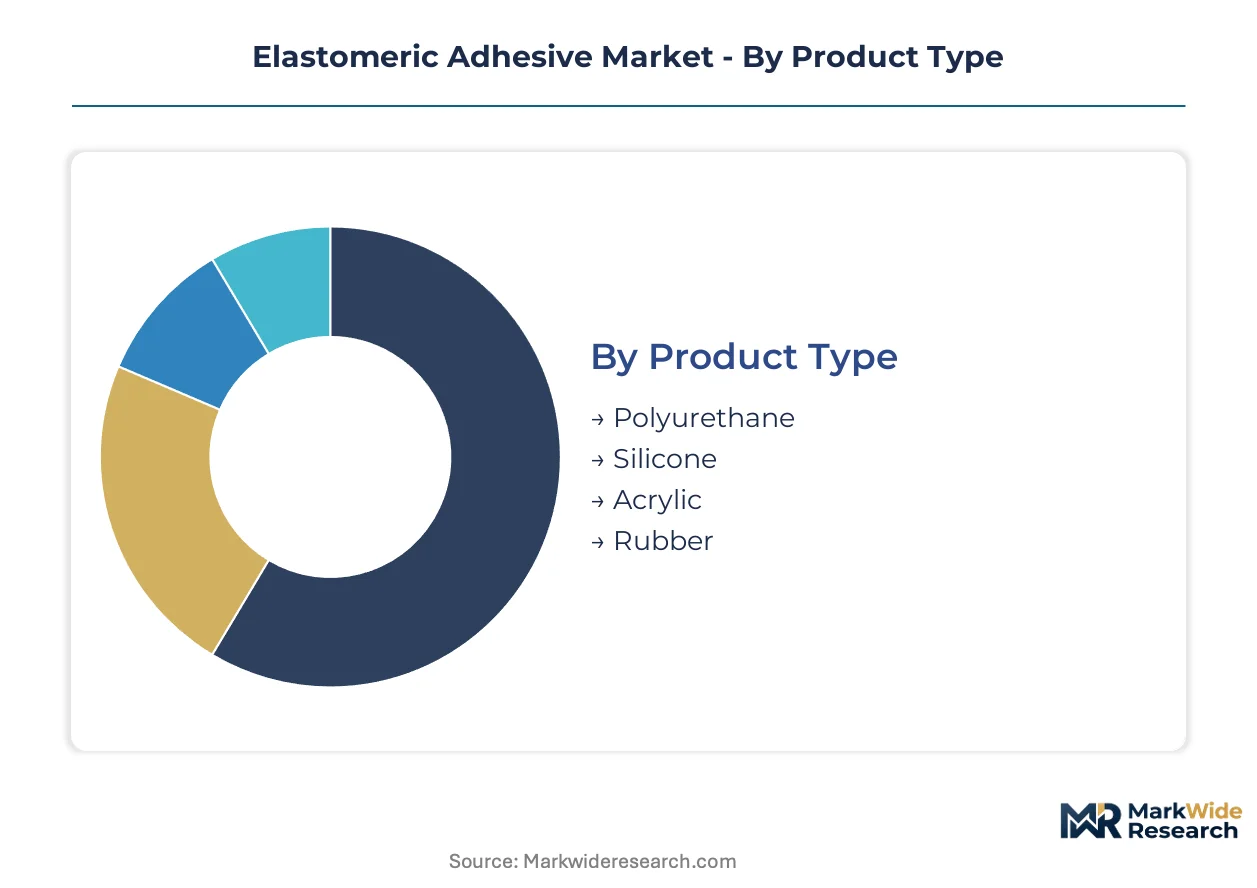
The elastomeric adhesive market exhibits diverse characteristics across its various segments, reflecting distinct material properties, end-use requirements, and technological advancements. Understanding these segmentations provides clarity on demand drivers, competitive dynamics, and areas for innovation within this specialized bonding solutions sector.
Product Type:
The product type segment reveals a maturity spectrum, with established chemistries dominating while newer formulations gain specialized traction for specific applications.
- Polyurethane:These adhesives offer excellent flexibility, impact resistance, and strong adhesion to diverse substrates, making them suitable for automotive and construction uses. Demand concentrates in vehicle assembly for structural bonding and sealing applications, driven by lightweighting initiatives.
- Silicone:Known for their high-temperature stability, UV resistance, and flexibility, silicone adhesives are critical in electronics and construction. The electronics industry drives significant demand for silicone due to its electrical insulation properties and performance in extreme thermal cycling.
- Acrylic:Acrylic-based elastomeric adhesives provide good weatherability and strong adhesion to plastics, finding use in signage and general assembly.
- Rubber:Rubber-based formulations offer high tack and elasticity, commonly used in packaging and non-structural bonding applications.
Polyurethane handles the majority of throughput; Silicone is the fastest mover on share.
End User:
End-user applications define demand concentration, dictating specific performance requirements and regulatory compliance needs for elastomeric adhesives across industries.
- Automotive:This sector utilizes elastomeric adhesives for bonding dissimilar materials, improving NVH characteristics, and reducing vehicle weight. Automotive OEMs in Germany and the United States demand high-performance formulations for battery pack assembly and body-in-white applications.
- Construction:The construction industry employs these adhesives for sealing expansion joints, bonding curtain walls, and installing flooring, requiring long-term durability and weather resistance. Advanced infrastructure projects in China and Europe drive demand for high-performance sealants.
- Electronics:Elastomeric adhesives protect sensitive components from shock and vibration, providing encapsulation and flexible bonding solutions.
- Packaging:These adhesives are used for flexible packaging, laminations, and carton sealing, prioritizing quick set times and strong bond integrity.
The automotive industry drives significant volume demand; construction applications are expanding most quickly.
Application:
Functional requirements shape the application segment, as elastomeric adhesives deliver specific performance attributes across diverse industrial processes.
- Bonding:This application involves permanently joining two or more substrates, providing structural integrity and stress distribution across the bonded area. The automotive sector demands robust bonding solutions for composite materials and advanced plastics, crucial for vehicle crashworthiness.
- Sealing:Sealing applications prevent the ingress of moisture, dust, or chemicals, maintaining environmental integrity and system performance. Construction projects in Europe require high-performance elastomeric sealants for energy-efficient building envelopes and weatherproofing.
- Coating:Elastomeric coatings provide a protective, flexible layer against abrasion, corrosion, and environmental degradation for various surfaces.
- Insulation:These adhesives are used to secure thermal and acoustic insulation materials, enhancing energy efficiency and noise reduction in buildings and vehicles.
Bonding applications represent the largest segment by volume; sealing applications are gaining share fastest due to infrastructure projects.
Technology:
Regulatory influence and environmental mandates significantly steer the technology segment, pushing innovation towards compliant and sustainable formulations.
- Water-Based:These technologies use water as the primary solvent, reducing VOC emissions and aligning with stringent environmental regulations like the US EPA rules and EU REACH. Demand for water-based formulations is rising in the furniture and automotive interior sectors in China.
- Hot Melt:Hot melt adhesives are thermoplastic materials applied in a molten state, offering fast setting times and solvent-free operation for high-speed assembly lines. The packaging industry in the United States increasingly adopts hot melt for efficient and clean production processes.
- Solvent-Based:Traditional solvent-based adhesives offer strong adhesion and quick drying, though their use is declining due to VOC regulations.
- UV-Cured:UV-cured adhesives polymerize rapidly under ultraviolet light, enabling high-speed production and precise bonding in electronics and medical device manufacturing.
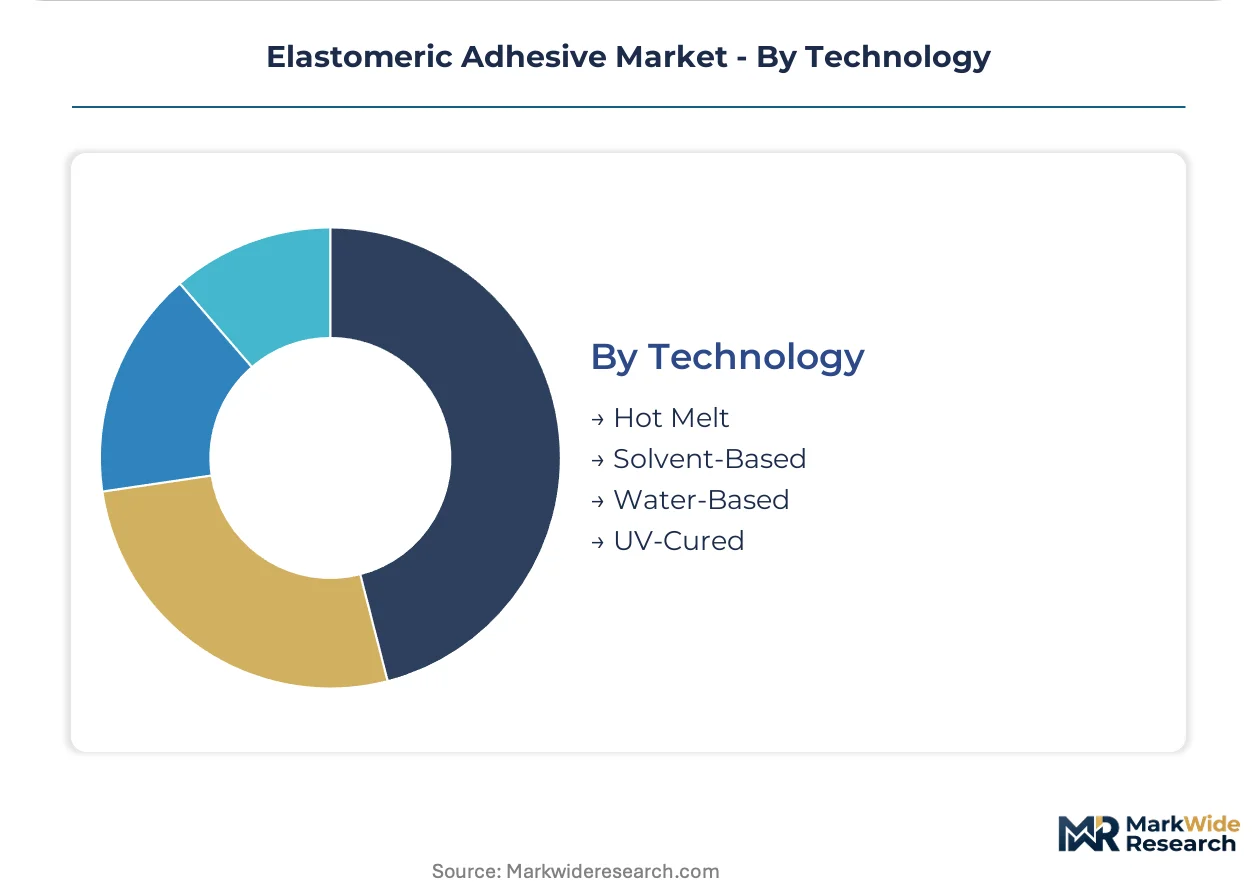
Water-Based technologies are capturing increasing R&D investment; hot melt formulations demonstrate steep expansion trajectory in assembly processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government regulations, particularly those targeting VOC emissions, serve as a primary policy driver for elastomeric adhesive market development globally. These mandates compel manufacturers to invest in compliant formulations, steering regional innovation toward water-based and hot-melt technologies. Industrial clusters in key economic zones are central to both production and research efforts.
United States
Demand for elastomeric adhesives in the United States stems from automotive lightweighting and advanced construction projects. US EPA rules on volatile organic compounds directly influence product development, favoring solvent-free options. The Detroit automotive manufacturing hub and Silicon Valley's electronics sector drive specialized adhesive innovation for high-performance applications.
Germany
Germany's automotive industry and sophisticated manufacturing sectors are significant consumers of elastomeric adhesives. The European Union's REACH regulation mandates strict chemical substance control, pushing German companies toward sustainable material innovation. Industrial clusters in Bavaria and North Rhine-Westphalia are centers for R&D and production of advanced adhesive formulations.
China
China's rapid industrialization and infrastructure expansion fuel substantial demand for elastomeric adhesives in construction and automotive sectors. Mandatory GB standards dictate formulation requirements for market access, especially for low-VOC products. The Yangtze River Delta region, including Shanghai, serves as a major hub for adhesive manufacturing and application engineering.
Japan
Advanced manufacturing in Japan, particularly in automotive and electronics, relies on high-performance elastomeric adhesives for precision bonding. Japan's environmental policies encourage the development of eco-friendly adhesive solutions. The Kanto region, encompassing Tokyo, hosts numerous specialized chemical companies engaged in cutting-edge adhesive material science.
Elastomeric Adhesive Market Key Industry Players
Channel-controlling players compete with product-specialist players across the elastomeric adhesive market, leading to a hybrid competitive structure. The landscape includes large chemical conglomerates offering broad portfolios alongside niche formulators focused on specific applications. Strategic partnerships and targeted acquisitions represent dominant competitive moves as companies seek to expand technological capabilities and geographic reach.
Among global chemical conglomerates, Dow and Henkel AG exemplify diversified approaches. Dow leverages its deep expertise in upstream polymer science and raw material control to offer a wide range of basic and specialty chemicals. Henkel AG, with its extensive global distribution network, serves a broad array of end-users across multiple segments. Sika AG occupies a position as a specialist in high-performance formulations for demanding construction and infrastructure projects, differentiating through application-specific solutions.
| Leading Market Players |
|---|
| Dow |
| Henkel AG |
| 3M |
| Arkema |
| Sika AG |
| H.B. Fuller |
| Wacker Chemie AG |
| PPG Industries |
| RPM International |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstocks like isocyanates and siloxanes, concentrated in global oil and gas markets, directly dictate manufacturing costs and subsequently influence margin pools for elastomeric adhesive formulators. This upstream dependency links adhesive pricing to crude oil volatility.
Pricing Analysis
Certification level, particularly compliance with EU REACH and China's GB standards, creates the primary spread in elastomeric adhesive pricing. Pricing for these specialized materials typically follows a contract-based long-term offtake model, often customized for project-specific needs. Pricing pressure stems from intense competition among formulators and end-user demand for cost-effective solutions. The packaging and general assembly segments exhibit high price sensitivity, while aerospace and medical device sectors prioritize performance over cost.
Supply Chain Analysis
Export-control regimes and environmental regulations, such as EU REACH and US EPA rules, limit the flow of certain solvent-based formulations, fragmenting global supply. Key raw materials like isocyanates and siloxanes are sourced globally, with significant production in petrochemical-rich regions. Commodity price volatility for these precursors presents a structural supply chain risk. Distribution runs through a hybrid model, combining direct sales to large automotive OEMs with specialized industrial distributors serving diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigating the elastomeric adhesive market requires addressing a critical shortage of polymer chemists and application engineers. This talent gap hinders new product development and limits crucial technical support for complex bonding solutions.
For Market Incumbents: Pre-empt the erosion of market share by investing heavily in compliant, solvent-free technology R&D. Develop hybrid polymer systems like SMPs to offer multi-functional solutions, countering specialized niche formulators. Reinforce application engineering capabilities to provide integrated bonding solutions, thereby offsetting the threat from substitute mechanical fasteners in structural applications. Secure long-term supply agreements for key petrochemical raw materials to mitigate price volatility.
For New Entrants and Emerging Players: Establish a beachhead in rapidly expanding regions like Southeast Asia, leveraging local manufacturing partnerships to meet localized demand. Focus on specific high-growth applications, such as flexible electronics or conductive adhesive formulations, where established players may be slower to adapt. Offer specialized technical support and customization to differentiate from broad-portfolio incumbents. Target underpenetrated segments requiring water-based or hot-melt technologies driven by regional regulatory mandates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the R&D-intensive solvent-free formulations segment, favoring larger players with deep pockets. Long-term viability in this market depends on access to advanced polymer science and application engineering expertise. Target mid-sized, technology-focused formulators with strong intellectual property in hybrid chemistries or specialized conductive adhesives. The signal to watch is the rate of regulatory enforcement in emerging markets, indicating accelerated demand for compliant solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces VOC emissions, aligning with EU REACH and US EPA rules, enhancing market access in regulated regions. |
| Capacity Expansion in Southeast Asia | Capitalizes on rapid industrialization and infrastructure investment in underpenetrated markets, meeting local demand for advanced bonding. |
| Joint Venture for Hybrid Chemistries | Accelerates development of silyl-modified polymers, combining silicone and polyurethane advantages for construction and transportation. |
| Acquisition of Application Engineering Firm | Deepens expertise in integrated bonding solutions, providing critical technical support to end-users in aerospace and medical devices. |
| Long-term Supply Agreement for Isocyanates | Mitigates raw material price volatility and ensures stable production of polyurethane-based adhesives for automotive and construction. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, chemical industry association reports, SEC 10-K filings, and academic polymer science journals. Primary interviews included R&D directors, procurement leads at automotive OEMs, construction project managers, and specialized adhesive distributors. This approach leveraged both bottom-up market sizing and top-down validation to ensure data accuracy. The analysis integrated diverse data points for comprehensive market understanding.
Forecast inputs considered macroeconomic indicators, technological advancements, and regulatory shifts across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user, application, technology, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected adoption rates. Industry-specific inputs included global vehicle production forecasts and infrastructure spending trends.
Stress conditions across raw material price shocks and new regulatory frameworks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning technological adoption and compliance rates. Material shifts in global petrochemical supply or major regional trade policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market