
 US Adhesives and Sealants Market | 2026-2036
US Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
US Adhesives and Sealants Market Intelligence
Application-specific formulation support as a bundled service is expanding the traditional product-centric sales model in the US adhesives sector. This approach embeds technical expertise directly into the customer relationship, creating stickier contracts. Henkel AG & Co. KGaA leverages its extensive portfolio to serve diverse end-users from construction to electronics. H.B. Fuller Company specializes in industrial adhesives for packaging and assembly, while Dow anchors a significant portion of the market with its upstream polymer science capabilities.
Adhesives are substances that hold materials together by surface attachment, while sealants are materials used to fill gaps and form a protective, flexible barrier. These formulations function through chemical processes like polymerization or physical solvent evaporation to create bonds with specific shear and peel strength. Water-based and reactive technologies are gaining market share from traditional solvent-based systems. While the construction end-user segment represents the largest volume, electronics applications command higher margins for specialized bonding.
The US Environmental Protection Agency (EPA) heavily influences formulation trends through stringent regulations on Volatile Organic Compounds (VOCs) under the Clean Air Act. Concurrently, the Occupational Safety and Health Administration (OSHA) sets Hazard Communication Standards for worker safety, impacting chemical labeling and handling procedures. Future success for suppliers depends on their ability to deliver compliant, high-performance formulations that are optimized for automated manufacturing lines.
Market Dynamics
The primary structural force shaping the US adhesives and sealants market is the dual pressure of environmental regulation and manufacturing automation. EPA mandates on VOCs are compelling formulation changes, while demands for higher throughput on factory floors prioritize fast-curing chemistries.
Growth Catalysts
- Electric Vehicle Production:The ramp-up of electric vehicle manufacturing in the US creates substantial demand for specialized adhesives for battery pack assembly, thermal management, and lightweight composite body-in-white structures.
- Manufacturing Reshoring:A concentration of new manufacturing investment, particularly in southeastern states like South Carolina and Georgia, is expanding the regional industrial base and creating localized demand for assembly and packaging adhesives.
- EPA Regulations:Stringent limits on Volatile Organic Compounds (VOCs) under the Clean Air Act accelerate the market transition from traditional solvent-based products to higher-value, compliant water-based and reactive technologies.
Market Restraints
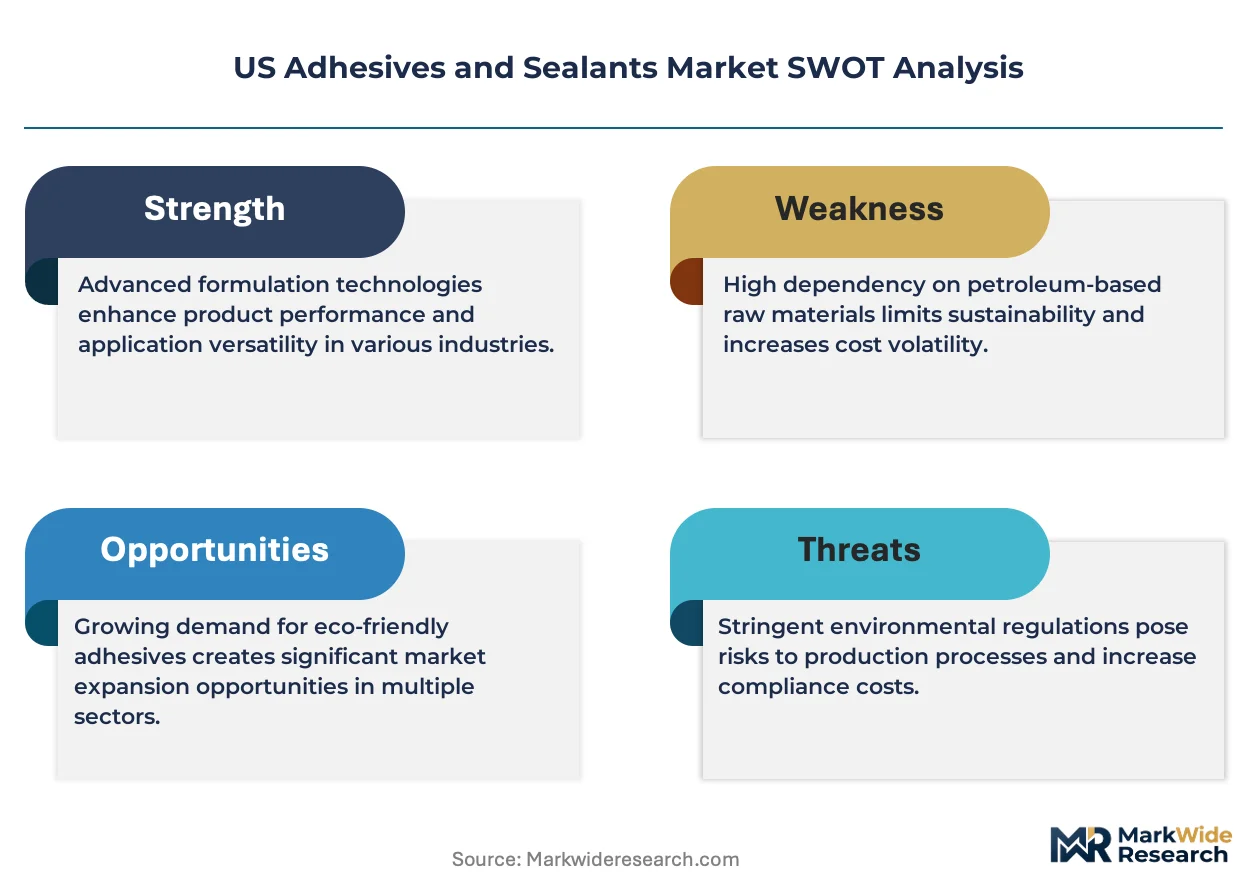
- Feedstock Volatility:The industry's dependence on petrochemical derivatives for many polymer systems creates exposure to price fluctuations in crude oil and natural gas, impacting formulation costs and margin stability.
- Performance Gaps:Certain water-based and bio-based formulations still exhibit longer cure times or lower bond strength under extreme temperature or moisture conditions compared to legacy solvent-based systems, limiting their use.
- Mechanical Fastening Substitution:In heavy-duty construction and industrial applications, mechanical fasteners like bolts and welds remain the default choice for structural joints, representing a persistent substitution threat for structural adhesives.
Strategic Opportunities
- Medical Wearables:Developing skin-contact adhesives for medical wearable sensors and drug delivery patches represents a high-margin opportunity, requiring expertise in biocompatibility and flexible bonding for extended wear.
- Bio-Based Formulations:The convergence of bio-based feedstocks, such as plant-derived resins and oils, with high-performance reactive chemistries offers a pathway to develop sustainable products that do not compromise on technical specifications.
- Digital Sales Channels:Creating direct-to-fabricator e-commerce platforms for specialized industrial adhesives can bypass traditional distribution, offering better technical support and capturing higher margins from large-volume accounts.
Industry Challenges
- Formulation Talent Scarcity:A shortage of polymer chemists who possess dual expertise in advanced formulation science and the nuances of evolving EPA and OSHA regulatory landscapes hinders new product development cycles.
- Automation Integration Costs:Integrating modern, high-viscosity or two-component adhesive systems requires significant capital investment in robotic dispensing equipment and process re-engineering on automated assembly lines.
- Hazard Communication Compliance:The need to generate and maintain updated Safety Data Sheets and worker training protocols under OSHA's Hazard Communication Standard for every new formulation adds significant administrative overhead and liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Adhesives and Sealants Market |
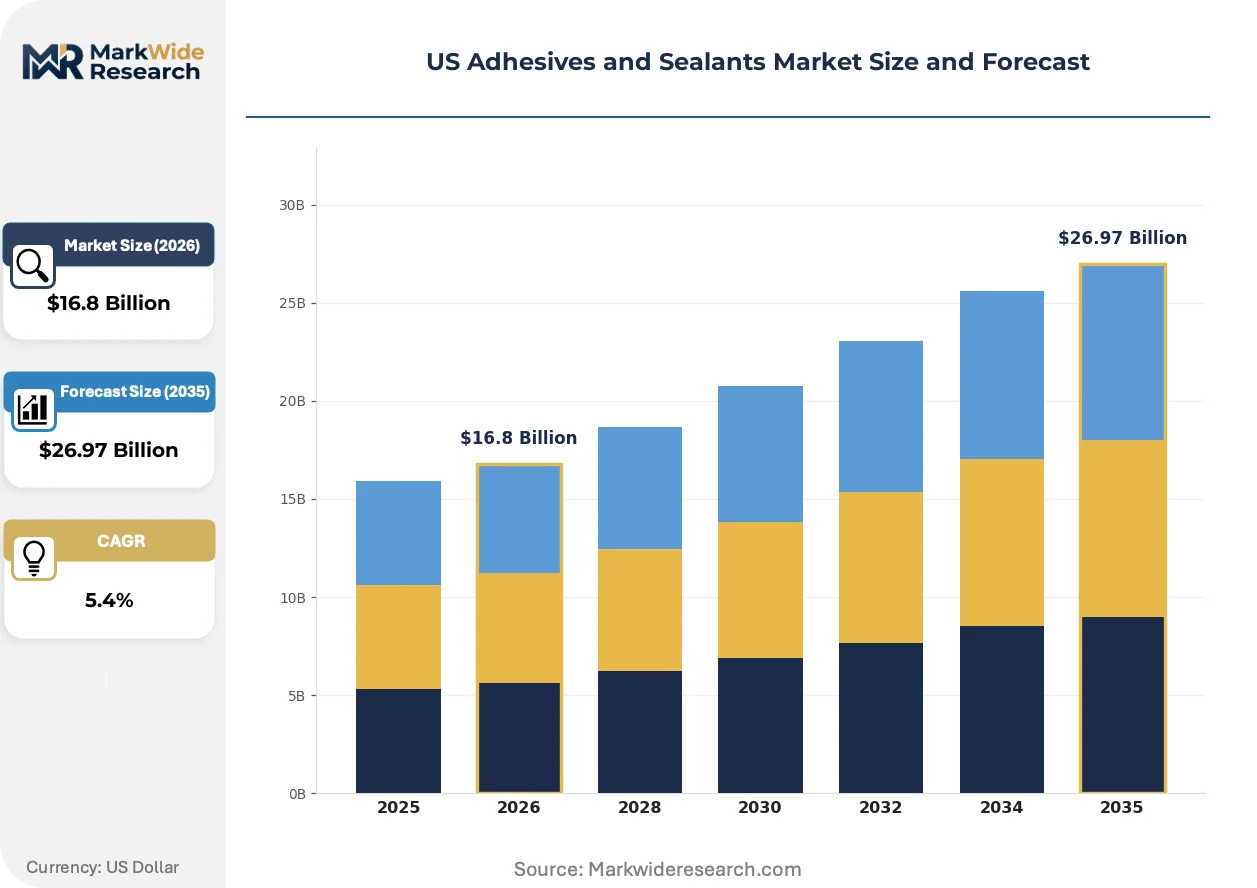
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Construction, Automotive, Electronics, Consumer Goods Application: Bonding, Coating, Sealing, Filling Technology: Water-Based, Solvent-Based, Hot-Melt, Reactive |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, Arkema Group, Sika AG, Dow, Huntsman Corporation, Illinois Tool Works Inc., Avery Dennison Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Adhesives and Sealants Market Strategic Shifts & Innovations
Formulation science is adapting to the twin demands of manufacturing efficiency and environmental stewardship. The market is defined by a push for chemistries that cure faster, emit less, and bond a wider array of dissimilar materials used in modern product design.
Reactive hot-melt adhesives provide strong initial bonds and rapid curing through chemical cross-linking. The automotive and packaging sectors are rapidly adopting these technologies for high-speed assembly lines. The fast set time of these adhesives is automating production processes by minimizing the need for clamps, fixtures, and extended curing ovens.
The US Environmental Protection Agency's stringent regulation of Volatile Organic Compounds (VOCs) directly influences product development. This regulatory pressure is forcing a systemic shift from solvent-based systems to water-based, 100% solids, and hot-melt technologies. The construction and furniture industries are most affected, prioritizing low-VOC products to meet green building and indoor air quality standards.
Industrial customers are increasingly choosing suppliers based on bundled technical support, including application testing and process optimization. This service-led model is disrupting traditional product-centric sales channels, especially for complex bonding challenges. The shift is most visible in the US aerospace and electronics sectors, where collaboration on adhesive selection is critical for final product performance.
US Adhesives and Sealants Market Segmentation
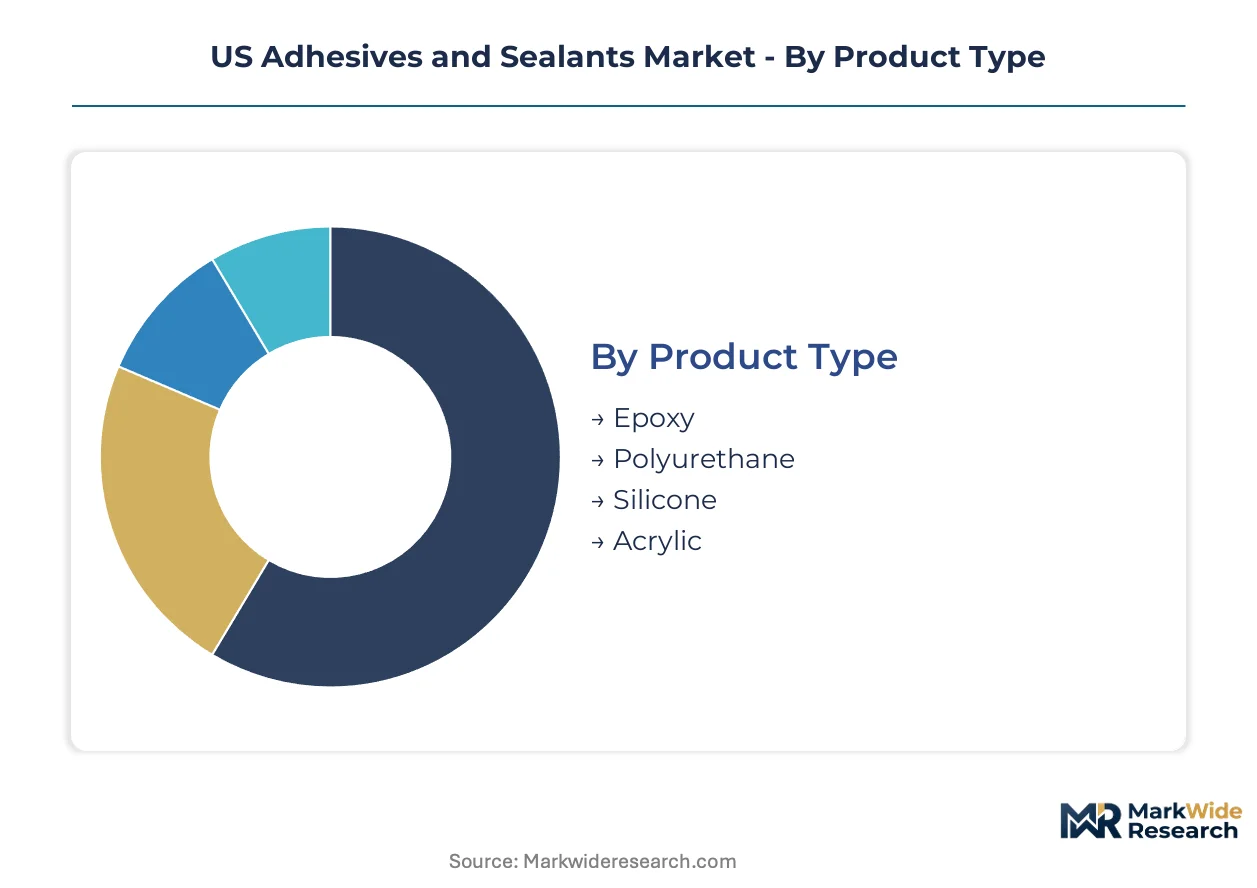
The US adhesives and sealants market segments across product type, end-user industry, application method, and core technology. Each segment reflects distinct material properties and performance requirements. Understanding these classifications is essential for strategic market positioning and product development within the country.
Product Type:
The supply concentration for specific polymer types dictates material availability and cost structures within the US adhesives and sealants market.
- Epoxy:These thermosetting polymers provide excellent adhesion, chemical resistance, and mechanical strength, often used for structural bonding. Demand for epoxy formulations is concentrating in the automotive sector for lightweighting applications and battery assembly, driven by electric vehicle production.
- Polyurethane:Polyurethane adhesives offer flexibility, good bond strength, and impact resistance, finding use in construction and automotive assembly.
- Silicone:Silicone-based sealants and adhesives provide high-temperature stability, UV resistance, and flexibility, critical for electronics and outdoor construction.
- Acrylic:Acrylic adhesives are known for their fast-curing properties, transparency, and versatility across various substrates. Their demand is concentrating in consumer goods and electronics, where rapid assembly and aesthetic bonding are crucial.
Acrylic absorbs the bulk of installed capacity; Epoxy is expanding most quickly.
End User:
Application-specific requirements drive material selection and formulation complexity across diverse end-user segments in the US adhesives market.
- Construction:This segment consumes high volumes of sealants and adhesives for building envelopes, flooring, and insulation, influenced by green building standards.
- Automotive:The automotive sector utilizes specialized adhesives for structural bonding, interior trim, and critical electric vehicle components like battery packs. Demand is concentrating in southeastern US manufacturing hubs, driven by new EV production facilities.
- Electronics:Electronics applications require high-performance, often conductive or thermally managing adhesives for micro-assembly and component protection. This segment commands higher margins for specialized bonding solutions, particularly for medical wearables.
- Consumer Goods:Adhesives for consumer goods facilitate assembly, packaging, and product integrity for a wide array of household and personal care items.
Market value is heavily weighted towards Electronics, while Automotive demonstrates robust expansion.
Application:
Margin profiles vary significantly across different application methods, reflecting the technical complexity and performance demands of each use case.
- Bonding:This application involves creating strong, permanent joints between two or more substrates, often replacing mechanical fasteners in structural applications. Demand for bonding solutions is concentrating in high-performance areas like aerospace and electric vehicle manufacturing.
- Coating:Adhesives used as coatings provide protective layers, enhance surface properties, or prepare substrates for further adhesion in various industrial processes.
- Sealing:Sealants create flexible barriers to prevent the ingress of moisture, air, or contaminants, crucial for weatherproofing and environmental protection. Demand for advanced sealants is concentrating in construction and automotive, particularly for battery enclosures.
- Filling:Filling applications involve using adhesive or sealant materials to fill gaps, voids, or cracks, improving structural integrity and aesthetics.
The largest volume of material moves into Sealing, with Bonding commanding premium pricing.
Technology:
Cost tiers for adhesive and sealant technologies are influenced by raw material sourcing, processing complexity, and regulatory compliance requirements.
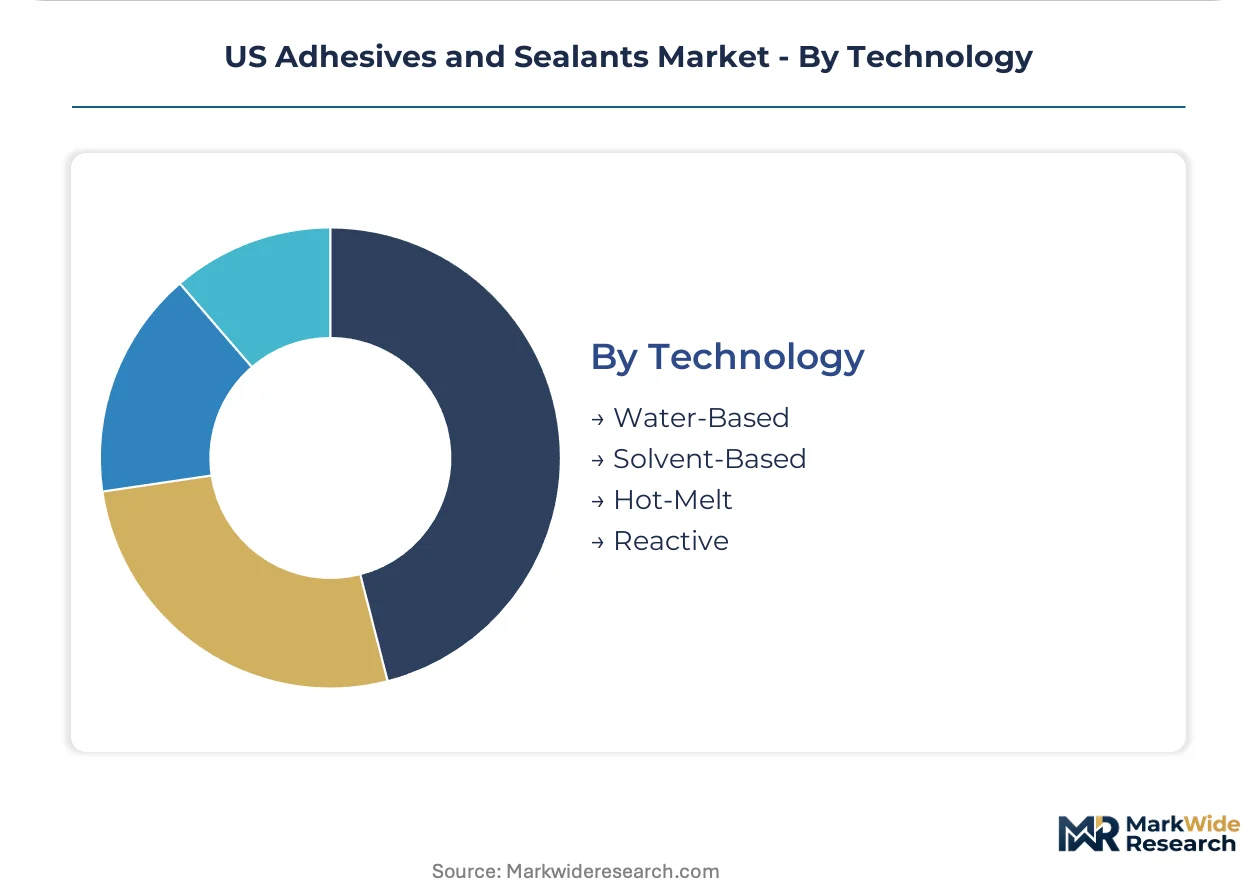
- Water-Based:These formulations use water as a solvent, reducing VOC emissions and aligning with stringent US EPA regulations under the Clean Air Act. Demand for water-based systems is concentrating in construction and furniture industries due to indoor air quality standards.
- Solvent-Based:Traditional solvent-based systems provide strong adhesion and fast drying but face declining market share due to VOC regulations and worker safety concerns.
- Hot-Melt:Hot-melt adhesives are thermoplastic materials applied in a molten state, offering rapid setting times for high-speed assembly lines in packaging and automotive.
- Reactive:Reactive adhesives undergo a chemical reaction to cure, forming strong, durable bonds with specific shear and peel strength. Demand for reactive technologies is concentrating in electric vehicle manufacturing for structural bonding and thermal management.
Compliance mandates drive demand for Water-Based technologies, as Solvent-Based systems face regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US adhesives and sealants market exhibits a unique dynamic where localized production centers are emerging to meet specific consumption patterns. Demand for these materials is heavily influenced by regional manufacturing shifts and regulatory environments. This creates distinct growth pockets across various states and metropolitan areas.
Southeast
The Southeast region, encompassing states like Georgia and South Carolina, experiences significant demand for specialized adhesives due to electric vehicle production and manufacturing reshoring initiatives. EPA standards on Volatile Organic Compounds (VOCs) influence new plant designs and formulation choices. New EV battery assembly plants in Georgia and South Carolina are driving demand for specialized structural adhesives and thermal management materials.
Midwest
Midwest states, including Michigan and Ohio, see substantial demand for adhesives in automotive assembly and packaging for consumer goods. OSHA Hazard Communication Standards impact material handling and safety protocols in manufacturing facilities. Ohio and Michigan's industrial corridors are seeing increased demand for hot-melt adhesives in high-speed packaging lines and automotive component bonding.
Northeast
Northeast's dense metropolitan areas, such as those in New York and Pennsylvania, show strong demand for construction-related sealants and adhesives. Green building codes and indoor air quality standards prioritize low-VOC sealants and water-based formulations. New York and Pennsylvania metropolitan areas show strong demand for water-based formulations in commercial and residential construction projects.
Southwest
The Southwest is seeing rising demand for high-performance adhesives in aerospace component assembly and semiconductor packaging. FAA regulations for aerospace materials require specific bonding solutions for structural integrity and thermal management. Arizona and Texas are experiencing demand for high-performance adhesives in micro-electronics and defense manufacturing clusters.
West Coast
California and the West Coast drive demand for adhesives in medical wearables, advanced electronics, and sustainable packaging solutions. California's stringent environmental regulations encourage bio-based and water-based adhesive innovations for various applications. Silicon Valley and Southern California are centers for specialized bonding solutions in high-margin medical and consumer electronics.
US Adhesives and Sealants Market Key Industry Players
Top-tier vendors anchor the US adhesives and sealants market, while mid-sized specialists and niche players serve specific application areas. The market features global chemical conglomerates, industrial adhesive specialists, and material science innovators. Portfolio diversification across end-use sectors is a common strategic move. Companies also engage in targeted acquisitions to enhance technological capabilities.
Within the global chemical conglomerate archetype, Henkel AG & Co. KGaA, with its German AG structure, exemplifies a broad portfolio approach. H.B. Fuller Company, an industrial adhesives specialist, occupies a position focused on assembly and packaging applications. Dow, a US-based corporation, anchors a significant portion of the market through its extensive upstream polymer science capabilities. These entities represent different strategic vectors, from diversified chemical manufacturing to specialized industrial solutions, reflecting the varied competitive strategies in the sector.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Arkema Group |
| Sika AG |
| Dow |
| Huntsman Corporation |
| Illinois Tool Works Inc. |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
Stringent EPA mandates on Volatile Organic Compounds (VOCs) gate qualified supply, creating a premium-tier pricing access for compliant, high-performance formulations in the US adhesives and sealants market.
Pricing Analysis
Cost-down pressure on commodity-grade solvent-based systems accelerates because of stringent EPA regulations and declining demand. The dominant pricing model for specialized industrial adhesives is contract-based long-term offtake, with transactional pricing for smaller volumes. Price differentiation stems from performance specifications, regulatory compliance certifications, and bundled technical support services. Electronics and aerospace segments exhibit lower price sensitivity due to critical performance requirements, while the construction sector remains highly sensitive to material costs.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common among large industrial buyers, mitigating single-supplier risks in the US adhesives market. The supply chain draws heavily from petrochemical derivatives, with significant raw material concentration in regions like the US Gulf Coast and the Middle East for primary chemical inputs. Feedstock price volatility, particularly for crude oil and natural gas, represents a persistent structural risk to formulation costs. Distribution runs through a hybrid model combining direct sales for major accounts and specialized industrial distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US adhesives and sealants market is fundamentally a cost-of-compliance story, where stringent EPA regulations create a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents:To counter the performance gaps of some water-based formulations, incumbents must invest heavily in advanced R&D for next-generation reactive chemistries. Strategic acquisitions of smaller firms specializing in bio-based or high-performance niche technologies can accelerate portfolio diversification. Enhancing application-specific technical support services creates stickier customer relationships and differentiates offerings from commodity suppliers. Focus on optimizing automated dispensing solutions for high-throughput manufacturing lines.
For New Entrants and Emerging Players:Begin with targeting underserved regional manufacturing clusters, particularly those in the Southeast US driven by EV production. Focus on developing high-margin, specialized solutions for electronics or medical wearables where performance outweighs initial cost. Leveraging digital sales channels and direct-to-fabricator e-commerce platforms can bypass traditional distribution complexities. Offer bundled technical support from the outset to build credibility and integrate into customer process flows.
For Investors and Strategic Acquirers:The consistent ramp-up of new electric vehicle production facilities in the Southeast US is the leading indicator that specialized adhesive demand will sustain long-term growth. Investment targets should prioritize vertically integrated specialists with robust R&D in compliant, high-performance chemistries. Companies possessing strong intellectual property in reactive hot-melts or advanced water-based systems are particularly attractive. Watch for announcements of new manufacturing plant investments in key industrial sectors as a signal for sustained demand growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-VOC R&D | Develop compliant, high-performance formulations aligning with EPA standards for broad market access. |
| Expand Application-Specific Support | Embed technical expertise with customers, creating stickier contracts and higher-value relationships. |
| Acquire Bio-based Formulation Expertise | Gain sustainable product capabilities and address growing demand for environmentally friendly materials. |
| Develop E-commerce Platforms | Bypass traditional distribution channels, capture higher margins, and improve direct customer engagement. |
| Regional Manufacturing Capacity in Southeast | Serve localized demand from new electric vehicle and reshoring initiatives efficiently. |
Research Approach
Government trade statistics, corporate financial filings, and industry association reports formed the secondary backbone for market sizing and trend identification. Primary research involved in-depth interviews with R&D chemists, procurement managers at automotive OEMs, plant engineers in construction, and regulatory compliance officers. This approach combined bottom-up and top-down triangulation to validate market data and segment performance.
Historical trendline analysis across product types, end-user industries, and application methods informed the quantitative modeling over the projection horizon. Segmentation dimensions modeled included core polymer technologies, key end-use industries, major application methods, and regional manufacturing shifts within the US. CAGRs were derived from a blend of historical growth rates, projected end-user segment expansion, and technological adoption curves, with electric vehicle production forecasts serving as a key input.
Feedstock price volatility, unforeseen regulatory changes, and shifts in manufacturing reshoring policies are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive research and expert consultations. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market