
 Ethyl Acrylate Market | 2026-2036
Ethyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Acrylate Market Analytics
High-purity ester-grade specifications is collapsing the gap between commodity and performance-oriented supply tiers. BASF SE leverages its Ludwigshafen acrylic acid complex to sustain backward integration into specialty ethyl acrylate derivatives. Dow Inc. anchors North American supply through its Freeport, Texas, production corridor, while Arkema S.A. differentiates via bio-attributed acrylate pathways developed at its Carling, France, platform.
Ethyl acrylate is an acrylic ester monomer with a molecular weight of approximately 100.12 g/mol and a glass transition temperature near -24°C, produced industrially through esterification of acrylic acid with ethanol to serve as a reactive building block for polymerization into coatings, adhesives, and sealant systems. Emulsion polymerization dominates manufacturing output because waterborne acrylic dispersions satisfy tightening VOC limits across architectural and industrial coating end uses. Pressure-sensitive adhesives represent the fastest-expanding application segment, absorbing rising volumes from electronics assembly and medical tape formulations where tack retention and aging stability carry premium value.
EPA hazardous air pollutant standards for acrylic acid and ester production shape US facility permitting and emission control investments, while REACH registration obligations in Europe mandate comprehensive substance dossiers that filter out smaller import competitors. China's MEE enforces GB standards on volatile organic compound content in coatings that redirect domestic formulation toward waterborne acrylic systems. Stakeholders must monitor how carbon border adjustment mechanisms and regional bio-content mandates reshape feedstock sourcing decisions for acrylic acid derivatives.
Market Dynamics
Waterborne acrylic dispersion technology is collapsing the cost-performance gap between solvent-based and low-VOC coating systems, forcing formulation houses across automotive refinishing and architectural end uses to retool polymerization infrastructure around emulsion-grade ethyl acrylate feedstocks.
Growth Catalysts
- REACH registration dossiers:ECHA substance registration obligations in Europe filter out smaller import competitors, concentrating compliant supply among integrated producers with toxicology testing capabilities.
- Pressure-sensitive adhesive electronics assembly:Medical tape and flexible electronics bonding applications demand tack retention and aging stability that ethyl acrylate copolymers uniquely deliver.
- East China acrylic acid integration:Downstream adhesive and coating supply chains in Jiangsu and Zhejiang provinces benefit from captive ethyl acrylate production tied to regional acrylic acid complexes.
Market Restraints
- Acrylic acid feedstock volatility:Propylene oxidation economics tie ethyl acrylate margins to naphtha-cracking spreads and regional propylene availability.
- EPA hazardous air pollutant standards:US facility permitting requires emission control investments that elevate capital intensity for new acrylic acid-ester production corridors.
- Methacrylate substitution in high-Tg applications:Methyl methacrylate and specialty methacrylate esters displace ethyl acrylate where glass transition temperatures above ambient are required.
Strategic Opportunities
- India construction chemicals penetration:BIS standards adoption and infrastructure spending create formulation demand for waterborne acrylic sealants and tile adhesives.
- EU Green Deal bio-attributed pathways:Mass-balance certification for bio-ethanol derived acrylic esters commands premium positioning in sustainable coating procurement.
- Digital coating specification platforms:Technical data sheet automation and formulation matching algorithms compress customer acquisition cycles for specialty ester producers.
Industry Challenges
- Emulsion polymerization process control expertise:Particle size distribution and coagulum control require specialized chemical engineering talent scarce in emerging production regions.
- Legacy solvent-based customer qualification timelines:Automotive OEM coating approvals span 18-36 months, delaying waterborne acrylic system substitution even where technical performance matches incumbent technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Acrylate Market |
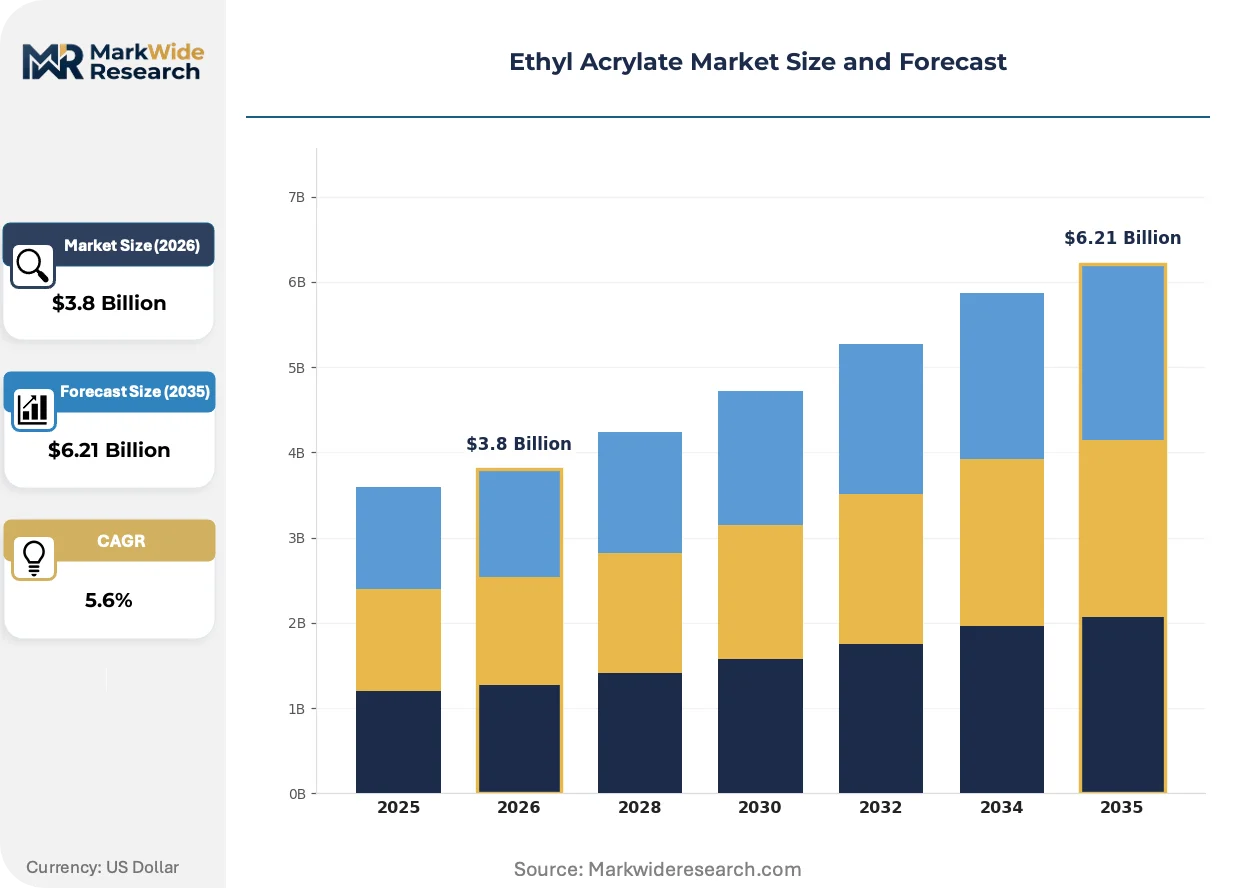
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solution, Film, Adhesive End Use Industry: Coatings, Textiles, Adhesives, Plastics Technology: Radical Polymerization, UV Polymerization, Solution Polymerization, Emulsion Polymerization Application: Paints, Sealants, Inks, Pressure-Sensitive Adhesives |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries, Arkema S.A., Mitsubishi Chemical Corporation, Nippon Shokubai Co., Ltd., Formosa Plastics Corporation, Merck KGaA, Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Acrylate Market Evolving Landscape
Reactive chemistry platforms are fragmenting along performance-commodity lines as buyers separate specification-grade esters from general-purpose volumes, creating divergent R&D investment priorities across the supplier base.
Hybrid waterborne-UV curing acrylic systems is bifurcating the industrial wood coating segment. Furniture manufacturers in Italy and Germany adopt dual-cure formulations combining ambient moisture crosslinking with UV-accelerated throughput. This technology is compressing conventional thermal-cure alkyd market share while creating formulation complexity that favors integrated resin suppliers over standalone monomer merchants.
China's MEE enforcement of GB standards on volatile organic compound content in coatings redirects domestic formulation toward waterborne acrylic systems. Architectural coating producers in Guangdong and Shandong provinces accelerate emulsion polymerization capacity additions. Industrial maintenance coating specifications now explicitly exclude solvent-borne options for state-funded infrastructure projects.
Specification-driven procurement now dominates automotive refinishing and electronics assembly segments, displacing volume-based tendering. Tier-1 coating formulators in Japan and South Korea consolidate supplier panels around certified ester-grade producers with documented impurity profiles. Medical device adhesive buyers audit polymerization batch records to ensure extractables compliance, compressing qualified supplier lists to three-to-five approved sources per region.
Ethyl Acrylate Market Segmentation
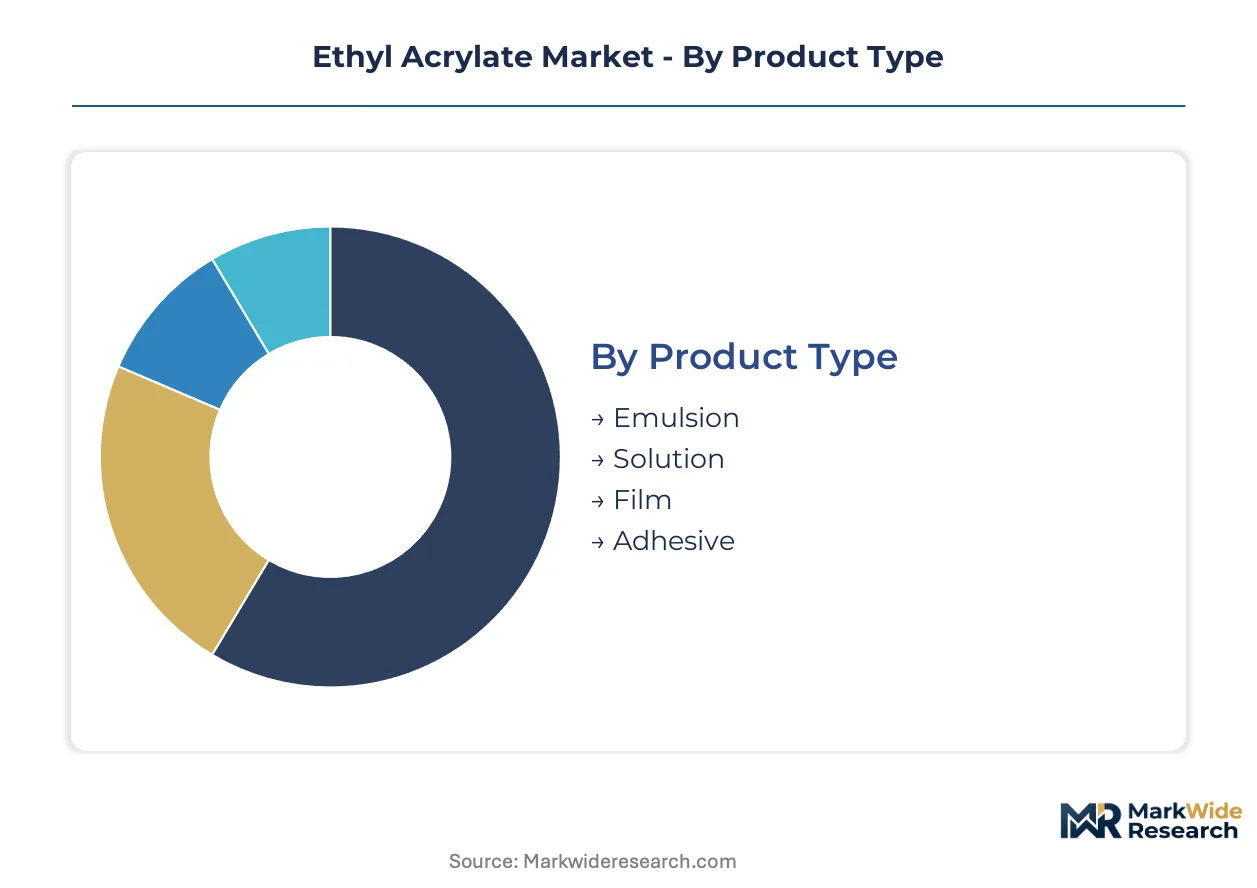
Segmentation in ethyl acrylate markets reveals how substitution pressures from methacrylate esters and bio-based alternatives reshape competitive priorities across formulation technologies. Understanding where performance premiums justify specification-grade sourcing versus commodity procurement enables suppliers to align R&D investments with defensible margin pools.
Product Type:
Emulsion formulations face the most acute substitution threat from waterborne polyurethane dispersions in high-performance coating segments, while film and adhesive grades defend position through specialized tack and clarity specifications that copolymer systems struggle to replicate.
- Emulsion:Waterborne acrylic dispersions with particle sizes between 80-300 nanometers serve architectural and industrial coating formulators confronting VOC limits. Demand concentrates in automotive refinishing corridors across Germany, China, and the United States where REACH and EPA regulations redirect investment from solvent-borne systems. The technology commands premium pricing where coagulum control and shelf stability specifications filter out merchant monomer suppliers lacking integrated polymerization expertise.
- Adhesive:Pressure-sensitive adhesive grades require precise molecular weight distribution and residual monomer control for medical tape and electronics bonding applications. East China manufacturers in Jiangsu province absorb rising volumes as regional acrylic acid integration supports downstream adhesive supply chains with reduced logistics exposure.
- Solution:Solvent-borne acrylic solutions retain niche position in specialty ink and high-gloss industrial coating segments where rapid drying and substrate wetting outweigh emission concerns.
- Film:Cast and extruded film grades serve packaging laminates and protective surface applications requiring optical clarity and weathering resistance.
Emulsion anchors the volume base while adhesive gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates specification-driven coatings procurement from price-sensitive textile processing, with adhesive applications occupying a middle tier where performance validation commands moderate premiums over commodity sourcing.
- Coatings:Architectural, automotive, and industrial maintenance coating formulators represent the largest ethyl acrylate consumption segment. Waterborne acrylic systems displace alkyd and epoxy technologies in state-funded infrastructure projects across China where MEE enforcement of GB standards explicitly excludes solvent-borne options.
- Adhesives:Pressure-sensitive, structural, and sealant applications demand copolymer formulations with precise glass transition temperature control. Medical device manufacturers audit polymerization batch records to ensure extractables compliance, compressing qualified supplier lists to certified ester-grade producers with documented impurity profiles.
- Plastics:Impact modifier and processing aid applications in PVC and engineering thermoplastics require consistent color and thermal stability specifications.
- Textiles:Sizing, finishing, and nonwoven binder applications compete with styrene-butadiene and vinyl acetate systems on cost in emerging production regions.
Coatings dominates absolute consumption while adhesive applications expand most quickly through electronics assembly and medical device qualification requirements.
Technology:
Process maturity creates divergence between established emulsion polymerization infrastructure and emerging UV-curing platforms that compress cycle times in industrial wood coating segments.
- Emulsion Polymerization:Dominant manufacturing output for waterborne acrylic dispersions using free-radical initiation in aqueous phase. Particle size distribution control and coagulum management require specialized chemical engineering talent scarce in emerging production regions, favoring integrated producers with captive acrylic acid supply.
- UV Polymerization:Dual-cure and UV-accelerated systems combine ambient moisture crosslinking with radiation-cured throughput for furniture manufacturers in Italy and Germany. The technology compresses conventional thermal-cure alkyd market share while creating formulation complexity that favors integrated resin suppliers.
- Radical Polymerization:Bulk and solution-phase free-radical processes serve solvent-borne coating and adhesive segments with high solids requirements.
- Solution Polymerization:Homogeneous phase polymerization in organic solvents enables precise molecular weight control for specialty adhesive and sealant grades.
Emulsion polymerization anchors the volume base while UV polymerization gains share at the steepest rate through hybrid waterborne-UV curing adoption.
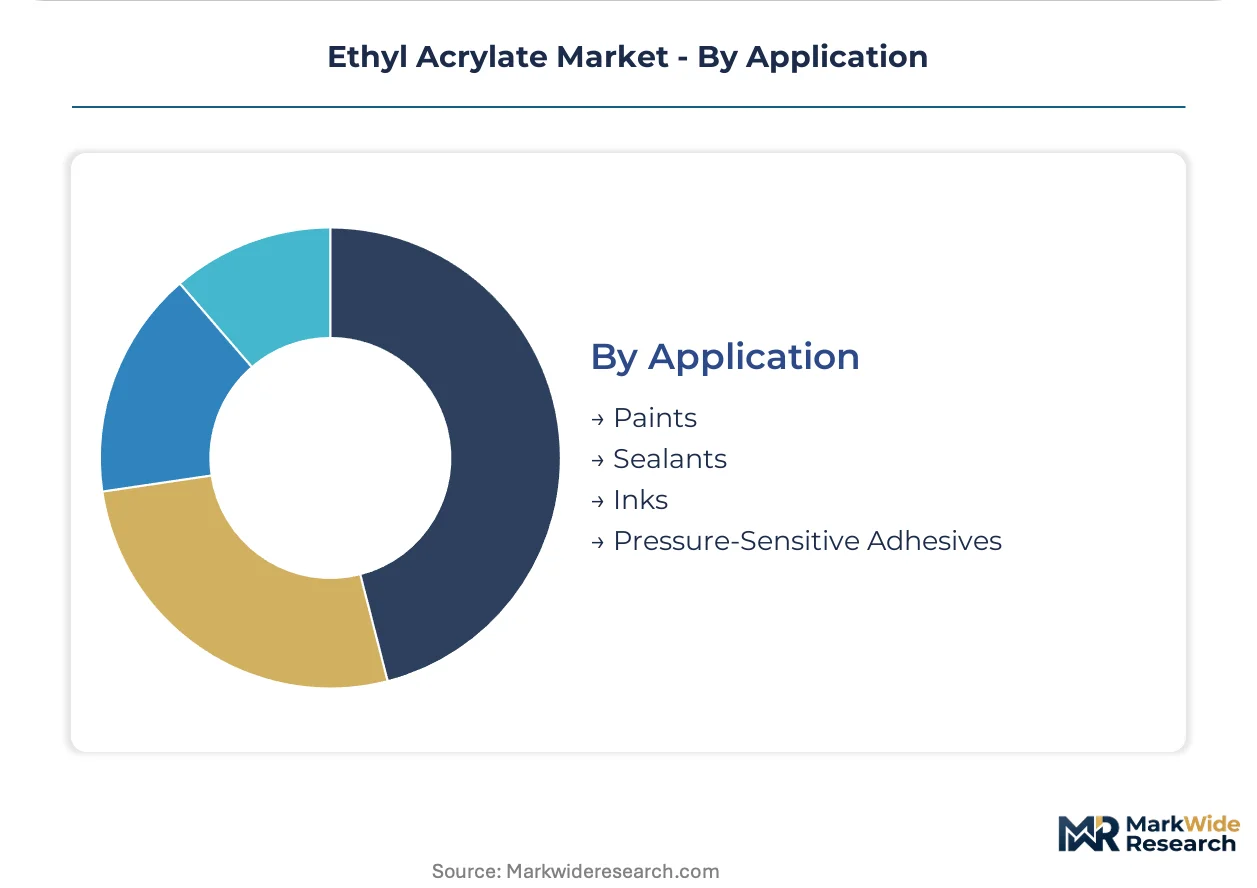
Application:
Customer type stratification separates automotive OEM qualification timelines from merchant market pressure-sensitive adhesive procurement, with specification intensity determining pricing power across application segments.
- Pressure-Sensitive Adhesives:Medical tape, flexible electronics bonding, and automotive trim applications demand tack retention and aging stability that ethyl acrylate copolymers uniquely deliver. Tier-1 formulators in Japan and South Korea consolidate supplier panels around certified ester-grade producers, with qualification protocols spanning 18-36 months that delay substitution even where alternative technologies match technical performance.
- Paints:Architectural and industrial maintenance coatings absorb emulsion-grade volumes as waterborne systems satisfy tightening VOC regulations. Formulation houses across automotive refinishing end uses retool polymerization infrastructure around low-emission acrylic feedstocks.
- Sealants:Construction and automotive seam sealing applications require elastomeric recovery and adhesion to diverse substrates.
- Inks:Flexographic and gravure printing applications compete with polyurethane and nitrocellulose systems on drying speed and substrate adhesion.
Paints anchors the volume base while pressure-sensitive adhesives gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in ethyl acrylate derivatives are redirecting regional production strategies, with net importers accelerating captive acrylic acid integration while established exporters defend position through specialty ester certification programs.
China
East China dominates regional consumption through Jiangsu and Zhejiang province adhesive and coating clusters. MEE enforcement of GB standards on volatile organic compound content redirects domestic formulation toward waterborne acrylic systems. Acrylic acid-ethyl acrylate integration in the Yangtze River Delta supports downstream supply chains with reduced logistics exposure.
United States
Automotive refinishing corridors in Michigan and Ohio absorb rising emulsion-grade volumes as OEMs retool for low-VOC compliance. EPA hazardous air pollutant standards shape facility permitting and emission control investments across the Gulf Coast production corridor. Freeport, Texas anchors North American supply through integrated acrylic acid-ester production infrastructure.
Germany
Waterborne coating formulations expand adoption in automotive refinishing across Bavaria and Baden-Württemberg manufacturing belts. REACH registration obligations filter out smaller import competitors, concentrating compliant supply among integrated producers with toxicology testing capabilities. The Ludwigshafen chemical complex sustains backward integration into specialty ethyl acrylate derivatives.
India
Infrastructure spending and BIS standards adoption create formulation demand for waterborne acrylic sealants and tile adhesives in Maharashtra and Gujarat construction corridors. The country's national chemical regulator enforces quality specifications that redirect procurement toward certified ester-grade producers. Mumbai-Pune industrial clusters accelerate emulsion polymerization capacity additions for architectural coating applications.
Japan
Electronics assembly and medical tape applications in the Kanto and Kansai regions demand tack retention and aging stability that ethyl acrylate copolymers uniquely deliver. METI industrial standards shape specification-driven procurement that compresses qualified supplier lists to certified producers. Tier-1 coating formulators in Tokyo and Osaka consolidate supplier panels around documented impurity profiles.
Ethyl Acrylate Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities, creating a tiered structure where integrated petrochemical conglomerates hold supply security advantages over standalone ester merchants. Three archetypes dominate: backward-integrated acrylic acid producers with captive ethanol supply, specialty ester houses with medical-grade certification infrastructure, and regional merchant suppliers serving price-sensitive textile and construction segments. Capacity expansion and mass-balance certification for bio-attributed pathways represent the dominant competitive moves.
Within the integrated producer tier, BASF SE and Dow Inc. exemplify the capital-heavy archetype that anchors regional supply through captive feedstock control. Arkema S.A. occupies a distinct position among European specialists pursuing differentiation via bio-attributed acrylate pathways. These three entities represent the competitive spectrum from commodity-scale production to sustainability-premium positioning.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries |
| Arkema S.A. |
| Mitsubishi Chemical Corporation |
| Nippon Shokubai Co., Ltd. |
| Formosa Plastics Corporation |
| Merck KGaA |
| Sasol Limited |
| Others |
Value Network & Pricing Analysis
Captive acrylic acid integration at Ludwigshafen and Freeport sustains 15-20% cost advantages over merchant monomer suppliers, compressing price floors for specification-grade ethyl acrylate while elevating barriers for non-integrated competitors in REACH-compliant European markets.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with quarterly price adjustments tied to propylene indices. Price differentiation separates medical-grade certified esters from standard industrial grades through REACH dossier completeness and residual monomer control. Cost compression in commodity emulsion grades is intensifying because East Chinese acrylic acid integration expands regional surplus capacity. Construction chemical distributors exhibit highest price sensitivity, while medical device adhesive manufacturers accept 25-40% premiums for documented batch traceability.
Supply Chain Analysis
Strategic stockpiling of ethanol feedstock and acrylic acid intermediates dominates integrated producer inventory strategy, while merchant buyers maintain just-in-time procurement exposed to propylene volatility. Supply concentrates in Germany, China, and the United States through backward-integrated production corridors. Raw material dependencies rest on propylene oxidation economics, ethanol bio-attribution certification, and sulfuric acid catalyst supply. Single-source vulnerability runs through the Yangtze River Delta acrylic acid cluster. Distribution feeds from integrated resin suppliers directly to tier-1 coating formulators, bypassing merchant chemical distributors for specification-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions expand faster than monomer commodity sales, converting transactional chemical supply into recurring-revenue relationships with automotive and electronics OEMs.
For Market Incumbents: Consolidate supplier panel positions by accelerating mass-balance certification for bio-attributed ester pathways and embedding technical service teams within tier-1 coating formulator R&D facilities. Methacrylate substitution in high-Tg applications threatens premium volume pools; defend through copolymer customization capabilities that methacrylate merchants cannot replicate at scale. For New Entrants and Emerging Players: EU REACH registration fast-tracks for specialty ester grades offer the most penetrable entry point, targeting medical tape and flexible electronics bonding segments where qualification protocols have compressed incumbent supplier lists to three-to-five approved sources per region. Pursue white-label toll manufacturing partnerships with East Chinese acrylic acid complexes to bypass capital-intensive propylene oxidation investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty ester houses with medical-grade certification infrastructure and embedded formulation support contracts. Over the projection horizon, acquisition targets should demonstrate captive acrylic acid integration or exclusive bio-ethanol supply agreements. The inflection signal to monitor is MEE enforcement intensity accelerating waterborne acrylic substitution beyond state-funded infrastructure projects into private commercial construction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive propylene oxidation at Freeport and Ludwigshafen eliminates merchant feedstock exposure and sustains margin compression resilience. |
| Mass-Balance Bio-Attribution Certification | EU Green Deal procurement mandates command premium positioning for bio-ethanol derived esters in sustainable coating specifications. |
| Emulsion Polymerization Capacity Expansion | Guangdong and Shandong province additions redirect domestic Chinese formulation away from solvent-borne alkyd systems. |
| Long-Term Supply Agreement with Tier-1 Formulators | Automotive refinishing OEMs in Bavaria consolidate supplier panels around certified producers with 18-36 month qualification timelines. |
| Technical Service Embedding | On-site formulation support at electronics assembly facilities in Kanto converts commodity monomer sales into sticky recurring relationships. |
Research Methodology
The analysis maps emulsion-grade, adhesive-grade, solution-grade, and film-grade supply tiers, each validated through procurement directors at coating formulators, plant managers at integrated acrylic acid complexes, and distribution channel partners across Germany, China, and the United States. Primary interview intelligence triangulates against customs trade data, Cefic and ACC industry reports, SEC 10-K chemical segment disclosures, and MEE regulatory enforcement records. Bottom-up capacity and consumption estimates reconcile with top-down market value reconstruction.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models grade tier, end-use industry, polymerization technology, and regional production hub segmentation. CAGRs derive from demand elasticity modeling against propylene price scenarios and regulatory enforcement intensity indices. Industry-specific inputs include automotive OEM coating qualification timeline distributions and medical device adhesive extractables compliance audit frequencies.
Underlying assumptions cover REACH registration maintenance, MEE GB standard enforcement continuity, and propylene supply elasticity from naphtha cracking, with deviation risk concentrated in carbon border adjustment mechanism implementation timing and bio-ethanol feedstock cost parity. Revision becomes warranted when acrylic acid-ethyl acrylate integration rates in East China exceed baseline capacity absorption assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Biobased Degreaser Market