
 Joint Sealants Market | 2026-2036
Joint Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Joint Sealants Market Analysis
Specialized polymer chemist availability is rotating toward Asia-Pacific manufacturing hubs, constraining formulation innovation cycles in Western Europe. Sika AG leverages its Swiss R&D base to sustain premium silicone development for facade applications. Dow Inc. anchors North American supply through integrated siloxane production at its Midland, Michigan complex. Henkel AG & Co. KGaA competes in automotive OEM channels with polyurethane systems engineered for thermal cycling resistance.
Joint sealants are elastomeric compounds formulated from silicone, polyurethane, acrylic, or bituminous polymers, typically exhibiting Shore A hardness between 15 and 50 and movement accommodation factors exceeding 25 percent; they function to block air, moisture, and contaminants across dynamic building or vehicular joints. Silicone commands the largest share of specification-grade construction demand due to UV stability and 20-plus-year service life in curtainwall applications. Polyurethane leads automotive and marine segments where paintability and structural adhesion to primed metal surfaces prove critical. Bituminous formulations occupy maintenance-driven waterproofing tunnels and below-grade infrastructure with lowest installed cost but narrow temperature performance windows.
REACH restrictions on volatile organic compounds and EU Green Deal embodied-carbon thresholds for construction materials are tightening formulation requirements across European supply chains. The US EPA and OSHA jointly enforce worker exposure limits during sealant installation in confined building envelopes. FDA food-contact regulations govern silicone sealants deployed in commercial kitchen and food processing facility joints. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that threaten incumbent silicone cure systems and evaluate bio-based polymer alternatives before specification standards harden.
Market Dynamics
EU Green Deal embodied-carbon thresholds are forcing formulation redesigns across European construction supply chains, compressing innovation cycles for incumbent silicone and polyurethane systems while opening specification windows for bio-based alternatives.
Growth Catalysts
- Renovation Wave mandates:EU Green Deal building performance standards require facade energy retrofits across Germany, France, and Italy. Specification-grade silicone procurement is accelerating for curtainwall joint replacement.
- Automotive lightweighting:Polyurethane structural bonding systems are capturing share in electric vehicle battery enclosure assembly. OEM thermal cycling specifications now exceed prior internal combustion requirements.
- China:Dual carbon goals and GB standards for green building materials are creating certified product demand in tier-one city commercial construction pipelines.
Market Restraints
- Siloxane feedstock concentration:Integrated siloxane production clusters in the US and China control upstream monomer supply. European formulators face margin compression during feedstock allocation cycles.
- REACH VOC restrictions:ECHA enforcement of volatile organic compound limits in construction sealants is eliminating solvent-borne acrylic formulations from specification-grade tendering.
- Technical service life gaps:Bio-based polymer alternatives currently demonstrate 10-15 year durability in accelerated weathering tests versus 20-plus-year silicone benchmarks.
Strategic Opportunities
- India:BIS certification gaps in high-performance facade sealants create first-mover positioning for specification-grade silicone suppliers in Mumbai and Delhi commercial towers.
- Modular construction:Factory-applied joint sealing in offsite building manufacturing is shifting quality control liability from site contractors to sealant producers.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit PFAS in cure systems are accelerating fluorine-free catalyst development programs.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation talent is migrating to Asia-Pacific manufacturing hubs. Western European R&D teams face recruitment bottlenecks for silicone innovation.
- Certification timeline compression:EU Green Deal performance standards are updating faster than EN 15651-1 test protocol revision cycles. Validated product data lags specification requirement shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Joint Sealants Market |
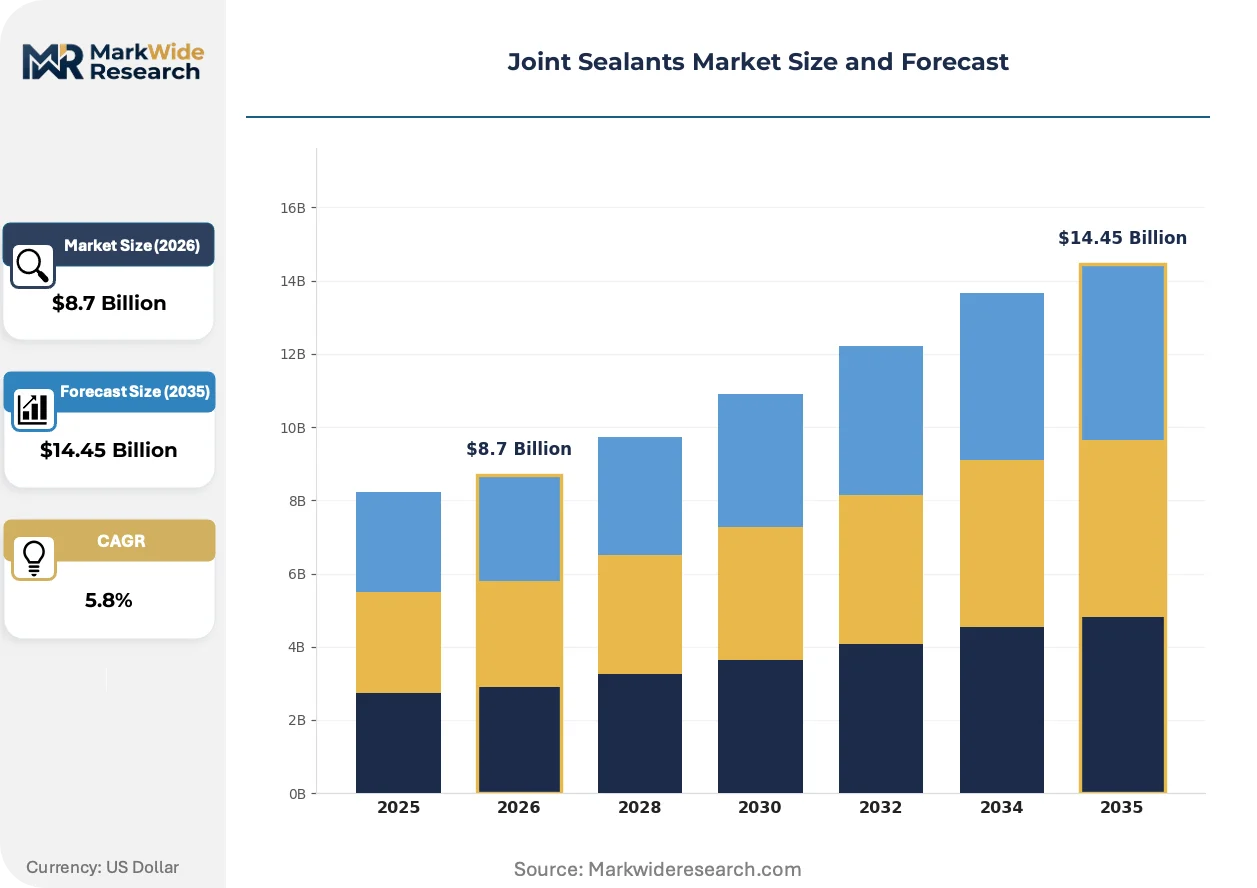
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Bituminous Application: Construction, Automotive, Aerospace, Marine End User: Contractors, Manufacturers, Consumers, Maintenance Providers Distribution Channel: Retail, Online, Distributors, Wholesale |
| Companies Covered | Dow Inc., MAPEI S.p.A., Sika AG, Pidilite Industries Limited, RPM International Inc., 3M, Wacker Chemie AG, ITW Performance Polymer, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Joint Sealants Market Emerging Trajectories
Formulation chemistry is pivoting toward lower-carbon cure systems and modular-compatible application methods, driven by regulatory pressure and construction productivity demands.
Hybrid silyl-terminated polyurethane technology is displacing conventional two-component polyurethane in structural glazing applications. European facade contractors are adopting single-component cartridges for high-rise installation efficiency. The technology is displacing established two-part mixing protocols and reducing site labor hours per linear meter.
REACH restrictions on volatile organic compounds are eliminating solvent-borne systems from tender eligibility. ECHA enforcement is narrowing formulation latitude for acrylic construction sealants. German and French commercial contractors are now specifying 100% solids silicone and MS polymer alternatives exclusively.
Direct procurement from sealant manufacturers is consolidating distributor intermediaries in large commercial construction. Tier-one general contractors in Germany are establishing frame agreements with Sika AG and Dow Inc. for specification-grade supply. This channel compression is most visible in Frankfurt and Munich tower projects exceeding 50,000 square meters of facade area.
Joint Sealants Market Segmentation
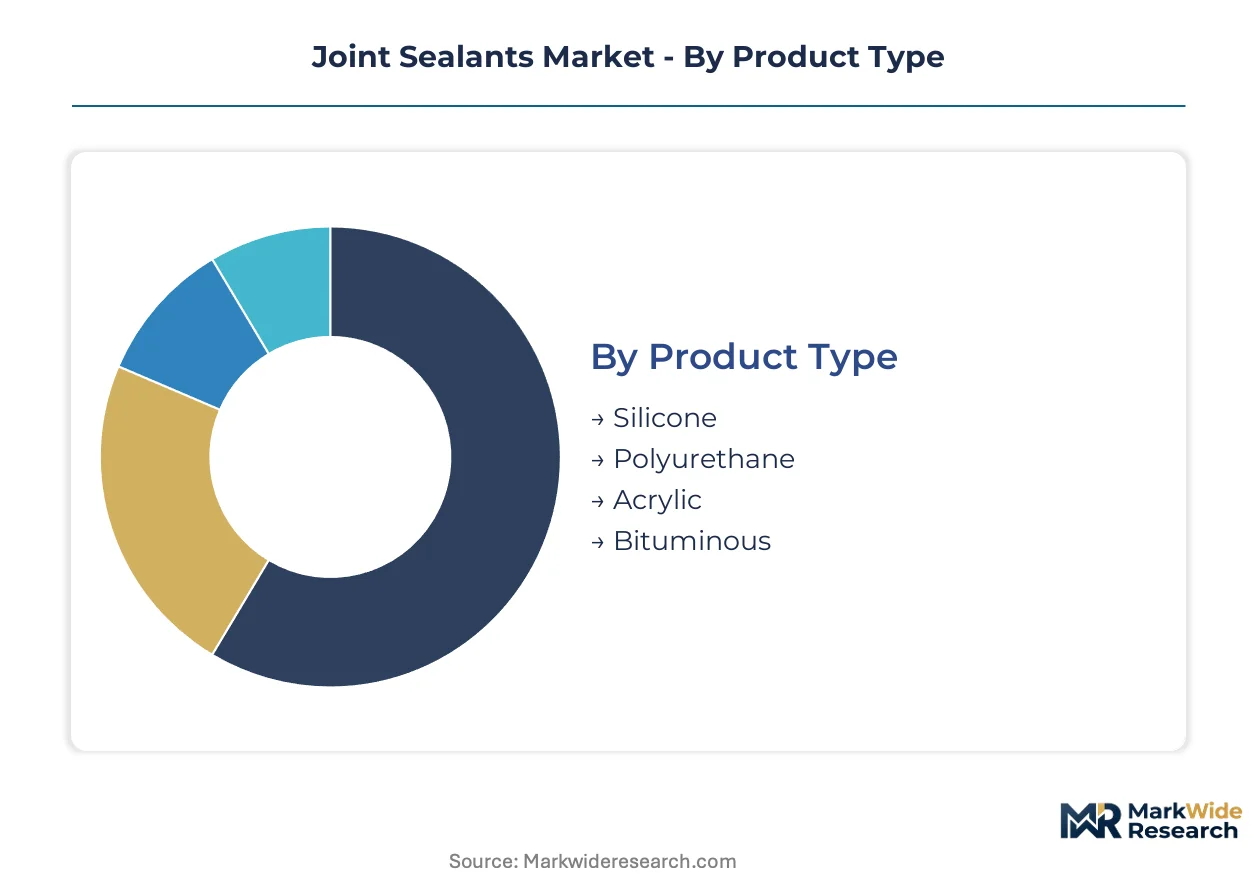
Joint sealant procurement patterns diverge sharply across formulation chemistry, installation setting, and buyer sophistication. Specification-grade tendering in commercial construction rewards certified performance data, while automotive OEM channels prioritize thermal cycling validation and paint compatibility.
Product Type:
Margin pools concentrate in silicone formulations where UV stability and movement accommodation command specification premiums in facade retrofit pipelines.
- Silicone:Elastomeric systems formulated from siloxane polymers exhibit Shore A hardness of 20-40 and accommodate joint movement exceeding 25 percent. Demand concentrates in German and French curtainwall renovation projects driven by EU Green Deal embodied-carbon thresholds for building envelopes.
- Polyurethane:Two-component and hybrid silyl-terminated systems bond primed metal surfaces with structural adhesion strength. Automotive battery enclosure assembly in electric vehicle platforms is rotating procurement toward thermal cycling-resistant grades.
- Acrylic:Water-borne emulsions serve interior caulking and paintable finishing applications with lower installed cost but narrower temperature performance windows.
- Bituminous:Solvent-based and modified asphalt formulations occupy below-grade waterproofing tunnels and maintenance-driven infrastructure with lowest material cost but 10-year service life benchmarks.
Silicone holds installed capacity. Polyurethane is rotating up the share rankings.
Application:
Volume concentration sits with construction, though automotive specifications are tightening faster than EN test protocol cycles can validate.
- Construction:Facade glazing, expansion joint sealing, and waterproofing membranes represent the dominant procurement channel. German commercial contractors are establishing direct frame agreements with formulators for projects exceeding 50,000 square meters of envelope area.
- Automotive:Structural bonding in battery enclosures and lightweight body-in-white assembly demands thermal cycling resistance beyond prior internal combustion specifications. OEM validation timelines now stretch 18-24 months for new sealant qualifications.
- Aerospace:Fuel-resistant polysulfide and fluorosilicone grades seal airframe joints and fuel tank cavities under FAA airworthiness directives.
- Marine:Polyurethane and polysulfide systems resist saltwater immersion and deck flexing in hull sealing and superstructure applications.
Construction retains volume leadership. Automotive is climbing the fastest on specification intensity.
End User:
Procurement authority is consolidating toward contractors with certified installation crews and direct manufacturer relationships.
- Contractors:Commercial facade specialists in Frankfurt and Munich tower projects are absorbing quality control liability previously held by distributor intermediaries. REACH-compliant silicone procurement is now mandatory for EU Green Deal tender eligibility.
- Manufacturers:Automotive OEMs and tier-one suppliers validate sealant performance through 10,000-cycle thermal shock protocols. Battery enclosure bonding specifications exceed prior underhood requirements.
- Consumers:DIY retail channels move standard-grade acrylic and silicone cartridges for residential window and bathroom sealing.
- Maintenance Providers:Infrastructure asset managers specify bituminous and polyurethane injection systems for tunnel and bridge joint rehabilitation.
Contractors hold specification authority. Manufacturers are gaining procurement sophistication fastest.
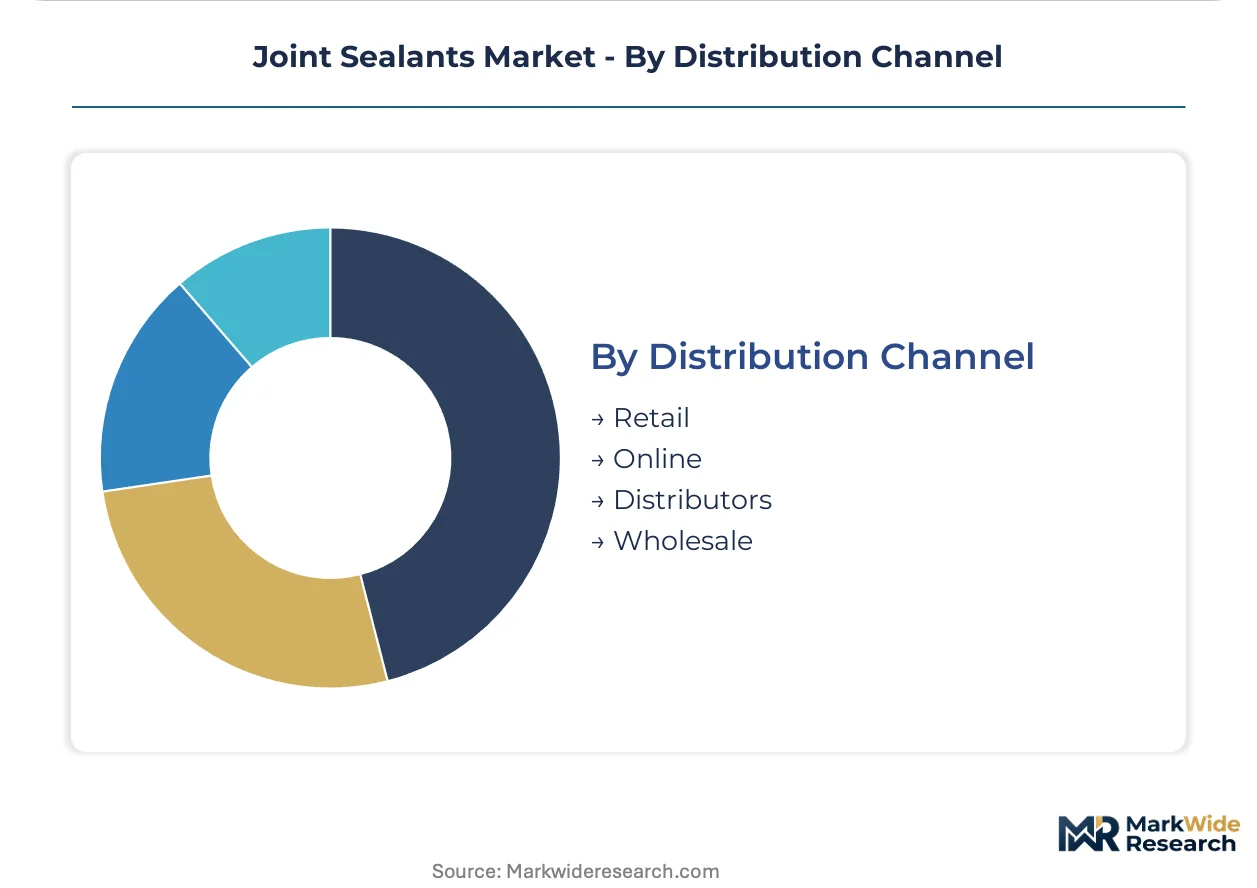
Distribution Channel:
Channel compression is eliminating intermediary margins in large commercial construction while digital procurement penetrates standard-grade segments.
- Retail:Home improvement chains stock consumer-grade silicone and acrylic cartridges for residential repair and renovation. Shelf space allocation favors 100% solids formulations as REACH solvent restrictions tighten.
- Online:E-commerce platforms are capturing specification-grade procurement for maintenance providers and small contractors seeking technical data sheet accessibility without distributor markup.
- Distributors:Regional building material distributors retain logistics value for mid-size contractors but lose share to direct manufacturer agreements in tier-one commercial projects.
- Wholesale:Volume procurement cooperatives serve national contractor chains with consolidated silicone and polyurethane drum deliveries.
Distributors retain logistics infrastructure. Online is expanding most quickly in technical data accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embodied-carbon thresholds anchor European procurement patterns. German and French commercial contractors now mandate REACH-compliant silicone formulations for facade renovation tenders. Specification-grade sealant demand concentrates where building performance standards tighten fastest.
Germany
Frankfurt and Munich tower projects exceeding 50,000 square meters drive specification-grade silicone procurement. EU Green Deal building performance standards require curtainwall joint replacement across commercial portfolios. Bavarian facade contractors are absorbing quality control liability previously held by distributor intermediaries.
France
Paris commercial renovation pipelines are expanding under tightened embodied-carbon thresholds for building envelopes. ECHA enforcement of REACH VOC limits is eliminating solvent-borne acrylic formulations from tender eligibility. Île-de-France contractors now specify 100% solids silicone and MS polymer alternatives exclusively.
United States
EPA and OSHA jointly enforce worker exposure limits during sealant installation in confined building envelopes. Midland, Michigan anchors integrated siloxane production clusters that control upstream monomer supply. Commercial construction in Texas and California rotates procurement toward certified performance data for high-rise glazing applications.
China
Dual carbon goals and GB standards for green building materials create certified product demand in tier-one city commercial construction. Shanghai and Beijing facade retrofit pipelines are absorbing specification-grade silicone volumes. MIIT enforcement of building material carbon intensity metrics is compressing formulation innovation cycles for incumbent systems.
India
BIS certification gaps in high-performance facade sealants create first-mover positioning for specification-grade suppliers. Mumbai and Delhi commercial towers are rotating procurement toward certified silicone systems for curtainwall applications. CDSCO-aligned quality benchmarks are tightening as green building codes penetrate tier-one construction markets.
Joint Sealants Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier. Consolidated siloxane production clusters in the US and China control upstream monomer supply, compressing margins for European formulators during feedstock allocation cycles. Two strategic archetypes dominate: vertically integrated chemical conglomerates with captive siloxane supply, and formulation specialists leveraging regional R&D proximity to specification-grade demand. Competitive moves concentrate on direct frame agreements with tier-one contractors and fluorine-free catalyst development programs.
Within the integrated chemical tier, Dow Inc. and Wacker Chemie AG exemplify upstream control over siloxane monomer production. Sika AG occupies a position representing Swiss-based R&D proximity to Western European facade specification pipelines. Among Asia-Pacific-exposed specialists, Pidilite Industries Limited anchors the specialist tier serving emerging market construction growth.
| Leading Market Players |
|---|
| Dow Inc. |
| MAPEI S.p.A. |
| Sika AG |
| Pidilite Industries Limited |
| RPM International Inc. |
| 3M |
| Wacker Chemie AG |
| ITW Performance Polymer |
| Henkel AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Hybrid silyl-terminated polyurethane substitution for conventional two-component systems is redrawing procurement economics, compressing site labor costs while concentrating formulation value capture with integrated producers in Germany and the United States. This chemistry migration simultaneously shortens supply chains to cartridge-ready single-component formats and elevates price premiums for technical service bundling.
Pricing Analysis
Price spreads between specification-grade silicone in Frankfurt and standard acrylic in Mumbai exceed material cost differentials by certification tier alone. Three-tier pricing structure across premium silicone, standard polyurethane, and economy bituminous levels anchors construction procurement, with ECHA REACH compliance and EN 15651-1 certification as primary price differentiation drivers. Cost compression in solvent-borne acrylic tiers is intensifying because ECHA VOC enforcement eliminates tender eligibility. Maintenance providers exhibit highest price sensitivity; facade contractors with direct manufacturer frame agreements show lowest.
Supply Chain Analysis
Siloxane monomer chokepoints at Midland, Michigan and Zhangjiagang, China tether European formulators to allocation cycles beyond their control. Upstream concentration in the United States and China draws from methyl chloride and silicon metal feedstocks, with formulation finishing dispersed across Switzerland, Germany, and Italy. Single-source vulnerability in specialty catalyst supply threatens fluorine-free cure system timelines. Distribution runs through direct frame agreements for tier-one commercial projects and regional distributors for mid-scale contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The joint sealants market functions as a service-attach opportunity where technical consultation and certified installation training expand faster than commodity cartridge volumes, particularly in EU Green Deal-driven facade retrofit pipelines.
For Market Incumbents: Secure captive siloxane supply through backward integration or long-term offtake agreements with Midland and Zhangjiagang producers to defend margin position against feedstock allocation volatility. Accelerate fluorine-free catalyst R&D programs before ECHA PFAS restrictions harden specification requirements. Channel control through direct frame agreements with Bavarian and Île-de-France contractors remains essential.
For New Entrants and Emerging Players: Anchor in Indian BIS certification gaps for high-performance facade sealants, where Mumbai and Delhi commercial towers lack validated domestic suppliers. Target specification-grade silicone procurement in tier-one Chinese cities where GB green building standards outpace local formulation capability. Pursue digital-first technical data accessibility to bypass distributor markups in maintenance provider segments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European formulation specialists lacking upstream siloxane integration. Five-to-ten year viability hinges on REACH compliance cost absorption and modular construction channel positioning. Watch for ECHA PFAS restriction finalization as inflection signal for fluorine-free catalyst acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomers | Midland and Zhangjiagang production clusters control upstream supply for specification-grade silicone. |
| Fluorine-Free Catalyst Development Program | ECHA PFAS proposals threaten incumbent cure systems in European facade applications. |
| Direct Frame Agreement with Tier-One Contractors | Bavarian and Île-de-France facade specialists now absorb quality control liability from distributors. |
| Modular Construction Channel Certification | Factory-applied sealing shifts liability from site contractors to sealant producers in offsite manufacturing. |
| BIS Certification Investment for Indian Market Entry | Mumbai and Delhi commercial towers lack validated high-performance domestic sealant suppliers. |
Methodological Framework
A spread of perspectives from facade contractors, automotive OEM procurement leads, polymer R&D directors, and building materials distributors converged on the working assumptions underlying this analysis. Primary interviews with EN 15651-1 test protocol specialists and ECHA regulatory affairs consultants combined with secondary validation from SEC 10-K filings, Cefic construction chemicals reports, and customs trade data for siloxane monomer flows. Bottom-up project pipeline assessments and top-down chemical industry aggregates underwent triangulation for convergence.
Segmentation dimensions modeled span formulation chemistry, installation setting, and buyer sophistication across the projection horizon. Grade tier, end-use industry, and regional regulatory cluster shaped volume and value outputs. CAGRs derived from historical elasticity analysis applied to renovation wave mandates and automotive lightweighting content-per-vehicle trajectories. Forecast inputs incorporated EU Green Deal embodied-carbon threshold implementation pacing and MIIT dual carbon enforcement intensity.
Decision-makers should treat outputs as directional under sustained REACH enforcement and modular construction adoption assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA PFAS restriction timelines and China GB standard certification pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Global EVA Adhesives Market