
 Asia-Pacific Automotive Adhesives and Sealants Market | 2026-2036
Asia-Pacific Automotive Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Adhesives and Sealants Market Outlook
Direct supply agreements between adhesive formulators and EV battery pack manufacturers are reshaping procurement channels across the Asia-Pacific region. Henkel AG & Co. KGaA leverages its reactive polyurethane portfolio to secure tier-1 supplier relationships with Korean and Japanese battery producers. Sika AG anchors its position through specialized structural bonding solutions for aluminum-intensive vehicle platforms. H.B. Fuller Company competes via water-based technology leadership aimed at Southeast Asian assembly plants seeking lower-VOC compliance pathways.
Asia-Pacific automotive adhesives and sealants comprise formulated polymer systems—typically polyurethane, epoxy, silicone, or acrylic chemistries cured through moisture, heat, or UV activation—that create structural bonds, environmental seals, or thermal management interfaces between dissimilar vehicle substrates. These materials replace mechanical fasteners in multi-material body-in-white construction, achieving continuous load distribution while reducing assembled mass by eliminating weld points and bolted joints. Polyurethane dominates body structural applications due to its crash-durable flexibility and adhesion to coated metals, while silicone leads exterior sealing where thermal cycling resistance and UV stability determine warranty performance. Water-based technology commands expanding share among interior applications as cabin air quality regulations tighten across the region, though solvent-based systems retain footholds in electronics potting where rapid processing and dielectric properties remain critical.
China's MIIT enforces GB standards for passenger vehicle interior air quality that directly limit volatile organic compound emissions from adhesive systems, while Japan's METI promotes JIS-certified materials through green procurement guidelines affecting supplier qualification. South Korea's MFDS and KATRI coordinate on automotive chemical substance notification requirements that shape import compliance costs for non-domestic formulators. Stakeholders must monitor how China's SAMR evolves its dual carbon implementation rules for automotive supply chains, as carbon intensity accounting will increasingly determine adhesive specification decisions in regional sourcing contracts.
Market Dynamics
China's dual carbon goals and Japan's tightening vehicle emissions standards are forcing automakers toward adhesive-intensive multi-material designs that eliminate weld points and reduce mass. Direct supply agreements between adhesive formulators and EV battery pack manufacturers are compressing traditional tiered procurement channels across the region.
Growth Catalysts
- MIIT GB Standards:China's passenger vehicle interior air quality regulations mandate low-VOC adhesive systems, creating specification pull-through for compliant formulators in the Yangtze River Delta cluster.
- Aluminum-Intensive Platforms:Structural bonding solutions for multi-material body-in-white construction are displacing mechanical fasteners as OEMs pursue crash-durable continuous load distribution.
- Reactive Polyurethane Chemistry:Korean and Japanese battery producers specify moisture-cured systems for pack assembly, generating dedicated supply line investments from regional formulators.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane precursor costs fluctuate with regional propylene oxide supply, compressing margin stability for formulators serving price-sensitive Southeast Asian assembly plants.
- Import Compliance Burden:South Korea's MFDS and KATRI chemical substance notification requirements impose documentation costs on non-domestic suppliers that domestic competitors avoid.
- Mechanical Fastener Persistence:Solvent-based electronics potting retains footholds in high-volume connector sealing where rapid processing speed outweighs adhesive conversion benefits.
Strategic Opportunities
- Thai and Indonesian Assembly Expansion:Southeast Asian plants seeking lower-VOC compliance pathways present white space for water-based technology leadership as regional production scales.
- SAMR Carbon Intensity Accounting:China's evolving dual carbon implementation rules for automotive supply chains will increasingly determine adhesive specification decisions in regional sourcing contracts.
- Thermal Management Interface Bonding:Convergence of silicone sealant chemistry with battery thermal runaway protection systems creates new specification categories for exterior-grade UV-stable formulations.
Industry Challenges
- Multi-Substrate Compatibility Expertise:Formulators lack sufficient technical personnel trained in adhesion science for coated metals, composites, and aluminum alloys in combined assembly sequences.
- JIS Certification Timeline Compression:Japan's METI green procurement guidelines require accelerated supplier qualification cycles that strain R&D-to-production handoff capabilities.
- Legacy Equipment Retrofit Costs:Water-based system conversion demands capital expenditure for humidity-controlled dispensing infrastructure that mid-tier suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Adhesives and Sealants Market |
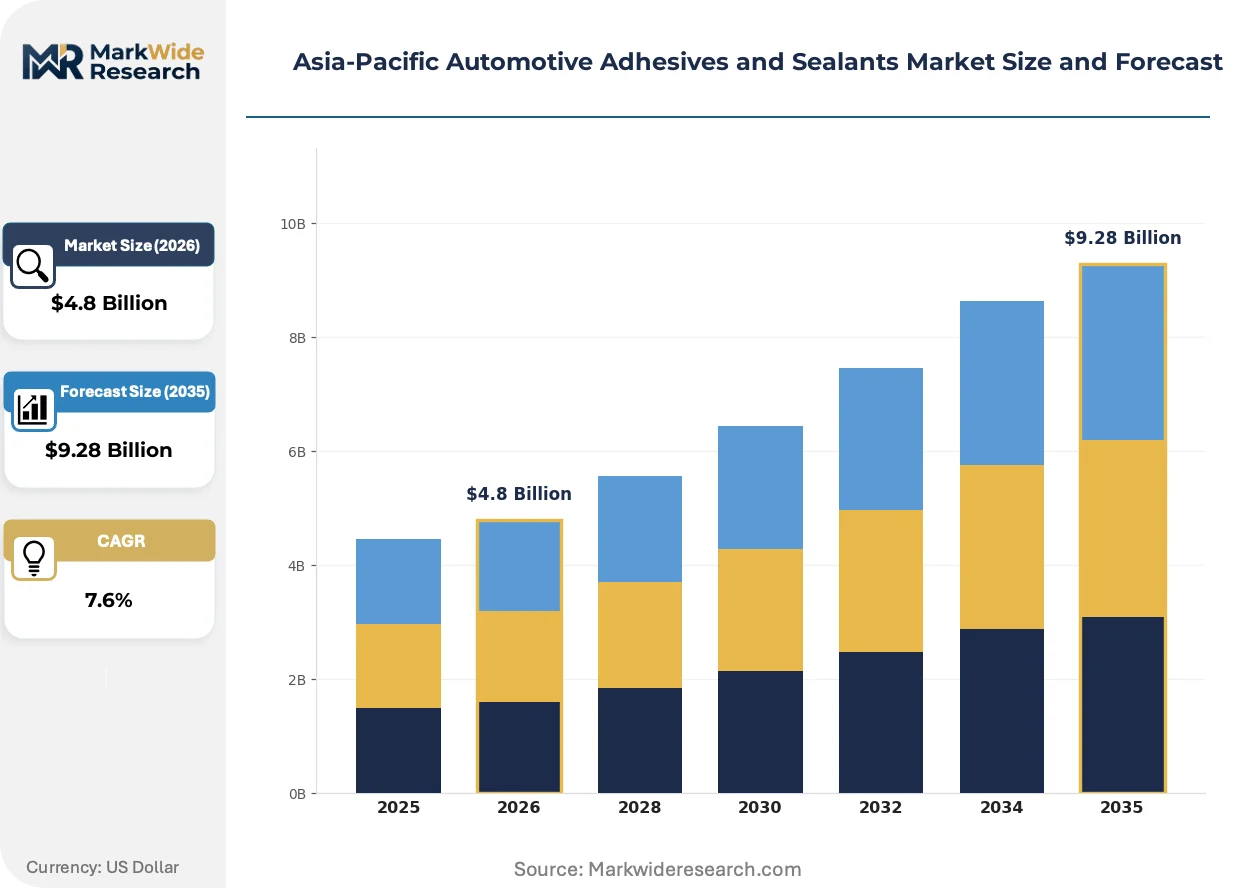
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Body Structural, Interior, Exterior, Electronics End User: OEMs, Aftermarket, Tier-1 Suppliers, Workshops Technology: Solvent-Based, Water-Based, Hot Melt, Reactive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Arkema, BASF SE, Dow Inc., Hubei Huitian New Materials Co., Ltd., Nitto Denko Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Adhesives and Sealants Market Strategic Shifts
Digital process control and predictive curing systems are reshaping how adhesive bonds are specified, monitored, and warranted across Asia-Pacific vehicle assembly. Formulators now compete on data integration capabilities as much as chemistry performance.
UV-activated acrylic chemistry is digitizing quality assurance protocols in Japanese and Korean electronics potting operations. Tier-1 suppliers deploy in-line spectroscopic monitoring to verify cure completion in real time. This capability is compressing warranty exposure for high-reliability connector sealing while reducing offline inspection labor.
METI's green procurement guidelines and China's SAMR dual carbon rules are mandating supply chain carbon intensity disclosure for automotive materials. Formulators must now document cradle-to-gate emissions for every specified product. Adhesive systems with verified low-carbon feedstock sourcing command qualification preference in Japanese OEM supplier scorecards.
Battery pack manufacturers now specify adhesive systems through direct technical partnerships rather than tier-2 nomination. This disintermediation concentrates purchasing influence with Korean and Chinese cell producers who dictate chemistry selection. Southeast Asian module assemblers respond by developing captive formulation capabilities to retain margin capture.
Asia-Pacific Automotive Adhesives and Sealants Market Segmentation
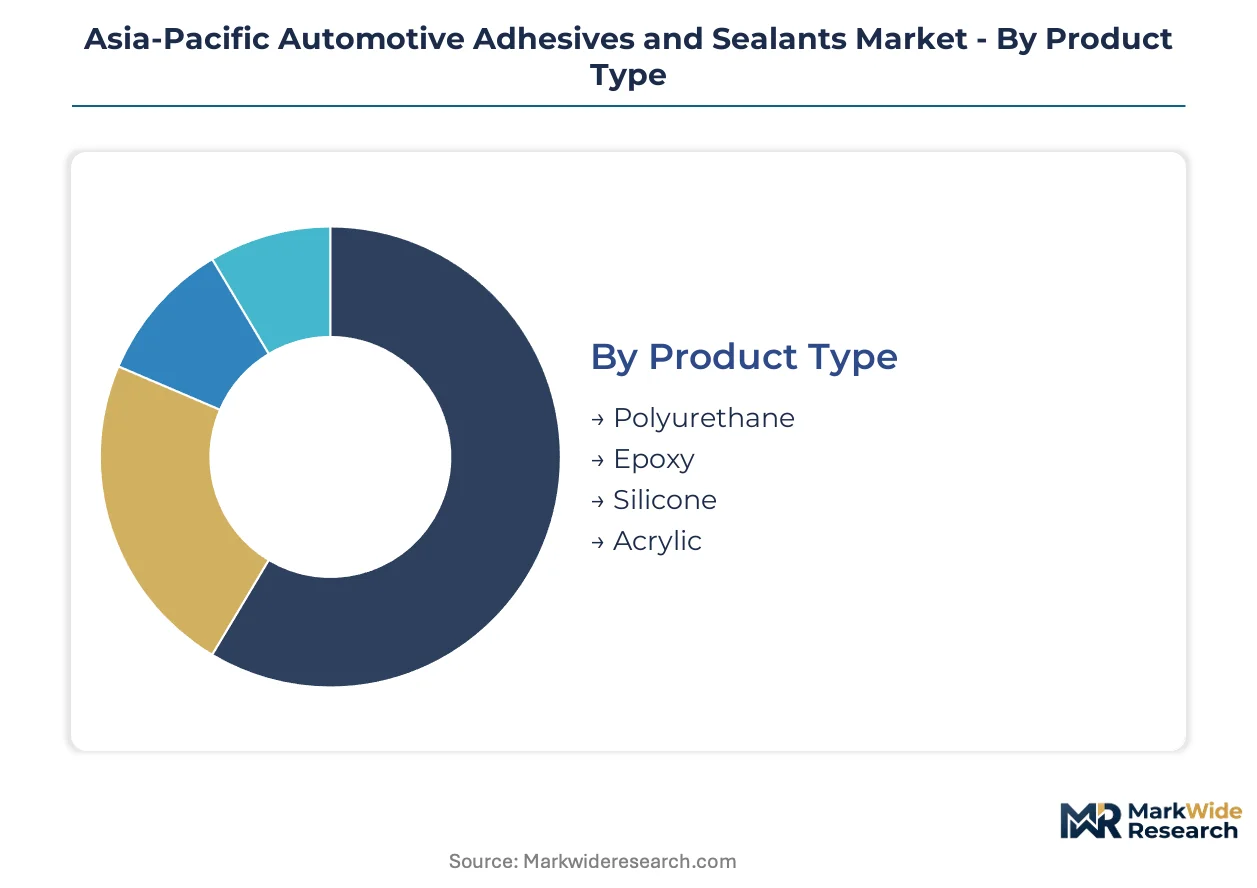
Segmentation in the Asia-Pacific automotive adhesives and sealants market reveals how procurement channels, technical specifications, and regulatory compliance requirements diverge across customer types and application environments. Understanding these divides clarifies where formulators must build distinct capabilities versus where scale economies apply.
Product Type:
After-sales service intensity varies sharply across chemistry platforms, with structural grades demanding technical field support while commodity sealants rely on distributor inventory.
- Polyurethane:Moisture-cured or two-component systems dominate body-in-white structural bonding for their crash-durable flexibility and adhesion to coated metals. Demand concentrates in China's Yangtze River Delta EV cluster, where OEMs specify continuous load distribution for aluminum-intensive platforms.
- Silicone:RTV and heat-cured formulations provide thermal cycling resistance and UV stability for exterior sealing applications. Korean battery pack manufacturers specify exterior-grade silicone for thermal runaway protection interfaces, creating dedicated specification categories.
- Epoxy:Rigid, high-strength systems serve electronics potting and underhood applications requiring dielectric properties and chemical resistance.
- Acrylic:UV-activated chemistry enables rapid processing in Japanese and Korean electronics operations with in-line spectroscopic cure verification.
Polyurethane holds the largest share; momentum sits with silicone as thermal management applications expand.
Application:
Cost tier differentiation separates specification-grade structural systems from commodity interior adhesives, with price multiples reaching three to five times between categories.
- Body Structural:High-performance bonding solutions replace mechanical fasteners in multi-material construction, achieving mass reduction through elimination of weld points. Chinese OEMs pursuing MIIT emissions compliance drive specification intensity for crash-durable formulations.
- Electronics:Potting and encapsulation systems protect connectors and control modules from moisture, vibration, and thermal shock. Japanese tier-1 suppliers deploy predictive curing systems with real-time quality assurance to compress warranty exposure.
- Interior:Water-based and low-VOC systems dominate cabin applications as GB standards tighten on passenger air quality across Chinese provinces.
- Exterior:Weatherstrip bonding and seam sealing require UV-stable, paint-compatible formulations with extended durability warranties.
Body structural commands premium pricing; electronics represents the fastest-expanding application as vehicle electrical architectures densify.
End User:
Volume concentration among battery pack producers is restructuring traditional tiered supply relationships across the region.
- OEMs:Direct technical partnerships with adhesive formulators for platform-specific structural bonding specifications, particularly among Chinese and Japanese EV manufacturers.
- Tier-1 Suppliers:Module assemblers and system integrators serving as specification gatekeepers for interior and exterior applications, though their influence is compressing in battery-related categories.
- Aftermarket:Collision repair and refurbishment channels requiring color-matched, rapid-cure systems compatible with existing paint processes.
- Workshops:Independent service providers sourcing through distributor networks for maintenance sealing and minor repair applications.
OEMs dominate value capture; tier-1 suppliers face margin pressure as direct formulator-to-cell-producer agreements proliferate.
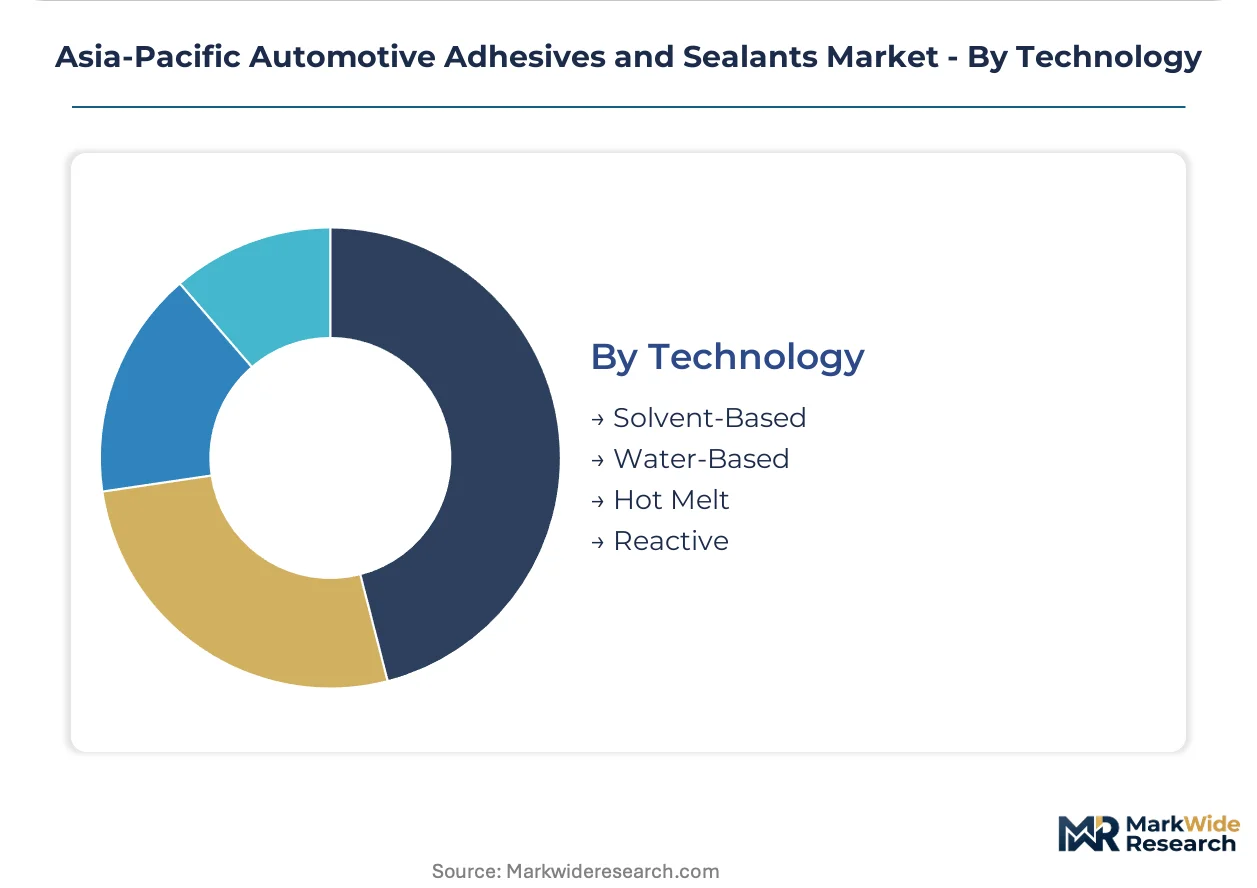
Technology:
Supply concentration among Korean and Japanese formulators in reactive systems contrasts with fragmented Southeast Asian production of water-based alternatives.
- Reactive:Moisture-cured polyurethane and heat-activated epoxy systems specified for structural and battery applications where cure kinetics determine throughput. Korean producers anchor regional supply for moisture-cured battery pack assembly systems.
- Water-Based:Acrylic and polyurethane dispersions serving interior applications and Southeast Asian assembly plants seeking lower-VOC compliance pathways without solvent recovery infrastructure.
- Solvent-Based:Rapid-processing systems retaining footholds in electronics potting where dielectric properties and speed outweigh conversion benefits, despite regulatory pressure from China's MEE.
- Hot Melt:Thermoplastic systems for interior trim attachment and carpet bonding, valued for instant handling strength and elimination of fixture time.
Reactive technology leads in value terms; water-based formulations are climbing fastest as Thai and Indonesian capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors the region's adhesive supply chain, handling bulk chemical imports that feed formulator plants across the Yangtze River Delta while connecting Korean and Japanese battery producers to Chinese substrate suppliers.
China
MIIT's GB standards for passenger vehicle interior air quality mandate low-VOC adhesive specifications across EV platforms. SAMR's evolving dual carbon implementation rules now require cradle-to-gate emissions disclosure from automotive material suppliers. The Yangtze River Delta cluster concentrates demand as BYD, NIO, and Tesla Shanghai scale aluminum-intensive body-in-white production requiring structural polyurethane bonding systems.
Japan
Japanese OEMs specify adhesive systems through direct technical partnerships rather than traditional tier-2 nomination channels. METI's green procurement guidelines accelerate JIS certification timelines for supplier qualification. The Nagoya-Toyota corridor hosts specialized formulator R&D facilities serving Lexus and Toyota's multi-material platform strategies with predictive curing system integration.
South Korea
LG Energy Solution and Samsung SDI dictate chemistry selection through direct formulator agreements for battery pack assembly. MFDS and KATRI coordinate chemical substance notification requirements that impose documentation costs on non-domestic suppliers. The Ulsan-Busan industrial belt concentrates moisture-cured polyurethane demand for cell-to-pack bonding applications.
Thailand
Thai assembly plants serving Japanese OEM exports seek water-based technology pathways to meet lower-VOC compliance without solvent recovery infrastructure. The country's Board of Investment incentives attract adhesive formulator capacity expansion for regional supply. The Eastern Economic Corridor hosts expanding module assembly operations developing captive formulation capabilities to retain margin capture.
India
Maruti Suzuki and Tata Motors drive specification intensity for structural bonding as domestic EV production scales. The country's automotive research associations coordinate with BIS on evolving material standards for multi-material construction. The Chennai-Bengaluru corridor concentrates tier-1 supplier investment in humidity-controlled dispensing infrastructure for water-based system conversion.
Asia-Pacific Automotive Adhesives and Sealants Market Competitive Environment
On the supply side, the industry is consolidating around chemistry specialists with direct OEM technical partnerships and battery producer supply agreements. Three archetypes dominate: diversified chemical conglomerates with automotive divisions, pure-play adhesive formulators with reactive system expertise, and regional specialists serving cost-sensitive assembly plants. Competitive moves concentrate on strategic partnerships with cell producers and geographic expansion into Southeast Asian manufacturing zones.
Within the diversified chemical tier, 3M and BASF SE exemplify scale-driven players leveraging broad polymer portfolios across multiple automotive applications. Henkel AG & Co. KGaA and Sika AG occupy positions as pure-play specialists, with the former anchoring reactive polyurethane supply relationships and the latter representing structural bonding expertise for aluminum-intensive platforms. H.B. Fuller Company sits within the regional adaptation archetype, its water-based technology leadership targeting Southeast Asian compliance pathways.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Arkema |
| BASF SE |
| Dow Inc. |
| Hubei Huitian New Materials Co., Ltd. |
| Nitto Denko Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Nagoya container corridor funnels propylene oxide derivatives and formulated adhesives across the East China Sea, its freight cost volatility compressing margin buffers for Korean battery pack assemblers while amplifying price spreads between reactive polyurethane grades and commodity water-based alternatives. Chinese EV OEMs exploit Yangtze River Delta supply concentration to extract volume concessions on structural bonding systems, whereas Thai and Indonesian plants absorb logistics premiums that widen their cost disadvantage against integrated regional formulators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with JIS-certified structural polyurethanes commanding certification premiums over GB-compliant interior grades and unbranded Southeast Asian water-based alternatives. Price differentiation hinges on MIIT emissions certification tier and direct OEM technical partnership status, with qualified suppliers capturing margin premiums unavailable to distributor-dependent competitors. Cost compression in standard-grade interior applications is intensifying because Thai assembly plants lack solvent recovery infrastructure and must absorb higher compliance costs. Tier-1 battery pack manufacturers exhibit lowest price sensitivity due to thermal runaway liability exposure, while independent collision repair workshops in India negotiate aggressively on color-matched aftermarket sealants.
Supply Chain Analysis
Tariff exposure between China and Japan disrupts just-in-time delivery schedules for moisture-cured polyurethane precursors, forcing Korean battery producers to maintain safety stock that inflates working capital requirements. Geographic supply concentration centers on China for propylene oxide and formulated intermediates, Japan for specialty silicone monomers, and South Korea for captive battery-grade adhesive production. Raw material dependencies include propylene oxide for polyurethane backbone synthesis, silane coupling agents for substrate adhesion promotion, and acrylic monomers for UV-curable electronics potting. Single-source vulnerability persists in JIS-certified additive packages controlled by Nagoya-area specialty chemical houses. Distribution runs through direct formulator-to-cell-producer agreements that disintermediate traditional tier-1 module assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical field service contracts for structural bonding system validation represent a faster-expanding revenue layer than base chemistry sales, as Chinese OEMs outsource multi-substrate compatibility troubleshooting to qualified formulator partners. Recurring calibration and predictive curing system maintenance generate annuity streams that stabilize revenue against petrochemical feedstock volatility.
For Market Incumbents: Insulate qualified supplier status by accelerating JIS certification timelines ahead of METI green procurement guideline enforcement, while securing backward integration into propylene oxide supply through Korean petrochemical partnerships. Emerging Chinese domestic formulators with MIIT fast-track approval capabilities threaten incumbents' Yangtze River Delta relationships. Channel control through exclusive direct technical partnerships with LG Energy Solution and Samsung SDI provides defensive moats against price-aggressive entrants. For New Entrants and Emerging Players: Build out water-based formulation capacity in Thailand's Eastern Economic Corridor to capture Japanese OEM export assembly demand seeking lower-VOC compliance without capital-intensive solvent recovery investments. Southeast Asian interior applications present the most penetrable segment due to fragmented incumbent presence and Board of Investment incentive eligibility. A technical service-led go-to-market approach emphasizing humidity-controlled dispensing infrastructure support differentiates against commodity distributors. For Investors and Strategic Acquirers: SAMR's evolving dual carbon implementation rules reshape the acquisition landscape by elevating cradle-to-gate emissions disclosure capabilities to primary due diligence criteria. Long-term viability favors formulators with verified low-carbon feedstock sourcing and predictive curing data integration platforms over pure chemistry commodity producers. Acquisition target archetype: mid-tier Japanese specialists with JIS certification infrastructure and untapped Southeast Asian distribution. The signal to watch is carbon intensity accounting integration into Chinese OEM supplier scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Battery Producer Partnership | Henkel and Sika bypass tier-1 assemblers to secure Korean cell manufacturer specifications. |
| Water-Based Capacity Expansion | H.B. Fuller targets Thai compliance demand with lower-VOC interior adhesive production. |
| JIS Certification Acceleration | Japanese formulators compress R&D-to-production cycles under METI green procurement pressure. |
| Backward Integration into Feedstock | Regional players secure propylene oxide supply stability against petrochemical volatility. |
| Predictive Curing System Integration | Tier-1 suppliers deploy real-time spectroscopic monitoring for warranty exposure compression. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, adhesive formulator technical directors, and aftermarket distributor operations managers. Secondary validation drew from MIIT GB standard filings, SAMR dual carbon disclosure protocols, Japan METI green procurement guidelines, Korean MFDS chemical substance notifications, and customs trade data for propylene oxide derivatives. Bottom-up volume estimates by chemistry platform and application were triangulated against top-down OEM production forecasts across the analysis window.
Calibration against historical adhesive content per vehicle trends and disclosed supplier contract values anchored the quantitative framework. Segmentation dimensions modeled include chemistry type, application environment, end-user category, and technology platform, with additional granularity on regional regulatory compliance tiers. CAGRs were derived from slope analysis of disclosed capacity investments and OEM platform rollout schedules, cross-checked against petrochemical feedstock demand elasticity parameters and EV production scaling assumptions.
Stress conditions across propylene oxide supply disruptions, JIS certification timeline compression, and Thai Baht exchange rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT emissions standard enforcement intensity and battery producer direct procurement adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market