
 Anti-Seize Compounds Market | 2026-2036
Anti-Seize Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Seize Compounds Market Analysis
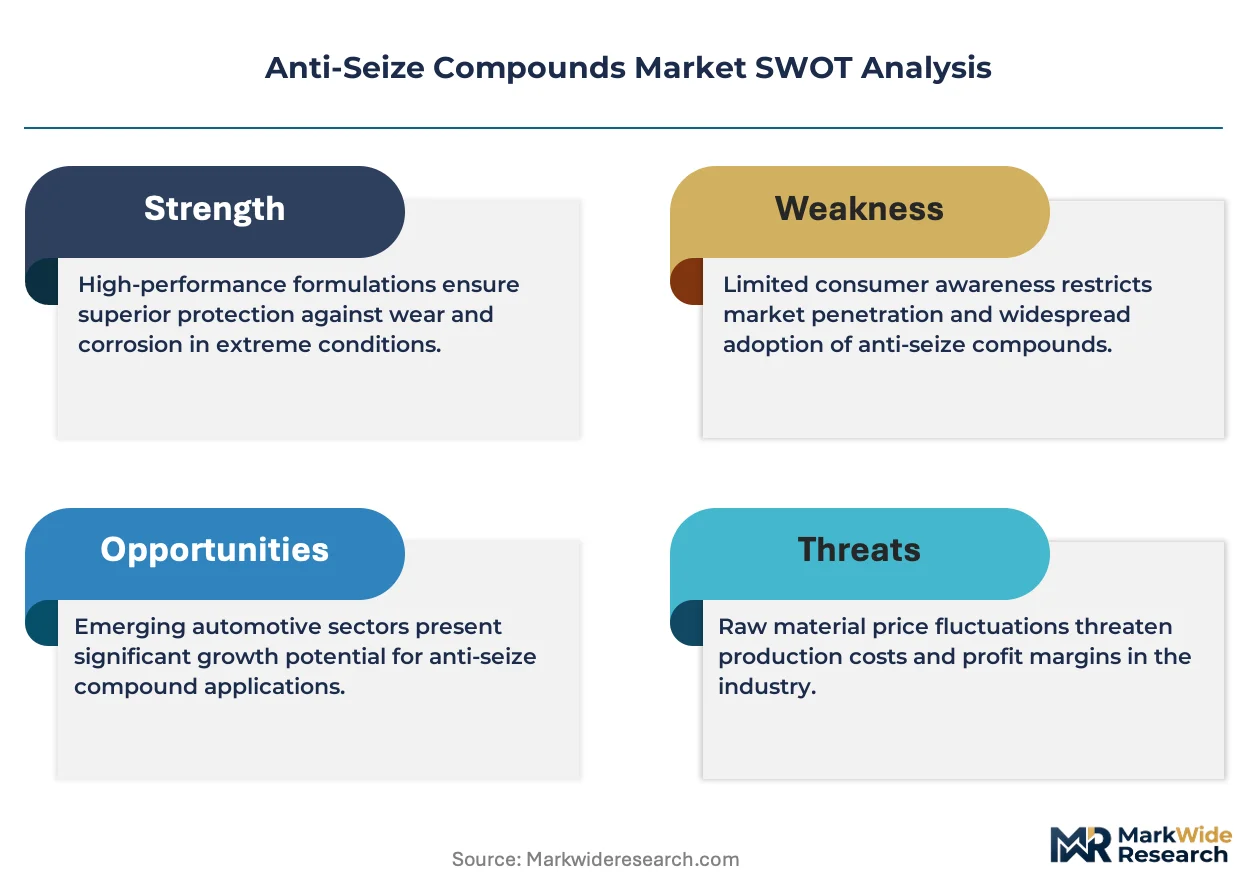
The capability gap between integrated compound manufacturers and regional blenders is collapsing as raw material sourcing complexity rises. Henkel AG & Co. KGaA leverages its adhesive-lubricant crossover chemistry to anchor premium industrial formulations. 3M Company sustains technology leadership through fluoropolymer-bound anti-seize patents. CRC Industries competes on distribution density, occupying shelf space across North American maintenance channels.
Anti-seize compounds are lubricating formulations containing metallic or non-metallic solids suspended in carrier oils, designed to prevent thread galling and seizing in high-temperature or corrosive environments between mated metal surfaces. They typically function from -29°C to 1315°C depending on base composition, with copper-nickel blends serving moderate heat and ceramic-paste grades protecting stainless steel turbine bolts. Metallic pastes still dominate volume in oil & gas flange maintenance, though ceramic segments are gaining share where nickel and copper face regulatory pressure. Spray forms are expanding fastest in automotive aftermarket channels, while OEM demand concentrates on calibrated paste syringes for assembly-line torque consistency.
EPA oversight of metal-containing industrial lubricants shapes disposal protocols and workplace exposure limits in the United States, while REACH registration requirements in Europe restrict certain heavy-metal additives and mandate full substance dossiers for imported formulations. OSHA hazard communication standards further compel SDS transparency on aluminum, copper, and graphite content classifications. Stakeholders must monitor evolving alloy-restriction schedules and decide whether to reformulate legacy metallic lines or accelerate non-metallic platform development ahead of compliance deadlines.
Market Dynamics
REACH registration deadlines are forcing formulators to retire copper-heavy legacy pastes ahead of 2025 substance dossier requirements, collapsing the capability gap between integrated manufacturers and regional blenders as raw material sourcing complexity rises.
Growth Catalysts
- Aerospace maintenance expansion:Engine overhaul facilities in Germany and the United States are expanding high-temperature ceramic formulations to eliminate fastener galling on turbine assemblies.
- REACH compliance pressure:ECHA substance dossier mandates are accelerating ceramic and graphite alternatives as copper-nickel blends face nickel content thresholds.
- Automotive OEM supply chain certification:Precision manufacturing clusters in Germany require certified lubricant solutions, concentrating demand among qualified compound suppliers.
Market Restraints
- Raw material sourcing volatility:Synthetic graphite flake and hexagonal boron nitride supply concentrates in Chinese processing facilities, exposing formulators to export quota uncertainty.
- Technical performance ceiling:Ceramic pastes lack the electrical conductivity of copper-based compounds, limiting substitution in grounding flange applications.
- Regulatory fragmentation:Divergent EPA metal disposal protocols and OSHA workplace exposure limits create compliance friction for multinational maintenance product portfolios.
Strategic Opportunities
- Underpenetrated precision manufacturing in India:BIS certification pathways for industrial lubricants remain underdeveloped, creating first-mover advantage for ceramic formulation registration.
- Distribution channel innovation:Calibrated paste syringes for assembly-line torque consistency are displacing bulk pail procurement in automotive OEM tier-one supplier networks.
- Regulatory tailwind from EU Green Deal:F-Gas Regulation phase-down schedules are accelerating demand for fluoropolymer-bound compounds in high-temperature sealing applications.
Industry Challenges
- Formulation chemistry talent scarcity:Cross-functional expertise spanning tribology and polymer science commands premium compensation, constraining regional blender R&D staffing.
- Certification timeline compression:REACH substance dossier preparation for novel ceramic binders requires 18-24 month toxicology studies, delaying market entry against metallic legacy products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Seize Compounds Market |
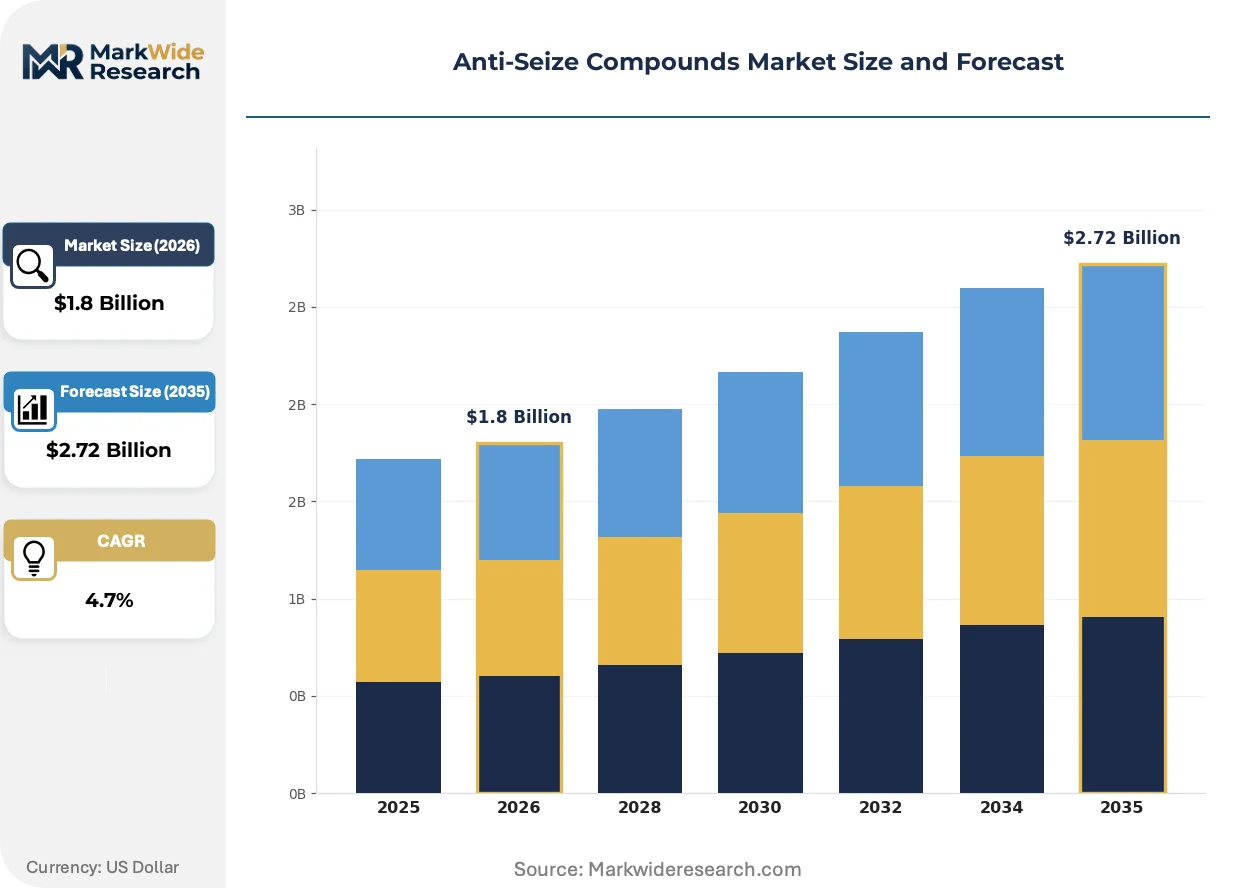
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Non-Metallic, Graphite, Ceramic Application: Automotive, Aerospace, Oil & Gas, Manufacturing Form: Paste, Liquid, Gel, Spray End User: OEMs, Aftermarket Providers, Maintenance Services, Industrial Suppliers |
| Companies Covered | CRC Industries, Bostik, Henkel AG & Co. KGaA, Bel-Ray Company, Jet-Lube, 3M Company, Permatex, ROCOL, Anti-Seize Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Seize Compounds Market Emerging Trajectories
Ceramic and fluoropolymer technologies are fragmenting the metallic paste dominance that has defined industrial maintenance for decades, while regulatory pressure and procurement rationalization reshape how compounds reach end-users.
Hexagonal boron nitride and aluminum-cerium oxide suspensions are fragmenting the copper-nickel blend monopoly in stainless steel fastener applications. Aerospace MRO facilities in Germany and the United States are adopting these formulations at accelerating pace for turbine bolt protection. The technology is fragmenting volume concentration among legacy metallic paste suppliers as ceramic patents expire and regional blenders gain formulation access.
REACH authorization requirements for nickel compounds are tightening permissible thresholds in industrial lubricants. ECHA substance dossier mandates now cover anti-seize imports previously exempt under intermediate-use exemptions. European formulators are responding by accelerating graphite-ceramic platform development ahead of 2025 compliance deadlines, while importers face registration cost barriers.
Maintenance procurement rationalization is compressing supplier counts as fleet operators consolidate lubricant specifications across multiple equipment OEMs. Distributors with technical service capabilities are displacing pure product resellers in North American industrial channels. This consolidation is most visible in oil and gas flange maintenance, where integrated supply agreements now specify compound performance rather than brand names.
Anti-Seize Compounds Market Segmentation
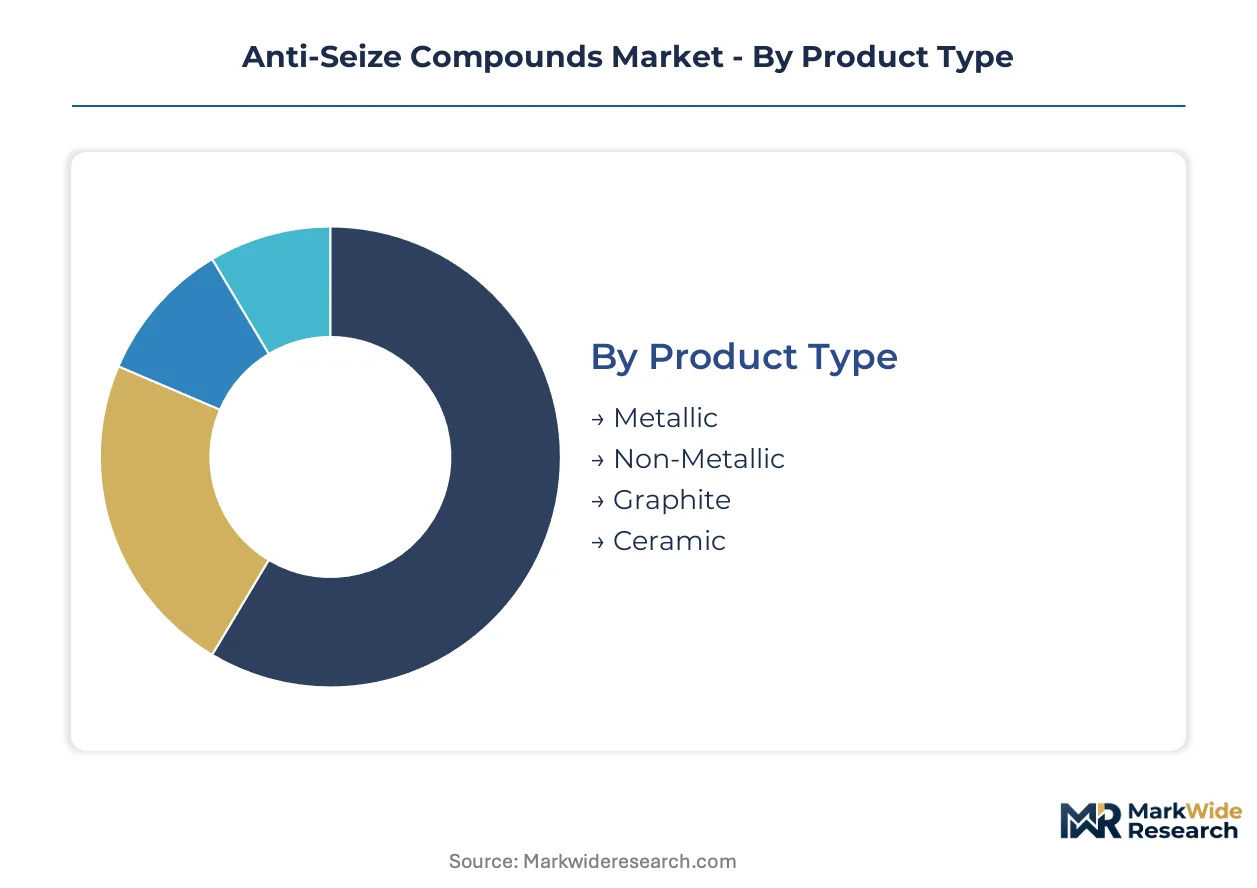
Anti-seize compound procurement splits across four distinct dimensions, each shaping formulation priorities and channel strategy. Product chemistry determines regulatory exposure, while form factor dictates application speed and torque precision.
Product Type:
Substitution pressure from REACH nickel thresholds and EPA metal disposal rules is fragmenting the traditional metallic paste monopoly, forcing reformulation decisions across every chemistry tier.
- Metallic:Copper-nickel and aluminum-based suspensions in petroleum carriers dominate oil and gas flange maintenance. Demand concentrates in United States petrochemical corridors where electrical conductivity requirements in grounding applications resist ceramic substitution.
- Non-Metallic:Synthetic polymer-bound formulations eliminate heavy-metal content entirely, serving food-processing and pharmaceutical equipment where contamination risk overrides cost considerations. German precision manufacturers are certifying these for cleanroom assembly operations ahead of ECHA dossier deadlines.
- Graphite:Flake graphite in high-temperature binders offers moderate thermal performance without nickel content exposure. Chinese export quotas on synthetic graphite feedstock constrain formulator margin flexibility.
- Ceramic:Hexagonal boron nitride and aluminum-cerium oxide suspensions protect stainless steel fasteners in turbine assemblies. Aerospace MRO facilities in Germany and the United States are adopting these formulations for engine overhaul operations.
Metallic pastes retain volume leadership in legacy industrial maintenance; ceramic formulations hold the steepest expansion curve as REACH compliance deadlines approach.
Application:
Cost tier stratification separates specification-grade aerospace compounds from commodity automotive aftermarket products, with certification requirements widening the price spread between tiers.
- Automotive:Assembly-line paste syringes demand calibrated torque consistency for powertrain fasteners. OEM tier-one suppliers in Germany require certified lubricant solutions with full substance dossiers.
- Aerospace:Engine overhaul facilities specify high-temperature ceramic formulations to eliminate fastener galling on turbine bolt assemblies. FAA maintenance protocols drive specification rigor.
- Oil & Gas:Flange maintenance in United States petrochemical infrastructure relies on copper-based electrical conductivity for grounding applications. Integrated supply agreements now specify performance metrics rather than brand names.
- Manufacturing:General industrial maintenance spans metallic pastes for moderate heat and ceramic grades for precision equipment. BIS certification pathways in India remain underdeveloped, creating first-mover opportunity for ceramic registration.
Automotive applications concentrate procurement volume through OEM supply chains; aerospace commands the highest specification premiums per kilogram.
Form:
Volume throughput in high-speed maintenance operations favors spray delivery, while torque-critical assembly lines require paste precision.
- Paste:Thick suspensions in syringe or pail formats enable controlled application to threaded fasteners. Automotive OEM assembly lines are displacing bulk pail procurement with calibrated syringe systems for torque consistency.
- Liquid:Low-viscosity carrier oils with suspended solids penetrate tight clearances in precision mechanisms. Demand concentrates in hydraulic fitting maintenance across German manufacturing clusters.
- Gel:Thixotropic formulations cling to vertical and overhead surfaces without drip. Specialized applications in wind turbine tower bolt maintenance favor this consistency.
- Spray:Aerosol or pump-spray delivery accelerates coverage in high-volume maintenance environments. Automotive aftermarket channels in North America are expanding spray SKUs fastest.
Paste forms retain procurement volume in OEM assembly; spray applications are climbing the fastest in aftermarket maintenance channels.
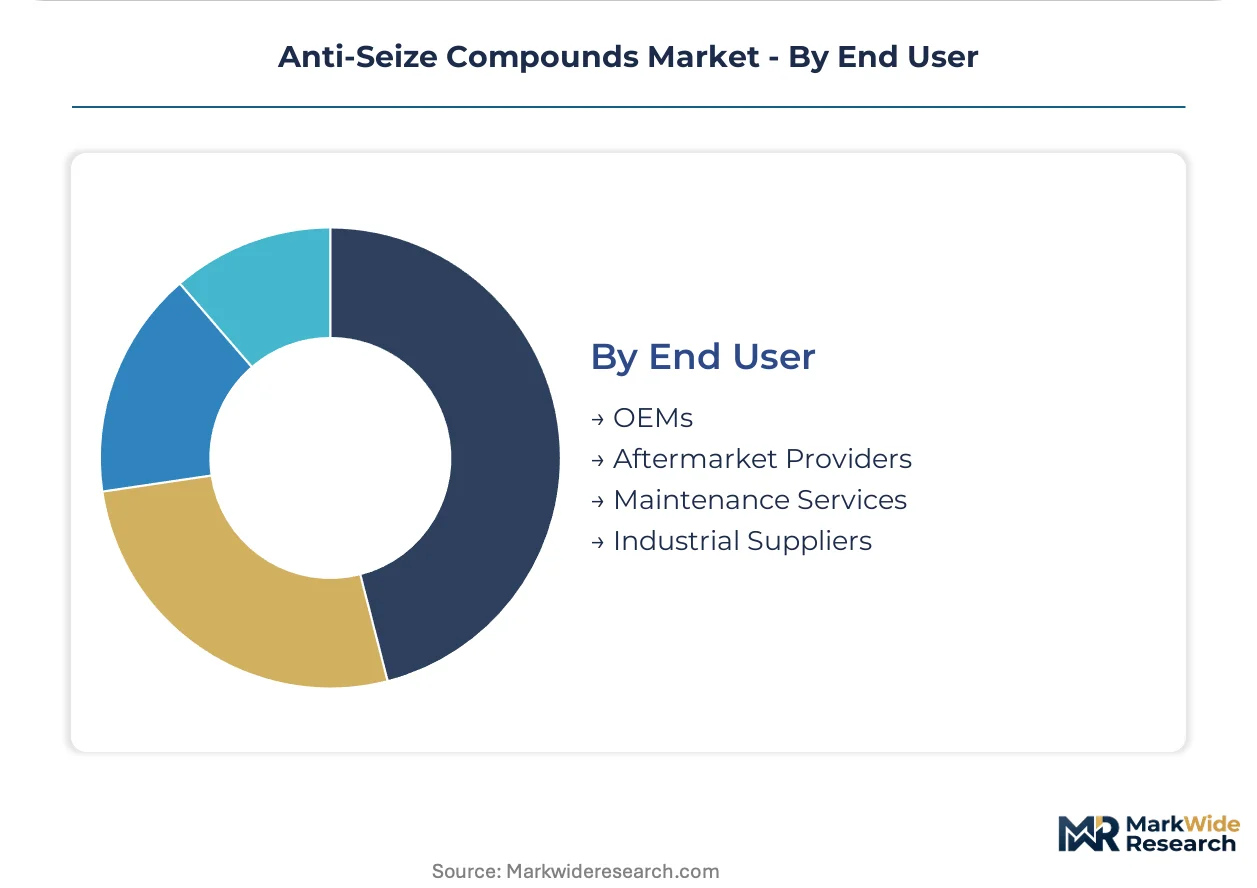
End User:
Customer type determines specification authority, with OEMs dictating chemistry standards that cascade through tiered supply networks.
- OEMs:Original equipment manufacturers specify certified compounds for assembly-line torque consistency. German automotive OEM supply chains require full REACH substance dossiers from qualified compound suppliers.
- Aftermarket Providers:Independent distributors and retailers serve maintenance shops with multi-purpose metallic pastes. Shelf-space competition in North American auto parts channels favors spray-format convenience.
- Maintenance Services:Contract maintenance operators consolidate lubricant specifications across multiple equipment OEMs. Technical service capabilities are displacing pure product resellers in industrial procurement.
- Industrial Suppliers:Broad-line distributors serve fragmented manufacturing accounts with standard-grade formulations. Procurement rationalization is compressing supplier counts in oil and gas flange maintenance.
OEMs retain specification authority over chemistry standards; aftermarket providers are expanding volume fastest through spray-format convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in graphite flake and ceramic precursors are reshaping regional manufacturing footprints. Formulators in Germany and the United States are securing alternative supply chains as Chinese export quotas tighten. This geographic recalibration is accelerating local blending capacity investments.
United States
Petrochemical infrastructure maintenance in Gulf Coast corridors sustains copper-based compound demand for electrical grounding applications. EPA metal disposal protocols under the Resource Conservation and Recovery Act constrain formulation choices. Houston-area flange maintenance contractors now specify performance metrics rather than brand names in integrated supply agreements.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria require REACH-certified lubricant solutions for automotive OEM supply chains. ECHA substance dossier mandates for nickel compounds are accelerating ceramic formulation adoption ahead of 2025 deadlines. Stuttgart-area engine overhaul facilities are expanding hexagonal boron nitride procurement for turbine bolt protection.
China
Synthetic graphite processing dominance creates supply leverage over global formulators dependent on flake feedstock. MIIT industrial standards for high-temperature lubricants are tightening domestic quality benchmarks. Shandong Peninsula processing facilities control export quotas that expose foreign blenders to raw material volatility.
India
BIS certification pathways for industrial lubricants remain underdeveloped, creating first-mover opportunity for ceramic formulation registration. CDSCO oversight of manufacturing facility standards is intensifying as domestic precision engineering expands. Maharashtra and Gujarat manufacturing corridors are attracting compound suppliers seeking untapped automotive tier-one networks.
Japan
Automotive OEM supply chains demand calibrated torque consistency specifications that favor paste syringe formats. METI energy efficiency standards are influencing high-temperature lubricant selection in precision assembly operations. Nagoya-area industrial equipment manufacturers are consolidating supplier counts under technical service procurement models.
Anti-Seize Compounds Market Vendor Landscape
Concentration sits with integrated chemical conglomerates possessing adhesive-lubricant crossover capabilities. The vendor base spans three tiers: multinational diversified industrials with fluoropolymer patent estates, regional blenders competing on distribution density, and specialty formulators serving aerospace certification requirements. Strategic moves center on REACH-compliant platform development and calibrated delivery system innovation for automotive assembly lines.
Among diversified industrial groups, Henkel AG & Co. KGaA and 3M Company exemplify the technology-anchored tier, while CRC Industries represents distribution-scale competitiveness in North American maintenance channels. These players occupy positions that reflect divergent strategic bets: chemistry integration versus channel penetration versus fluoropolymer-bound formulation patents. The competitive dynamic is compressing margins for regional blenders lacking either upstream material control or downstream specification authority.
| Leading Market Players |
|---|
| CRC Industries |
| Bostik |
| Henkel AG & Co. KGaA |
| Bel-Ray Company |
| Jet-Lube |
| 3M Company |
| Permatex |
| ROCOL |
| Anti-Seize Technology |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for hexagonal boron nitride feedstock concentrate pricing power with Shandong Peninsula processors, compressing margin flexibility for European and North American formulators facing REACH compliance deadlines. Ceramic compound premiums over metallic pastes reflect this supply asymmetry alongside toxicology study costs for novel binder platforms.
Pricing Analysis
Configured-to-order ceramic formulations for aerospace turbine applications command substantial premiums over standard-grade copper-nickel pastes. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace compounds from automotive OEM assembly grades and commodity aftermarket sprays. Pricing pressure stems from Chinese export quota volatility on synthetic graphite flake, squeezing mid-tier formulators lacking long-term offtake agreements. Automotive OEM procurement teams exhibit lowest price sensitivity due to torque-consistency specification requirements, while independent aftermarket distributors face margin compression from shelf-space competition.
Supply Chain Analysis
Ninety-day inventory cycles expose formulators to Chinese export quota volatility on hexagonal boron nitride and synthetic graphite flake. Raw material sourcing rests on Shandong Peninsula processing facilities for ceramic precursors, German specialty chemical producers for fluoropolymer binders, and domestic petroleum distillate refiners for carrier oils. Single-source vulnerability concentrates in hexagonal boron nitride purification capacity, where limited alternative suppliers extend qualification timelines. Distribution runs through integrated supply agreements with oil and gas maintenance contractors, technical-service distributors in German precision manufacturing clusters, and auto parts retailers across North American aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as fleet operators consolidate lubricant specifications across multiple equipment OEMs, compressing supplier counts and shifting procurement toward performance-based contracts.
For Market Incumbents: Compound defensive positions by securing REACH-compliant ceramic formulation patents ahead of ECHA dossier deadlines and locking long-term offtake agreements with Shandong Peninsula graphite processors. Threat substitution from regional blenders gaining formulation access as ceramic patents expire demands preemptive certification investment. Backward integration into fluoropolymer binder production anchors margin control against raw material volatility. For New Entrants and Emerging Players: Anchor in underpenetrated Indian precision manufacturing corridors where BIS certification pathways remain underdeveloped for ceramic formulations. White-space opportunity concentrates in Maharashtra and Gujarat automotive tier-one networks seeking qualified compound suppliers. Go-to-market execution through technical service partnerships with maintenance contractors displaces pure product resellers in procurement rationalization. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming lubricant-adhesive crossover divisions lacking REACH platform investment. Long-term viability favors formulators with captive ceramic precursor supply and established aerospace certification pathways. Signal to monitor: ECHA authorization list expansions for nickel compounds accelerating ceramic substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Precursors | Captive hexagonal boron nitride supply insulates margin against Chinese export quota volatility. |
| REACH-Compliant Platform Development | Graphite-ceramic formulations secure market access ahead of ECHA nickel authorization deadlines. |
| Calibrated Syringe System Launch | Torque-precision delivery captures automotive OEM assembly-line procurement consolidation. |
| Long-Term Supply Agreement with Aerospace MRO | FAA-certified compound specifications lock recurring revenue in engine overhaul operations. |
| Joint Venture with Indian Distributor | BIS certification acceleration opens Maharashtra precision manufacturing tier-one networks. |
Methodological Framework
Desk research of customs trade data, ECHA substance dossier filings, and aerospace maintenance protocol documentation preceded structured interviews with formulator R&D directors, procurement leads at German automotive OEMs, technical service managers at North American industrial distributors, and plant engineers at Gulf Coast petrochemical facilities. Primary fieldwork combined with secondary validation from SEC 10-K filings, specialty chemical industry association reports, and patent landscape analysis. Bottom-up volume modeling triangulated against top-down market sizing across chemistry tiers and application segments.
Variance decomposition across chemistry type, application vertical, form factor, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices and regulatory compliance timeline impacts. Forecast inputs incorporated REACH authorization schedule probability-weighting and aerospace MRO fleet expansion trajectories.
Material uncertainties — ECHA nickel compound list expansions, Chinese graphite export quota adjustments, and automotive OEM supply chain consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory compliance cost absorption and substitution elasticity in grounding flange applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
North America Acrylic Adhesives Market