
 Global Glass Bonding Adhesive Market | 2026-2036
Global Glass Bonding Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Bonding Adhesive Market Foresight
Automotive windshield assemblers is reorganizing procurement priorities toward high-strength structural bonding solutions. Henkel AG & Co. KGaA leverages its UV-curing portfolio to dominate European vehicle assembly lines. 3M Company sustains technology leadership in optical-grade adhesive films for electronics displays. Dow anchors North American supply through moisture-curing silicone platforms tailored to solar panel laminators.
Glass bonding adhesives are formulated polymer systems, typically epoxies or modified silanes, engineered to achieve optical clarity and structural load transfer across glass-to-metal or glass-to-glass interfaces. These materials cure via UV initiation, moisture reaction, or thermal activation to deliver shear strengths exceeding 20 MPa while maintaining yellowing resistance under prolonged solar exposure. Silicone adhesives lead architectural glazing applications due to proven durability in facade movement joints. UV-curing technology commands premium positioning in electronics display assembly where cycle-time compression determines factory economics. Epoxy formulations occupy the fastest-growing tier in optical devices as refractive-index matching becomes critical for augmented-reality waveguides.
The EPA regulates volatile organic compound emissions from solvent-based adhesive formulations in US manufacturing facilities. REACH restricts isocyanate content in polyurethane glass bonding products sold across European member states. China's MEE enforces GB standards for hazardous substance limits in construction-grade adhesives. Stakeholders must monitor divergence between regional chemical compliance regimes when scaling cross-border formulation platforms.
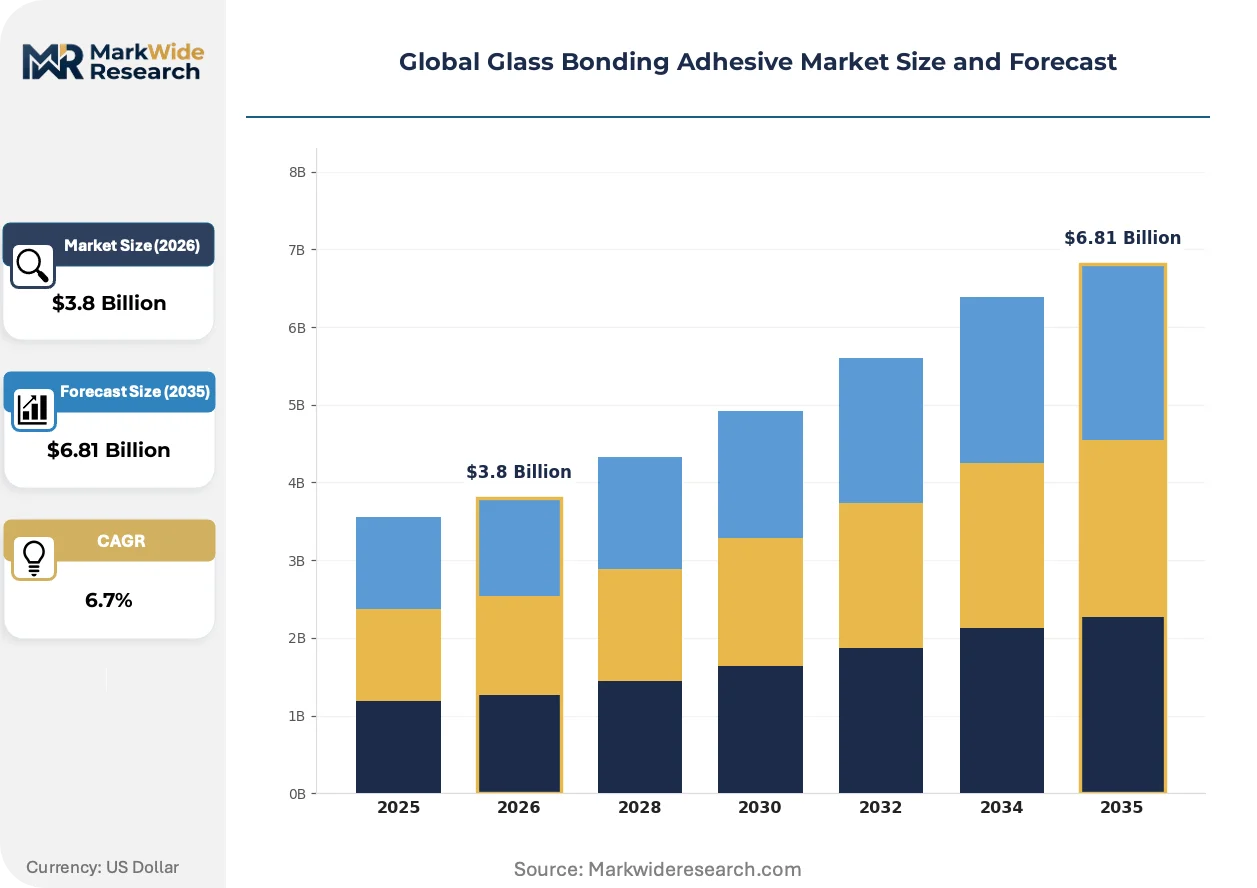
Market Dynamics
Automotive OEMs are consolidating adhesive specifications toward single-platform structural bonding systems that eliminate process steps, compressing supplier qualification cycles and favoring formulation houses with integrated UV-curing and thermal-cure portfolios.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is accelerating silicone adhesive substitution in architectural glazing across Germany, France, and Italy.
- Electronics display manufacturing:Cycle-time compression in panel assembly lines is pulling UV-curing epoxies into bonding stacks previously served by thermal-cure systems.
- Lightweight vehicle architectures:Windshield bonding specifications now demand shear strengths above 25 MPa to enable thinner glass substrates without structural compromise.
Market Restraints
- Silicone feedstock volatility:Methyl chlorosilane supply interruptions in Chinese manufacturing clusters create raw material cost instability for sealant formulators.
- REACH isocyanate restrictions:Polyurethane glass bonding products face reformulation mandates that extend R&D timelines and elevate compliance expenditures.
- Optical-grade epoxy substitution ceiling:Acrylic pressure-sensitive adhesives are capturing share in temporary display bonding applications where reworkability outweighs structural strength.
Strategic Opportunities
- India construction-grade expansion:BIS certification requirements for structural glazing silicones are creating first-mover advantages for compliant formulation platforms.
- AR waveguide optical bonding:Refractive-index-matched epoxies are opening specification windows in augmented-reality headset manufacturing.
- Dual carbon goals in China:MEE enforcement of lower-VOC adhesive standards is redirecting procurement toward waterborne and UV-curing technologies in facade projects.
Industry Challenges
- Photoinitiator supply security:Concentrated production of specialty UV-cure activators in German and Japanese chemical clusters creates single-source vulnerability for electronics adhesive lines.
- Multi-regulatory formulation complexity:Divergent EPA VOC limits, REACH substance restrictions, and China GB hazardous substance standards force parallel product development tracks rather than global platform scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Bonding Adhesive Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Adhesive Type: Epoxy, Silicone, Polyurethane, Acrylic, Cyanoacrylate Technology: UV Curing, Anaerobic, Hot Melt, Moisture Curing, Solvent Based Application: Architectural Glazing, Electronics Display, Automotive Windshields, Optical Devices, Solar Panels End User Industry: Construction, Electronics Manufacturing, Vehicle Assemblers, Optoelectronics, Renewable Energy Equipment |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Sika AG, Dymax Corporation, Dow, Ashland Inc., Permabond Engineering Adhesives, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Bonding Adhesive Market Shifts & Advancements
Formulation chemistry is pivoting toward energy-efficient cure mechanisms that align with factory decarbonization targets while maintaining optical performance thresholds demanded by next-generation display and glazing applications.
UV-LED curing systems are displacing mercury-arc UV lamps in electronics display assembly, cutting energy consumption by half and eliminating mercury handling protocols. Panel manufacturers in South Korea and Taiwan are retrofitting bonding lines at pace. The technology is displacing thermal-cure epoxies in applications where substrate temperature sensitivity previously mandated slower process cycles.
REACH authorization requirements for SVHC substances are forcing systematic substance screening across European adhesive supply chains. Formulators must now document safe-use scenarios for residual monomers and catalyst residues. Architectural glazing silicones face the tightest scrutiny, with German facade contractors demanding full material disclosure ahead of project tendering.
Automotive Tier-1 suppliers are unbundling adhesive specification authority from windshield assembly contracts, creating direct procurement relationships with formulation specialists. This disintermediation is compressing traditional distribution margins and elevating technical service capabilities as the primary competitive differentiator. The pattern is most visible in German and US automotive manufacturing clusters where platform consolidation has concentrated buying power.
Global Glass Bonding Adhesive Market Segmentation
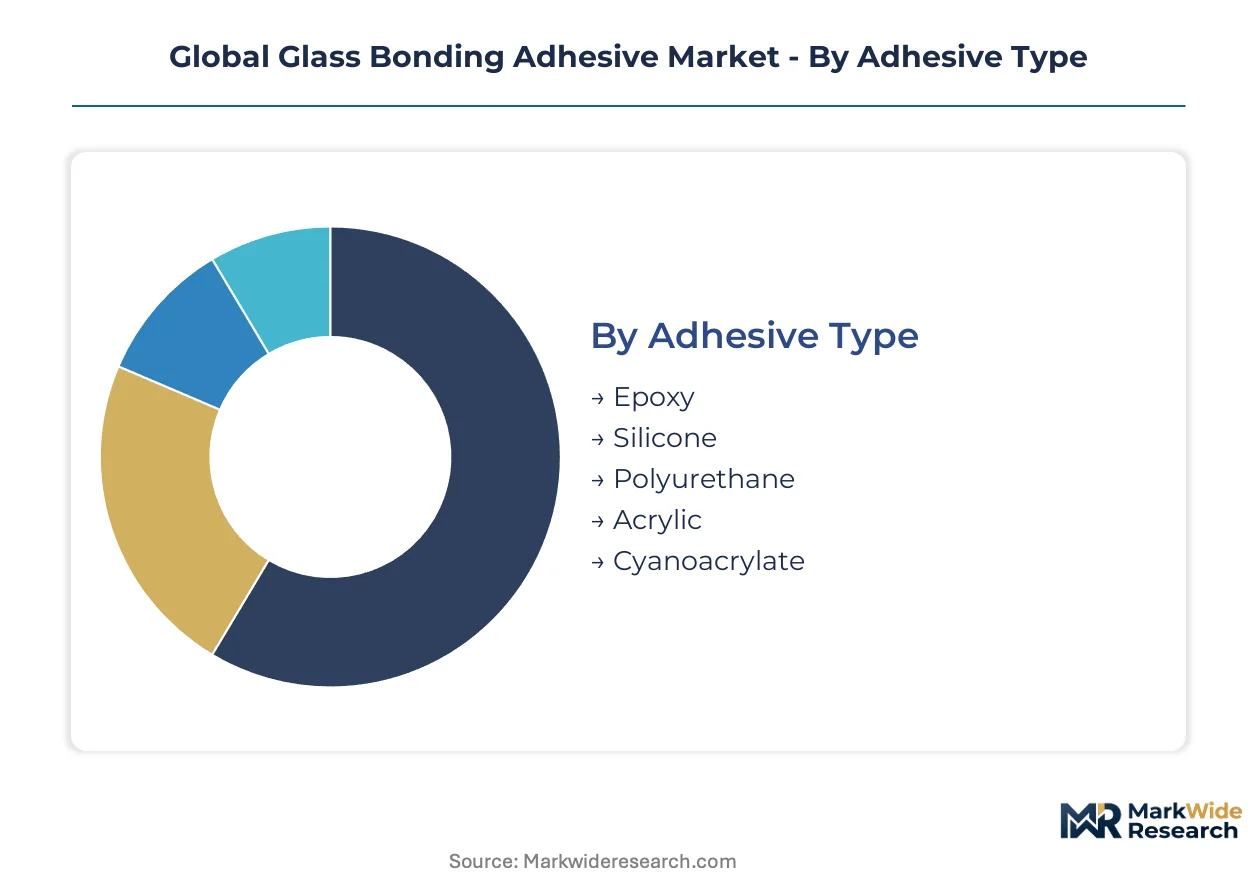
Glass bonding adhesive procurement splits along cure chemistry, application stress requirements, and regulatory exposure. Formulators optimize margin capture by matching technology platforms to end-use certification tiers rather than pursuing horizontal coverage.
Adhesive Type:
Margin pools concentrate in formulations commanding structural certification premiums and optical-grade purity standards.
- Epoxy:Two-part thermoset systems deliver refractive-index precision below 0.001 deviation for optical waveguide bonding. Electronics manufacturers in Taiwan and South Korea specify epoxies for AR headset laminates where index matching prevents image distortion.
- Silicone:Room-temperature-vulcanizing formulations dominate facade movement joints with 50-year durability certification. German and Italian glazing contractors specify high-modulus silicones for structural sealant glazing under EOTA ETAG 002 guidelines.
- Polyurethane:Moisture-curing systems bond automotive windshields with 25 MPa shear strength and crash-test validation.
- Acrylic:Pressure-sensitive variants serve temporary display bonding where reworkability outweighs permanent adhesion.
- Cyanoacrylate:Instant-bonding formulations address small-area glass repairs and craft applications with minimal surface preparation.
Silicone holds installed capacity. Epoxy is rotating up the share rankings.
Technology:
Cost tier stratification separates energy-intensive thermal systems from capital-light UV installations.
- UV Curing:LED-activated photoinitiator systems cut energy consumption 50% versus mercury-arc lamps. South Korean panel manufacturers retrofit bonding lines to compress cycle times from minutes to seconds.
- Moisture Curing:Alkoxy-silane chemistry anchors solar panel laminator operations where substrate temperature limits prohibit thermal cure. Dow's North American supply platforms target this specification tier.
- Anaerobic:Metal-surface activation enables glass-to-metal structural joints in automotive hardware.
- Hot Melt:Thermoplastic formulations serve high-speed edge-sealing in appliance manufacturing.
- Solvent Based:VOC-exposed systems face EPA emission limits and declining specification authority in US facilities.
Moisture curing commands volume scale. UV curing is climbing the fastest.
Application:
Customer type divergence separates project-based construction procurement from continuous electronics manufacturing.
- Electronics Display:TFT-LCD and OLED panel assembly demands optical clarity below 1% haze and yellowing resistance. UV-curing epoxies displace thermal systems in Taiwan and South Korea where line speed determines factory economics.
- Automotive Windshields:Structural bonding specifications now require 25 MPa shear strength to enable thinner glass substrates. German and US vehicle assemblers consolidate procurement toward single-platform systems.
- Architectural Glazing:Structural sealant glazing and facade movement joints specify silicone durability.
- Optical Devices:AR waveguide manufacturing requires refractive-index-matched epoxies with sub-micron bondline control.
- Solar Panels:Moisture-curing silicones laminate glass-to-cell interfaces in photovoltaic module assembly.
Automotive windshields hold installed capacity. Electronics display is gaining share fastest.
End User Industry:
Supply concentration tracks manufacturing cluster geography rather than end-use dispersion.
- Electronics Manufacturing:Display panel producers in Taiwan, South Korea, and China concentrate UV-curing adhesive demand. Cycle-time compression pulls specification toward LED-curable systems.
- Construction:Facade contractors in Germany, France, and Italy drive silicone specification under EU F-Gas phase-down pressure.
- Vehicle Assemblers:OEMs and Tier-1 suppliers consolidate bonding specifications toward structural platforms.
- Optoelectronics:AR headset manufacturers specify index-matched epoxies for waveguide assembly.
- Renewable Energy Equipment:Solar panel laminators in China and the US specify moisture-curing silicones for field durability.
Construction holds installed capacity. Electronics manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive exports supply automotive assembly lines across the United States and China, creating a transatlantic-Pacific trade corridor for structural bonding technologies. This flow concentrates procurement authority in manufacturing clusters where windshield and display panel production dominates factory economics.
United States
Automotive OEMs in Michigan and Ohio consolidate adhesive specifications toward single-platform structural systems. EPA VOC emission limits from solvent-based formulations tighten procurement standards in Ohio and Kentucky assembly plants. Detroit-area Tier-1 suppliers now source directly from formulation specialists, bypassing traditional distribution channels.
Germany
Windshield manufacturers in Baden-Württemberg demand shear strengths exceeding 25 MPa for lightweight vehicle architectures. EU F-Gas Regulation phase-down accelerates silicone adhesive substitution in facade glazing across Stuttgart and Munich industrial zones. EOTA ETAG 002 certification requirements dominate specification authority for structural sealant glazing contractors.
China
Display panel producers in Suzhou and Shenzhen retrofit bonding lines toward UV-LED curing systems for cycle-time compression. MEE enforcement of GB hazardous substance limits redirects procurement toward waterborne and UV-curing technologies in Yangtze River Delta facade projects. Dual carbon goals tighten formulation standards for construction-grade silicones in Shanghai and Beijing.
South Korea
TFT-LCD and OLED manufacturers in Gyeonggi Province specify optical clarity below 1% haze for panel assembly applications. LED-curable adhesive demand concentrates in Suwon and Ansan manufacturing corridors where line speed determines factory economics. Domestic panel producers displace thermal-cure systems with UV-curing epoxies for throughput optimization.
India
Facade contractors in Maharashtra and Gujarat drive specification authority for structural glazing silicones under BIS certification requirements. Construction-grade adhesive demand concentrates in Mumbai and Ahmedabad where commercial building stock expansion accelerates procurement cycles. First-mover advantages accrue to compliant formulation platforms meeting national standards.
Global Glass Bonding Adhesive Market Competitive Landscape
Listed leaders compete with private specialists across technology platform breadth, with publicly traded chemical conglomerates anchoring volume scale while family-owned formulation houses capture premium niches. Market structure tilts toward consolidation in automotive and electronics tiers where qualification cycles favor integrated portfolios, while architectural glazing retains fragmentation due to project-based procurement patterns. Three archetypes dominate: diversified chemical conglomerates with cross-sector adhesive platforms, mid-cap specialists with single-cure-technology depth, and regional formulators with local certification expertise. Competitive moves concentrate on backward integration into silicone feedstock and technology licensing partnerships for UV-LED curing equipment.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow exemplify the integrated-platform archetype through their spanning of multiple cure chemistries and end-use certifications. 3M Company occupies a position representing the technology-licensing vector, particularly in optical-grade purity standards. These three entities anchor the competitive landscape by exemplifying the scale-driven, certification-heavy, and innovation-led positioning vectors that define procurement authority in automotive and electronics manufacturing clusters.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Sika AG |
| Dymax Corporation |
| Dow |
| Ashland Inc. |
| Permabond Engineering Adhesives |
| Bostik |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between automotive OEMs and silicone feedstock suppliers lock in volume commitments and price visibility across multi-year procurement cycles, insulating German and US vehicle assemblers from methyl chlorosilane volatility while compressing margin buffers for non-integrated formulators.
Pricing Analysis
UV-LED curing technology commands a 40-60% premium over legacy mercury-arc systems, while thermal-cure epoxies trade at standard tier and solvent-based formulations face economy-tier pricing pressure from EPA VOC enforcement. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade purity certifications from construction-grade durability ratings and temporary bonding reworkability tiers. Cost compression in thermal-cure segments is intensifying because South Korean panel manufacturers are retrofitting lines toward LED-curable systems. Electronics display assemblers exhibit highest price sensitivity due to throughput-driven factory economics, while AR headset manufacturers accept premium positioning for refractive-index-matched epoxies.
Supply Chain Analysis
Inventory buffers for photoinitiator activators stretch to 12-16 weeks given concentrated production in German and Japanese chemical clusters, forcing electronics adhesive lines to carry working capital premiums. Supply concentrates in China for silicone feedstock, Germany for automotive-grade formulation, and South Korea for display panel integration. Specialty UV-cure activators and high-purity epoxy resins constitute critical input dependencies. Single-source vulnerability for photoinitiator supply creates qualification risk for electronics manufacturers. Distribution runs through direct procurement relationships with Tier-1 automotive suppliers and formulation specialists, bypassing traditional chemical distributors in German and US manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as acrylic pressure-sensitive adhesives capture temporary display bonding share where reworkability outweighs structural strength, threatening epoxy volume in electronics assembly.
For Market Incumbents: Compound technology platform breadth by integrating UV-LED curing portfolios with thermal-cure systems to capture single-platform automotive specifications, while anchoring silicone feedstock through backward integration into Chinese methyl chlorosilane supply or long-term offtake partnerships. EOTA ETAG 002 certification investment defends structural glazing positioning against regional formulators.
For New Entrants and Emerging Players: BIS certification fast-track for structural glazing silicones unlocks first-mover positioning in Maharashtra and Gujarat facade markets where commercial building stock expansion accelerates procurement cycles. Target India construction-grade expansion and AR waveguide optical bonding as penetrable white-space segments, leveraging refractive-index-matched epoxy formulation partnerships with Taiwan optoelectronics assemblers.
For Investors and Strategic Acquirers: Mid-cap specialists with single-cure-technology depth in UV-LED activation represent acquisition targets as automotive and electronics tiers consolidate toward integrated portfolios. Long-term viability hinges on backward integration into silicone feedstock and technology licensing partnerships for curing equipment. Monitor photoinitiator supply security disruptions as inflection indicator for electronics adhesive line valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | Captive methyl chlorosilane supply insulates Henkel and Dow from Chinese manufacturing cluster volatility. |
| UV-LED Curing Technology Licensing | Equipment partnerships with South Korean panel manufacturers compress cycle times from minutes to seconds. |
| EOTA ETAG 002 Certification Investment | German facade contractors demand full material disclosure ahead of structural sealant glazing project tendering. |
| Direct Procurement Relationship Development | Tier-1 suppliers in Michigan and Ohio bypass distributors to source from formulation specialists. |
| Refractive-Index-Matched Epoxy R&D | Sub-micron bondline control opens specification windows in augmented-reality headset manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with adhesive formulation R&D directors, automotive Tier-1 procurement managers, electronics display panel engineers, facade contractor technical leads, and solar panel laminator operations heads. Secondary validation drew from SEC 10-K filings of listed chemical conglomerates, ECHA REACH substance restriction updates, Chinese MEE GB standard enforcement notices, and customs trade data for silicone feedstock flows. Bottom-up segment sizing triangulated against top-down market aggregation across cure chemistry, application stress, and regulatory exposure tiers.
Across the analysis window, volume and value outputs reflect modeled projections for adhesive type, technology platform, application segment, and end-user industry dimensions. CAGRs were derived from segment-level growth trajectory analysis calibrated to manufacturing cluster expansion rates and regulatory phase-in timelines. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules, China dual carbon goal enforcement intensity, and UV-LED curing equipment retrofit adoption curves in South Korean and Taiwanese panel facilities.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive lightweighting, electronics display manufacturing consolidation, and REACH authorization timeline adherence; material deviation in methyl chlorosilane supply stability or photoinitiator production concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market